
 Japan Food Sweetener Market | 2026-2036
Japan Food Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Food Sweetener Market Foresight
Subscription-based flavor optimization platforms is recalibrating how sweetener portfolios reach Japanese food manufacturers. Ajinomoto Co., Inc. leverages its amino acid fermentation expertise to anchor high-intensity sweetener supply chains. Matsutani Chemical Industry Co. Ltd specializes in rare sugar production, occupying a defensible niche in functional ingredient markets. Mitsui DM Sugar Holdings Co., Ltd controls traditional sucrose distribution networks, sustaining volume leadership across institutional channels.
Food sweeteners encompass caloric and non-caloric substances added to food and beverages to impart sweetness, typically measured by sucrose equivalence values ranging from 0.5x to 600x depending on molecular structure. These compounds serve primarily to enhance palatability, extend shelf stability, and enable calorie reduction in processed foods. Sucrose retains dominant volume share in Japanese confectionery applications, though stevia extracts are gaining fastest in beverage reformulations targeting reduced-sugar claims. Powder and liquid forms command distinct margin pools, with liquid syrups capturing premium pricing in industrial bakery operations while granulated formats compete on scale in retail channels.
METI enforces food labeling standards that mandate added-sugar line-item disclosure, directly pressuring manufacturers toward high-potency alternatives. JIS standards govern purity specifications for food-grade sweeteners, creating compliance barriers for imported raw materials. The Consumer Affairs Agency monitors health claim substantiation, limiting how products position reduced-calorie benefits. Stakeholders must monitor evolving FOSHU approval pathways for functional sweeteners, as regulatory clarity on novel compounds will determine which R&D pipelines merit scaled investment.
Market Dynamics
Functional beverage reformulation is compressing sucrose volumes across Japanese manufacturing corridors, with METI's added-sugar disclosure mandates forcing processors toward high-potency alternatives that preserve sweetness intensity while collapsing caloric contribution.
Growth Catalysts
- Tokyo-Yokohama Processing Clusters:Concentrated demand from functional beverage manufacturers in the Kanto corridor accelerates procurement of rare sugars and high-intensity alternatives for reformulation programs.
- METI Labeling Mandates:Tightened added-sugar disclosure thresholds pressure confectionery and beverage producers toward ingredient portfolios that enable clean-label positioning.
- Fermentation Biotechnology:Amino acid-derived sweetener production scales through microbial fermentation platforms, reducing unit costs for high-potency compounds.
Market Restraints
- Import Raw Material Barriers:JIS purity specifications for food-grade sweeteners create compliance friction for non-domestic suppliers, concentrating supply risk among certified domestic producers.
- Sucrose Price Volatility:Traditional sugar commodity fluctuations compress margins for institutional bakery channels locked into long-term volume contracts.
- Consumer Affairs Agency Claim Limits:Restricted health claim substantiation pathways constrain how reduced-calorie products communicate benefits to end consumers.
Strategic Opportunities
- FOSHU Approval Pathways:Regulatory clarity on functional sweetener health claims will determine which R&D pipelines merit scaled capital deployment.
- Kansai Manufacturing Belt:Underpenetrated processing capacity in Osaka-Kobe corridors offers expansion terrain for rare sugar distribution networks.
- Subscription Flavor Optimization:Digital platforms connecting sweetener portfolios directly to food manufacturers are collapsing traditional distributor margins.
Industry Challenges
- Reformulation Technical Talent:Scarce food technologists capable of balancing sweetness intensity with mouthfeel preservation in reduced-sugar applications command premium compensation.
- Legacy System Integration:Beverage manufacturers face friction embedding novel high-potency compounds into existing production lines calibrated for sucrose rheology.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Food Sweetener Market |
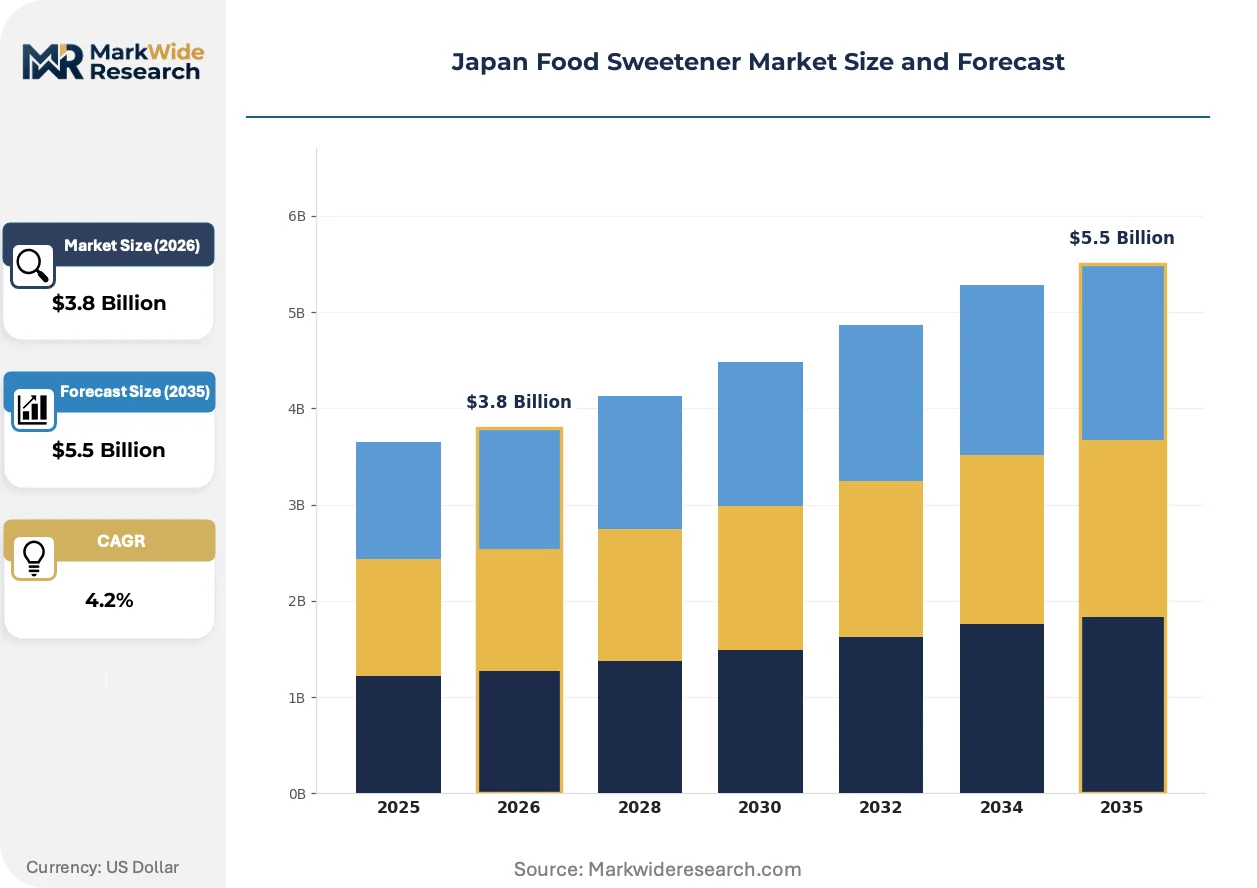
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sucrose, Fructose, Stevia, Aspartame Application: Beverages, Confectionery, Bakery, Dairy Form: Liquid, Powder, Granulated, Syrup Distribution Channel: Online, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Cargill, Incorporated, Mitsui DM Sugar Holdings Co., Ltd, Mitsubishi Corporation, Nagase & Co. Ltd, Tate and Lyle Plc, Ajinomoto Co., Inc., Showa Sangyo Co. Ltd, Matsutani Chemical Industry Co. Ltd, Japan Corn Starch Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Food Sweetener Market Shifts & Advancements
Biotechnology fermentation and digital procurement platforms are restructuring how sweetener compounds reach Japanese food processors. Three developments merit particular attention.
Stevia glycoside extraction and enzymatic modification is absorbing volume share from synthetic high-intensity alternatives in beverage applications. Major soft drink bottlers have accelerated adoption timelines from pilot to commercial scale within eighteen-month windows. This absorption is compressing demand for aspartame and acesulfame potassium in carbonated and still beverage categories.
METI's 2023 nutrition labeling revision mandates line-item disclosure of added sugars exceeding defined thresholds, with enforcement beginning in fiscal year 2025. Food manufacturers are restructuring ingredient declarations to minimize visible sugar content. Premium confectionery brands face the steepest compliance costs as they reformulate heritage recipes.
Direct-to-manufacturer digital procurement is fragmenting traditional distributor dominance in sweetener supply chains. Large food processors now benchmark rare sugar and high-intensity compound pricing through subscription-based platforms rather than incumbent trading houses. This behavioral shift concentrates most visibly in Tokyo and Osaka metropolitan manufacturing zones where procurement functions have centralized.
Japan Food Sweetener Market Segmentation
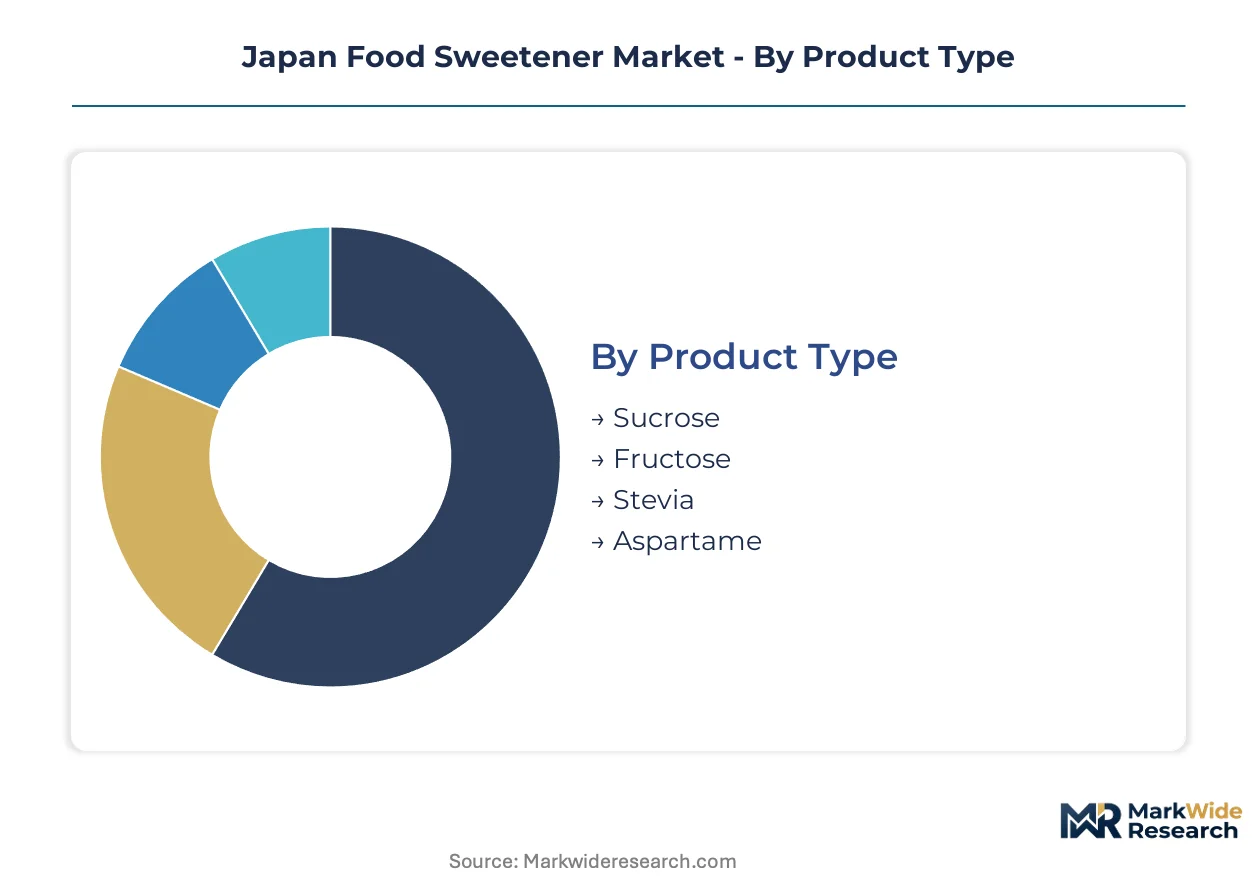
Segmentation in the Japan Food Sweetener Market reveals how reformulation pressures and METI labeling mandates are fragmenting demand across molecular categories and physical formats. Procurement patterns diverge sharply between beverage manufacturers chasing clean-label positioning and confectionery producers defending heritage formulations.
Product Type:
The customization-vs-standardization spectrum spans commodity sucrose at one pole and precision-engineered high-intensity compounds at the other, with fermentation-derived alternatives occupying the contested middle ground.
- Sucrose:Derived from sugarcane and sugar beet through crystallization refining, this caloric disaccharide retains dominant volume share in Japanese confectionery applications. Demand concentrates in heritage wagashi producers and institutional bakery channels across the Kanto corridor, though METI disclosure mandates are forcing gradual displacement in premium positioning segments.
- Stevia:Glycoside extracts from Stevia rebaudiana leaves deliver 200-400x sucrose sweetness intensity with negligible caloric contribution. Beverage reformulation programs in Tokyo-Yokohama processing clusters are accelerating procurement of enzymatically modified Reb M and Reb D variants that bypass bitter aftertaste limitations.
- Fructose:Monosaccharide sweetness from corn or sugarcane hydrolysis provides enhanced flavor release in cold beverage applications.
- Aspartame:Dipeptide methyl ester compound synthesized from phenylalanine and aspartic acid serves cost-sensitive carbonated drink segments.
Leading the category by volume: sucrose. Expanding most quickly: stevia glycoside variants.
Application:
Cost tier stratification separates premium reformulation projects from mass-market line extensions, with compliance-driven investments clustering in disclosure-sensitive categories.
- Beverages:Functional and reduced-sugar drink manufacturers drive fastest adoption of high-intensity alternatives, with carbonated soft drinks and RTD teas absorbing the majority of stevia and rare sugar volumes in Japan.
- Confectionery:Traditional candy and chocolate producers face the steepest technical barriers, as sucrose contributes critical crystalline structure and shelf stability that high-potency substitutes cannot replicate without extensive formulation redevelopment.
- Bakery:Yeast-fermented and chemically leavened products require Maillard-reactive sugars for browning and moisture retention, limiting direct substitution rates.
- Dairy:Yogurt and flavored milk applications balance sweetness intensity with probiotic culture compatibility and freeze-thaw stability requirements.
Highest compliance investment intensity: beverages. Most reformulation-resistant: confectionery heritage segments.
Form:
Margin pools separate concentrated liquid formats commanding premium industrial pricing from commodity granulated products competing on scale.
- Liquid:Pumpable high-fructose and rare sugar solutions enable precise dosing in automated beverage production lines, capturing premium pricing in Osaka-Kobe manufacturing belt soft drink operations.
- Powder:Spray-dried and agglomerated formats serve dry blend applications where dissolution speed and flowability determine processing efficiency.
- Granulated:Crystalline sucrose and blended sugar products dominate retail channel shelf presence and institutional bakery procurement.
- Syrup:Viscous aqueous solutions provide humectant functionality and visual gloss in premium confectionery glazing operations.
Premium pricing concentration: liquid formats. Volume leadership: granulated sucrose.
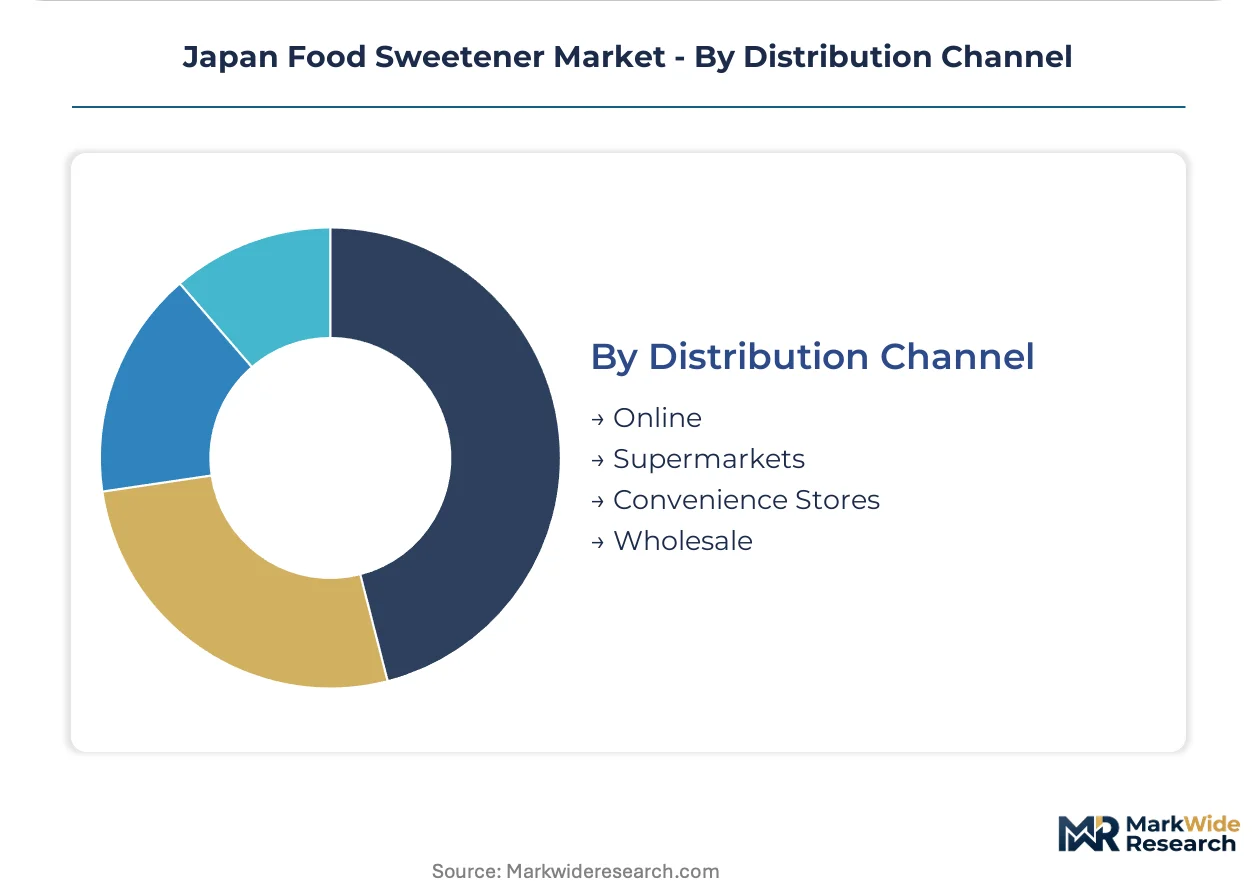
Distribution Channel:
Customer type fragmentation splits procurement between centralized manufacturing direct-buy and fragmented retail channel replenishment.
- Wholesale:Trading houses and industrial distributors maintain dominant position in bulk sweetener movement to food processors, though digital procurement platforms are eroding traditional margin structures.
- Online:Subscription-based flavor optimization platforms and direct-manufacturer portals are gaining share among mid-sized beverage and bakery operations seeking rare sugar and high-intensity compound price transparency.
- Supermarkets:Packaged consumer sweetener SKUs serve household baking and tabletop use cases with established brand loyalty.
- Convenience Stores:Single-serve and small-format retail presence targets impulse and immediate-consumption scenarios.
Fastest channel transformation: online procurement platforms. Remaining volume concentration: wholesale industrial distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan produces minimal domestic sugarcane and relies heavily on imported raw materials for sweetener manufacturing. Consumption concentrates in industrial processing corridors where beverage and confectionery manufacturers drive procurement patterns. METI labeling mandates are redistributing demand across domestic production zones.
Kanto/Tokyo
Functional beverage manufacturers dominate procurement of high-intensity sweeteners and rare sugars in the Tokyo-Yokohama processing belt. METI's 2023 nutrition labeling revision forces reformulation investments among carbonated drink bottlers headquartered in the capital region. The Kanto corridor absorbs the majority of stevia glycoside volumes for reduced-sugar product lines.
Kansai/Osaka
Traditional confectionery producers in Osaka-Kobe manufacturing zones defend heritage formulations against disclosure-driven substitution pressures. The Consumer Affairs Agency monitors health claim substantiation from regional headquarters in Osaka. Underpenetrated rare sugar distribution networks present expansion opportunities for fermentation-derived sweetener suppliers.
Chubu/Nagoya
Industrial bakery channels in the Chubu region maintain long-term volume contracts for granulated sucrose despite commodity price volatility. JIS purity specifications for food-grade sweeteners favor certified domestic producers supplying Nagoya-based processors. Automated production lines in Aichi Prefecture favor liquid syrup formats for precise dosing efficiency.
Kyushu
Sugar beet cultivation in northern Kyushu provides limited domestic raw material for regional sucrose refining operations. Local processors face margin compression from import-dependent supply chains subject to currency fluctuation. Fukuoka manufacturing zones show emerging interest in enzymatically modified stevia variants for export-oriented beverage production.
Hokkaido
Beet sugar production in Hokkaido sustains Japan's only significant domestic sucrose extraction capacity. Cold climate agriculture limits cultivation scale, constraining supply security for northern confectionery manufacturers. Sapporo-based food technologists command premium compensation for reformulation expertise in reduced-sugar dairy applications.
Japan Food Sweetener Market Competitive Landscape
Top-tier vendors anchor fermentation biotechnology and traditional distribution networks, while mid-scale specialists occupy rare sugar and high-intensity compound niches. The vendor base stratifies across amino acid-derived sweetener producers, beet sugar refiners, and trading house intermediaries. Three archetypes dominate: fermentation platform operators, rare sugar specialists, and legacy sucrose distributors. Competitive moves concentrate on backward integration into raw material sourcing and digital procurement platform development.
Within the fermentation platform tier, Ajinomoto Co., Inc. and Matsutani Chemical Industry Co. Ltd exemplify divergent specialization strategies. Ajinomoto leverages amino acid fermentation expertise to anchor high-intensity sweetener supply chains, while Matsutani occupies a defensible position in rare sugar production for functional ingredient markets. Mitsui DM Sugar Holdings Co., Ltd represents the legacy distribution archetype, sustaining volume leadership across institutional channels through traditional sucrose network control.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Mitsui DM Sugar Holdings Co., Ltd |
| Mitsubishi Corporation |
| Nagase & Co. Ltd |
| Tate and Lyle Plc |
| Ajinomoto Co., Inc. |
| Showa Sangyo Co. Ltd |
| Matsutani Chemical Industry Co. Ltd |
| Japan Corn Starch Co. |
| Others |
Supply & Pricing Matrix
Fermentation biotechnology scale-up is compressing unit economics for high-intensity sweeteners while concentrating production capacity among amino acid platform operators. This technological transition simultaneously reduces per-kilogram production costs and tightens supply control among certified domestic manufacturers navigating METI and JIS compliance frameworks.
Pricing Analysis
Margin tightening in liquid rare sugar formats reflects enzymatic processing cost premiums and precision dosing requirements in automated beverage lines. Three-tier pricing structure across premium enzymatically-modified stevia variants, standard fermentation-derived compounds, and economy-grade synthetic alternatives dominates procurement. Pricing pressure stems from digital procurement platforms collapsing traditional distributor markups. Institutional bakery channels locked into granulated sucrose contracts show highest price sensitivity, while functional beverage manufacturers absorb premiums for clean-label positioning.
Supply Chain Analysis
Direct-to-manufacturer digital channels handle mid-scale beverage and bakery procurement, though wholesale trading houses retain bulk institutional dominance. Raw material dependencies center on imported sugarcane and sugar beet feedstock, amino acid fermentation precursors, and stevia leaf extracts. Supply chain risk concentrates in single-source vulnerability for JIS-certified domestic fermentation capacity. Distribution runs through Tokyo-Yokohama processing clusters for high-intensity compounds and Osaka-Kobe corridors for traditional confectionery inputs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's food sweetener sector sits at a fermentation technology transition phase, with amino acid-derived and enzymatically-modified compounds displacing synthetic high-intensity alternatives. This substitution dynamic favors platform operators with backward integration into microbial strain development.
For Market Incumbents: Anchor fermentation capacity expansion in JIS-certified facilities to defend against import raw material barriers tightening under METI enforcement. Deepen backward integration into amino acid precursor supply to secure margin position as stevia glycoside extraction scales. Prioritize rare sugar IP portfolios around enzymatic modification patents before FOSHU pathway clarity accelerates competitor R&D.
For New Entrants and Emerging Players: Launch via subscription-based flavor optimization platforms targeting mid-tier beverage manufacturers in the Kansai manufacturing belt. Underpenetrated rare sugar distribution networks in Osaka-Kobe corridors offer lowest competitive density. Position around technical formulation support services, as reformulation talent scarcity commands premium positioning.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by fermentation platform operators seeking rare sugar capabilities. Long-term viability favors specialists with JIS certification and FOSHU approval track records. Monitor METI disclosure threshold enforcement as the signal indicating accelerated reformulation capex cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Feedstock | Captive amino acid supply secures cost position against imported precursor volatility. |
| JIS Certification Investment | Compliance barrier creation limits import competition in food-grade sweetener segments. |
| FOSHU Approval Pathway Development | Regulatory clarity on functional claims enables premium positioning in health-conscious channels. |
| Digital Procurement Platform Launch | Direct manufacturer relationships collapse traditional trading house margin structures. |
| Rare Sugar Distribution Network Expansion | Osaka-Kobe corridor penetration captures underpenetrated confectionery reformulation demand. |
Research Methodology
Multi-period observation of METI labeling enforcement timelines, fermentation capacity expansions, and procurement platform adoption anchored the trend analysis, supplemented by interviews with beverage formulation directors, confectionery R&D heads, JIS certification auditors, and trading house procurement managers. Secondary validation drew from METI regulatory filings, Consumer Affairs Agency health claim databases, customs import records for raw sugar materials, and food processor SEC disclosures. Bottom-up segment sizing triangulated against top-down market value estimates.
Segment-weighting across product type, application, physical form, and distribution channel dimensions structured the analytical framework. CAGRs were derived from trend extrapolation of reformulation investment cycles and substitution elasticity estimates. Industry-specific inputs included FOSHU approval pipeline tracking and rare sugar production capacity utilization rates across domestic fermentation facilities.
Regulatory enforcement delays, fermentation yield breakthroughs, and currency fluctuation in imported feedstock markets are the dominant revision risks. Forecasts reflect documented assumptions on substitution timelines and compliance cost pass-through rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Glucose Syrup Market
Sweeteners
Gluten-Free Sugar Syrup Market
Sweeteners
Low-Fat Sugar Market
Sweeteners
United Kingdom Food Sweetener Market
Sweeteners
Fructose Market
Sweeteners
Global Starch Sweetener Market
Sweeteners
Sugar-Free Syrups Market
Sweeteners
Saudi Arabia Allulose Market
Sweeteners
High-Intensity Sweeteners Market
Sweeteners
Sucrose Acetate Isobutyrate Market
Sweeteners
Tapioca Maltodextrin Market
Sweeteners
Rare Sugar Market
Sweeteners
South America Food Sweetener Market
Sweeteners
Australia Allulose Market
Sweeteners
Sugar Beet Juice Extract Market
Sweeteners
United States Food Sweetener Market