
 Low Fat Protein Snacks Market | 2026-2036
Low Fat Protein Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Protein Snacks Market Analytics
Asset-light contract manufacturing is fragmenting competitive dynamics in low fat protein snacks, enabling new entrants to scale without capital-intensive production facilities. Quest Nutrition LLC leverages co-manufacturing partnerships to extend its flavor innovation pipeline across North American retail channels. General Mills sustains category leadership through captive R&D facilities that control proprietary extrusion processes for texture-optimized protein matrices. PepsiCo anchors its position via direct-store-delivery networks that dominate convenience and gas station channels where impulse protein purchases concentrate.
Low fat protein snacks are formulated food products containing reduced lipid content with protein concentrations typically ranging from ten to thirty grams per serving, manufactured through extrusion, baking, or cold-pressing processes designed to preserve amino acid bioavailability while limiting caloric density from fat sources. The ingredient dimension shows whey protein occupying the premium tier due to superior leucine content and established sports nutrition positioning, while pea protein differentiates through allergen-free claims that unlock vegan and clean-label consumer segments. Pouch packaging leads volume growth in on-the-go consumption occasions, though box formats retain margin advantages in subscription and club retail channels where unit economics favor larger pack sizes.
FDA nutrition labeling requirements and EFSA health claim frameworks shape permissible protein content assertions and front-of-pack communication across major markets, directly influencing reformulation investments and new product qualification timelines. The EU Green Deal packaging directives and emerging extended producer responsibility schemes in California and New York add compliance layers that favor suppliers with integrated sustainable packaging capabilities. Stakeholders must monitor evolving amino acid scoring methodologies and front-of-pack warning label expansions that could recategorize products currently positioned as health-forward alternatives.
Market Dynamics
Clean-label formulation mandates from the FDA and EFSA are compressing reformulation cycles and forcing ingredient transparency across protein snack portfolios, fundamentally restructuring how manufacturers qualify new products for retail distribution.
Growth Catalysts
- Fitness-oriented consumer segments:Corporate wellness programs in the United States and Germany are institutionalizing protein snack procurement, creating institutional demand pull that stabilizes volume forecasts for ready-to-eat formats.
- EU Green Deal packaging directives:Extended producer responsibility schemes in California and New York are accelerating investment in recyclable pouch technologies, favoring suppliers with integrated sustainable packaging capabilities.
- Pea protein processing advances:Cold-pressing extraction methods are improving amino acid bioavailability in allergen-free formulations, unlocking vegan consumer segments previously inaccessible to whey-dependent portfolios.
Market Restraints
- Leucine-standard whey protein concentration:Premium-tier whey sourcing concentrates in New Zealand and Irish dairy cooperatives, creating input cost volatility that compresses margins for mid-tier brands.
- Extrusion equipment capital intensity:Proprietary texture-optimized protein matrix production requires captive R&D facilities with multi-million dollar extrusion lines, erecting barriers to in-house manufacturing scale.
- Front-of-pack warning label expansion:Emerging nutrient profiling schemes in Latin American markets threaten to recategorize products currently positioned as health-forward alternatives, complicating international portfolio standardization.
Strategic Opportunities
- Chinese functional nutrition retail:Specialized distribution infrastructure for sports nutrition in tier-one cities remains underpenetrated relative to per-capita protein consumption growth, creating whitespace for format innovation.
- Subscription channel economics:Box formats with larger pack sizes generate superior unit economics in club retail, enabling direct-to-consumer models that bypass conventional slotting fee structures.
- Dual carbon goals alignment:China's national carbon neutrality targets are accelerating demand for plant-protein formulations with verified supply chain emissions data, rewarding early movers in lifecycle assessment documentation.
Industry Challenges
- Food technologist specialization gap:Formulating palatable low-fat protein matrices requires expertise in hydrocolloid stabilization and flavor masking that outpaces current vocational training pipeline output.
- Amino acid scoring methodology evolution:Pending updates to FAO/WHO protein quality benchmarks threaten to invalidate existing content claims, forcing preemptive reformulation investments ahead of regulatory certainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Protein Snacks Market |
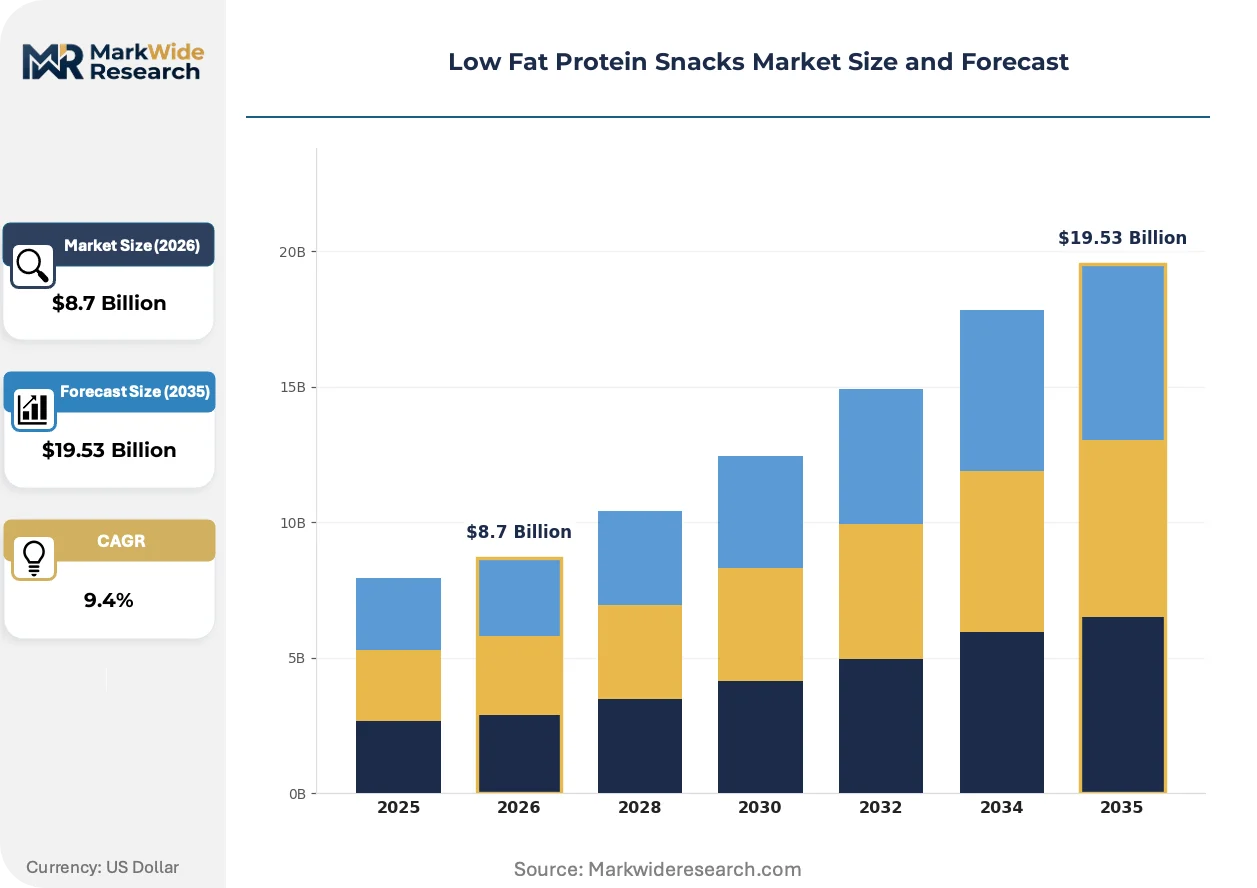
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bars, Chips, Cookies, Powders Ingredient Type: Whey Protein, Soy Protein, Pea Protein, Casein Flavor Profile: Chocolate, Vanilla, Berry, Savory Packaging Type: Bags, Boxes, Pouches, Tubs |
| Companies Covered | Quest Nutrition LLC, General Mills, PepsiCo, Mondelez International, Nestlé, Kellanova, The Simply Good Foods Company, Kellogg Company, Tyson Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Protein Snacks Market Evolving Landscape
Digital traceability infrastructure is penetrating protein snack supply chains, compressing qualification timelines while enabling real-time compliance documentation that satisfies both retailer requirements and emerging disclosure mandates.
Blockchain-enabled ingredient provenance tracking is digitizing supplier verification workflows for whey and pea protein sourcing. Major retail banners in Germany and the United States are mandating lot-level traceability data for shelf placement, accelerating adoption among contract manufacturers seeking to defend co-packing relationships. This technology is digitizing quality assurance documentation that previously required manual audit trails, reducing new supplier onboarding cycles.
EFSA health claim frameworks are tightening permissible protein content assertions on front-of-pack labeling, directly constraining marketing vocabulary for sports nutrition positioning. Manufacturers must now substantiate muscle maintenance claims with clinical trial data, extending new product development timelines. Ready-to-drink formats face the strictest scrutiny, prompting reformulation toward bar and bite formats where satiety claims face lower evidentiary thresholds.
Impulse purchase patterns are fragmenting across channel types, with convenience and gas station networks capturing growing share of unplanned protein snack transactions. Direct-store-delivery networks dominate these locations, displacing traditional warehouse distribution for single-serve formats. This shift concentrates volume in channels where price elasticity is highest, pressuring manufacturers to develop channel-specific SKU architectures.
Low Fat Protein Snacks Market Segmentation
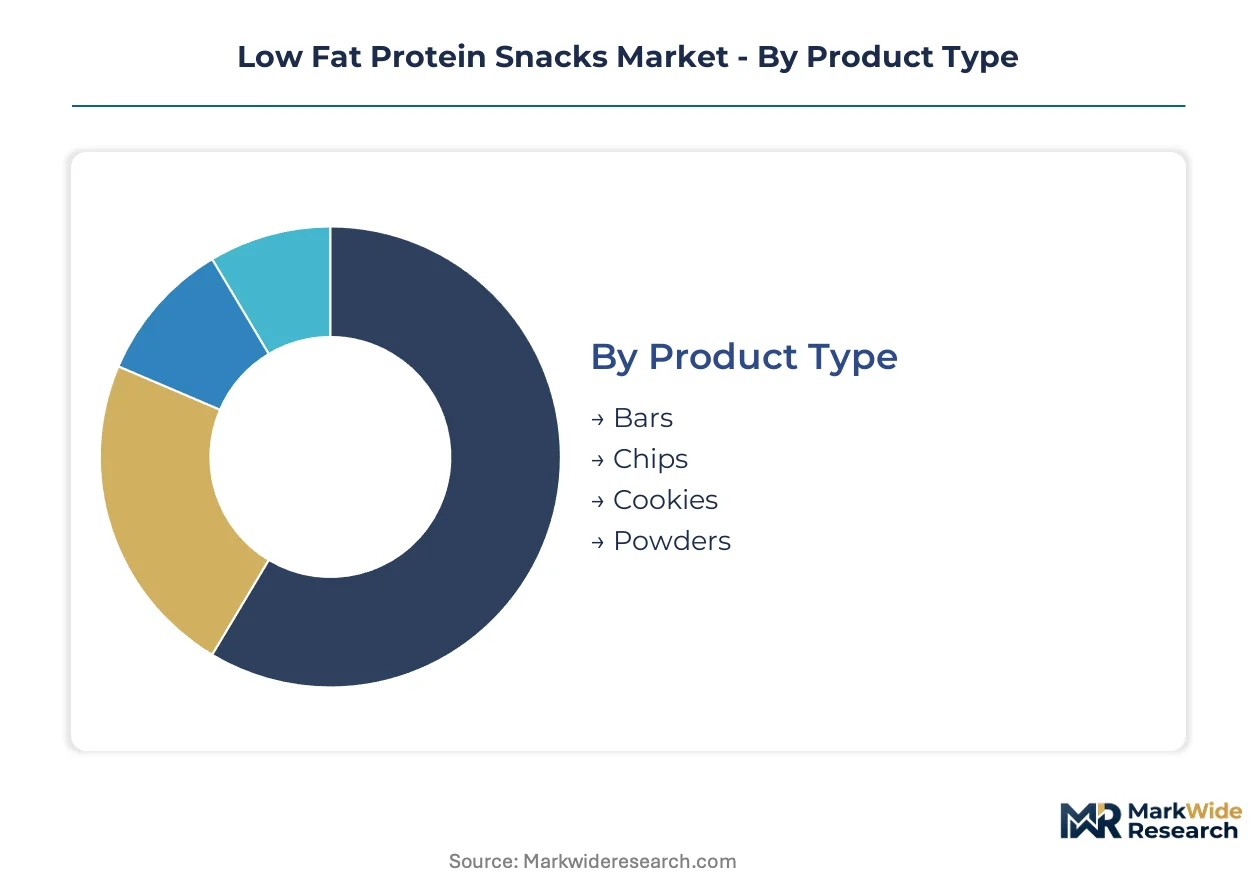
Segmentation in low fat protein snacks determines manufacturing asset allocation and channel strategy. Product format dictates extrusion versus baking capital requirements. Ingredient selection governs allergen labeling complexity and premium positioning potential.
Product Type:
After-sales service intensity varies sharply across formats, with bars requiring minimal consumer support while powders demand extensive usage guidance and satisfaction guarantees.
- Bars:Extruded or cold-pressed formats with 10-30g protein per serving, stabilized through hydrocolloid matrices to achieve chewy texture without fat-laden binders. Demand concentrates in United States convenience channels where impulse purchases dominate; corporate wellness programs institutionalize procurement for ready-to-eat formats.
- Chips:Baked or air-popped protein crisps using extruded protein isolates, formulated for crunch retention in low-moisture environments. German fitness retail shows strongest adoption, driven by clean-label positioning that satisfies EFSA health claim frameworks.
- Cookies:Soft-baked formulations replacing butter with protein-enriched fat replacers, targeting indulgence-seeking consumers in subscription channels.
- Powders:Spray-dried or agglomerated protein concentrates requiring reconstitution, dominating Chinese e-commerce platforms where tier-one city consumers prioritize cost-per-gram efficiency.
Bars hold the largest share; momentum sits with chips as clean-label positioning accelerates.
Ingredient Type:
Cost tier stratification separates premium dairy-derived isolates from economy plant concentrates, with mid-tier blends capturing price-sensitive performance consumers.
- Whey Protein:Leucine-rich dairy isolates with superior amino acid scoring under FAO/WHO benchmarks, commanding premium pricing in sports nutrition channels. New Zealand and Irish dairy cooperatives concentrate supply, creating input cost volatility that compresses margins for mid-tier brands.
- Soy Protein:Isolated or concentrated legume proteins with established supply infrastructure, facing consumer perception challenges in North American markets despite functional equivalence.
- Pea Protein:Allergen-free isolates extracted through cold-pressing methods that improve amino acid bioavailability, unlocking vegan segments previously inaccessible to whey-dependent portfolios.
- Casein:Slow-digesting milk proteins forming micellar gels, targeting overnight recovery positioning in specialized sports nutrition retail.
Whey protein commands the premium tier; pea protein is gaining share fastest as allergen-free claims reshape formulation priorities.
Flavor Profile:
Application context determines flavor innovation investment, with post-workout occasions tolerating functional taste profiles while desk-snacking occasions demand full indulgence masking.
- Chocolate:Cocoa-based formulations using alkalized powders or chocolate coatings, dominating United States mass retail where familiarity reduces trial barriers.
- Vanilla:Neutral base flavors enabling protein taste masking, prevalent in powder formats where mixability with other ingredients matters.
- Berry:Fruit-infused profiles using natural or nature-identical flavor systems, performing strongly in German organic retail channels.
- Savory:Cheese, barbecue, or spice-forward formulations displacing traditional salty snacks, concentrated in Chinese convenience stores where local palate preferences favor umami over sweetness.
Chocolate maintains volume leadership; savory is climbing the fastest as meal-replacement positioning expands beyond sweet occasions.
Packaging Type:
Customer type stratification separates individual convenience seekers from household stockpilers, with format selection directly impacting unit economics and distribution channel fit.
- Bags:Flexible film structures for multi-serve chip or bite formats, standard in club retail where per-ounce pricing drives purchase decisions.
- Boxes:Rigid paperboard containers enabling shelf differentiation and portion control, generating superior unit economics in subscription channels that bypass conventional slotting fees.
- Pouches:Stand-up or flat barrier films with reseal features, leading volume growth in on-the-go consumption across United States gas station networks where impulse protein purchases concentrate.
- Tubs:Rigid plastic containers with wide-mouth access for scoop-based powder dispensing, dominant in Chinese e-commerce where shipping durability concerns favor protective packaging.
Pouches capture the fastest volume expansion; boxes retain margin advantages in direct-to-consumer channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in low fat protein snacks tilt toward net-import dependence in premium whey-dependent markets, while plant-protein manufacturing hubs in Asia-Pacific generate surplus capacity for regional export.
United States
FDA nutrition labeling requirements and corporate wellness procurement programs institutionalize demand for ready-to-eat formats. Convenience and gas station networks concentrate impulse purchases through direct-store-delivery dominance. Chicago and Dallas-Fort Worth anchor co-manufacturing clusters serving national retail banners.
Germany
EFSA health claim frameworks and EU Green Deal packaging directives compress reformulation timelines for clean-label positioning. Organic retail channels in Berlin and Munich show strongest adoption of baked protein chips. Bavaria hosts specialized extrusion equipment suppliers serving Central European contract manufacturers.
China
Dual carbon goals and tier-one city functional nutrition retail expansion accelerate plant-protein formulation demand. SAMR registration requirements for imported sports nutrition products extend qualification timelines. Shanghai and Shenzhen concentrate e-commerce distribution infrastructure for powder formats.
United Kingdom
Subscription channel economics and club retail penetration favor box-format unit economics over conventional slotting structures. FSA front-of-pack labeling consultations threaten recategorization of current health-forward positioning. Greater Manchester hosts cold-pressing equipment specialists serving allergen-free vegan segments.
India
FSSAI protein content claim regulations and PLI scheme incentives for food processing investment reshape domestic manufacturing capacity. Tier-one metro consumers in Mumbai and Bangalore drive trial of savory-flavored formats displacing traditional salty snacks. Gujarat concentrates pea protein isolate import processing for regional formulation.
Low Fat Protein Snacks Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream controlling proprietary extrusion processes and flavor innovation pipelines. Market structure tilts toward consolidation at the branded portfolio level, with mid-tier players dependent on asset-light contract manufacturing for scale. Three archetypes dominate: captive R&D facilities with multi-million dollar extrusion lines, co-manufacturing partnerships enabling rapid flavor extension, and direct-store-delivery networks capturing impulse channel concentration. Competitive moves concentrate on strategic partnerships for sustainable packaging integration and portfolio diversification into allergen-free vegan positioning.
Within the branded platform tier, Quest Nutrition LLC and General Mills occupy distinct strategic positions. Quest Nutrition LLC exemplifies the co-manufacturing archetype, leveraging external production partnerships to extend innovation velocity without capital-intensive facility ownership. General Mills represents captive R&D integration, controlling proprietary texture-optimized protein matrices through in-house extrusion capabilities. PepsiCo anchors the distribution-intensive archetype, with network density in convenience and gas station channels where unplanned protein purchases concentrate. Mondelez International and Nestlé sit within the diversified snacking conglomerate tier, cross-leveraging formulation expertise from adjacent confectionery and nutrition portfolios. Kellanova and The Simply Good Foods Company exemplify mid-scale specialists navigating the tension between clean-label positioning requirements and input cost volatility from premium-tier whey sourcing.
| Leading Market Players |
|---|
| Quest Nutrition LLC |
| General Mills |
| PepsiCo |
| Mondelez International |
| Nestlé |
| Kellanova |
| The Simply Good Foods Company |
| Kellogg Company |
| Tyson Foods |
| Others |
Value Network & Pricing Analysis
Single-source dependency on New Zealand and Irish dairy cooperatives for leucine-standard whey protein determines both the premium-economy spread in finished snack pricing and the geographic configuration of contract manufacturing networks. Tariff exposure on imported plant protein isolates and EFSA-compliant packaging materials further compresses margin structures for mid-tier brands lacking captive supply arrangements.
Pricing Analysis
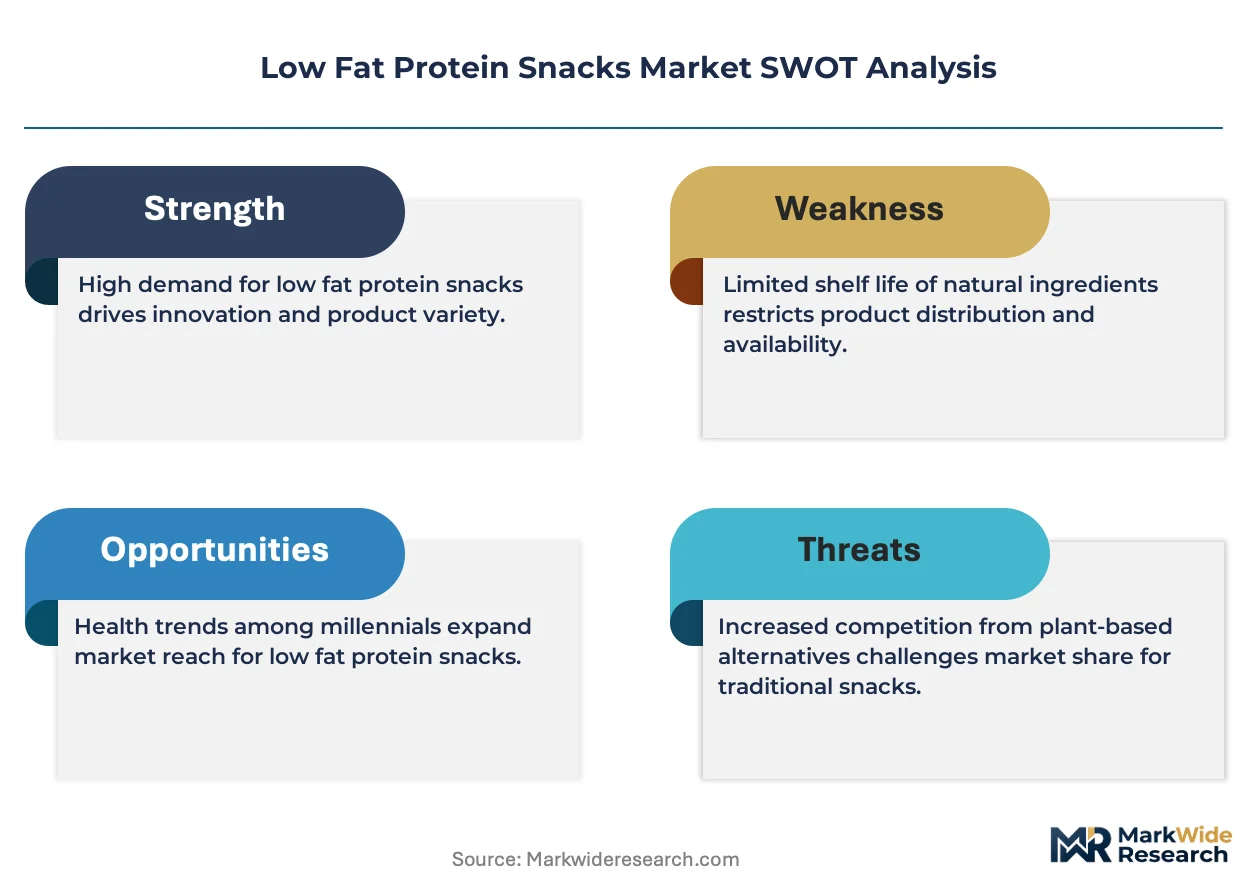
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the low fat protein snacks market. Price differentiation separates whey-based formulations with FAO/WHO amino acid scoring certification from pea protein alternatives and economy soy blends. Cost compression in the standard tier is intensifying because cold-pressing equipment suppliers in Germany and China are expanding capacity. Corporate wellness procurement teams show lowest price sensitivity; convenience channel distributors exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for protein isolate sourcing. Manufacturing concentrates in the United States, Germany, and China, with New Zealand and Ireland anchoring premium whey raw material supply. Raw material dependencies include whey protein concentrates, pea protein isolates, and sustainable barrier films for pouch packaging. Distribution runs through direct-store-delivery networks for impulse channels and e-commerce fulfillment centers for subscription formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as fitness-oriented consumer segments splinter across occasion-based usage contexts, creating specialized niches for format-specific innovators.
For Market Incumbents: Pre-empt allergen-free vegan positioning by acquiring cold-pressing equipment specialists in Greater Manchester before pea protein processing advances commoditize the technology. Secure backward integration into sustainable packaging capabilities to defend co-packing relationships against EU Green Deal compliance requirements. Channel control through direct-store-delivery network density remains the priority lever against emerging contract-manufactured entrants. For New Entrants and Emerging Players: Pursue white-space in Chinese tier-one city functional nutrition retail, where specialized distribution infrastructure for sports nutrition remains underpenetrated relative to per-capita protein consumption growth. Target savory-flavored chip formats displacing traditional salty snacks in Indian metro markets. Anchor go-to-market through subscription channel economics that bypass conventional slotting fee structures. For Investors and Strategic Acquirers: Asset-light contract manufacturers with integrated sustainable packaging capabilities represent the most defensible acquisition archetype as extended producer responsibility schemes proliferate. Long-term viability hinges on qualification timeline compression through digital traceability infrastructure deployment. Watch for FAO/WHO amino acid scoring methodology updates as the signal indicating reformulation investment cycles ahead.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | EFSA health claim frameworks force clinical trial substantiation for muscle maintenance positioning. |
| Sustainable Packaging Integration | EU Green Deal directives favor suppliers with recyclable pouch technologies and lifecycle assessment documentation. |
| Direct-to-Consumer Channel Expansion | Subscription models bypass conventional slotting fees while capturing superior unit economics through box formats. |
| Allergen-Free Portfolio Diversification | Pea protein processing advances unlock vegan segments previously inaccessible to whey-dependent portfolios. |
| Digital Traceability Infrastructure | Blockchain-enabled provenance tracking compresses supplier onboarding cycles for major retail banners. |
Research Methodology
Initial hypotheses were tested against primary input from brand managers, category buyers at retail banners, supply planners, and contract manufacturing executives and refined through secondary validation. Sources included Nielsen retail audit data, FDA nutrition labeling guidance documents, EFSA health claim registers, and customs records for protein isolate trade flows. Bottom-up volume modeling across product formats and ingredient tiers triangulated with top-down macro consumption trend analysis.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, ingredient type, flavor profile, packaging type, and channel structure. CAGRs were derived from curve-fitting historical volume trajectories against projected fitness-oriented consumer penetration and corporate wellness program adoption. Industry-specific inputs incorporated extrusion equipment capacity utilization rates and cold-pressing technology diffusion patterns.
Macroeconomic conditions sit as an overlay; deviation in dairy commodity price volatility, tariff regimes, or carbon neutrality policy enforcement would shift the trajectory. Forecasts reflect documented assumptions on regulatory stability and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Asia-Pacific Snack Bar Market
Snacks
Organic Snack Food Market
Snacks
United Arab Emirates Energy Bar Market
Snacks
Fruit Jerky Market
Snacks
Granola Bars Market
Snacks
Non-Potato Veggie Chips Market
Snacks
Snack Bar Market
Snacks
Marshmallow Market
Snacks
United Kingdom Snack Bar Market
Snacks
Dairy Snacks Market
Snacks
North America Snack Pellets Market
Snacks
Veggie Chips Market
Snacks
Fried Potato Chips Market
Snacks
Plant-Based Snacks Market
Snacks
Organic Snacks Market
Snacks
Qatar Potato Chips Market