
 Beetroot Molasses Market | 2026-2036
Beetroot Molasses Market Size, Share, and Industry Trends Forecast 2026-2036
Beetroot Molasses Market Outlook
Asset-light leasing models for sugar processing equipment is rewriting competitive entry barriers in beetroot molasses production. ED&F MAN Deutschland GmbH leverages its European distribution footprint to secure bulk supply contracts. Amalgamated Sugar Company anchors its position through captive beet sourcing across the Pacific Northwest. Crosby Molasses Company specializes in premium-grade molasses for food manufacturers seeking clean-label ingredients.
Beetroot molasses is a viscous byproduct of sugar beet refining, containing approximately 50% fermentable sugars, minerals, and betaine, produced through countercurrent diffusion extraction followed by evaporation. Its primary commercial purpose spans fermentation feedstock, animal nutrition, and natural sweetener applications in processed foods. Conventional beetroot molasses dominates volume due to established supply chains, while organic beetroot molasses commands premium positioning among health-conscious consumers and clean-label food manufacturers. The health supplements application segment is gaining traction as betaine extraction for nutraceutical use expands processing margins beyond commodity sweetener markets.
The EPA oversees effluent discharge limits from sugar processing facilities, while the FDA sets food-grade purity standards for molasses destined for human consumption. USDA organic certification requirements shape product differentiation and pricing tiers for certified organic beetroot molasses. Stakeholders must monitor evolving clean-label regulations and betaine extraction technology economics to capture value migration from commodity to specialty applications.
Market Dynamics
The beetroot molasses market is being fundamentally restructured by the EU Green Deal and F-Gas Regulation, which are compelling processors to abandon conventional thermal evaporation in favor of membrane filtration and mechanical vapor recompression systems.
Growth Catalysts
- Betaine extraction technology:Advanced chromatographic separation methods now recover pharmaceutical-grade betaine from molasses, opening nutraceutical revenue streams that command multiples over commodity feedstock pricing.
- EU Green Deal compliance mandates:The European Commission's binding emissions targets for sugar processing facilities are accelerating capital deployment into closed-loop water recovery and biogas cogeneration systems.
- Germany:Concentrated beet sugar processing clusters in Saxony-Anhalt and Bavaria provide integrated infrastructure that lowers logistics costs for molasses offtake.
Market Restraints
- Natural gas price volatility:Evaporation stages consume substantial thermal energy, making processing margins vulnerable to European gas market fluctuations.
- Single-source dependency:Beet supply concentrates in temperate growing belts, creating harvest risk exposure to drought or frost in the North European Plain.
- Cane molasses substitution:Tropical cane molasses from Brazil and India competes on price for fermentation feedstock applications, pressuring beet-origin premiums.
Strategic Opportunities
- Organic certification tier:USDA organic and EU organic label requirements create pricing stratification that rewards processors investing in pesticide-free beet sourcing and non-synthetic processing aids.
- Precision fermentation feedstock:Synthetic biology companies seek consistent, traceable sugar profiles for cultured protein and bio-based chemical production.
- Direct-to-manufacturer platforms:Digital procurement portals are disintermediating traditional commodity traders, enabling molasses producers to capture margin from food and beverage formulators.
Industry Challenges
- Process engineering talent scarcity:Sugar technology expertise has atrophied as the industry consolidated, complicating recruitment for advanced separation and energy recovery roles.
- USDA organic certification timelines:Three-year transition requirements for land and processing equipment lock in compliance costs before premium pricing materializes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beetroot Molasses Market |
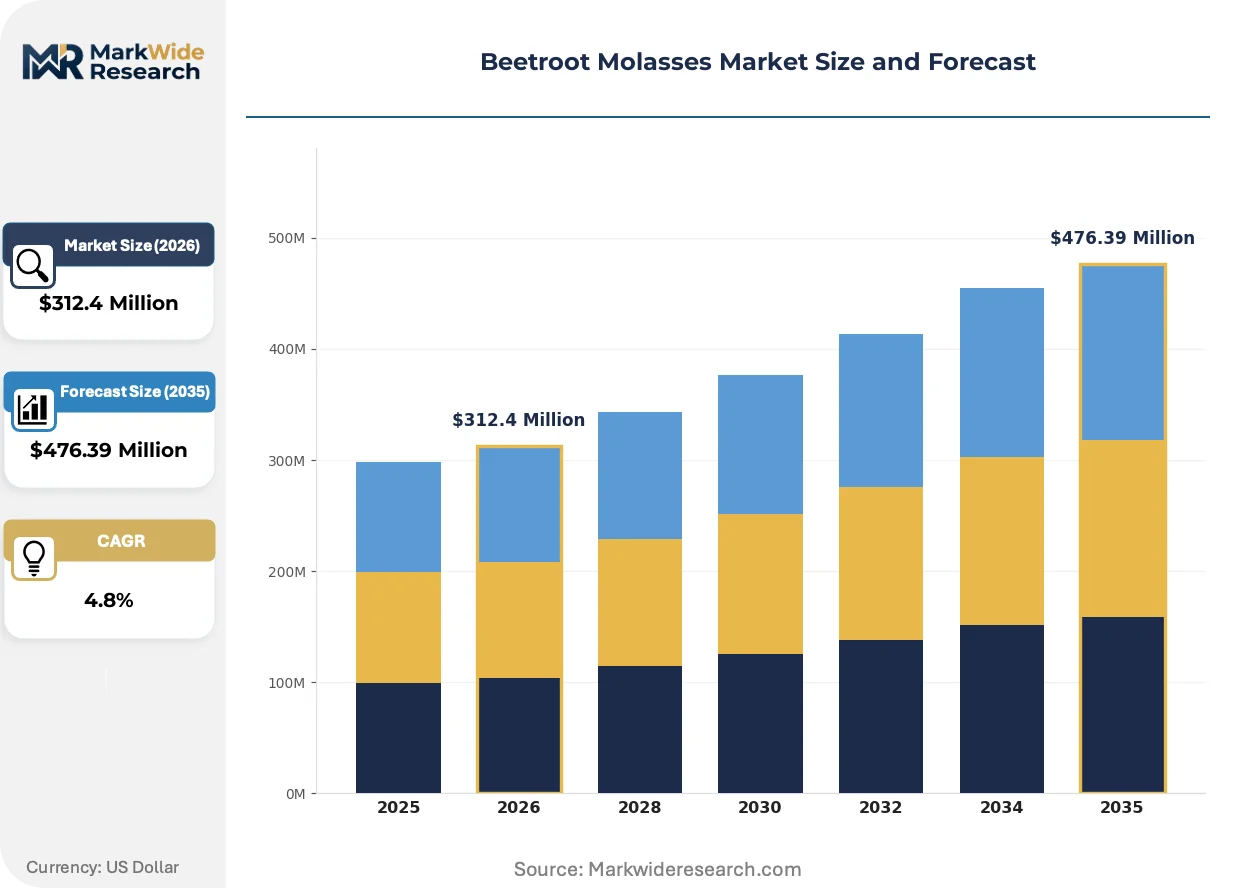
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Beetroot Molasses, Conventional Beetroot Molasses, Reduced Sugar Beetroot Molasses, Raw Beetroot Molasses Application: Food Industry, Beverage Production, Health Supplements, Animal Feed Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales End User: Food Manufacturers, Beverage Companies, Health-conscious Consumers, Agricultural Sector |
| Companies Covered | ED&F MAN Deutschland GmbH, Amalgamated Sugar Company, Spreckals Sugar Company, Renuka Beet Sugar, Michigan Sugar Company, American Crystal Sugar Company, Crosby Molasses Company, Daqahila Sugar Company, Nippon Beet Sugar Manufacturing Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beetroot Molasses Market Strategic Shifts
Digital process control and membrane separation technologies are displacing conventional thermal processing, while regulatory pressure on carbon intensity and water use is rewriting facility design standards.
Membrane filtration systems with nanofiltration and reverse osmosis stages are digitizing molasses concentration workflows by replacing multi-effect evaporators. Food-grade molasses producers in the Netherlands and Denmark are adopting these systems to meet corporate Scope 1 reduction commitments. The technology is digitizing energy management across extraction plants, cutting thermal loads by half while enabling real-time quality monitoring that reduces batch rejection rates.
REACH registration requirements for betaine derivatives are tightening purity documentation standards for molasses entering pharmaceutical and cosmetic supply chains. ECHA's updated guidance on substance identification demands enhanced analytical testing that smaller processors struggle to fund. German and French extraction facilities are responding by consolidating testing capabilities through third-party laboratory partnerships.
Clean-label procurement criteria now extend to ingredient provenance, with bakery and beverage formulators demanding batch-level traceability from beet field to final molasses delivery. This specification compression is eliminating spot-market purchasing in favor of annual contracts with defined sustainability metrics. The shift is most pronounced in Scandinavian markets, where retail chains require documented carbon footprints for shelf placement.
Beetroot Molasses Market Segmentation
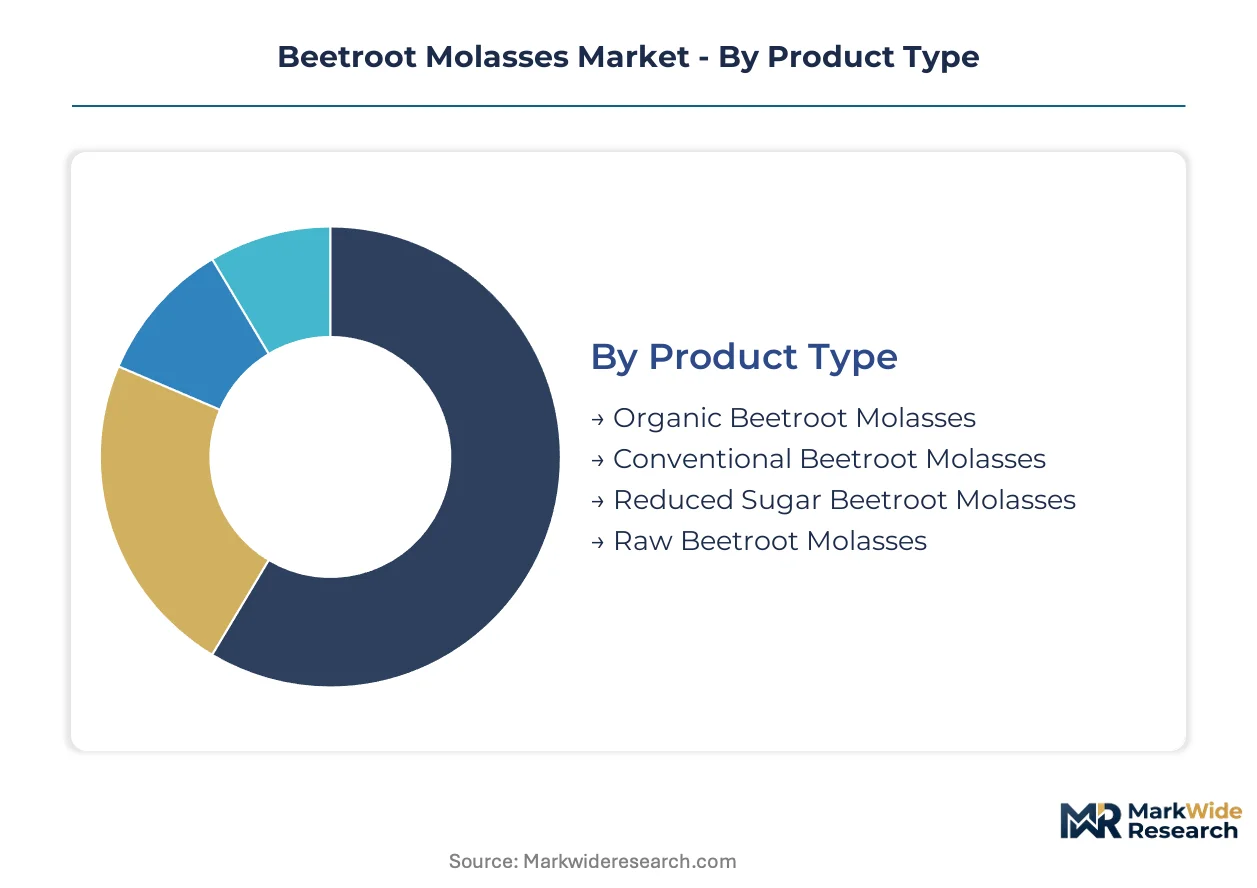
Segmentation in beetroot molasses reveals how certification tiers, processing intensity, and channel economics partition value capture. Product grade and application destination together determine margin structure across the value chain.
Product Type:
Maturity spreads across a spectrum from century-old conventional refining to nascent reduced-sugar extraction technologies.
- Conventional Beetroot Molasses:Standard-refinery output containing 50% fermentable sugars with residual minerals and betaine. German and French sugar beet cooperatives move the largest volumes into industrial fermentation and animal nutrition contracts.
- Organic Beetroot Molasses:USDA and EU organic certified, derived from pesticide-free beets using non-synthetic processing aids. Scandinavian bakery chains and clean-label food manufacturers in Denmark and Sweden absorb premium-priced supply under multi-year sourcing agreements.
- Reduced Sugar Beetroot Molasses:Membrane-filtered to lower fermentable carbohydrate content for specialized dietary applications.
- Raw Beetroot Molasses:Unrefined post-diffusion syrup retaining full mineral and betaine profile for bulk industrial buyers.
Conventional beetroot molasses handles the majority of throughput; organic beetroot molasses is climbing the fastest on share.
Application:
Cost tier separation distinguishes commodity feedstock uses from pharmaceutical-grade extraction.
- Food Industry:Natural sweetener and browning agent in baked goods, sauces, and confections requiring clean-label positioning. German and Dutch formulators specify low-ash grades for premium retail products.
- Health Supplements:Betaine extraction for nutraceutical capsules and sports nutrition formulations. Chromatographic separation facilities in France and Germany supply pharmaceutical-grade material to dietary supplement contract manufacturers.
- Beverage Production:Fermentation feedstock for alcohol and non-alcoholic fermented drinks.
- Animal Feed:Palatability enhancer and energy supplement for ruminant and swine rations.
Animal feed absorbs the largest volume base; health supplements commands the steepest expansion trajectory.
Distribution Channel:
Customer type dictates channel selection, with industrial buyers bypassing retail infrastructure entirely.
- Direct Sales:Bulk contracts between beet sugar processors and food manufacturers, fermentation facilities, or feed compounders. ED&F MAN Deutschland GmbH and similar traders coordinate multi-tonne annual offtake agreements with defined sustainability metrics.
- Specialty Stores:Premium organic SKUs targeting home bakers and wellness consumers in urban centers.
- Supermarkets:Standard-grade molasses in food-service sizing for restaurant and small-batch food producers.
- Online Retail:Direct-to-consumer packaging for niche health and culinary applications.
Direct sales captures the dominant share of tonnage; specialty stores is expanding most quickly in value terms.
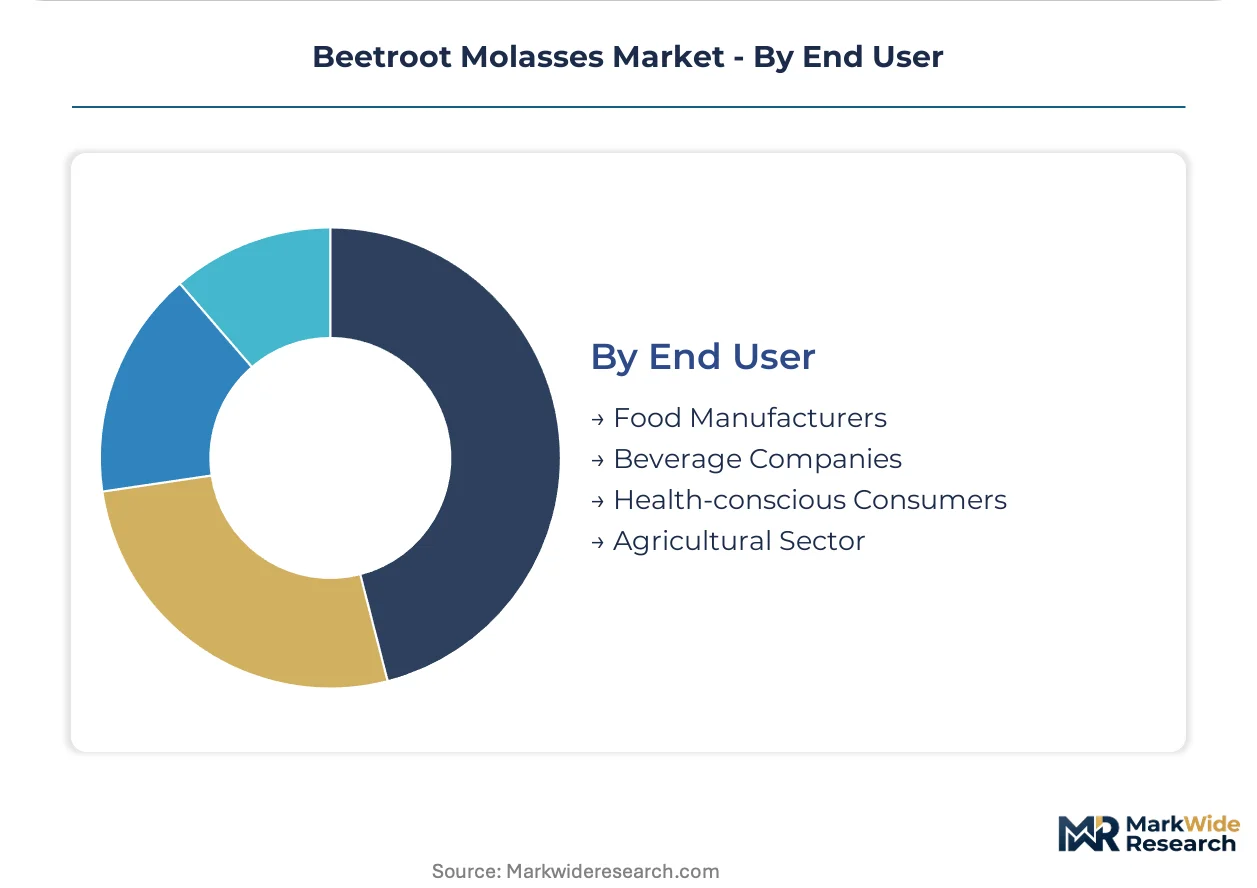
End User:
Supply concentration aligns with geography, as beet processing clusters determine accessible offtake.
- Food Manufacturers:Industrial bakeries, confectioners, and sauce producers requiring consistent viscosity and color specifications. Clean-label procurement teams in Scandinavia now mandate batch-level carbon footprint documentation.
- Agricultural Sector:Feed mills and livestock operations purchasing commodity-grade molasses for energy supplementation.
- Beverage Companies:Distillers and fermenters utilizing molasses as primary or adjunct sugar source.
- Health-conscious Consumers:Direct purchasers of organic molasses for home use in alternative sweetening and wellness applications.
Food manufacturers represent the largest demand block; health-conscious consumers is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beetroot molasses trade flows reflect regional sugar beet processing capacity and proximity to fermentation demand centers. Net exporters cluster in temperate beet-growing belts, while import dependence concentrates in tropical regions lacking domestic beet infrastructure.
Germany
Saxony-Anhalt and Bavaria host Europe's densest beet sugar processing clusters, supplying integrated molasses offtake to pharmaceutical-grade betaine extractors. The EU Green Deal and F-Gas Regulation compel facility upgrades toward membrane filtration and mechanical vapor recompression. Leipzig-Halle logistics corridors enable efficient bulk distribution to Dutch and Danish food formulators.
United States
Pacific Northwest beet cooperatives anchor domestic molasses supply for animal nutrition and industrial fermentation contracts. EPA effluent discharge limits shape processing facility investments, while USDA organic certification requirements segment pricing tiers for certified output. Michigan and Minnesota processing clusters serve Great Lakes food manufacturers seeking clean-label sweetener alternatives.
France
Nord-Pas-de-Calais and Champagne-Ardenne beet regions supply chromatographic betaine separation facilities serving pharmaceutical and cosmetic supply chains. ECHA REACH registration requirements tighten purity documentation standards for molasses derivatives. Strasbourg extraction specialists partner with German laboratories to consolidate analytical testing capabilities.
Japan
Hokkaido beet cultivation supports domestic molasses production for fermentation feedstock and specialty food applications. METI industrial policy encourages energy recovery investments in sugar processing facilities. Tokyo-Osaka distribution channels prioritize consistent viscosity specifications for confectionery and sauce manufacturers.
Egypt
Nile Delta beet farming supplies regional molasses demand for animal feed and alcohol fermentation. National agricultural programs expand beet cultivation to reduce import dependence for sugar derivatives. Alexandria processing infrastructure serves Middle Eastern markets lacking domestic beet processing capacity.
Beetroot Molasses Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in extraction technology and regional distribution. The vendor base organizes around three archetypes: integrated beet sugar cooperatives with captive molasses output, specialty traders coordinating multi-origin supply, and precision extraction firms isolating pharmaceutical-grade betaine. Competitive moves concentrate on backward integration into organic beet sourcing and technology licensing for membrane filtration systems.
Among European distribution specialists, ED&F MAN Deutschland GmbH exemplifies the trading archetype securing bulk supply contracts through continental logistics networks. Amalgamated Sugar Company and Crosby Molasses Company occupy positions on opposite ends of the value spectrum—one representing cooperative-scale integrated production, the other specializing in premium-grade clean-label positioning for food manufacturers. These three anchors illustrate how geographic concentration and certification tier differentiation stratify competitive positioning.
| Leading Market Players |
|---|
| ED&F MAN Deutschland GmbH |
| Amalgamated Sugar Company |
| Spreckals Sugar Company |
| Renuka Beet Sugar |
| Michigan Sugar Company |
| American Crystal Sugar Company |
| Crosby Molasses Company |
| Daqahila Sugar Company |
| Nippon Beet Sugar Manufacturing Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Natural gas price volatility in European thermal evaporation plants determines both the spread between organic and conventional molasses tiers and the geographic clustering of processing capacity around Germany's beet sugar cooperatives.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with pricing stratifying across organic certification, pharmaceutical-grade betaine content, and volume scale. The EU Green Deal compliance costs compress margins on conventional grades while USDA organic premiums widen. Feed compounders exhibit highest price sensitivity; pharmaceutical extractors accept premium positioning for traceability guarantees.
Supply Chain Analysis
Single-source dependency on North European Plain beet harvests dominates supply risk exposure, with raw material flows drawing from Germany, France, and Poland. Processing rests on natural gas for evaporation, membrane filtration equipment, and chromatographic separation resins. Distribution runs through Rotterdam-Antwerp bulk terminals and Leipzig-Halle rail corridors to fermentation facilities and food formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label procurement fragmentation creates specialty-tier openings for differentiated molasses positioning across Scandinavian bakery chains and precision fermentation feedstock buyers.
For Market Incumbents: Insulate captive beet sourcing through multi-year organic transition contracts with Saxony-Anhalt and Bavaria growers. Secure membrane filtration technology licensing before process engineering talent scarcity intensifies. Backward integration into pesticide-free land banking defends against USDA organic certification bottlenecks.
For New Entrants and Emerging Players: Build out direct-to-manufacturer digital procurement platforms disintermediating ED&F MAN Deutschland GmbH's trading dominance. Target reduced-sugar extraction for specialized dietary applications where incumbents lack processing flexibility. Position through batch-level carbon footprint documentation for Scandinavian retail chain compliance.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors precision extraction specialists over commodity processors. Five-to-ten-year viability hinges on betaine separation capabilities and organic certification infrastructure. Acquisition candidates should demonstrate chromatographic separation scale and closed-loop water recovery systems. Watch for F-Gas Regulation enforcement intensity as margin compression signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Adoption | EU Green Deal mandates displace thermal evaporation, halving energy loads at Dutch and Danish facilities. |
| Organic Certification Investment | Three-year land transition timelines lock in premium positioning before Scandinavian demand saturation. |
| Backward Integration into Beet Sourcing | Captive supply from Pacific Northwest cooperatives secures volume priority during harvest volatility. |
| Pharmaceutical-Grade Betaine Expansion | Chromatographic separation upgrades in France and Germany capture nutraceutical margin multiples. |
| Direct-to-Manufacturer Platform Launch | Digital procurement disintermediation captures margin from food formulators seeking traceability documentation. |
Study Parameters
A spread of perspectives from sugar processing plant managers, fermentation facility procurement leads, clean-label food formulators, membrane filtration technology providers, and EU regulatory affairs specialists converged on the working assumptions. Primary fieldwork combined with secondary validation from ECHA REACH guidance documents, USDA organic certification databases, EU F-Gas Regulation filings, and customs trade flows. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation by product certification tier, application destination, and regional processing cluster. CAGRs derived from historical capacity expansion rates, organic transition timelines, and betaine extraction technology diffusion curves. Forecast inputs incorporated natural gas price scenario modeling and EU emissions compliance cost trajectories.
Practitioners should monitor beet harvest yields in the North European Plain, F-Gas Regulation enforcement sequencing, and precision fermentation feedstock contract announcements for early signals. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Compressible Sugar Market
Sweeteners
Europe Natural Sweetener Market
Sweeteners
Brown Rice Syrup Market
Sweeteners
Dry Sweeteners Market
Sweeteners
Low-Calorie Sweetener Market
Sweeteners
Middle East and Africa Plant-Derived and Synthetic Sugar Market
Sweeteners
Japan Allulose Market
Sweeteners
Clarified Rice Syrup Market
Sweeteners
Isomaltooligosaccharide Market
Sweeteners
South America Sugar Substitutes Market
Sweeteners
Dry Molasses Market
Sweeteners
Sorbitol Market
Sweeteners
Rice Syrup Market
Sweeteners
Date Sugar Market
Sweeteners
Dextrates Market
Sweeteners
North America Starch Sweetener Market