
 Tapioca Maltodextrin Market | 2026-2036
Tapioca Maltodextrin Market Size, Share, and Industry Trends Forecast 2026-2036
Tapioca Maltodextrin Market Analytics
Multi-source procurement from Southeast Asian cassava processors is shifting toward vertically integrated supply agreements with dedicated extraction partners. Ingredion Incorporated leverages its Thai manufacturing footprint to secure consistent tapioca feedstock for North American and European customers. Cargill Incorporated anchors its position through backward integration into Vietnamese cassava farming cooperatives, reducing price volatility exposure. Roquette Frères differentiates via specialty hydrolyzed grades targeting pharmaceutical binding applications.
Tapioca maltodextrin is a carbohydrate polymer produced by partial enzymatic or acid hydrolysis of tapioca starch, typically yielding dextrose equivalents between 3 and 20, valued for its neutral flavor profile and excellent solubility in cold water systems. The ingredient functions primarily as a bulking agent, carrier for flavors and oils, and texture modifier across spray-dried preparations and instant dry mixes. Hydrolyzed grades dominate current volume flows due to their superior dispersibility in sports nutrition powders, while organic variants command concentrated margin pools from premium clean-label food and beverage contracts. Powder form occupies the largest share of commercial transactions, though granule formats are gaining traction in tableting operations for pharmaceutical and dietary supplement end uses.
The FDA's GRAS self-affirmation pathway and EFSA's novel food catalog updates shape ingredient approval timelines for tapioca-derived entrants into US and European markets, with organic certification under USDA NOP and EU Regulation 2018/848 adding compliance layers for premium positioning. Thailand's Ministry of Agriculture and Cooperatives enforces pesticide residue limits on exported cassava chips, directly constraining raw material eligibility for maltodextrin bound for regulated jurisdictions. Stakeholders must monitor evolving carbon intensity disclosure rules under the EU CSRD, as Scope 3 agricultural sourcing data becomes material to customer retention in European food manufacturing channels.
Market Dynamics
Southeast Asia's cassava processing clusters are consolidating extraction capacity under vertically integrated supply agreements, tightening feedstock access for North American and European formulators seeking clean-label carbohydrate alternatives.
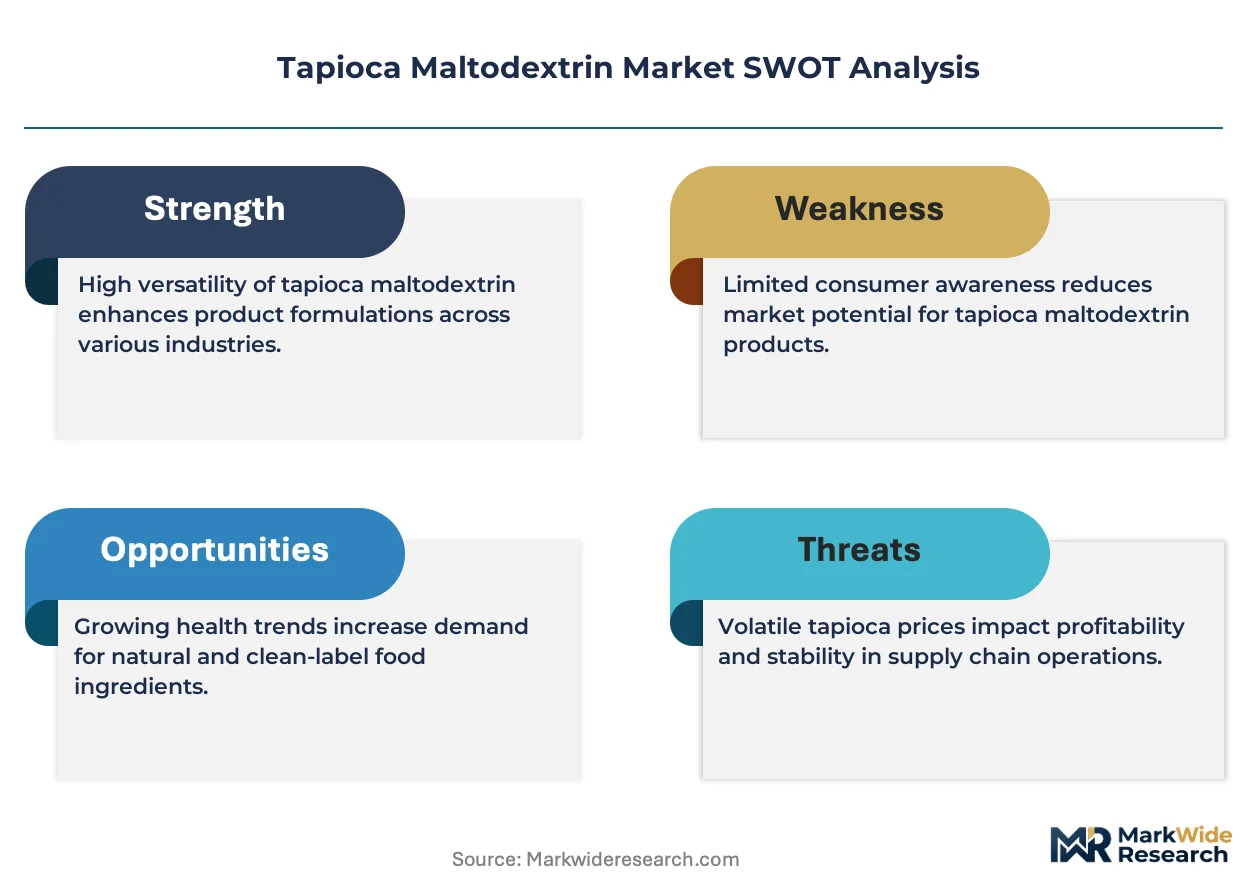
Growth Catalysts
- EU CSRD carbon disclosure mandates:European food manufacturers now require Scope 3 agricultural sourcing data, accelerating demand for traceable tapioca supply chains from Thai and Vietnamese processors with verified carbon accounting.
- Sports nutrition powder formulations:Hydrolyzed tapioca maltodextrin's superior cold-water dispersibility is displacing corn-derived alternatives in pre-workout and recovery drink mixes.
- Thai Ministry of Agriculture export standards:Stringent pesticide residue limits on cassava chips are qualifying Thai-origin maltodextrin for premium organic certification pathways under USDA NOP and EU Regulation 2018/848.
Market Restraints
- Cassava root price volatility:Weather-driven yield fluctuations across Thai and Vietnamese farming regions transmit directly to maltodextrin input costs, compressing processor margins during El Niño cycles.
- Modified starch GRAS documentation:FDA's updated notification requirements impose extended validation timelines for new tapioca-derived entrants, delaying US market access by 18-24 months.
- Enzymatic hydrolysis equipment concentration:Specialized bioreactor systems for controlled dextrose equivalent production cluster with three equipment suppliers, creating capacity bottlenecks during demand surges.
Strategic Opportunities
- Pharmaceutical tableting applications:Granule-format maltodextrin variants targeting direct compression binders remain underpenetrated relative to spray-dried powders, offering margin expansion for processors with milling capabilities.
- Organic infant nutrition channels:Clean-label positioning in follow-on formula and baby food applications commands premium pricing, with EU 2018/848 organic certification unlocking shelf placement in German and French retail.
- Dual carbon goals compliance:China's national carbon intensity targets are redirecting domestic starch capacity toward lower-emission tapioca processing, creating export surplus for Southeast Asian-origin material.
Industry Challenges
- Enzymatic process engineering talent:Shortage of specialists in continuous-flow hydrolysis reactor optimization limits throughput scaling at mid-sized extraction facilities.
- Legacy ERP integration with traceability platforms:Blockchain-enabled farm-to-fork tracking systems require substantial middleware investment for processors running on-premise SAP or Oracle instances.
- Cross-jurisdiction organic certification harmonization:Divergent audit protocols between USDA NOP and EU 2018/848 create duplicate compliance costs for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tapioca Maltodextrin Market |
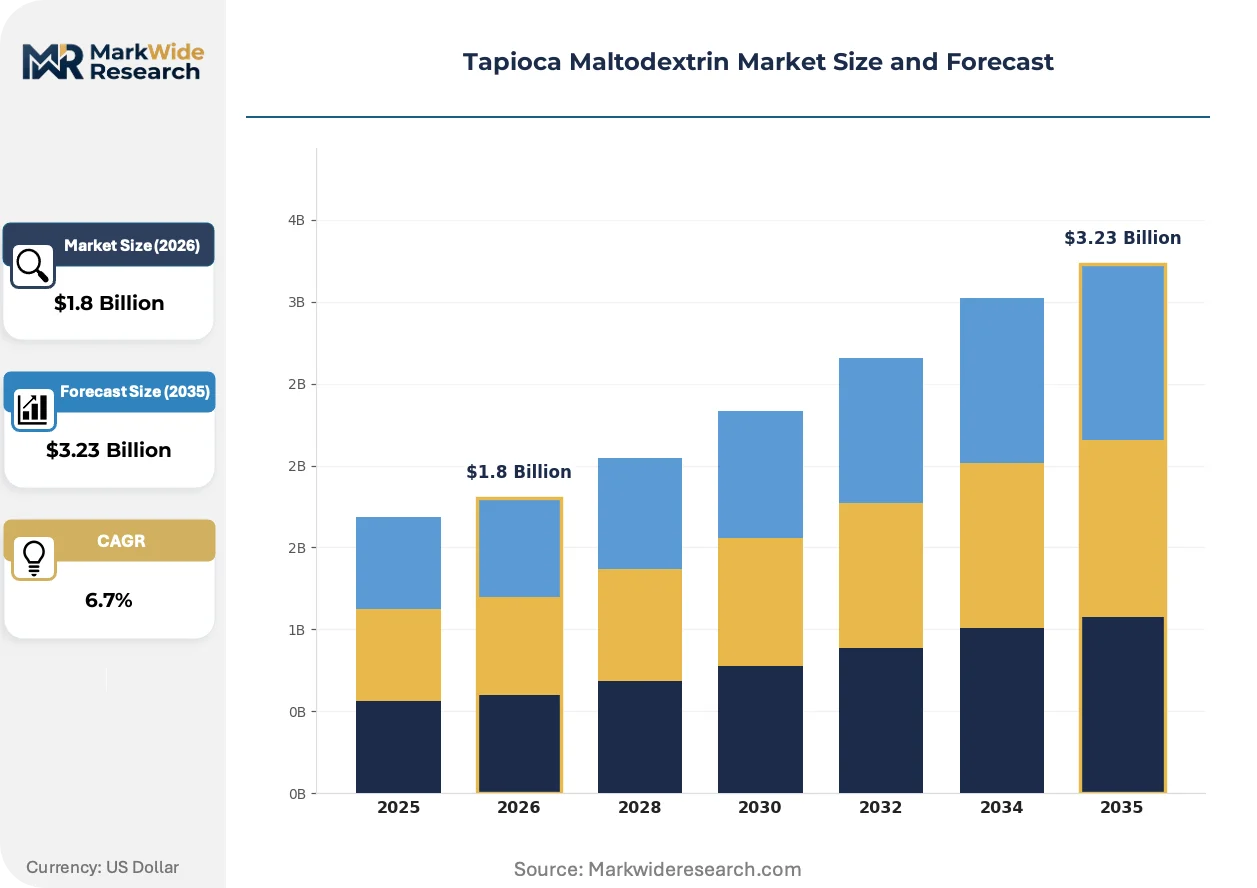
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed, Non-hydrolyzed, Organic, Conventional Application: Food & Beverage, Pharmaceuticals, Sports Nutrition, Animal Feed End User: Manufacturers, Distributors, Retailers, Food Service Form: Powder, Granule, Liquid, Tablet |
| Companies Covered | Ingredion Incorporated, Cargill Incorporated, Archer Daniels Midland Company, Tate & Lyle PLC, Roquette Frères, Grain Processing Corporation, AGRANA Beteiligungs-AG, Tereos, Shafi Gluco Chem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tapioca Maltodextrin Market Evolving Landscape
Enzymatic processing advances and regulatory disclosure requirements are restructuring how tapioca maltodextrin is manufactured, certified, and procured across food, pharmaceutical, and sports nutrition channels.
Continuous-flow enzymatic hydrolysis technology is absorbing batch-reactor market share by enabling precise dextrose equivalent control with 40% lower water consumption. Sports nutrition contract manufacturers in Germany and the Netherlands are adopting these systems to meet EMAS environmental audit standards. The technology is absorbing capital investment that previously flowed toward corn wet-milling retrofits, reshaping equipment vendor priorities.
EFSA's updated novel food catalog interpretations are tightening documentation requirements for modified starches entering European markets, forcing processors to submit comprehensive toxicology dossiers. Thai exporters must now demonstrate enzymatic source documentation and allergen absence protocols to secure positive safety opinions. Pharmaceutical-grade hydrolyzed variants face the steepest compliance burden, with some applicants withdrawing rather than absorbing EFSA consultation costs.
Long-term offtake agreements are replacing spot-market purchasing among North American sports nutrition brands seeking supply security. Ingredient procurement teams now embed sustainability auditors directly within Thai and Vietnamese cassava cooperative assessments. This behavioral shift is most pronounced in California and Colorado, where state-level climate disclosure laws amplify customer pressure for verified Scope 3 data.
Tapioca Maltodextrin Market Segmentation
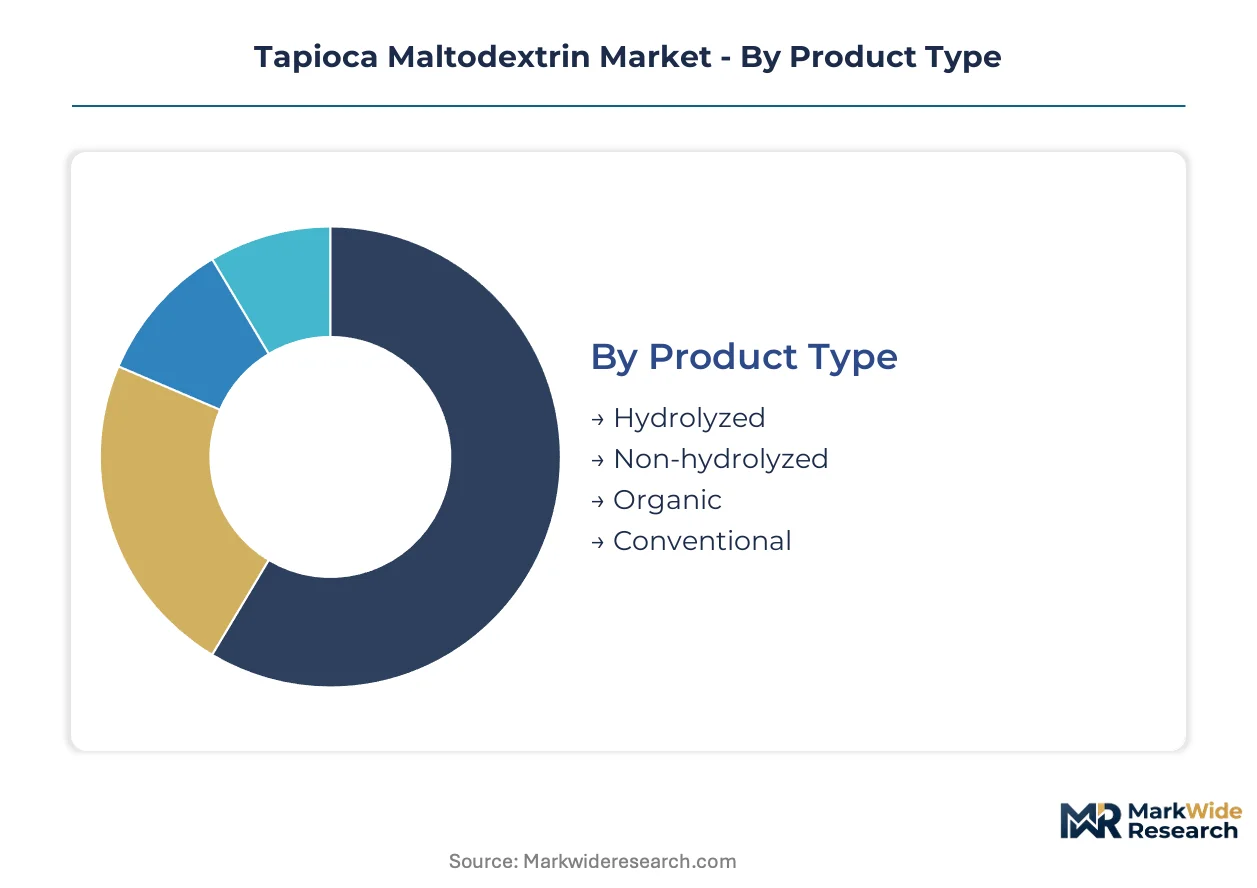
Segmentation in tapioca maltodextrin reveals how enzymatic hydrolysis capabilities, clean-label certification tiers, and form-factor processing constraints partition margin pools across food, pharmaceutical, and sports nutrition channels. Supply chain configuration and regulatory compliance burdens vary sharply by segment, dictating procurement strategies for North American and European formulators.
Product Type:
Thai and Vietnamese extraction clusters concentrate enzymatic hydrolysis capacity, concentrating premium-grade supply under vertically integrated processors with dedicated bioreactor installations.
- Hydrolyzed:Partial enzymatic breakdown yields dextrose equivalents of 3-20, delivering superior cold-water dispersibility that sports nutrition powder manufacturers in Germany and the Netherlands specify for pre-workout formulations. Demand concentrates in North American contract manufacturing facilities serving CrossFit and endurance athlete segments, where rapid dissolution without clumping commands formulation priority.
- Organic:USDA NOP and EU Regulation 2018/848 certification requires pesticide residue compliance enforced by Thailand's Ministry of Agriculture, restricting eligible cassava feedstock to contracted farming cooperatives with documented cultivation protocols. Premium infant nutrition and clean-label beverage applications in California and Colorado absorb output at substantial margin premiums over conventional grades.
- Non-hydrolyzed:Native starch retains original polymer structure for applications requiring viscosity build and gel formation, primarily serving Southeast Asian food manufacturers with lower processing cost tolerance.
- Conventional:Standard-grade material without organic certification fills commodity bulking and carrier applications where price sensitivity dominates supplier selection.
Today's leader: Hydrolyzed. Tomorrow's challenger: Organic.
Application:
End-use demand fragments across regulatory intensity tiers, with pharmaceutical and sports nutrition channels imposing documentation burdens that food and beverage applications escape.
- Sports Nutrition:Pre-workout and recovery drink mixes demand hydrolyzed grades with DE 10-20 for rapid glycemic response and clean flavor profiles; EMAS environmental audit standards in German contract manufacturing facilities favor Thai processors with verified carbon accounting. Protein powder brands embed sustainability auditors directly within Vietnamese cooperative assessments to secure Scope 3 data.
- Pharmaceuticals:Tablet binders and excipient applications require granule-format material with controlled particle size distribution; EFSA's updated novel food catalog interpretations and comprehensive toxicology dossier requirements impose steep compliance costs that filter processor participation.
- Food & Beverage:Spray-dried flavor carriers and instant dry mix bulking agents absorb volume flows with less stringent documentation, though clean-label positioning drives substitution away from corn-derived alternatives.
- Animal Feed:Calorie-dense carbohydrate supplementation for livestock and pet food applications prioritizes cost efficiency over solubility performance.
Sports Nutrition captures the steepest expansion trajectory. Pharmaceuticals defend the highest margin per kilogram.
End User:
Procurement sophistication stratifies by scale and vertical integration depth, with direct manufacturers extracting supply security advantages unavailable to fragmented retail channels.
- Manufacturers:Sports nutrition and infant formula producers negotiate long-term offtake agreements with Thai processors, embedding sustainability auditors within cassava cooperative assessments to satisfy California and Colorado climate disclosure mandates.
- Distributors:Regional ingredient traders manage inventory risk across multiple Southeast Asian sources, absorbing price volatility from weather-driven Thai and Vietnamese yield fluctuations.
- Retailers:Private-label food and beverage brands source through consolidated distribution networks with limited direct farm-to-fork traceability.
- Food Service:Commercial bakery and beverage operators purchase blended carbohydrate systems without specification of maltodextrin origin.
Manufacturers anchor volume commitment. Distributors intermediate price discovery.
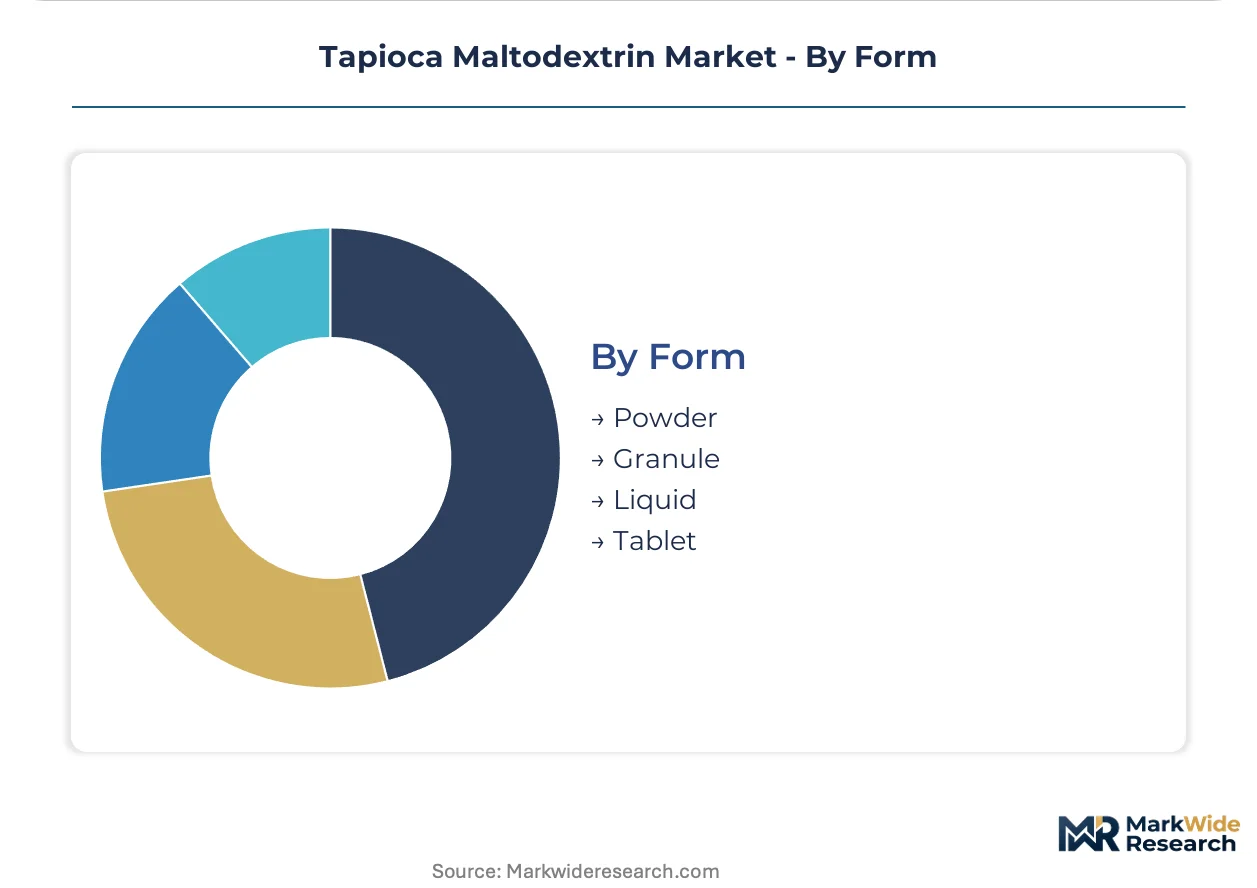
Form:
Processing technology constraints and end-use handling requirements segment form-factor supply, with powder dominance challenged by pharmaceutical granule demand.
- Powder:Spray-dried particles dominate commercial transactions across food, beverage, and sports nutrition channels, with instant dispersibility specifications driving equipment investment at Thai processing facilities.
- Granule:Direct compression tableting for pharmaceutical and dietary supplement applications requires controlled particle size distribution; milling capabilities at mid-sized extraction facilities remain underpenetrated relative to spray-dried capacity.
- Liquid:Pre-hydrolyzed syrup concentrates serve beverage manufacturers seeking to eliminate dry-mix handling steps.
- Tablet:Compressed excipient formats for clinical trial supplies and unit-dose packaging command specialized contract manufacturing relationships.
Powder commands current volume. Granule offers margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's cassava processing clusters anchor global tapioca maltodextrin supply, with enzymatic hydrolysis capacity concentrating under vertically integrated processors serving North American and European formulators.
Thailand
Sports nutrition powder manufacturers in Germany and the Netherlands source hydrolyzed grades with verified carbon accounting to satisfy EMAS environmental audit standards. The Ministry of Agriculture and Cooperatives enforces pesticide residue limits on exported cassava chips, restricting eligible feedstock for organic certification pathways. Processing facilities in Nakhon Ratchasima and Kanchanaburi provinces concentrate spray-dried capacity for instant dispersibility specifications.
United States
California and Colorado-based sports nutrition brands embed sustainability auditors within Southeast Asian cooperative assessments to satisfy state-level climate disclosure mandates. FDA's updated GRAS notification requirements for modified starches impose extended validation timelines for new tapioca-derived entrants. Contract manufacturing facilities in Utah and Texas absorb volume flows for pre-workout and recovery drink formulations.
Vietnam
Backward integration into cassava farming cooperatives reduces price volatility exposure for processors serving European pharmaceutical and infant nutrition channels. The country's national agricultural quality standards align with EU 2018/848 organic certification requirements for premium positioning. Extraction clusters in Dak Lak and Tay Ninh provinces expand hydrolyzed grade output for clean-label beverage applications.
Germany
EMAS-registered contract manufacturers specify Thai-origin material with documented Scope 3 agricultural sourcing data for sports nutrition powder formulations. EFSA's updated novel food catalog interpretations tighten documentation requirements for modified starches entering European markets. Processing and formulation activity concentrates in North Rhine-Westphalia and Bavaria for pharmaceutical tableting and dietary supplement applications.
China
National carbon intensity targets redirect domestic starch capacity toward lower-emission tapioca processing, creating export surplus for Southeast Asian-origin material. SAMR enforcement of food additive safety standards shapes ingredient approval timelines for modified starches. Yangtze River Delta and Pearl River Delta manufacturing hubs absorb granule-format material for pharmaceutical and dietary supplement tableting operations.
Tapioca Maltodextrin Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue organic certification and pharmaceutical-grade specialization. The vendor base stratifies across three capability tiers: multinational ingredient conglomerates with Thai manufacturing footprints, regional Southeast Asian processors with cooperative farming relationships, and European specialists in hydrolyzed grades for pharmaceutical applications. Dominant competitive moves include backward integration into cassava farming cooperatives and long-term offtake agreements with sustainability audit provisions.
Within the multinational tier, Ingredion Incorporated and Cargill Incorporated exemplify scale-driven positioning through Southeast Asian manufacturing infrastructure. Roquette Frères occupies a specialist position emphasizing pharmaceutical and nutritional applications. These three entities anchor the competitive structure by representing distinct strategic archetypes: Thai-based supply security, Vietnamese cooperative integration, and European specialty-grade focus respectively.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Tate & Lyle PLC |
| Roquette Frères |
| Grain Processing Corporation |
| AGRANA Beteiligungs-AG |
| Tereos |
| Shafi Gluco Chem |
| Others |
Value Network & Pricing Analysis
North American sports nutrition contract manufacturers concentrate procurement leverage through long-term offtake agreements, anchoring a contract-based pricing model that insulates premium hydrolyzed grades from commodity spot volatility. Thai and Vietnamese processors respond with tiered pricing structures that separate organic-certified feedstock from conventional cassava origins.
Pricing Analysis
Cassava root input costs transmit directly to maltodextrin pricing through enzymatic hydrolysis energy expenses and bioreactor maintenance overhead. Three-tier pricing structure across premium, standard, and economy levels reflects USDA NOP certification status, dextrose equivalent precision, and volume commitment scale. Pricing pressure stems from El Niño-driven Thai yield fluctuations compressing processor margins. Animal feed manufacturers exhibit highest price sensitivity; pharmaceutical tableting operations absorb lowest.
Supply Chain Analysis
Specialized enzymatic process engineers cluster in Nakhon Ratchasima and Kanchanaburi provinces, constraining throughput scaling at mid-sized Vietnamese facilities. Thailand, Vietnam, and China's Yangtze River Delta anchor global extraction capacity. Supply chains draw from cassava farming cooperatives, alpha-amylase enzyme suppliers, and spray-drying equipment vendors. Single-source vulnerability concentrates in three bioreactor system manufacturers. Distribution runs through regional ingredient traders consolidating Southeast Asian output for North American and European formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU CSRD carbon disclosure mandate compounds market value by forcing traceable agricultural sourcing data into procurement specifications, elevating compliant Thai processors above commodity alternatives.
For Market Incumbents: Extend backward integration into Vietnamese cassava farming cooperatives to secure feedstock priority during El Niño cycles. Expand granule-format milling capabilities at Dak Lak facilities to capture pharmaceutical tableting margins escaping spray-dried powder competition. Defend against emerging organic-certified entrants by accelerating EU 2018/848 dual-certification harmonization. For New Entrants and Emerging Players: Launch via direct-to-manufacturer supply agreements with Colorado and California sports nutrition brands seeking verified Scope 3 data. Target pharmaceutical granule applications as the most penetrable white space, where controlled particle size distribution capabilities remain underdeveloped relative to spray-dried capacity. Pursue EMAS-registered German contract manufacturers as anchor customers. For Investors and Strategic Acquirers: Ingredient conglomerates with Southeast Asian manufacturing footprints are the most active acquirers in this space, consolidating enzymatic hydrolysis capacity under vertically integrated structures. Mid-term viability hinges on carbon accounting infrastructure deployment across Thai cooperative networks. Monitor FDA GRAS notification approval velocity as inflection signal for US market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farming Cooperatives | Cargill's Vietnamese cooperative model reduces price volatility exposure for European pharmaceutical channels. |
| Continuous-Flow Enzymatic Hydrolysis Adoption | German EMAS-registered facilities specify Thai processors with 40% lower water consumption bioreactors. |
| Dual Organic Certification Harmonization | USDA NOP and EU 2018/848 alignment eliminates duplicate audit costs for multi-market suppliers. |
| Granule-Format Milling Capacity Expansion | Pharmaceutical tableting applications command premium margins over spray-dried powder commodity tiers. |
| Blockchain-Enabled Farm-to-Fork Tracking | California climate disclosure laws embed sustainability auditors directly within Thai cooperative assessments. |
Research Methodology
Bottom-up sports nutrition and pharmaceutical formulation modeling reconciled against top-down Thai and Vietnamese extraction capacity tracking forms the analytical core of this study. Primary interviews with enzymatic process engineers, procurement leads at North American contract manufacturers, sustainability auditors, and EMAS-registered facility managers combined with secondary validation from FDA GRAS notifications, EU 2018/848 organic certification registries, Thailand Ministry of Agriculture export records, and customs trade data. Triangulation across these sources calibrated volume and value estimates.
Input-output matrices mapped cassava root availability through hydrolysis reactor utilization to finished maltodextrin output across the projection horizon. Segmentation dimensions modeled include hydrolysis grade tier, organic certification status, end-use application, form factor, and regional production cluster. CAGRs derived from weighted average of capacity expansion announcements, customer procurement pipeline visibility, and regulatory approval trajectory analysis. Forecast inputs incorporated enzymatic equipment supplier order backlogs and EFSA novel food catalog update timing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under El Niño severity deviation and FDA GRAS notification processing delays. Forecasts reflect documented assumptions regarding Thai agricultural yield stability and EU carbon disclosure enforcement timelines. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
White Sugar Market
Sweeteners
D Psicose Market
Sweeteners
Sugar Market
Sweeteners
Egypt Food Sweetener Market
Sweeteners
Argentina Food Sweetener Market
Sweeteners
Stevia Market
Sweeteners
Digestion Resistant Maltodextrin Market
Sweeteners
Asia-Pacific Plant-Derived and Synthetic Sugar Market
Sweeteners
Sucrose Acetate Isobutyrate Market
Sweeteners
Italy Food Sweetener Market
Sweeteners
Asia-Pacific Low-Calorie Sweeteners Market
Sweeteners
Sanding Sugar Market
Sweeteners
Rare Sugar Market
Sweeteners
Aspartame Market
Sweeteners
Dry Molasses Market
Sweeteners
Clarified Rice Syrup Market