
 Low Fat Cream Cheese Nutrition Market | 2026-2036
Low Fat Cream Cheese Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Cream Cheese Nutrition Market Analytics
Buyer concentration in the food service channel is shifting as regional bakery chains and cafe networks consolidate procurement decisions away from fragmented independent operators. The Kraft Heinz Company leverages its refrigerated distribution infrastructure to sustain national retail coverage. Arla Foods amba anchors its position through European sourcing protocols that compete on clean-label credentials. Lactalis Group specializes in private-label manufacturing scale, occupying cost-sensitive shelf space across multiple retail banners.
Low fat cream cheese nutrition denotes dairy-based or analog spread products formulated with reduced butterfat content, typically manufactured through centrifugal separation of milk fat followed by standardization to achieve protein-to-fat ratios between 2:1 and 4:1 for functional spreadability. The category serves commercial food manufacturing, retail table spreads, and ingredient applications requiring controlled fat contribution with preserved emulsion stability. Spreadable formats dominate household purchase frequency due to convenience positioning, while organic variants capture premium margin pools as certification costs limit supplier participation. Food service distribution channels exhibit the fastest structural expansion as bakeries and QSR chains reformulate menus around reduced-fat dairy ingredients.
The FDA governs standard of identity requirements for reduced-fat cream cheese through its Code of Federal Regulations, while the USDA administers organic certification pathways that constrain ingredient sourcing flexibility. State-level dairy marketing orders in Wisconsin and California further shape raw milk pricing structures that cascade into formulation economics. Stakeholders must monitor evolving front-of-pack labeling mandates and plant-based identity standards that threaten to bifurcate regulatory compliance pathways for traditional and alternative formulations.
Market Dynamics
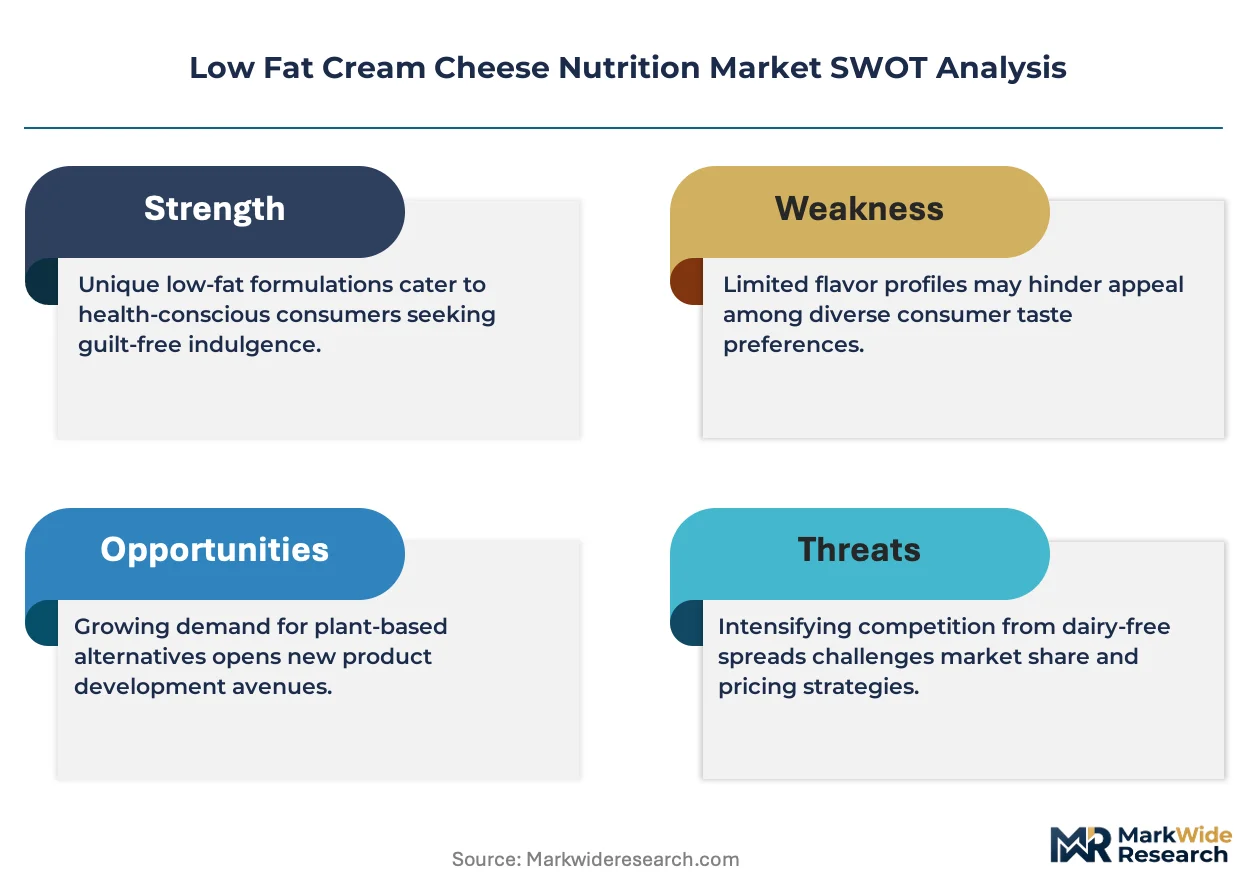
Clean-label reformulation and FDA nutrition labeling tightening are compressing formulation flexibility while concentrating procurement authority among consolidated food service buyers. This structural pressure is reshaping supplier relationships across the dairy spread category.
Growth Catalysts
- Menu Reformulation Mandates:National bakery chains and QSR networks are standardizing reduced-fat dairy specifications across franchise locations, creating predictable bulk demand volumes for certified suppliers.
- Organic Certification Pathways:USDA organic protocols are constraining competitor entry while rewarding incumbent investment in certified milk sourcing and segregated processing infrastructure.
- Centrifugal Separation Advances:Precision butterfat standardization technology is enabling protein-to-fat ratio control between 2:1 and 4:1, preserving functional spreadability at reduced fat levels.
Market Restraints
- Raw Milk Price Volatility:Wisconsin and California dairy marketing orders cascade pricing instability directly into formulation economics, compressing margin predictability for standardized products.
- Plant-Based Substitution Acceleration:Almond and oat-based spread analogs are capturing shelf space in premium retail segments, threatening traditional cream cheese velocity in health-positioned channels.
- Clean-Label Ingredient Scarcity:Natural stabilizer alternatives to modified food starch face supply concentration among limited qualified suppliers, constraining rapid formulation pivots.
Strategic Opportunities
- Private-Label Manufacturing Scale:Retail banner consolidation is creating dedicated production contract opportunities for facilities capable of allergen-segregated, multi-SKU runs.
- Food Service Distribution Integration:Direct-to-bakery ingredient supply bypasses traditional retail brokerage, capturing margin through refrigerated logistics specialization.
- Front-of-Pack Labeling Tailwinds:Evolving FDA disclosure mandates favor suppliers with pre-invested nutritional transparency infrastructure and reformulated low-sodium variants.
Industry Challenges
- Emulsion Stability Expertise Gap:Dairy technologists capable of maintaining protein matrix integrity at reduced fat concentrations command premium compensation, constraining R&D throughput.
- Certification Timeline Compression:Organic and clean-label audits require 12-18 month validation cycles, delaying new product commercialization against faster-moving plant-based competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Cream Cheese Nutrition Market |
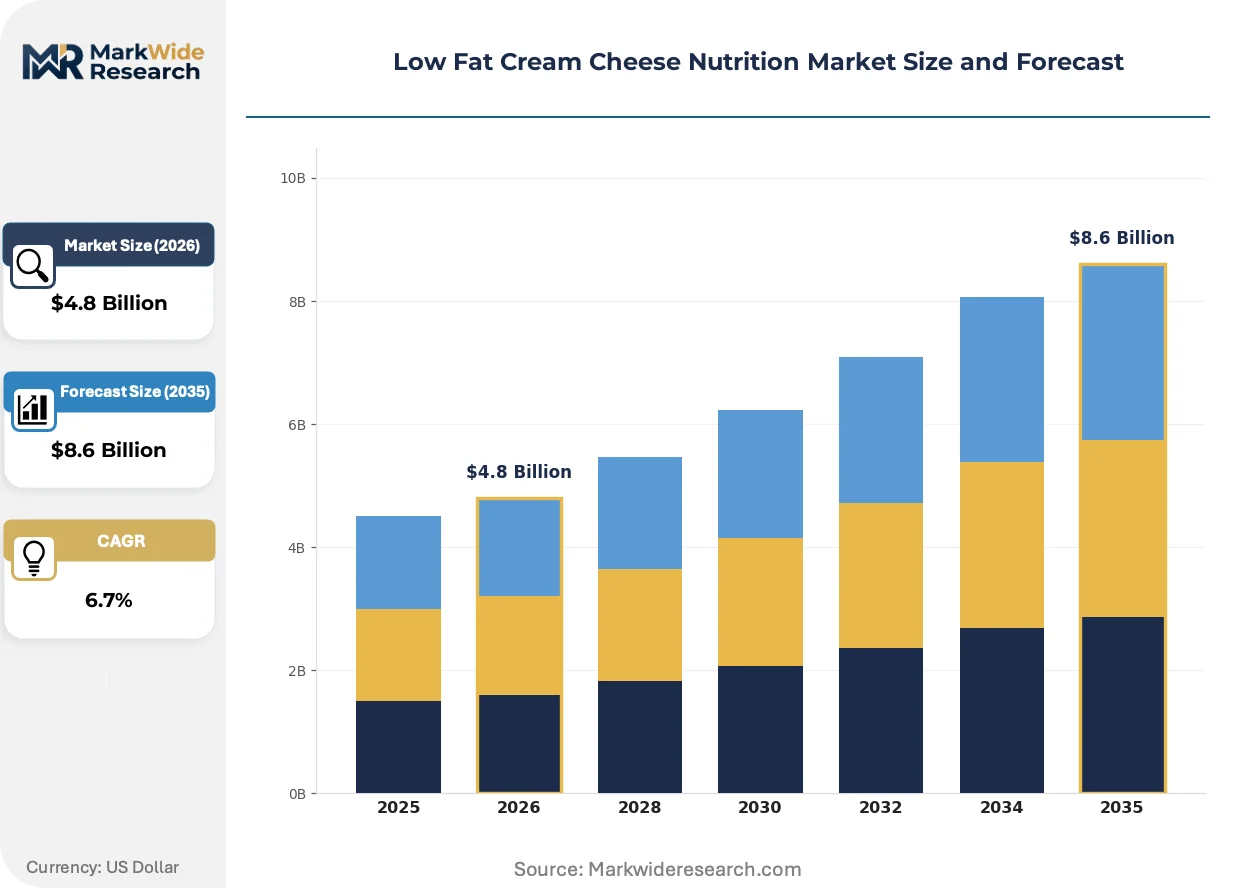
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spreadable, Block, Whipped, Organic Packaging Type: Tubs, Sachets, Pouches, Jars Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Food Service Customer Type: Households, Restaurants, Cafes, Bakeries |
| Companies Covered | The Kraft Heinz Company, Arla Foods amba, Lactalis Group, Kite Hill, Miyoko’s Creamery, Daiya Foods Inc., Savencia SA, Fonterra Co-operative Group Limited, Associated Milk Producers Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Cream Cheese Nutrition Market Evolving Landscape
Protein matrix engineering and regulatory transparency mandates are converging to reshape competitive positioning across reduced-fat dairy spreads. Suppliers must now balance functional performance with ingredient minimalism.
Membrane filtration technology is unifying protein concentration and fat separation into continuous processing lines, eliminating batch variability. Regional dairy cooperatives in Wisconsin and California are retrofitting plants with ceramic microfiltration systems to achieve precise standardization. This convergence is compressing the cost gap between commodity and premium low-fat formulations.
FDA updated nutrition labeling requirements for reduced-fat dairy products are mandating revised serving-size disclosures and added sugar callouts. Reformulation teams must recalculate nutrient density claims while maintaining sensory benchmarks. Bakeries and cafe chains sourcing bulk ingredients are demanding pre-certified nutritional documentation to accelerate their own compliance timelines.
Consolidated procurement by regional bakery networks is displacing fragmented independent operator purchasing, concentrating volume decisions among fewer buyers. Multi-unit food service contracts now specify multi-year supply agreements with penalty clauses for formulation changes. This concentration is most visible in the United States, where private-label expansion and clean-label positioning drive category velocity through centralized distribution.
Low Fat Cream Cheese Nutrition Market Segmentation
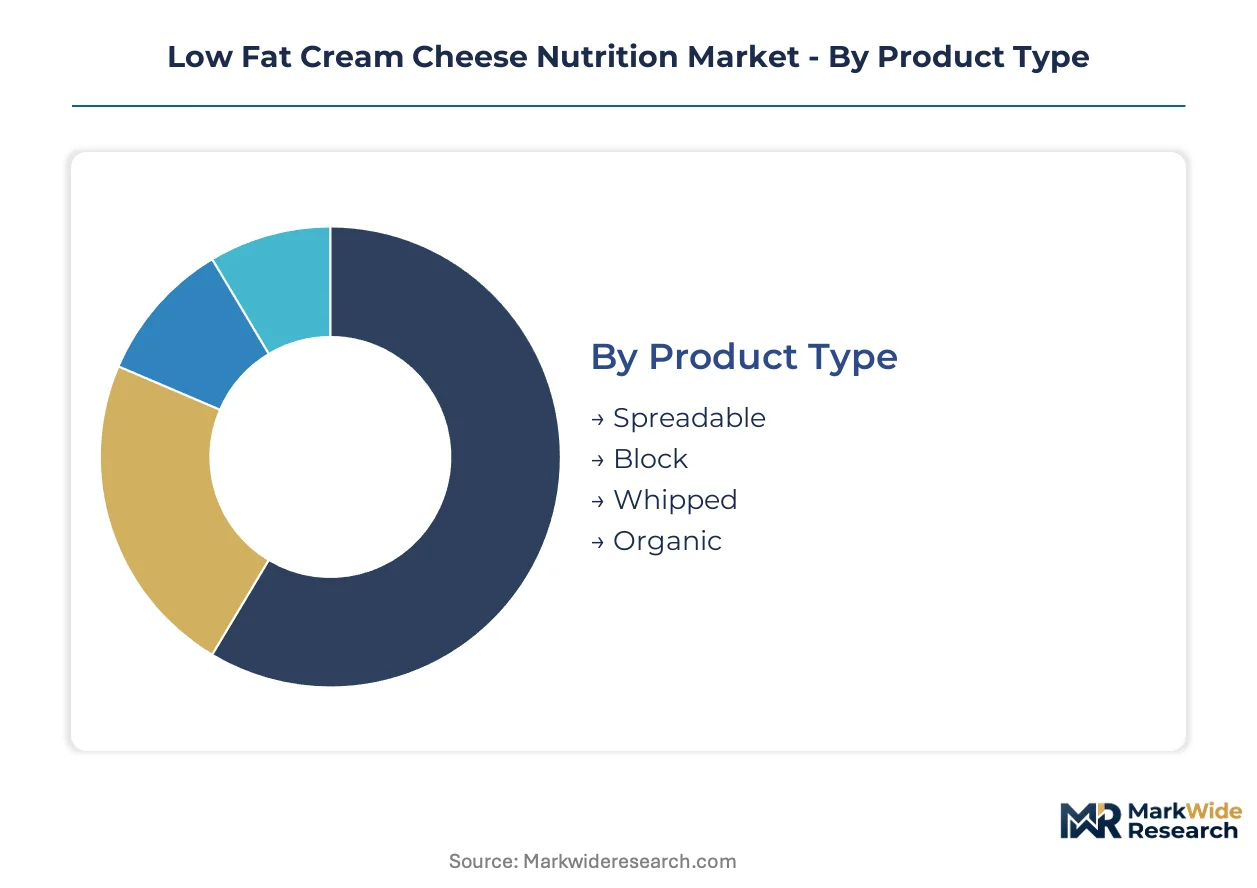
Low fat cream cheese nutrition markets fragment across functional formats, logistical requirements, and procurement behaviors. Each segmentation dimension reveals distinct margin structures and buyer concentration patterns that reshape supplier priorities.
Product Type:
Buyers differentiate by application flexibility and shelf-life requirements rather than price sensitivity alone.
- Spreadable:Formulations achieve protein-to-fat ratios between 2:1 and 4:1 through centrifugal standardization, preserving emulsion stability for direct table use. Households in the United States drive repeat purchase frequency through convenience positioning, though refrigerated distribution costs constrain rural penetration.
- Organic:USDA certification mandates segregated processing infrastructure and certified milk sourcing, limiting supplier participation to incumbents with 12-18 month audit timelines. Premium margin pools attract investment despite certification bottlenecks that delay commercialization against plant-based alternatives.
- Block:Compressed formats target ingredient applications in bakery and food manufacturing where portion control and extended shelf stability matter.
- Whipped:Aerated textures command specialty positioning for dessert applications and premium bagel shop channels.
Spreadable leads volumes today; Organic is gaining share fastest.
Packaging Type:
Packaging selection tracks channel logistics and portion economics more than consumer preference.
- Tubs:Refrigerated retail distribution dominates household purchase occasions through resealable convenience and established cold-chain infrastructure.
- Sachets:Single-serve portions align with food service portion control and QSR condiment programs.
- Pouches:Flexible formats reduce shipping cube and refrigeration load for bakery bulk procurement.
- Jars:Premium positioning in specialty retail channels supports clean-label visibility and gift-market applications.
Tubs anchor current volume; Pouches show steepest expansion trajectory in food service channels.
Distribution Channel:
Channel selection determines margin capture versus volume scale tradeoffs for suppliers.
- Food Service:Direct-to-bakery and QSR supply bypasses retail brokerage, capturing margin through refrigerated logistics specialization while multi-year contracts with penalty clauses lock in formulation stability.
- Supermarkets:Private-label expansion and clean-label positioning drive category velocity through centralized distribution, with retail banner consolidation creating dedicated production contract opportunities.
- Online Retail:Cold-chain fulfillment complexity limits participation to suppliers with national refrigerated warehouse networks.
- Specialty Stores:Curated assortments support premium organic and artisanal variants with higher per-unit margins.
Supermarkets maintain volume leadership; Food Service channels are expanding most quickly.
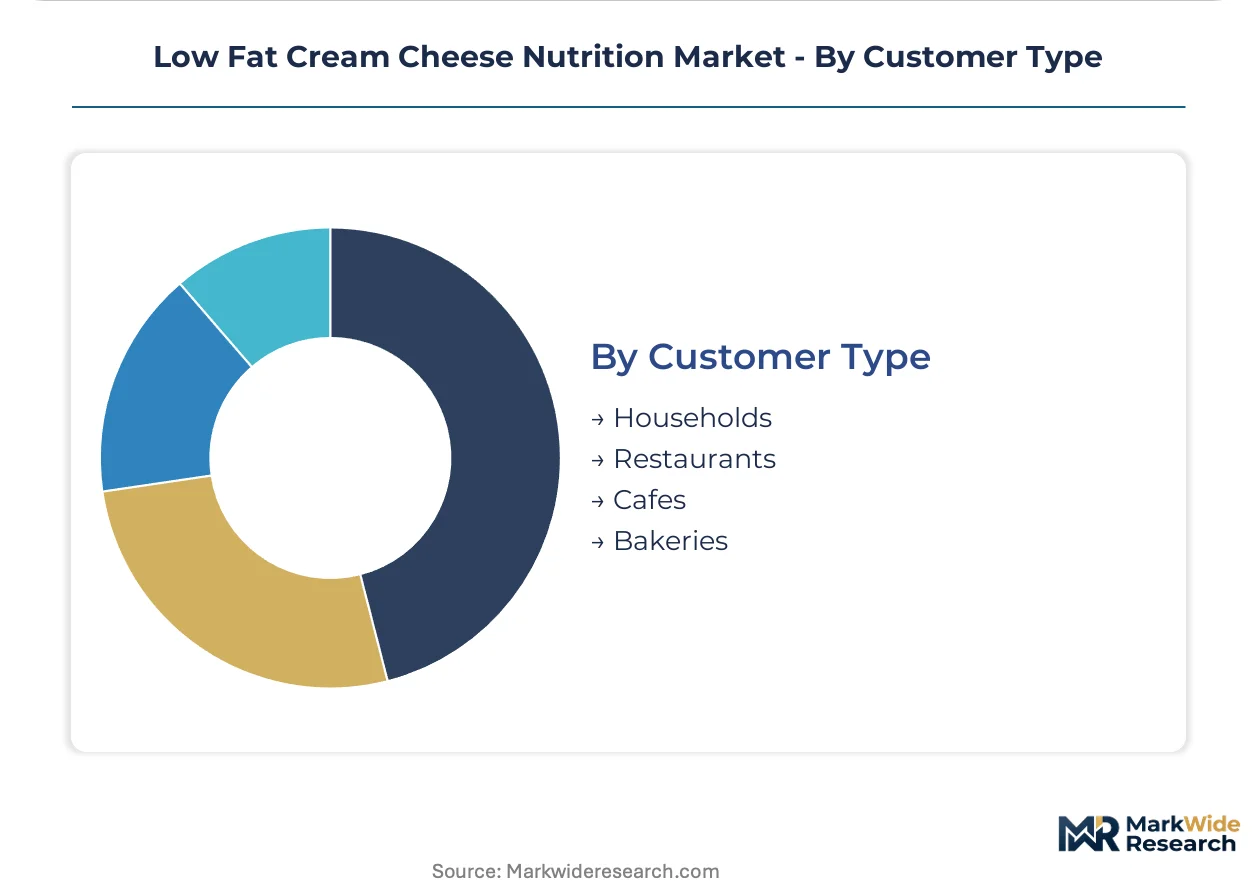
Customer Type:
Procurement scale and specification rigor separate customer tiers more than end-use application.
- Bakeries:Regional chain consolidation concentrates volume decisions among fewer buyers, with standardized reduced-fat dairy specifications across franchise locations creating predictable bulk demand for certified suppliers.
- Households:Fragmented purchase patterns favor spreadable formats through retail convenience, with frequency driven by health-conscious menu reformulation at home.
- Restaurants:Menu reformulation mandates vary by segment, with fast-casual chains adopting reduced-fat ingredients faster than full-service operators.
- Cafes:Bagel-forward concepts and specialty coffee chains drive premium positioning for whipped and organic variants.
Households dominate current consumption; Bakeries are climbing the fastest as procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Private-label expansion in the United States outpaces branded velocity in Germany, while clean-label positioning accelerates faster in Nordic markets than in Southern Europe. Regulatory divergence between FDA nutrition labeling mandates and EFSA dairy identity standards is fragmenting formulation compliance pathways. Food service procurement consolidation concentrates volume decisions among fewer buyers in mature dairy economies.
United States
Bakery chain consolidation and QSR menu reformulation drive bulk procurement standardization across franchise networks. The FDA's updated nutrition labeling requirements for reduced-fat dairy products mandate revised serving-size disclosures and added sugar callouts. Wisconsin dairy cooperatives retrofit plants with ceramic microfiltration systems to achieve precise butterfat standardization for protein-to-fat ratio control.
Germany
Retail banner consolidation creates dedicated production contract opportunities for allergen-segregated, multi-SKU manufacturing facilities. EFSA dairy identity standards govern reduced-fat spread classifications while the EU Green Deal pressures carbon footprint disclosure across supply chains. Bavarian dairy processors leverage membrane filtration technology to unify protein concentration and fat separation into continuous processing lines.
France
Artisan bakery networks and specialty cheese retail channels sustain premium positioning for organic and whipped variants. ANSM and DGCCRF enforce dairy product labeling compliance while the country's national agricultural regulator administers organic certification pathways. The Normandy dairy cluster maintains segregated processing infrastructure for certified milk sourcing and export-grade low-fat formulation.
United Kingdom
Supermarket private-label expansion concentrates procurement authority among Tesco, Sainsbury's, and Aldi UK banners. The Food Standards Agency coordinates with Trading Standards on reduced-fat dairy identity enforcement post-Brexit regulatory divergence. The West Country dairy belt supplies certified organic milk to segregated processing facilities serving London-centric food service distribution networks.
Japan
Convenience store chains and bakery cafe networks standardize reduced-fat dairy specifications across metropolitan franchise locations. METI administers food labeling standards while the national dairy regulator enforces quality specifications for processed cheese spreads. The Hokkaido dairy basin anchors domestic milk supply for low-fat cream cheese manufacturing serving Tokyo-Osaka food service corridors.
Low Fat Cream Cheese Nutrition Market Competitive Landscape
North American producers anchor one tier; European specialists hold differentiated positions through clean-label credentials and organic certification infrastructure. The vendor base fragments across refrigerated distribution scale players, private-label manufacturers, and plant-based analog entrants. Three strategic archetypes dominate: legacy dairy conglomerates with national retail coverage, cooperative processors with regional milk supply control, and alternative formulation startups capturing premium shelf space. Competitive moves concentrate on multi-year food service contracting with penalty clauses and backward integration into certified milk sourcing.
Within the legacy conglomerate tier, The Kraft Heinz Company and Lactalis Group exemplify scale-driven positioning through refrigerated distribution infrastructure and private-label manufacturing capacity respectively. Arla Foods amba occupies a cooperative archetype anchored by European sourcing protocols and segregated organic processing infrastructure. Among alternative formulation specialists, Kite Hill and Miyoko's Creamery represent plant-based and cultured dairy approaches to reduced-fat spread positioning. Daiya Foods Inc. sits within the allergen-free manufacturing segment serving retail banners with dedicated production lines.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| Arla Foods amba |
| Lactalis Group |
| Kite Hill |
| Miyoko's Creamery |
| Daiya Foods Inc. |
| Savencia SA |
| Fonterra Co-operative Group Limited |
| Associated Milk Producers Inc |
| Others |
Value Network & Pricing Analysis
Dairy technologists capable of maintaining protein matrix integrity at reduced fat concentrations cluster in Wisconsin and California, where labor-cost differentials between certified organic processing specialists and commodity production workers drive spreads between premium USDA-certified tiers and private-label economy positioning.
Pricing Analysis
Capacity additions in Wisconsin and California are reshaping price floors for standardized low-fat cream cheese formulations. Three-tier pricing structure across premium organic, standard clean-label, and economy private-label levels stratifies the category, with certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from plant-based spread analogs capturing premium shelf space, compressing margins for traditional dairy in health-positioned channels. Food service bakery chains exhibit lowest price sensitivity due to multi-year contract lock-ins, while independent retailers face highest sensitivity to raw milk price volatility passed through dairy marketing orders.
Supply Chain Analysis
Workforce availability for certified dairy processing specialists concentrates in Wisconsin, California, and Normandy, constraining rapid capacity expansion for organic low-fat cream cheese production. Raw milk supply draws from Wisconsin and California dairy cooperatives, with natural stabilizer alternatives to modified food starch sourcing from limited qualified suppliers. Single-source vulnerability in certified organic milk procurement creates structural risk for suppliers dependent on segregated processing infrastructure. Distribution runs through refrigerated logistics networks serving national retail banners and direct-to-bakery food service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Low Fat Cream Cheese Nutrition Market functions as a regulatory compounder, with FDA updated nutrition labeling requirements for reduced-fat dairy products tightening formulation standards and accelerating demand for pre-certified nutritional documentation.
For Market Incumbents: Lock in multi-year food service contracts with penalty clauses for formulation changes to defend against plant-based substitution acceleration. Deepen backward integration into certified organic milk sourcing to secure segregated processing infrastructure and constrain competitor entry through 12-18 month USDA audit timelines.
For New Entrants and Emerging Players: Capture white-space in regional bakery chain procurement consolidation by offering direct-to-bakery refrigerated logistics specialization bypassing traditional retail brokerage. Target allergen-segregated private-label manufacturing contracts with retail banner consolidation creating dedicated production opportunities for multi-SKU facilities.
For Investors and Strategic Acquirers: Food service distribution platforms are the most active acquirer in this space, seeking refrigerated logistics specialization to capture margin through direct bakery supply. Long-term viability hinges on organic certification infrastructure and clean-label reformulation capabilities. Watch for FDA front-of-pack labeling mandate acceleration as inflection indicator for nutritional transparency infrastructure demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Milk Sourcing | USDA organic protocols constrain competitor entry while securing segregated processing infrastructure. |
| Food Service Distribution Integration | Direct-to-bakery supply bypasses retail brokerage and captures margin through refrigerated logistics specialization. |
| Clean-Label Reformulation Investment | Natural stabilizer alternatives to modified food starch meet FDA tightening standards and premium positioning. |
| Membrane Filtration Technology Deployment | Ceramic microfiltration systems in Wisconsin and California achieve precise protein-to-fat ratio control. |
| Multi-Year Contract Structuring | Penalty clauses for formulation changes lock in volume with consolidating regional bakery chains and QSR networks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dairy processing technologists, food service procurement directors at regional bakery chains, retail category buyers, and regulatory affairs specialists at reduced-fat dairy manufacturers with secondary validation from FDA Code of Federal Regulations filings, USDA organic certification databases, Wisconsin and California dairy marketing order price reports, and refrigerated distribution trade data. Bottom-up facility capacity assessments and top-down category consumption estimates were triangulated to anchor volume figures.
Segment-weighting approaches modeled product type, packaging format, distribution channel, and customer procurement behavior dimensions across the projection horizon. CAGRs were derived from rolling average growth rate analysis applied to standardized protein-to-fat ratio formulation adoption curves and food service channel penetration trajectories. Forecast inputs incorporated membrane filtration technology deployment timelines and organic certification audit cycle durations.
Raw milk price volatility, plant-based substitution acceleration, and FDA labeling mandate timing are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about dairy marketing order stability and clean-label ingredient supply concentration. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Lactose Free Dairy Products Market
Dairy Products
Butter Concentrate Market
Dairy Products
Skim Milk Powder Market
Dairy Products
Asia-Pacific Milk Protein Market
Dairy Products
Dairy Protein Market
Dairy Products
Germany Dairy Market
Dairy Products
North America Casein Market
Dairy Products
Cheese Shreds Market
Dairy Products
Europe Cow Milk Minerals Market
Dairy Products
Paneer Market
Dairy Products
Europe Cheese Market
Dairy Products
Recombined Milk Products Market
Dairy Products
Yogurt and Probiotic Drink Market
Dairy Products
United States Casein and Caseinate Market
Dairy Products
Organic Cheese Powder Market
Dairy Products
White Cheese Market