
 Fermented Sweeteners Market | 2026-2036
Fermented Sweeteners Market Size, Share, and Industry Trends Forecast 2026-2036
Fermented Sweeteners Market Foresight
Precision fermentation is fragmenting the traditional sweetener supply chain by enabling microbial production of rare sugars without agricultural feedstock dependency. Cargill leverages its existing corn processing infrastructure to integrate fermentation-derived erythritol and allulose into bulk ingredient portfolios. Jungbunzlauer Suisse AG anchors European supply through citric acid and xylitol fermentation expertise that extends into sweetener co-production. Ajinomoto Co., Inc. dominates amino acid fermentation technology that it adapts for high-intensity sweetener manufacturing.
Fermented sweeteners comprise polyols, rare sugars, and amino acid-derived compounds produced via controlled microbial cultivation in bioreactors, typically achieving purity grades exceeding 99.5% through downstream chromatographic separation. These ingredients function as low-glycemic alternatives to sucrose in formulations targeting diabetic and weight-management consumers. The application dimension shows beverages commanding the largest volume share due to reformulation mandates from major soda and sports drink producers, while bakery products represent the fastest-expanding segment as clean-label bread and pastry brands replace high-fructose corn syrup. Product type segmentation reveals agave syrup maintaining premium positioning in organic retail channels, whereas coconut sugar competes on mineral-content differentiation in health stores.
The FDA governs GRAS self-affirmation pathways for novel fermented sweeteners, while EFSA enforces novel food authorization requirements that extend market access timelines for European entrants. USDA organic certification and EU organic regulation shape premium pricing eligibility for fermentation inputs derived from certified agricultural feedstocks. Stakeholders must monitor emerging genome-editing regulatory classifications, as CRISPR-optimized yeast strains face divergent oversight frameworks across jurisdictions that will determine competitive manufacturing costs.
Market Dynamics
Precision fermentation infrastructure is consolidating around industrial biotech clusters as beverage reformulation mandates force rapid supplier qualification timelines. Clean-label regulatory pressure from FDA and EFSA is compressing the window for novel sweetener commercialization.
Growth Catalysts
- GRAS Self-Affirmation Pathway:FDA's streamlined safety review process accelerates time-to-market for novel polyols and rare sugars, enabling faster portfolio expansion by functional beverage formulators.
- Beverage Reformulation Mandates:Major carbonated drink producers are systematically replacing high-fructose corn syrup and artificial sweeteners with fermentation-derived alternatives to meet retailer clean-label requirements.
- Bioreactor Scale-Up:Stainless steel fermentation vessel capacity in industrial biotech corridors is expanding to support multi-thousand-liter production runs of erythritol and allulose.
Market Restraints
- Feedstock Cost Volatility:Organic corn and sugarcane substrate prices fluctuate with climate-induced harvest variability, squeezing margin structures for fermentation-based sweetener producers.
- European Authorization Timelines:EFSA novel food assessments extend commercialization cycles by 18-36 months compared to US pathways, fragmenting go-to-market synchronization.
- Enzymatic Conversion Limits:Current cellulase and amylase efficiencies cap yield rates for certain rare sugars, constraining unit economics against mature extraction methods.
Strategic Opportunities
- India Functional Beverage Entry:FSSAI regulatory harmonization with Codex standards is opening formulation partnerships for fermented sweeteners in sports and wellness drinks.
- Bakery Segment Penetration:Clean-label bread and pastry brands represent underexploited volume potential as technical hurdles around moisture retention and Maillard browning resolve.
- CRISPR Strain Optimization:Genome-edited yeast platforms promise 40-60% yield improvements for xylitol and erythritol, pending regulatory clarity on edited organism classifications.
Industry Challenges
- Downstream Chromatography Bottleneck:Purification equipment lead times for achieving 99.5% purity grades now stretch 14-18 months, constraining production ramp schedules.
- Cross-Contamination Protocols:Facilities producing both allergen-containing and allergen-free sweeteners face complex sanitation validation requirements under FDA food safety modernization mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fermented Sweeteners Market |
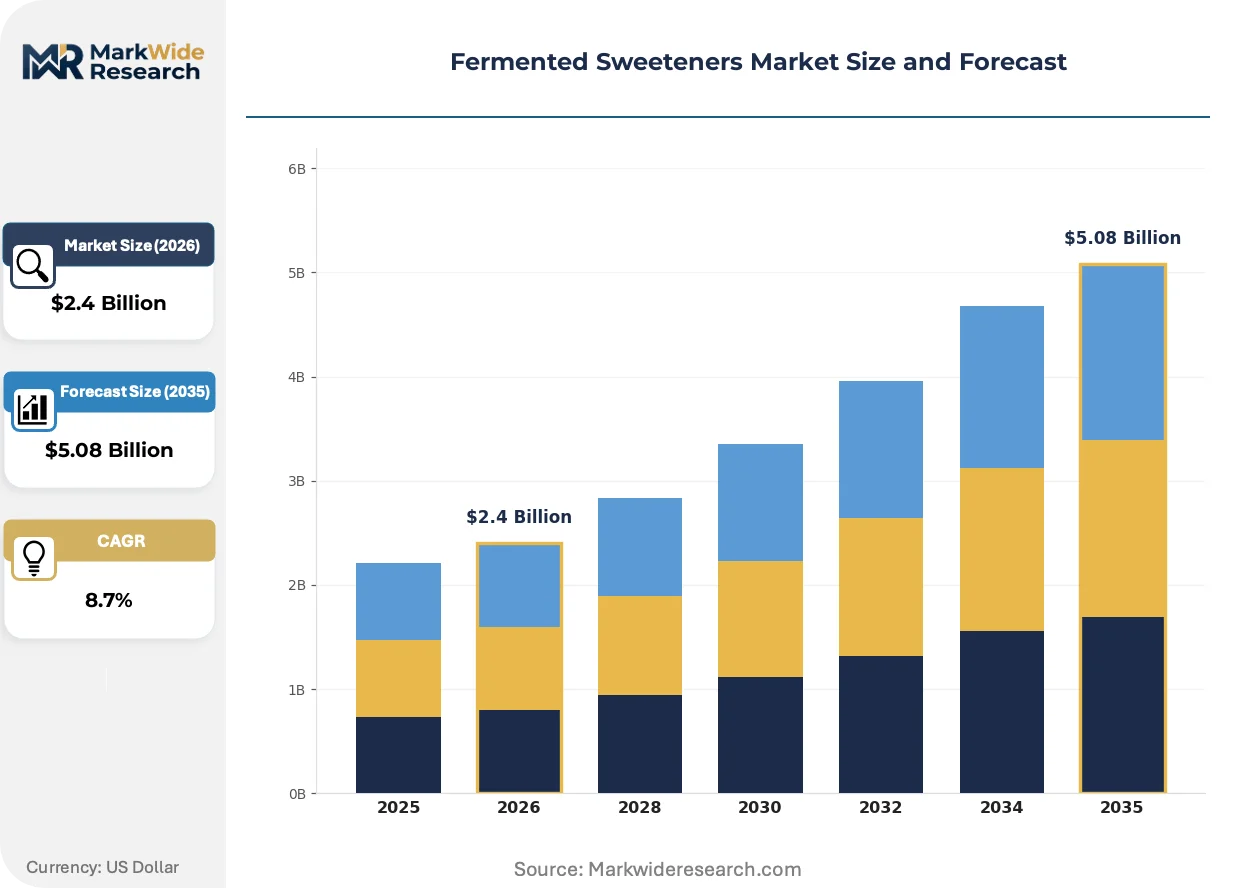
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Honey, Agave Syrup, Maple Syrup, Coconut Sugar Application: Beverages, Bakery Products, Dairy, Snacks End User: Food Manufacturers, Beverage Companies, Retailers, Health Stores Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Cargill, Archer Daniels Midland Company, Ingredion, Tereos, Ajinomoto Co., Inc., Jungbunzlauer Suisse AG, Gulshan Polyols Ltd., Hylen Co., Ltd., Evolva, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fermented Sweeteners Market Shifts & Advancements
Bioprocess engineering advances are collapsing the traditional separation between agricultural commodity extraction and microbial production. Three interconnected developments are restructuring competitive positioning.
Continuous fermentation systems with real-time metabolite monitoring are hybridizing batch and fed-batch operations into hybrid configurations that cut cycle times by half. Contract manufacturers in Denmark and Singapore are deploying these systems for allulose production at 50,000-liter scale. The technology is hybridizing capital efficiency curves, enabling mid-tier suppliers to challenge integrated majors on unit costs.
EFSA's 2023 updated guidance on novel food safety assessments now requires extended subchronic toxicity datasets for fermentation-derived ingredients without established consumption history. European entrants must budget additional 12-18 months for study completion before submission. Bakery applications face particular scrutiny given higher per-capita exposure estimates in reformulated bread categories.
Direct procurement relationships between beverage brands and fermentation facilities are displacing traditional ingredient distributor intermediaries. Large CPG buyers now require dedicated bioreactor capacity and transparent strain lineage documentation. This pattern concentrates most visibly in the United States, where functional drink startups negotiate offtake agreements before facility construction completion.
Fermented Sweeteners Market Segmentation
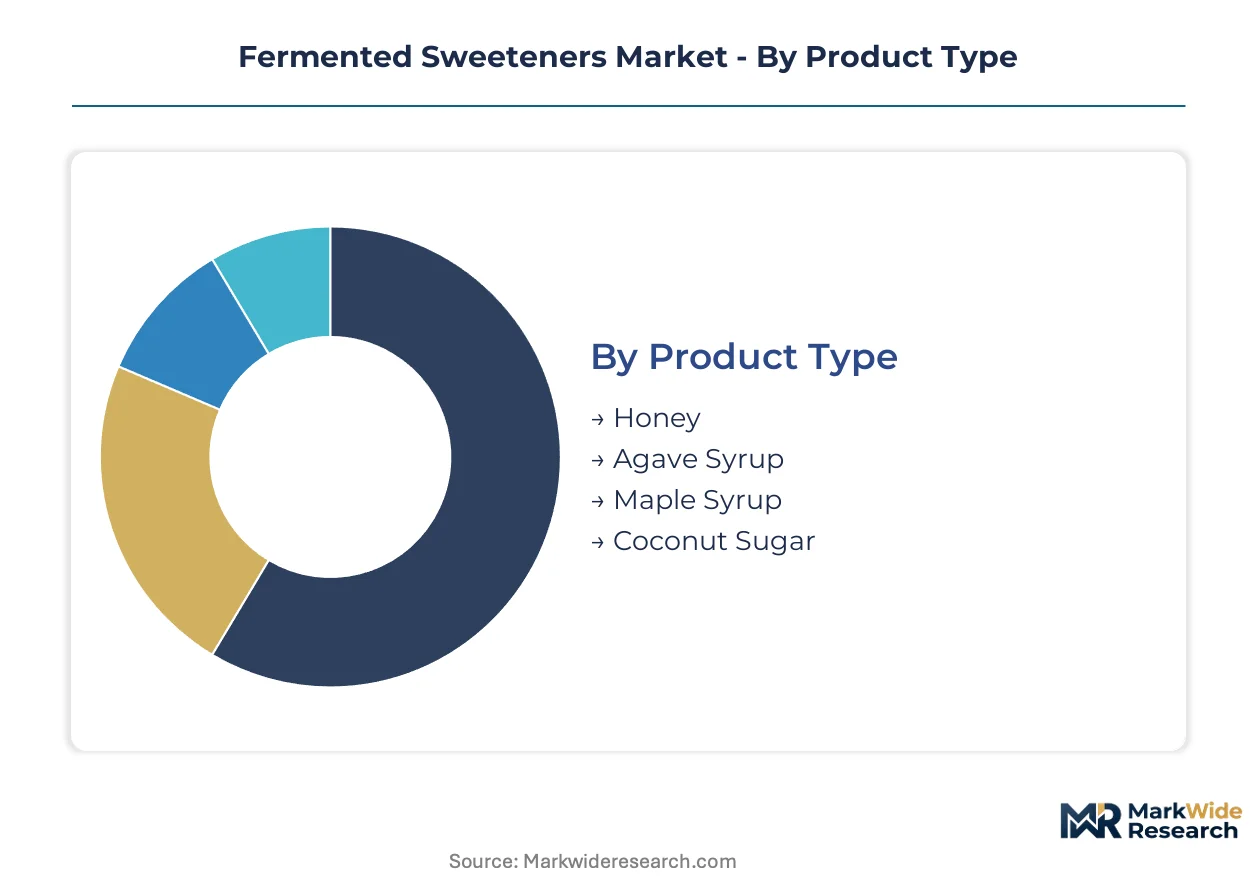
Segmentation in fermented sweeteners reveals how production methods, formulation requirements, and channel access create distinct competitive arenas. Each dimension carries different margin structures and regulatory burdens that reshape supplier strategies across the value chain.
Product Type:
Mature extraction-based sweeteners coexist with emerging fermentation-derived alternatives across the four product categories.
- Honey:Enzymatically processed and fermentation-enhanced variants achieve standardized moisture content and HMF levels for industrial baking. North American contract manufacturers are qualifying enzymatically treated honey for clean-label bread formulations where Maillard browning control matters.
- Agave Syrup:Fermentation-derived inulin conversion creates low-glycemic agave formulations with 90% fructose concentration. Premium organic retail channels in the United States concentrate demand as beverage startups reformulate around transparent supply chains.
- Maple Syrup:Precision fermentation replicates maple flavor compounds without sap harvesting constraints. Quebec and Vermont producers face emerging competition from bioreactor-derived alternatives.
- Coconut Sugar:Mineral-content positioning differentiates this segment in health stores, though fermentation-based rare sugars now compete on glycemic index claims.
Agave syrup handles the majority of throughput in premium beverage applications; coconut sugar is climbing the fastest on share as mineral-content marketing expands.
Application:
Volume concentration and technical specification intensity vary sharply across end-use categories.
- Beverages:Carbonated drinks and sports beverages drive the largest absolute volume, with reformulation mandates from major soda producers forcing rapid supplier qualification timelines. EFSA novel food requirements create 18-36 month commercialization gaps for European entrants.
- Bakery Products:Moisture retention and Maillard browning control present unresolved technical hurdles for erythritol and allulose incorporation. Clean-label bread brands in Denmark and Singapore are piloting continuous fermentation systems to resolve these formulation barriers.
- Dairy:Fermented sweeteners enable reduced-sugar yogurt and ice cream formulations without compromising freeze-thaw stability.
- Snacks:Energy bars and coated nuts represent emerging volume as protein-forward brands seek low-glycemic binding agents.
Beverages command the dominant share of current procurement; bakery products are gaining share fastest as technical hurdles around moisture retention resolve.
End User:
Procurement sophistication and volume commitment levels stratify sharply across buyer types.
- Food Manufacturers:Industrial bakeries and confectionery producers negotiate long-term offtake agreements for erythritol and xylitol at 99.5% purity grades. Stainless steel bioreactor capacity constraints now stretch 14-18 months for dedicated production lines.
- Beverage Companies:Direct procurement relationships with fermentation facilities are displacing traditional ingredient distributors. Large CPG buyers require transparent strain lineage documentation and dedicated capacity.
- Retailers:Private-label clean-label programs create fragmented demand across multiple SKUs with shorter contract horizons.
- Health Stores:Mineral-content differentiation and organic certification drive premium pricing for coconut sugar and raw honey variants.
Food manufacturers anchor volume commitments; beverage companies are expanding fastest as reformulation mandates accelerate.
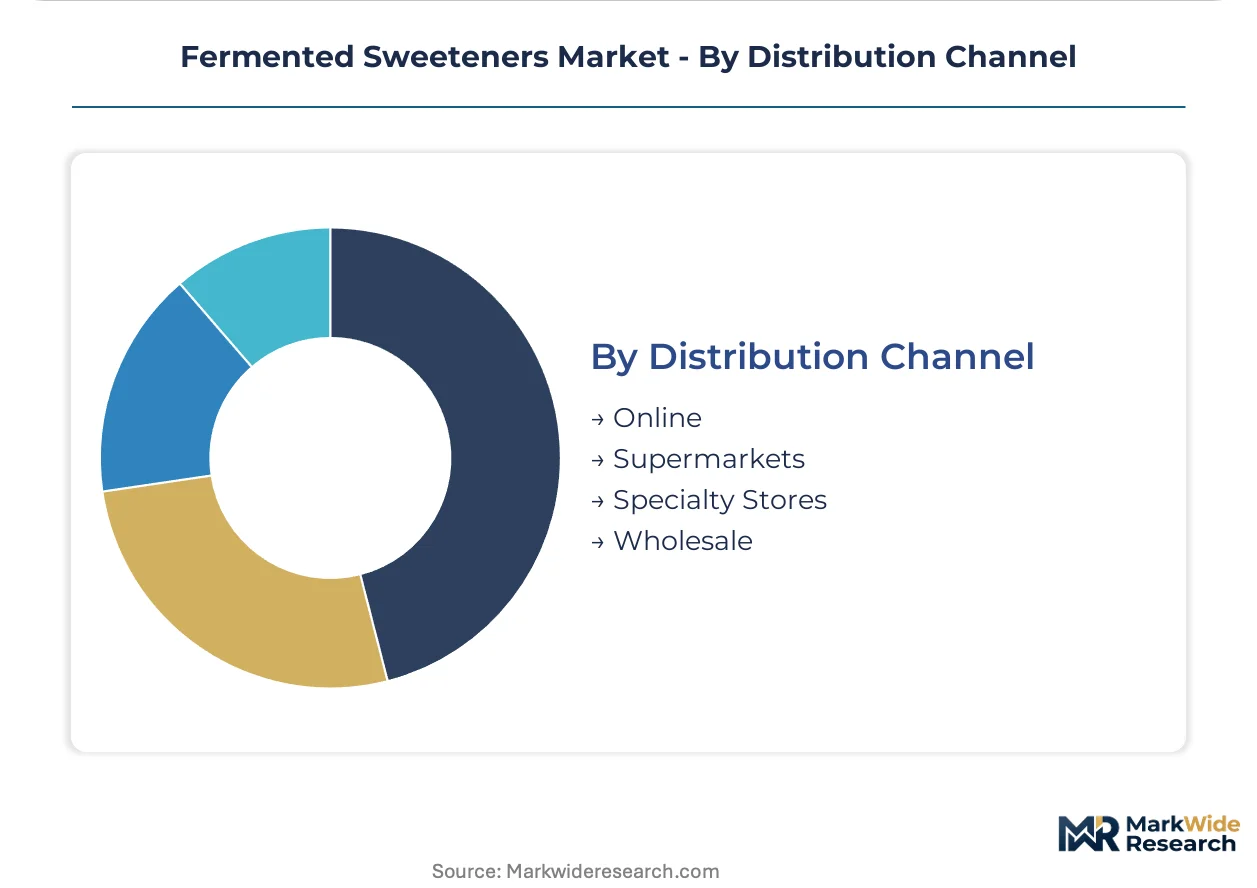
Distribution Channel:
Channel economics reflect purity-grade requirements and lot-size flexibility needs.
- Online:Direct-to-manufacturer platforms enable small-batch procurement for functional beverage startups. Real-time inventory visibility supports just-in-time fermentation scheduling.
- Supermarkets:Mass-market retail requires bulk packaging and consistent lot-to-lot specification compliance for private-label programs.
- Specialty Stores:Organic certification and origin documentation command premium positioning in health-focused retail.
- Wholesale:Ingredient distributors maintain relationships with mid-tier food manufacturers seeking technical support for formulation integration.
Supermarkets move the largest absolute volumes; online channels are expanding most quickly as startup beverage brands bypass traditional procurement intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in fermented sweeteners reveal concentrated production in corn-processing corridors and emerging demand centers in functional beverage markets. The United States maintains a net export position in erythritol and allulose, while European Union markets rely on imported fermentation-derived polyols to meet clean-label reformulation timelines. Asian markets show accelerating import growth as beverage manufacturers phase out artificial sweeteners.
United States
Functional beverage startups in Austin and established CPG brands in Chicago drive procurement concentration. FDA GRAS self-affirmation pathways compress commercialization timelines relative to European alternatives. The Corn Belt fermentation corridor spanning Iowa and Illinois anchors bulk erythritol production capacity expansion.
Germany
Industrial bakeries in Munich and clean-label confectionery producers in Hamburg create dual demand streams for xylitol and rare sugars. EFSA novel food authorization requirements extend market access timelines by 18-36 months compared to US pathways. The North Rhine-Westphalia biotech cluster hosts contract fermentation facilities serving pan-European beverage reformulation mandates.
India
Sports drink manufacturers in Mumbai and wellness beverage startups in Bangalore accelerate formulation partnerships. FSSAI regulatory harmonization with Codex standards reduces technical barriers for imported fermentation-derived ingredients. The Maharashtra-Gujarat industrial corridor attracts contract manufacturing investments targeting domestic functional beverage growth.
Singapore
Regional headquarters for multinational beverage brands concentrate procurement decision-making for Southeast Asian markets. The city-state's food safety agency maintains alignment with Codex and FDA standards, streamlining import clearance for precision-fermentation sweeteners. Bioprocessing facilities in Tuas leverage continuous fermentation systems for allulose production at 50,000-liter scale.
Brazil
Sugarcane substrate availability in São Paulo state underpins cost-competitive fermentation feedstock access. ANVISA regulatory frameworks for novel food ingredients lag FDA and EFSA precedents, creating commercialization uncertainty. The Campinas biotech cluster hosts pilot-scale facilities evaluating xylitol production from sugarcane bagasse cellulose.
Fermented Sweeteners Market Competitive Landscape
On the supply side, the industry is consolidating around integrated agribusiness conglomerates with captive fermentation infrastructure and specialized biotech firms with precision-fermentation platforms. Three strategic archetypes dominate: diversified ingredient majors leveraging existing corn-processing assets, European fermentation specialists with polyol expertise, and emerging precision-fermentation pure-plays targeting rare sugars. Capacity expansion and direct procurement partnerships with beverage brands constitute the dominant competitive moves, displacing traditional distributor intermediaries.
Within the diversified agribusiness tier, Cargill and Archer Daniels Midland Company exemplify players with backward integration into agricultural feedstock supply and forward integration into fermentation-derived ingredient portfolios. Jungbunzlauer Suisse AG anchors the European specialist archetype, occupying a position defined by citric acid fermentation expertise extending into sweetener co-production. Ajinomoto Co., Inc. represents the amino acid fermentation technology adaptation archetype, with its positioning reflecting decades of microbial cultivation optimization for high-intensity sweetener manufacturing.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland Company |
| Ingredion |
| Tereos |
| Ajinomoto Co., Inc. |
| Jungbunzlauer Suisse AG |
| Gulshan Polyols Ltd. |
| Hylen Co., Ltd. |
| Evolva |
| Others |
Supply & Pricing Matrix
The Iowa-Illinois Corn Belt fermentation corridor anchors bulk erythritol and allulose capacity expansion, concentrating upstream supply power in the hands of integrated agribusiness conglomerates with captive corn processing infrastructure. Downstream pricing power accrues to beverage manufacturers negotiating direct procurement relationships with dedicated bioreactor capacity, while mid-tier suppliers face margin compression from stainless steel vessel lead times stretching 14-18 months.
Pricing Analysis
Prior-generation extraction-based sweeteners trade at commodity spot benchmarks, current-generation fermentation-derived polyols command contract-based long-term offtake premiums, and next-generation CRISPR-optimized rare sugars anticipate value-based pricing once regulatory clarity emerges. Three-tier pricing structure across premium organic-certified, standard food-grade, and economy industrial-grade levels separates USDA-certified inputs from conventional fermentation outputs. Cost compression in standard grades is intensifying because bioreactor scale-up lags demand acceleration from beverage reformulation mandates. Food manufacturers with multi-year volume commitments exhibit lowest price sensitivity; functional beverage startups purchasing through online direct-to-manufacturer platforms show highest elasticity.
Supply Chain Analysis
Contract manufacturing concentration sits with Danish continuous fermentation specialists and Singaporean 50,000-liter scale facilities in Tuas, supplemented by North Rhine-Westphalia biotech clusters serving pan-European demand. Geographic supply concentration centers on the United States, Germany, and Singapore for precision fermentation capacity, with Brazil's Campinas cluster emerging for sugarcane bagasse cellulose evaluation. Raw material dependencies draw from organic corn substrates, sugarcane feedstock, and enzymatic conversion catalysts. Single-source vulnerability runs through chromatographic purification equipment with 14-18 month lead times. Distribution runs through direct procurement relationships displacing traditional ingredient distributor intermediaries, particularly visible among Austin functional beverage startups and Chicago-established CPG brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fermented sweeteners market is cycling through a capacity-led recovery as beverage reformulation mandates force rapid supplier qualification timelines and compress commercialization windows. FDA GRAS self-affirmation pathways relative to EFSA novel food delays create divergent regional investment cycles.
For Market Incumbents: Insulate margin structures by securing dedicated organic corn supply contracts ahead of climate-induced harvest variability, and accelerate backward integration into chromatographic purification equipment to bypass 14-18 month lead time bottlenecks. Threats from precision-fermentation pure-plays with CRISPR-optimized yeast platforms demand preemptive capacity expansion in the Iowa-Illinois corridor. Certification investment in USDA organic and EU organic regulation compliance preserves premium tier access.
For New Entrants and Emerging Players: India's Maharashtra-Gujarat industrial corridor offers the most penetrable geographic underpenetration as FSSAI regulatory harmonization with Codex standards reduces technical barriers for imported fermentation-derived ingredients. Bakery applications represent underexploited volume potential as moisture retention and Maillard browning technical hurdles resolve. Sports and wellness drink formulation partnerships with Mumbai manufacturers provide the optimal go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-fermentation pure-plays with demonstrated strain optimization capabilities over diversified agribusiness incumbents facing legacy asset reconfiguration costs. Long-term viability across the 5-10 year window hinges on regulatory clarity for genome-edited organism classifications and bioreactor scale-up execution. CRISPR strain optimization yield improvements reaching 40-60% for xylitol and erythritol serve as the critical inflection indicator to monitor.
| Strategic Initiative | Industry Significance |
|---|---|
| Bioreactor Capacity Expansion | Dedicated 50,000-liter stainless steel vessels in Singapore and Denmark secure offtake agreements from Austin beverage startups. |
| Backward Integration into Feedstock | Captive organic corn supply contracts in Iowa and Illinois insulate margin structures from climate-induced harvest volatility. |
| Regulatory Certification Investment | USDA organic and EU organic regulation compliance unlocks premium pricing eligibility for fermentation inputs. |
| Direct Procurement Partnerships | Transparent strain lineage documentation satisfies Chicago CPG buyer requirements and displaces distributor intermediaries. |
| CRISPR Strain Optimization | Genome-edited yeast platforms pending FDA and EFSA classification clarity promise 40-60% yield improvements. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fermentation facility operations directors, beverage company procurement leads, regulatory affairs specialists at FDA and EFSA, and contract manufacturing executives; alongside secondary validation through FDA GRAS notification filings, EFSA novel food submission databases, USDA organic certification records, and customs trade data for erythritol and allulose import-export flows. Bottom-up volume modeling across product type, application, and end-user segments was cross-checked against top-down market sizing derived from bioreactor capacity announcements and offtake agreement disclosures.
Forecast inputs considered precision fermentation technology diffusion rates, clean-label regulatory pressure intensity from FDA and EFSA, beverage reformulation mandate timelines from major carbonated drink producers, and bakery segment technical hurdle resolution progress across the analysis window. Segmentation dimensions modeled include product type maturity tier, application technical specification intensity, end-user procurement sophistication level, and geographic regulatory pathway cluster. CAGRs were derived from supply-demand balance projections incorporating bioreactor capacity expansion schedules and feedstock cost trajectory assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by precision-fermentation pure-plays with CRISPR platforms or rapid EFSA regulatory pathway compression would shift outcomes substantially. Forecasts reflect assumptions regarding genome-edited organism classification timelines, organic feedstock availability, and chromatographic equipment lead time normalization. Quarterly review of FDA GRAS notification volumes, EFSA novel food submission queues, and stainless steel bioreactor order backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Erythritol Market
Sweeteners
Xylitol Market
Sweeteners
Europe Plant-Derived and Synthetic Sugar Market
Sweeteners
China Food Sweetener Market
Sweeteners
Glucose, Dextrose, and Maltodextrin Market
Sweeteners
Coconut Sugar Market
Sweeteners
Argentina Food Sweetener Market
Sweeteners
Asia-Pacific Plant-Derived and Synthetic Sugar Market
Sweeteners
Natural Caloric Sweeteners Market
Sweeteners
Sucrose Acetate Isobutyrate Market
Sweeteners
Indonesia Food Sweetener Market
Sweeteners
Japan Allulose Market
Sweeteners
Muscovado Sugar Market
Sweeteners
Europe Sugar Substitute Market
Sweeteners
Raw Beetroot Sugar Market
Sweeteners
Europe Natural Sweetener Market