
 High-Fructose Corn Syrup (HFCS) Market | 2026-2036
High-Fructose Corn Syrup (HFCS) Market Size, Share, and Industry Trends Forecast 2026-2036
High-Fructose Corn Syrup (HFCS) Market Foresight
Food and beverage manufacturer procurement is expanding beyond legacy carbonated drink contracts into sports drinks, flavored waters, and ready-to-drink teas. Cargill Incorporated leverages its corn wet milling network to secure supply contracts with multinational bottlers. Archer Daniels Midland Company anchors Midwest production corridors with integrated grain origination and syrup refining. Ingredion Incorporated differentiates through modified starch and sweetener co-production capabilities that tighten customer switching costs.
High-fructose corn syrup denotes a liquid sweetener manufactured by enzymatically converting corn starch glucose to fructose, typically yielding formulations containing 42%, 55%, or 90% fructose by dry weight for specific functional sweetness profiles. HFCS 55 dominates beverage applications where its sweetness equivalence to sucrose reduces raw material costs, while HFCS 42 sustains baked goods and dairy applications requiring controlled browning and moisture retention. Confectionery demand for higher-fructose concentrates is maturing as candy manufacturers reformulate for cleaner-label positioning.
The FDA governs HFCS labeling under its food additive and GRAS frameworks, while USDA corn commodity programs influence feedstock pricing dynamics through crop insurance and ethanol mandate interactions. EPA biofuel quotas indirectly tighten corn supply allocations between sweetener and fuel ethanol processors. Stakeholders must monitor FDA added-sugar disclosure enforcement and state-level sugar tax proposals that could accelerate reformulation timelines.
Market Dynamics
Enzymatic conversion efficiency gains and FDA added-sugar disclosure mandates are compressing formulation timelines while beverage manufacturers accelerate reformulation cycles to maintain label compliance. Corn wet milling capacity concentration in the US Midwest creates supply-side rigidity that amplifies price volatility during drought cycles.
Growth Catalysts
- EPA biofuel quotas:Ethanol mandate interactions tighten corn supply allocations, elevating sweetener feedstock costs that processors pass through to beverage contracts.
- Sports drink formulation expansion:Bottlers are extending HFCS procurement beyond carbonated lines into isotonic and functional hydration segments requiring 55% fructose equivalence.
- Midwest refining corridor density:Iowa and Illinois corn wet milling clusters minimize logistics drag between grain origination and syrup refining.
Market Restraints
- Feedstock concentration risk:US corn belt weather volatility exposes processors to yield shocks that propagate through sweetener pricing within one growing season.
- Sucrose substitution economics:Brazilian sugar cane harvest cycles periodically invert HFCS cost advantages in coastal beverage plants.
- Clean-label reformulation pressure:Candy manufacturers are displacing 90% fructose concentrates with alternative sweeteners to avoid ingredient panel scrutiny.
Strategic Opportunities
- Modified starch co-production:Ingredion's integrated sweetener-starch capabilities create captive demand that locks in bottler volume commitments.
- Ready-to-drink tea penetration:Unsweetened and lightly sweetened RTD tea lines present white space for HFCS 42 formulations with controlled browning profiles.
- USDA crop insurance interactions:Revenue protection programs stabilize corn basis pricing for processors negotiating multi-year supply agreements.
Industry Challenges
- Enzyme optimization talent scarcity:Glucose isomerase engineering expertise concentrates at a handful of industrial biotechnology firms, constraining process innovation.
- Legacy equipment retrofit costs:Carbonated bottling lines require capital-intensive reconfiguration to handle viscosity variations between HFCS grades and alternative sweeteners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Fructose Corn Syrup (HFCS) Market |
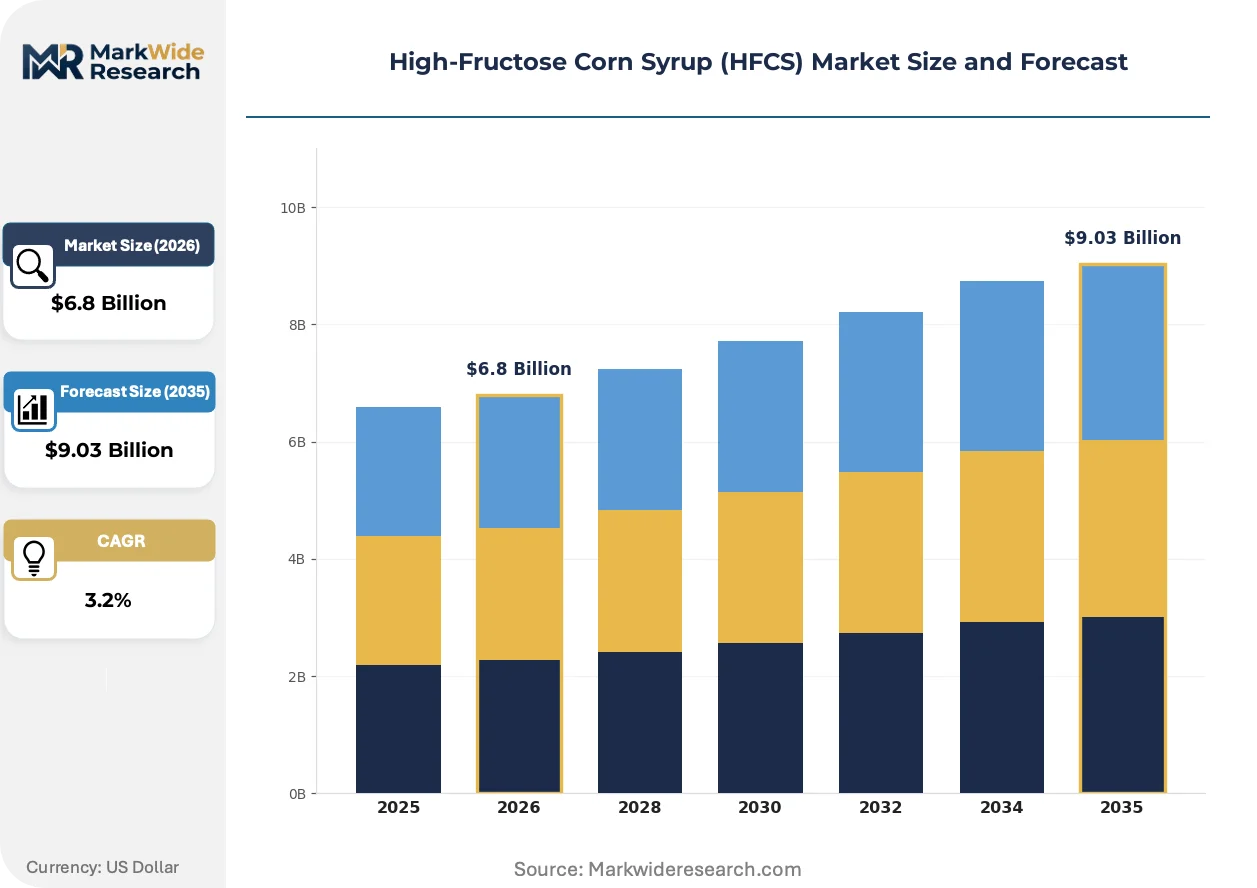
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.03 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HFCS 42, HFCS 55, HFCS 70, HFCS 90 Application: Beverages, Bakery, Dairy, Confectionery End User: Food Manufacturers, Beverage Producers, Pharmaceutical Companies, Other Industries Distribution Channel: Online Retail, Hypermarkets, Supermarkets, Direct Sales |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, Tate & Lyle PLC, Global Sweeteners Holdings Limited, Roquette Frères, Showa Sangyo Co. Ltd, AGRANA Beteiligungs-AG, COFCO Rongshi Biotechnology Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Fructose Corn Syrup (HFCS) Market Shifts & Advancements
Continuous enzymatic processing and real-time fructose monitoring are compressing conversion cycle times while reformulation chemistry shifts toward cleaner-label positioning. Regulatory disclosure mandates and procurement digitization are reshaping how sweetener specifications transmit through beverage supply chains.
Immobilized glucose isomerase reactor technology is electrifying starch-to-fructose conversion economics by enabling higher substrate throughput at lower enzyme loading rates. Archer Daniels Midland has deployed fixed-bed reactor arrays across Decatur and Cedar Rapids facilities. This process intensification is compressing unit conversion costs and tightening the cost gap against cane sugar in Gulf Coast bottling corridors.
FDA added-sugar line-item disclosure requirements are forcing nutrition panel redesigns that expose HFCS positioning to consumer scrutiny. Beverage formulators are responding with reduced-sugar line extensions that dilute fructose concentrations through bulking agent substitution. Sports drink and flavored water segments face the most acute label pressure, accelerating R&D timelines for stevia-HFCS hybrid formulations.
Bottler procurement departments are consolidating sweetener specifications into master service agreements that span multiple SKUs and production facilities. This specification bundling displaces spot-market purchasing and locks processors into volume-commitment contracts with penalty clauses. The shift is most visible among multinational beverage conglomerates operating integrated Midwest production and distribution networks.
High-Fructose Corn Syrup (HFCS) Market Segmentation
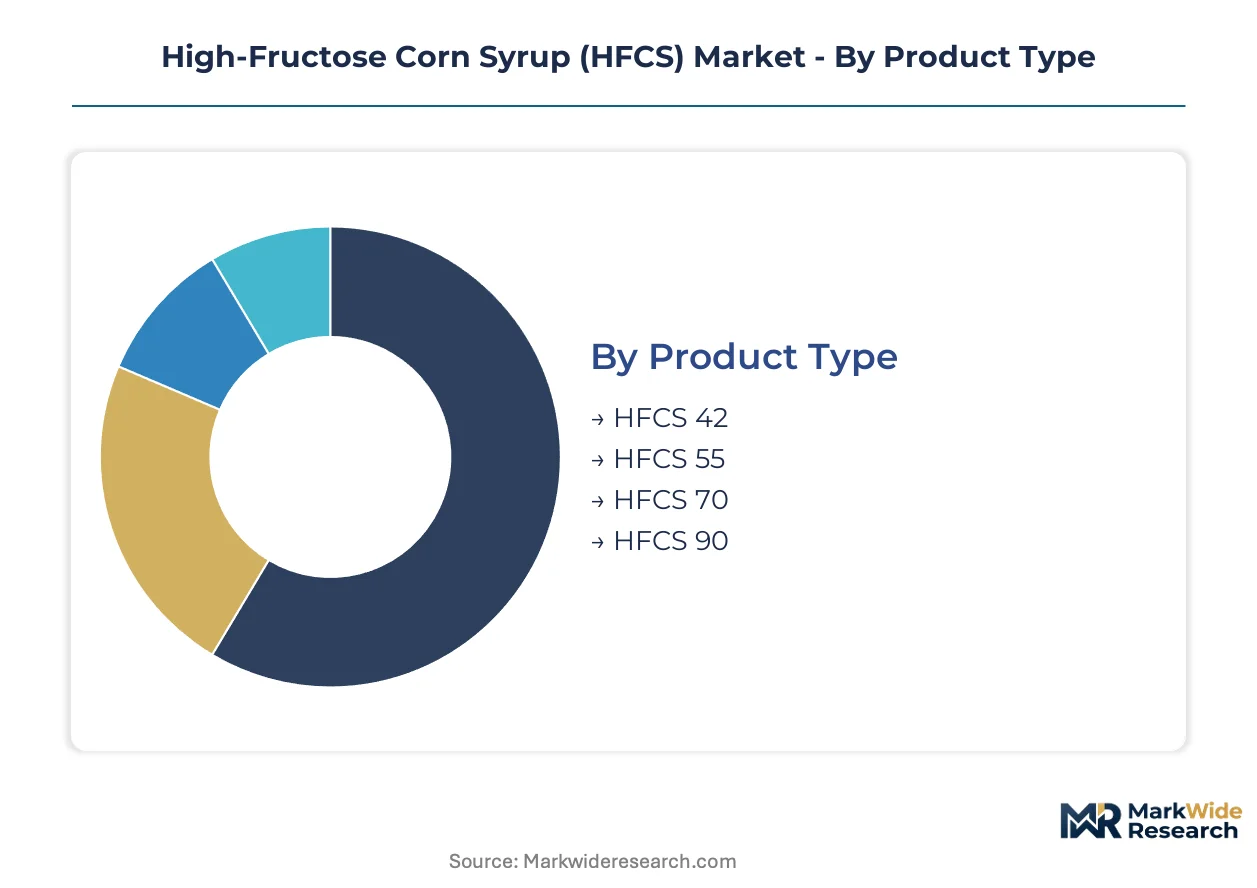
HFCS procurement patterns diverge sharply across product grades and end-use specifications. Manufacturers align enzymatic conversion intensity with functional sweetness requirements and label positioning strategies.
Product Type:
Buyers differentiate by fructose concentration thresholds that determine sweetness equivalence and browning chemistry.
- HFCS 55:Contains 55% fructose by dry weight, delivering sucrose-equivalent sweetness for carbonated and ready-to-drink formulations. Demand concentrates among multinational bottlers in the US Midwest where corn wet milling infrastructure minimizes logistics drag between grain origination and syrup refining.
- HFCS 42:Carries 42% fructose content, optimizing moisture retention and controlled Maillard browning in baked goods and dairy applications. Procurement from food manufacturers is accelerating as clean-label pressures force reformulation away from higher-fructose concentrates in confectionery segments.
- HFCS 70:Intermediate fructose concentration serving specialty applications requiring elevated sweetness without full sucrose replacement economics.
- HFCS 90:Highest fructose grade facing displacement as candy manufacturers reformulate for ingredient panel transparency and reduced added-sugar positioning.
Volume sits with HFCS 55; growth tilts toward HFCS 42.
Application:
Formulation chemistry dictates grade selection through viscosity, humectancy, and caramelization requirements.
- Beverages:Dominates procurement volume across carbonated soft drinks, sports drinks, and flavored waters. HFCS 55 equivalence to sucrose reduces raw material costs while maintaining sweetness intensity in high-acid formulations.
- Bakery:Requires HFCS 42 for moisture binding and shelf-life extension in breads, cakes, and pastries without excessive browning during baking cycles.
- Dairy:Ice cream and flavored milk applications leverage fructose hygroscopicity to control crystallization and texture stability.
- Confectionery:Facing structural decline as manufacturers displace high-fructose concentrates with alternative sweeteners for cleaner-label positioning.
Volume concentrates in Beverages; Bakery applications are climbing the fastest.
End User:
Customer scale and specification bundling power determine contract structures and pricing mechanisms.
- Food Manufacturers:Diverse procurement spanning bakery, dairy, and processed food segments with fragmented SKU-level purchasing.
- Beverage Producers:Consolidated master service agreements spanning multiple production facilities and product lines, locking processors into volume-commitment contracts with penalty clauses.
- Pharmaceutical Companies:Niche demand for excipient-grade syrups in cough suppressants and liquid formulations with stringent purity specifications.
- Other Industries:Industrial fermentation and animal feed applications utilizing lower-grade syrup streams.
Volume aggregates with Beverage Producers; Food Manufacturers are expanding most quickly.
Distribution Channel:
Logistics configuration and order scale determine channel economics for bulk liquid sweetener delivery.
- Direct Sales:Tanker-truck and railcar deliveries from corn wet milling facilities to integrated beverage production campuses dominate high-volume procurement.
- Hypermarkets:Retail-packaged HFCS for food service and small-scale manufacturing buyers requiring pallet-scale purchasing flexibility.
- Supermarkets:Consumer-facing bottled syrups and commercial kitchen supplies with limited volume relative to industrial channels.
- Online Retail:Emerging channel for specialty grades and smaller order quantities bypassing traditional distributor networks.
Volume flows through Direct Sales; Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iowa and Illinois corn belts anchor HFCS production geography through dense wet milling infrastructure that processes regional grain harvests into liquid sweetener streams for beverage manufacturing corridors.
United States
Midwest corn refining clusters in Decatur and Cedar Rapids supply carbonated bottlers through integrated rail and tanker networks. FDA added-sugar disclosure mandates force nutrition panel redesigns that expose HFCS positioning to consumer scrutiny. EPA biofuel quotas tighten corn supply allocations between sweetener and fuel ethanol processors, elevating feedstock cost volatility that passes through to beverage contracts.
Canada
Cross-border syrup flows from US Midwest refineries supply Ontario and Quebec beverage plants with HFCS 55 for carbonated and ready-to-drink formulations. Health Canada labeling standards align with FDA frameworks but enforce bilingual packaging requirements that complicate procurement specifications. Toronto-area bottling campuses receive railcar deliveries through Great Lakes logistics corridors.
Mexico
Beverage manufacturers in Mexico City and Monterrey metro areas source HFCS through NAFTA-era supply chains that integrate US corn refining output with Latin American bottling operations. Mexican sugar cane harvests periodically invert sweetener economics in coastal plants. Jalisco and Nuevo León production facilities balance HFCS procurement against domestic sucrose availability.
China
COFCO Rongshi Biotechnology anchors domestic HFCS production through state-backed corn processing infrastructure in Northeast China grain belts. SAMR food additive regulations govern enzymatic sweetener labeling under national food safety frameworks. Shandong and Jilin provinces concentrate starch-to-syrup conversion capacity that supplies beverage manufacturers in Yangtze River Delta urban corridors.
Japan
Showa Sangyo Co. Ltd exemplifies domestic HFCS production through corn wet milling operations serving Japanese beverage and food manufacturers. METI industrial policy supports sweetener sector consolidation amid declining per-capita soft drink consumption. Osaka and Nagoya industrial zones maintain refining capacity that processes imported corn into formulations for domestic confectionery and dairy applications.
High-Fructose Corn Syrup (HFCS) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue clean-label alternative sweetener adjacencies that threaten HFCS volume retention in confectionery segments. Three to five integrated agribusiness conglomerates dominate North American capacity through captive corn origination networks. Strategic archetypes separate grain-trading refiners from specialty starch-sweetener co-producers and regional Asian processors. Competitive moves concentrate on multi-year supply contract consolidation and enzymatic conversion efficiency investments that compress unit costs.
Among North American agribusiness conglomerates, Cargill Incorporated, Archer Daniels Midland Company, and Ingredion Incorporated exemplify the integrated refiner archetype that combines grain origination with wet milling output. Cargill leverages its global commodity trading infrastructure to secure corn feedstock pricing advantages. Archer Daniels Midland anchors Midwest production corridors through fixed-bed reactor deployments that intensify enzymatic conversion economics. Ingredion differentiates positioning through modified starch co-production capabilities that tighten customer switching costs across beverage and food manufacturing accounts.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Global Sweeteners Holdings Limited |
| Roquette Frères |
| Showa Sangyo Co. Ltd |
| AGRANA Beteiligungs-AG |
| COFCO Rongshi Biotechnology Co. Ltd |
| Others |
Supply & Pricing Matrix
Family-owned grain cooperatives and sovereign-backed corn processors anchor Midwest refining corridors, translating captive origination networks into pricing discipline that resists spot-market volatility during drought cycles. Their integrated control over elevator assets and wet milling capacity compresses basis spreads between farmgate corn and finished syrup, locking beverage bottlers into multi-year contracts with limited renegotiation leverage.
Pricing Analysis
Volume-heavy beverage contracts trade at thin margins against premium-grade pharmaceutical and export tiers. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade levels separates stringent purity specifications from standard beverage formulations. Cost compression in food-grade tiers is intensifying because EPA biofuel quotas tighten corn supply allocations between sweetener and fuel ethanol processors. Small-scale food manufacturers exhibit acute price sensitivity, while multinational bottlers absorb pass-through costs through specification bundling.
Supply Chain Analysis
Dual-sourcing requirements from multinational beverage conglomerates mandate qualification of at least two wet milling suppliers per production corridor, forcing redundancy into Midwest logistics networks. Geographic supply concentration centers on the United States, China, and Japan, with regional processors drawing from domestic corn harvests or imported grain streams. Raw material dependencies rest on corn kernel supply, glucose isomerase enzyme stocks, and caustic soda for pH adjustment. Single-source vulnerability concentrates in enzyme engineering expertise held by a handful of industrial biotechnology firms. Distribution runs through tanker-truck and railcar direct delivery from wet milling facilities to integrated beverage campuses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA added-sugar disclosure mandates erect compliance moats that favor established processors with regulatory affairs infrastructure, raising capital requirements for new entrants seeking GRAS affirmation and nutrition panel redesign capabilities.
For Market Incumbents: Lock in multi-year supply agreements with beverage conglomerates before enzyme optimization talent scarcity worsens, securing volume commitments that amortize fixed-bed reactor investments across Decatur and Cedar Rapids corridors. Defend against sucrose substitution by accelerating fixed-bed reactor deployments that compress unit conversion costs below Brazilian cane sugar import parity. For New Entrants and Emerging Players: Regional dairy processors represent the most penetrable customer segment, as fragmented SKU-level purchasing lacks specification bundling power and faces reformulation pressure from clean-label positioning. Target white space in ready-to-drink tea formulations requiring HFCS 42 with controlled browning profiles, partnering with co-manufacturers to bypass capital-intensive wet milling infrastructure. For Investors and Strategic Acquirers: USDA crop insurance enrollment spikes are the leading indicator that corn basis volatility will tighten processor margins and trigger distressed asset opportunities. Long-term viability hinges on backward integration into grain origination networks that stabilize feedstock costs across the analysis window. Watch for EPA biofuel quota expansion announcements as the signal that corn supply allocations will shift toward fuel ethanol, squeezing sweetener processor economics.| Strategic Initiative | Industry Significance |
|---|---|
| Fixed-Bed Reactor Deployment | Archer Daniels Midland's intensification of enzymatic conversion compresses unit costs against cane sugar in Gulf Coast corridors. |
| Modified Starch Co-Production | Ingredion's integrated capabilities tighten customer switching costs across beverage and food manufacturing accounts. |
| Multi-Year Supply Agreement Consolidation | Cargill's master service agreements with multinational bottlers displace spot-market purchasing and lock volume commitments. |
| Clean-Label Reformulation Partnership | Stevia-HFCS hybrid R&D collaborations address FDA disclosure mandates while preserving sweetness intensity in sports drinks. |
| Midwest Logistics Corridor Expansion | Railcar and tanker-truck fleet additions between Iowa corn belts and Chicago bottling campuses minimize logistics drag. |
Research Methodology
USDA crop reports, EPA biofuel quota filings, and FDA GRAS notifications formed the secondary backbone, cross-referenced against SEC 10-K disclosures from publicly traded agribusiness conglomerates. Primary interviews with corn wet milling plant managers, beverage procurement leads, and enzyme engineering specialists at industrial biotechnology firms validated conversion efficiency claims and contract structure terms. Bottom-up volume estimates from individual refinery capacity utilization rates were triangulated against top-down sweetener demand projections from beverage formulation databases.
Bottom-up modeling tracked HFCS 55, HFCS 42, HFCS 70, and HFCS 90 grade volumes through beverage, bakery, dairy, and confectionery end-use channels across the projection horizon. Analytical segmentation incorporated fructose concentration tiers, application-specific viscosity requirements, and customer scale archetypes from fragmented food manufacturers to consolidated beverage producers. CAGRs were derived from regression analysis of historical corn-sugar price spreads and enzymatic conversion cost trajectories, with forecast inputs including EPA renewable fuel mandate schedules and FDA enforcement patterns for added-sugar disclosures.
Caveats apply where drought-induced corn yield shocks, Brazilian sugar cane harvest inversions, or state-level sugar tax implementations could materially shift the outlook. Deviation in EPA biofuel quota stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Global Artificial Sweeteners Market
Sweeteners
North America Sugar Substitutes Market
Sweeteners
France Food Sweetener Market
Sweeteners
Corn Syrup Market
Sweeteners
Mexico Food Sweetener Market
Sweeteners
Oligofructose Market
Sweeteners
Australia Food Sweetener Market
Sweeteners
North America Plant-Derived and Synthetic Sugar Market
Sweeteners
Asia-Pacific Plant-Derived and Synthetic Sugar Market
Sweeteners
Palm Sugar Market
Sweeteners
Asia-Pacific Sugar Substitute Market
Sweeteners
China Saccharin Market
Sweeteners
South America Low-Calorie Sweeteners Market
Sweeteners
Europe Sugar Substitute Market
Sweeteners
Europe Low-Calorie Sweeteners Market
Sweeteners
Sugar Alcohol Market