
 Sweeteners Market | 2026-2036
Sweeteners Market Size, Share, and Industry Trends Forecast 2026-2036
Sweeteners Market Intelligence
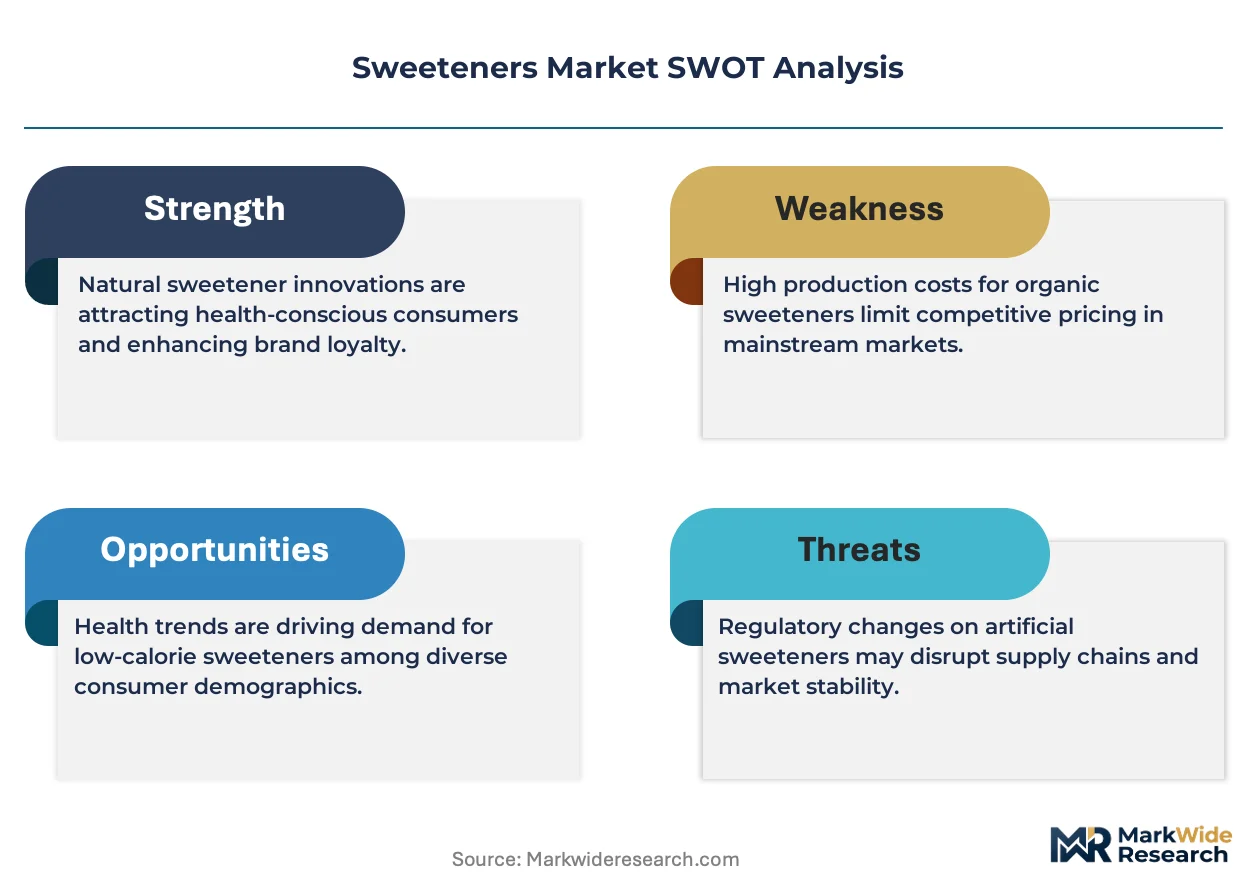
Profitability from high-fructose corn syrup production is narrowing as food manufacturers reformulate products with high-intensity natural sweeteners. Cargill, Incorporated leverages its vast agricultural supply chain to compete on both volume and specialized ingredients. Tate & Lyle PLC differentiates through its focus on texturants and specialty sweeteners for clean-label applications. Archer Daniels Midland Company sustains its market position through extensive processing capabilities and global distribution networks.
Sweeteners are food additives that provide a sweet taste, classified as nutritive or non-nutritive. Non-nutritive, high-intensity sweeteners like steviol glycosides offer intense sweetness with minimal calories, serving as sugar replacements in various formulations. Demand for natural sweeteners is outpacing growth in artificial types due to clean-label trends. The beverages application consumes the largest volume, driven by reformulations in soft drinks and juices.
Regulatory bodies like the U.S. FDA and the European Food Safety Authority (EFSA) define market access by approving new sweeteners and setting acceptable daily intake levels. In China, the State Administration for Market Regulation (SAMR) enforces GB standards for food additives, influencing ingredient choices. Stakeholders must navigate the divergent approval timelines and labeling mandates across key markets to ensure successful product commercialization.
Market Dynamics
The central structural force shaping the sweeteners market is the global regulatory and consumer-led campaign against sugar. This pressure, exemplified by sugar taxes in multiple countries, compels food and beverage companies to accelerate product reformulation using alternative sweeteners to meet health targets.
Growth Catalysts
- Government Health Policies:Sugar taxes enacted in the United Kingdom and Mexico create direct financial incentives for beverage and food manufacturers to reduce sugar content, boosting demand for alternative nutritive and non-nutritive sweeteners in reformulation efforts.
- Clean-Label Consumer Demand:A pronounced consumer preference for natural and recognizable ingredients is driving adoption of plant-based sweeteners like stevia and monk fruit, particularly in the North American and European food and beverage sectors.
- Emerging Market Health Awareness:In China, a rapidly expanding middle class with higher disposable income is increasingly seeking healthier, low-calorie products, creating a significant new demand center for natural and high-intensity sweeteners.
Market Restraints
- Formulation and Taste Hurdles:Many high-intensity natural sweeteners, including certain steviol glycosides, exhibit off-tastes such as bitterness or a lingering aftertaste, requiring complex masking solutions and increasing research and development costs for food manufacturers.
- Input Cost Volatility:The supply of agricultural raw materials for natural sweeteners, such as stevia leaf, is subject to climate-related variability and crop yield fluctuations, leading to price instability compared to synthetically produced artificial sweeteners.
- Divergent Regulatory Approvals:Inconsistent and lengthy approval processes for novel sweeteners between regulatory bodies like the U.S. FDA and the European Food Safety Authority (EFSA) delay market entry and complicate global product launch strategies.
Strategic Opportunities
- Fermentation-Based Production:Advances in precision fermentation enable the commercial-scale production of rare, better-tasting sweeteners like Reb M, offering a scalable and sustainable alternative to traditional agricultural extraction methods and improving taste profiles.
- Expansion into New Applications:Significant white space exists in applying advanced sweeteners to categories beyond beverages, including dairy, baked goods, and confectionery, where sugar reduction remains a key technical and marketing challenge for manufacturers.
- Untapped Pharmaceutical Demand:The pharmaceutical industry presents an opportunity for high-purity sweeteners as excipients in liquid medications, chewable tablets, and oral care products, masking the taste of active ingredients for improved patient compliance.
Industry Challenges
- Agricultural Supply Chain Consistency:Ensuring a stable and high-quality supply of raw materials like stevia leaves and monk fruit is a persistent operational challenge, complicated by geographical concentration of cultivation and susceptibility to agricultural diseases.
- Reformulation Expertise Gap:A shortage of food technologists skilled in reformulating complex products to replace sugar without compromising on texture, mouthfeel, and shelf stability creates a bottleneck for manufacturers seeking to adapt their portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweeteners Market |
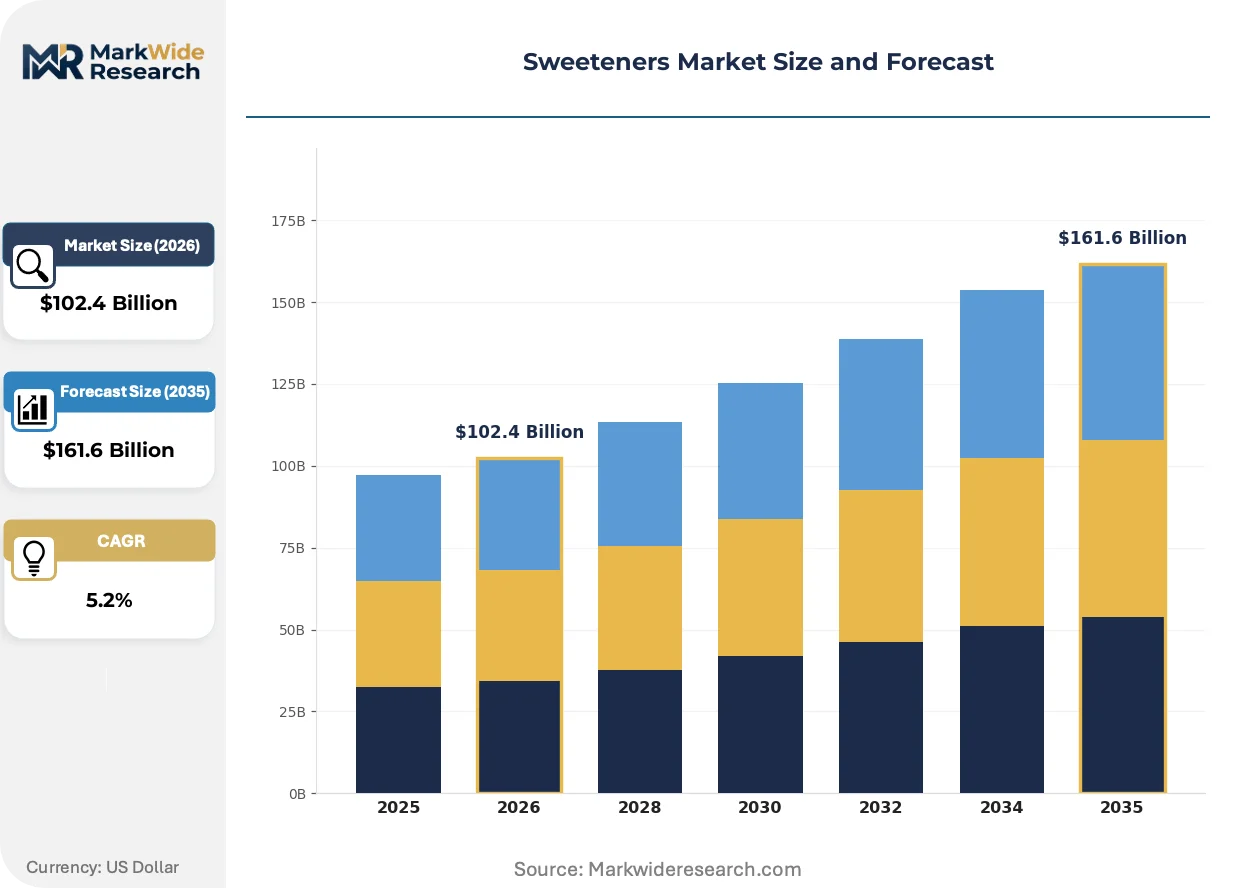
| Market Size in 2026 | $102.4 Billion |
| Market Size in 2035 | $161.6 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Sweeteners, Artificial Sweeteners, Sugar Alcohols, High-Intensity Sweeteners Application: Beverages, Bakery Products, Dairy Products, Confectionery End User: Food Manufacturers, Beverage Companies, Retail Consumers, Dietary Supplements Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Tate & Lyle PLC, Ingredion Incorporated, Roquette Frères, Südzucker AG, Ajinomoto Co., Inc., DuPont de Nemours Inc., Associated British Foods PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweeteners Market Strategic Shifts & Innovations
Biotechnology is redefining the concept of natural ingredients, creating a new competitive frontier in sweetener production. This shift allows for the scalable synthesis of rare, high-performance sweetening compounds that were previously constrained by inconsistent agricultural yields and high extraction costs.
Precision fermentation is a key enabling technology for producing specific, high-purity molecules like steviol glycosides and allulose. Major food and beverage corporations are adopting these ingredients to achieve superior taste profiles in zero-sugar formulations. This technology is virtualizing the agricultural supply chain for high-value sweeteners, creating a consistent, lab-based source that decouples production from farming land and climate variability.
Front-of-pack labeling regulations, including the Nutri-Score system in Europe and health warning labels in Latin American countries, are forcing rapid product changes. These policies directly penalize products with high sugar content, creating a powerful incentive for reformulation with low-calorie alternatives. The beverage, cereal, and dairy categories are most affected, accelerating their transition toward sweeteners like erythritol and stevia to improve nutritional scores.
A demand-side shift toward "clean-label" products influences ingredient selection across the food industry. Consumers are increasingly scrutinizing ingredient lists, favoring plant-derived, minimally processed options over artificial sweeteners such as aspartame or acesulfame potassium. This behavioral change is most visible in North America and Western Europe, where demand for products featuring stevia and monk fruit is strongest within the wellness and natural foods channels.
Sweeteners Market Segmentation
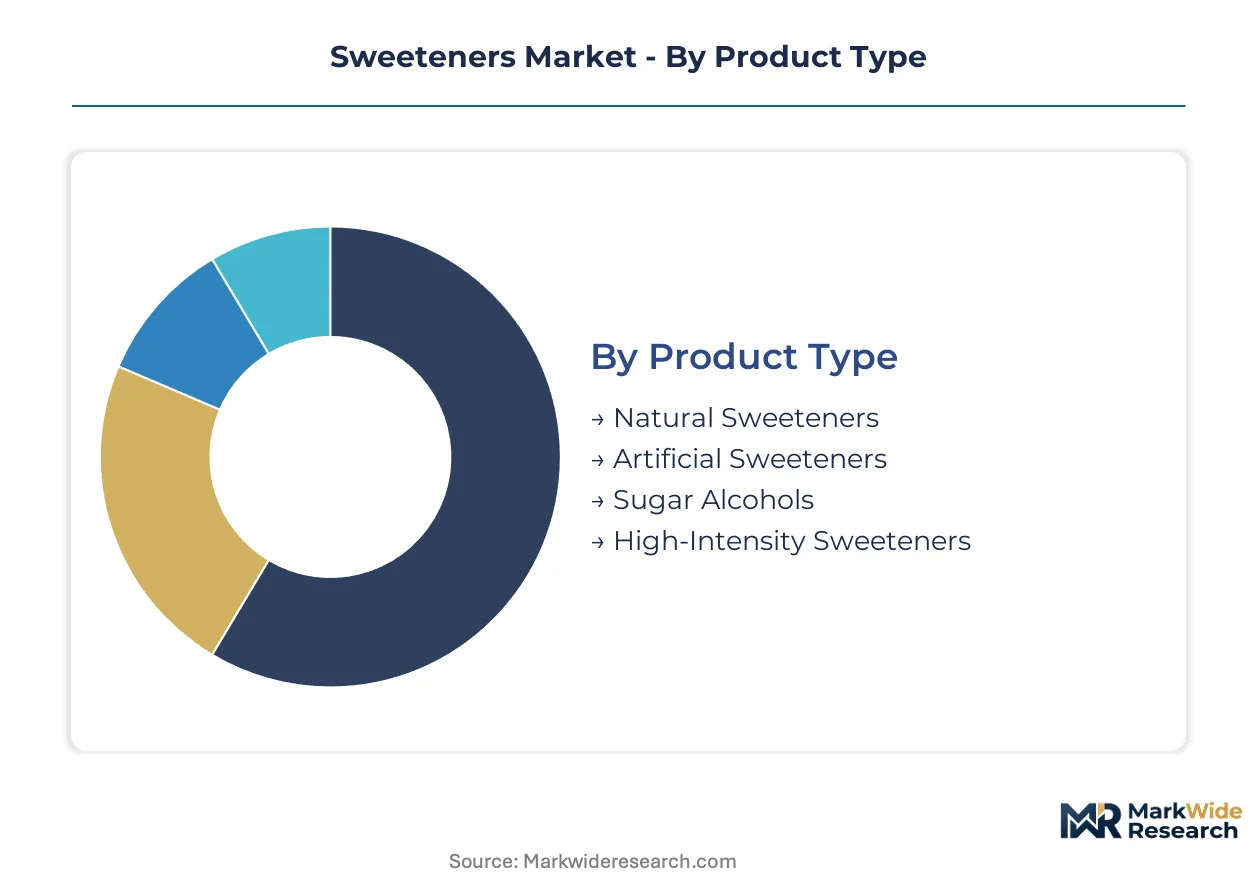
The sweeteners market exhibits diverse consumption patterns and product offerings, driven by evolving consumer health preferences and regulatory pressures. Understanding these distinct segments allows stakeholders to identify specific growth avenues and tailor product development strategies. This market's segmentation highlights areas of rapid innovation and established demand.
Product Type:
Product type segments display varying innovation cycles, from rapidly evolving natural options to established artificial compounds.
- Natural Sweeteners:These plant-derived compounds, such as stevia and monk fruit, provide sweetness with perceived health benefits. Demand is concentrating in North America and Western Europe, driven by clean-label consumer preferences and functional food trends.
- High-Intensity Sweeteners:Offering significant sweetness with minimal calories, this category includes both natural (e.g., Reb M) and artificial (e.g., sucralose) variants. Beverage companies are driving demand for these ingredients to achieve sugar reduction targets in soft drinks and juices.
- Artificial Sweeteners:Synthetically produced compounds like aspartame and acesulfame potassium offer cost-effective sweetness.
- Sugar Alcohols:Polyols such as erythritol and xylitol provide bulk and sweetness, often used in confectionery and sugar-free products.
Artificial Sweeteners dominate the installed base due to historical usage. Natural Sweeteners are where expansion concentrates, propelled by health-conscious consumer choices.
Application:
Application segments vary significantly in their volume requirements and formulation complexities.
- Beverages:This segment includes soft drinks, juices, and flavored waters, where sweeteners are critical for taste and calorie reduction. Reformulation efforts are intense in this category, particularly in countries with sugar taxes like the United Kingdom and Mexico.
- Bakery Products:Sweeteners here contribute to texture, browning, and moisture retention in items like cakes, cookies, and breads. Manufacturers face challenges in maintaining product integrity while reducing sugar content, leading to demand for functional alternatives.
- Dairy Products:This category encompasses yogurts, ice creams, and flavored milks, utilizing sweeteners for taste and mouthfeel.
- Confectionery:Sweeteners are essential in candies, chocolates, and chewing gums, driving innovation in sugar-free and reduced-sugar options.
Beverages consume the largest volume of sweeteners. Bakery Products are experiencing significant innovation as manufacturers seek sugar reduction without compromising texture.
End User:
End user segments exhibit distinct purchasing behaviors and regulatory compliance needs.
- Food Manufacturers:These entities incorporate sweeteners into a wide array of processed foods, including snacks, sauces, and ready meals. Their demand is shifting towards natural and high-intensity options to meet clean-label trends and health targets.
- Beverage Companies:Producers of soft drinks, fruit juices, and energy drinks are major consumers of alternative sweeteners. They are rapidly reformulating products to avoid sugar taxes and cater to consumer preferences for low-calorie options.
- Retail Consumers:Individual buyers purchase tabletop sweeteners and products containing them for home use and direct consumption.
- Dietary Supplements:Sweeteners are utilized in powders, chewables, and liquid formulations to improve palatability of health products.
Food Manufacturers represent a broad base of industrial demand. Beverage Companies are driving the fastest reformulation cycles in the market.
Distribution Channel:
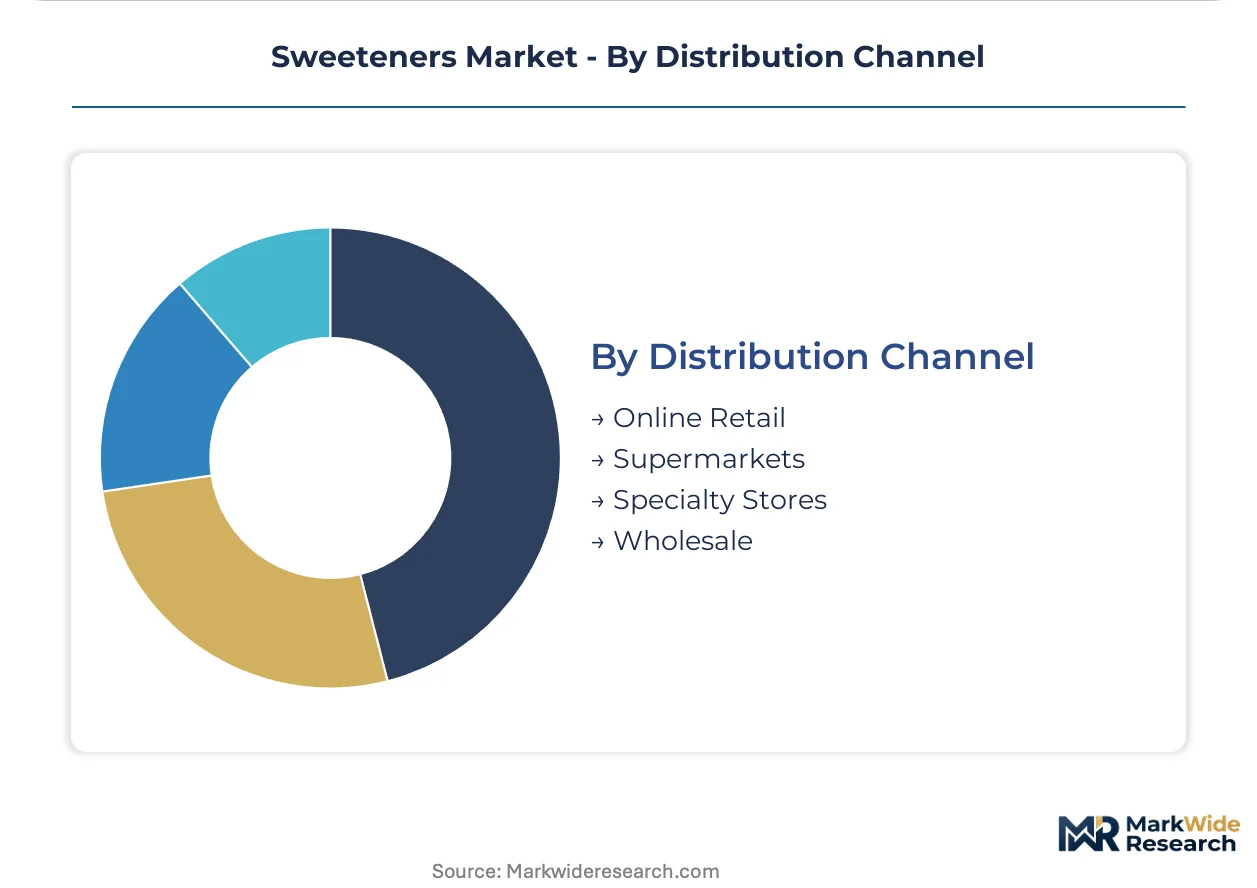
Distribution channels reflect varying levels of supply concentration and direct access to end-users.
- Wholesale:This channel supplies bulk sweeteners directly to industrial users like food and beverage manufacturers. It is characterized by large volume transactions and direct business-to-business relationships, supporting global supply chains.
- Supermarkets:These large-format retail stores offer a wide range of sweetener-containing products and tabletop sweeteners to general consumers. Product visibility and shelf placement are critical for brand success within this channel.
- Online Retail:E-commerce platforms provide direct-to-consumer access for tabletop sweeteners and specialty ingredients, expanding market reach.
- Specialty Stores:Health food stores and organic markets cater to niche consumer segments seeking premium and natural sweetener options.
Wholesale remains the foundational channel for industrial procurement. Online Retail is expanding its reach for consumer-packaged sweetener products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global sweeteners market exhibits varied consumption patterns, with some geographies prioritizing low-calorie reformulations while others still contend with traditional sugar usage. Regulatory actions and consumer health trends create distinct demand profiles across key economic regions. This differentiation influences ingredient choices and market penetration strategies for sweetener producers.
United States
Consumer demand for natural, plant-based sweeteners drives significant market activity across the United States. The U.S. FDA approves new high-intensity sweeteners, influencing product innovation and market entry for novel compounds. California's food and beverage sector actively adopts stevia and monk fruit in new product launches, reflecting a strong health-conscious consumer base.
China
China's expanding middle class increasingly seeks healthier, low-calorie food and beverage options, fueling demand for alternative sweeteners. The State Administration for Market Regulation (SAMR) enforces GB standards for food additives, guiding ingredient selection for domestic and imported products. Manufacturers in the Yangtze River Delta region are rapidly integrating advanced sweeteners into new product lines for beverages and dairy.
United Kingdom
The UK's sugar tax policies create direct financial incentives for beverage and food manufacturers to reduce sugar content. The Food Standards Agency (FSA) monitors compliance and safety standards for all food ingredients, including sweeteners. London-based food and beverage companies are at the forefront of reformulating soft drinks with erythritol and stevia to meet health targets.
Brazil
Brazil's large beverage market is undergoing reformulation, driven by health awareness and potential future regulatory pressures on sugar. ANVISA, the Brazilian Health Regulatory Agency, sets guidelines for sweetener usage and labeling in food products. São Paulo's food processing industry is actively exploring cost-effective, high-intensity sweeteners for juices and dairy items.
Germany
German consumers show a strong preference for natural and clean-label ingredients, influencing the adoption of plant-based sweeteners. The European Food Safety Authority (EFSA) sets acceptable daily intake levels for sweeteners, impacting their permissible use in food and drink. The Bavaria region, with its strong food manufacturing base, integrates specialty sweeteners into confectionery and bakery applications.
Sweeteners Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a dynamic competitive environment in the sweeteners market. The market structure features a mix of large agricultural commodity processors and specialized ingredient suppliers. These entities pursue strategic partnerships and portfolio diversification to maintain market relevance.
Within the agricultural processing archetype, Cargill, Incorporated and Archer Daniels Midland Company exemplify global reach and extensive supply chain integration. Tate & Lyle PLC represents a specialized ingredient focus, emphasizing texturants and specialty sweeteners for clean-label applications. These companies leverage their foundational strengths to navigate evolving consumer preferences and regulatory landscapes.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Tate & Lyle PLC |
| Ingredion Incorporated |
| Roquette Frères |
| Südzucker AG |
| Ajinomoto Co., Inc. |
| DuPont de Nemours Inc. |
| Associated British Foods PLC |
| Others |
Cost & Logistics Intelligence
Commodity volatility in agricultural raw materials like stevia leaf and monk fruit directly shapes pricing tier spreads for natural sweeteners and influences the geographic concentration of processing capabilities across the supply chain.
Pricing Analysis
Contract-based long-term offtake agreements dominate for high-volume sweeteners, while specialty ingredients often trade on a project-based or spot market. Quality grade and specific functional properties like taste profile drive price differentiation, with volume scale also impacting pricing for large industrial buyers. Pricing softness stems from intense competition among artificial sweetener producers and increasing availability of fermentation-derived natural alternatives. Beverage companies are highly price-sensitive for bulk sweeteners, whereas pharmaceutical manufacturers prioritize purity and specific excipient functionality.
Supply Chain Analysis
Upstream feedstock for natural sweeteners, such as stevia leaf and monk fruit, primarily originates from China and Southeast Asian countries. The market relies on agricultural inputs for natural variants and chemical precursors for artificial types. Agricultural supply chain consistency represents a structural risk, susceptible to climate variability and disease outbreaks. Wholesale channels distribute bulk ingredients directly to food and beverage manufacturers globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sweeteners market presents a platform-economics inflection, as precision fermentation technologies create a new ecosystem for scalable, taste-optimized ingredient production. This shift fosters interoperability between biotech firms and established food manufacturers.
For Market Incumbents: Harden existing agricultural supply chains through diversification and climate-resilient farming practices to mitigate input cost volatility. Invest strategically in fermentation-based production capabilities to counter the threat from emerging biotech firms. Expand portfolios into specialized clean-label texturants and functional ingredients, moving beyond bulk sweetener competition. Leverage global distribution networks to commercialize novel, better-tasting sweetening compounds rapidly.
For New Entrants and Emerging Players: Build out niche positions in fermentation-derived rare sweeteners like Reb M, targeting the pharmaceutical and premium beverage sectors. Focus on markets with strong clean-label demand, such as North America and Western Europe, for initial penetration. Develop robust intellectual property around novel enzymatic conversion processes. A go-to-market angle emphasizing superior taste profiles and consistent supply will differentiate offerings.
For Investors and Strategic Acquirers: The market sits at a transformative growth phase that favors technology-driven ingredient specialists with strong IP portfolios. Long-term viability over the next decade hinges on scaling precision fermentation capabilities and securing regulatory approvals across key geographies. Target acquisition archetypes include biotech startups with proven fermentation platforms or specialty ingredient firms possessing unique clean-label solutions. Watch for significant M&A activity involving established food companies acquiring fermentation expertise as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | This initiative enables cost-effective production of rare sweeteners like Reb M, addressing taste hurdles for beverage companies. |
| Clean-Label Ingredient Portfolio Expansion | Diversifying offerings with plant-derived texturants meets consumer demand for natural products in dairy and bakery. |
| Global Regulatory Approval Acceleration | Expediting market access for novel sweeteners like allulose ensures wider product commercialization across diverse markets. |
| Agricultural Supply Chain Diversification | Reducing reliance on single-origin sourcing for stevia leaf mitigates input cost volatility for food manufacturers. |
| Strategic Partnerships with Biotech Firms | Collaborations with technology specialists accelerate the development of next-generation, high-performance sweetening compounds. |
Research Approach
The analysis maps natural, artificial, and high-intensity sweetener sub-sectors, each validated through primary interviews with R&D directors, procurement leads, and regulatory affairs specialists. Secondary validation involved reviewing U.S. FDA approvals, EFSA opinions, and SAMR GB standards. This approach combined bottom-up data collection with top-down market assessments.
Assumptions held fixed include stable global economic conditions, while regulatory shifts and consumer preference trends were varied across the analysis window. Segmentation dimensions modeled include product type, application, end-user, and regional consumption patterns. Compound annual growth rates were derived from historical trends and projected adoption rates of new technologies. Key forecast inputs included sugar tax implementation schedules and precision fermentation capacity expansions.
Sensitivities concentrate around unforeseen regulatory changes impacting novel sweetener approvals and rapid shifts in agricultural commodity prices. Forecasts reflect documented assumptions regarding technological advancements and consumer health awareness. Cross-checking against national food consumption data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Refined Cane Sugar Market
Sweeteners
China Allulose Market
Sweeteners
Cassava Syrup Market
Sweeteners
Dextrates Market
Sweeteners
Beetroot Molasses Market
Sweeteners
Steviol Glycoside Market
Sweeteners
North America Food Sweetener Market
Sweeteners
United Kingdom Food Sweetener Market
Sweeteners
Resistant Maltodextrin Market
Sweeteners
Asia-Pacific Low-Calorie Sweeteners Market
Sweeteners
South America Food Sweetener Market
Sweeteners
Canada Food Sweetener Market
Sweeteners
Low-Calorie Sweetener Market
Sweeteners
South America Low-Calorie Sweeteners Market
Sweeteners
Icing Sugar Market
Sweeteners
Organic Palm Sugar Market