
 Glucose-Fructose Syrup (GFS) Market | 2026-2036
Glucose-Fructose Syrup (GFS) Market Size, Share, and Industry Trends Forecast 2026-2036
Glucose-Fructose Syrup (GFS) Market Insights
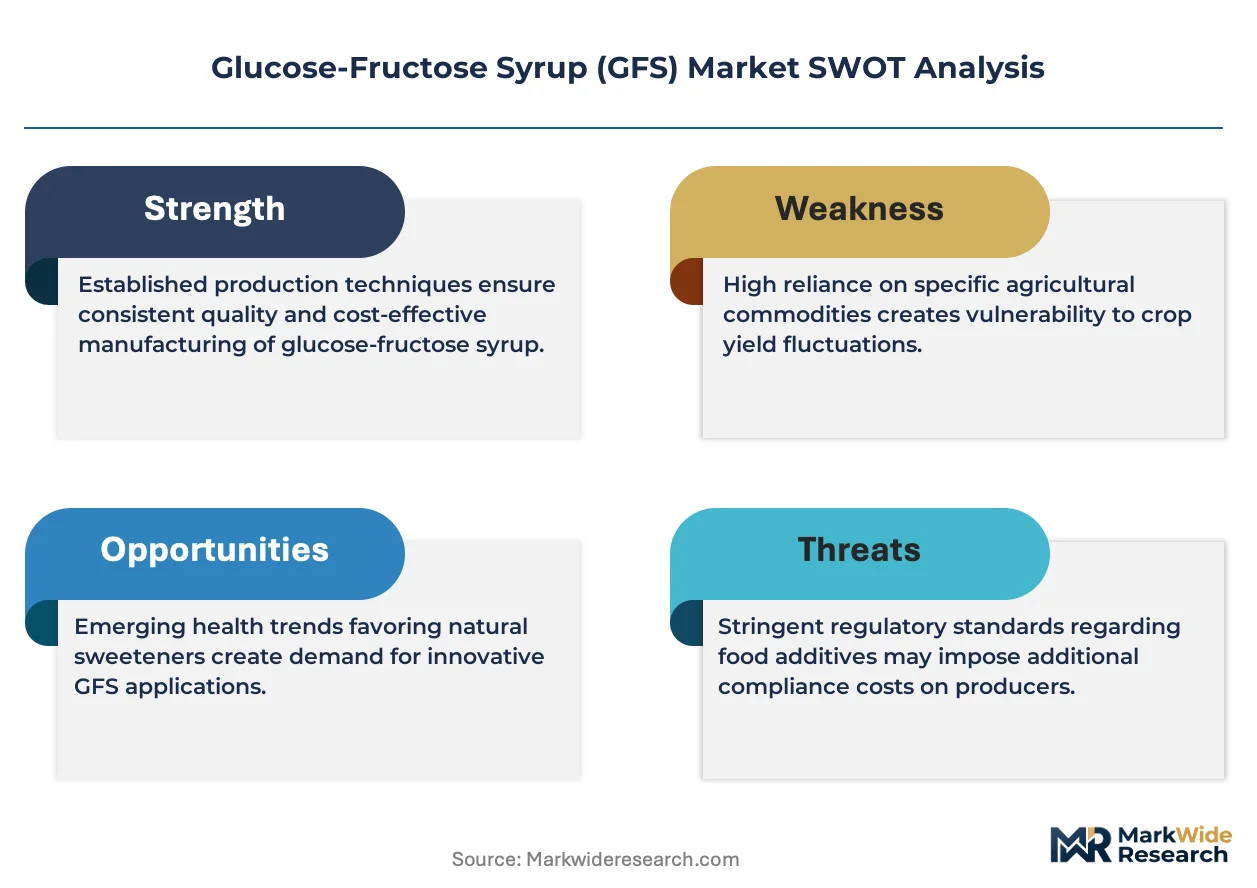
Multi-source starch procurement is pivoting toward vertically integrated supply chains across the GFS industry. Cargill Incorporated leverages its captive corn-milling infrastructure to secure feedstock cost advantages. Südzucker AG anchors European supply through beet-sugar diversification into glucose derivatives. Tate & Lyle PLC competes on specialty-grade formulations for pharmaceutical and premium food applications.
Glucose-Fructose Syrup denotes a starch hydrolysate blend containing glucose and fructose in variable ratios, typically manufactured through enzymatic isomerization of corn or wheat starch at controlled temperature and pH parameters. The product functions primarily as a bulk sweetener, humectant, and freezing-point depressant across processed food systems. High Fructose Corn Syrup occupies the largest volume position within product type segmentation, though Liquid Glucose retains stronger margins in pharmaceutical-grade applications. Food & Beverage end users consume the dominant share of output, while Humectant applications in baked goods represent the fastest-expanding functional segment.
FDA food additive regulations and EPA wastewater discharge standards govern North American production economics, while REACH compliance and EFSA sweetness evaluations shape European formulation choices. The EU Green Deal carbon border adjustments will raise compliance costs for imported starch derivatives entering the European market. Stakeholders must monitor enzymatic processing innovations and regional carbon-accounting rules to preserve margin structures.
Market Dynamics
Enzymatic isomerization efficiency gains and EU carbon border adjustments are compressing legacy processing margins while rewarding facilities with captive starch supply and low-carbon certification. Reformulation mandates from Brussels are forcing capital redeployment toward energy recovery systems and alternative feedstock qualification.
Growth Catalysts
- EU Green Deal carbon accounting:Import tariffs on high-carbon starch derivatives incentivize European manufacturers to source from certified low-emission facilities, accelerating facility upgrades in supplier countries.
- China confectionery output expansion:Domestic starch-processing capacity additions in Shandong and Jilin provinces are securing feedstock for glucose-fructose syrup used in packaged sweets and functional beverages.
- Enzyme immobilization technology:Fixed-bed reactor designs with reusable enzyme carriers are cutting conversion costs and extending catalyst life in high-fructose syrup production lines.
Market Restraints
- Corn price volatility:Drought cycles in US Midwest growing regions transmit directly to input cost instability for maize-based syrup producers without long-term supply contracts.
- EU F-Gas Regulation compliance:Refrigerant phase-down requirements for starch-processing cooling systems impose retrofit capital burdens on facilities using legacy equipment.
- Natural sweetener substitution:Stevia and monk fruit extract formulations in premium beverage segments are capturing label-conscious consumers in North American and Western European markets.
Strategic Opportunities
- India FSSAI sweetener code expansion:Regulatory clarity on glucose-fructose syrup labeling standards opens formulation opportunities in India's processed dairy and traditional sweet categories.
- Pharmaceutical-grade liquid glucose:Injectable and excipient applications command margin premiums five to seven times above food-grade equivalents, rewarding purity investments.
- Bio-based packaging alignment:Syrup producers with ISCC PLUS certification can bundle sweetener supply with carbon footprint documentation for brand owners facing Scope 3 disclosure requirements.
Industry Challenges
- Process engineer scarcity:Specialized expertise in continuous enzymatic systems and membrane filtration operation concentrates among retirees and competing biotech sectors, inflating compensation for qualified hires.
- Multi-jurisdiction certification timelines:Simultaneous FDA food additive petitions, EFSA novel food evaluations, and national regulator approvals for new starch sources extend product launch cycles by eighteen to thirty months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glucose-Fructose Syrup (GFS) Market |
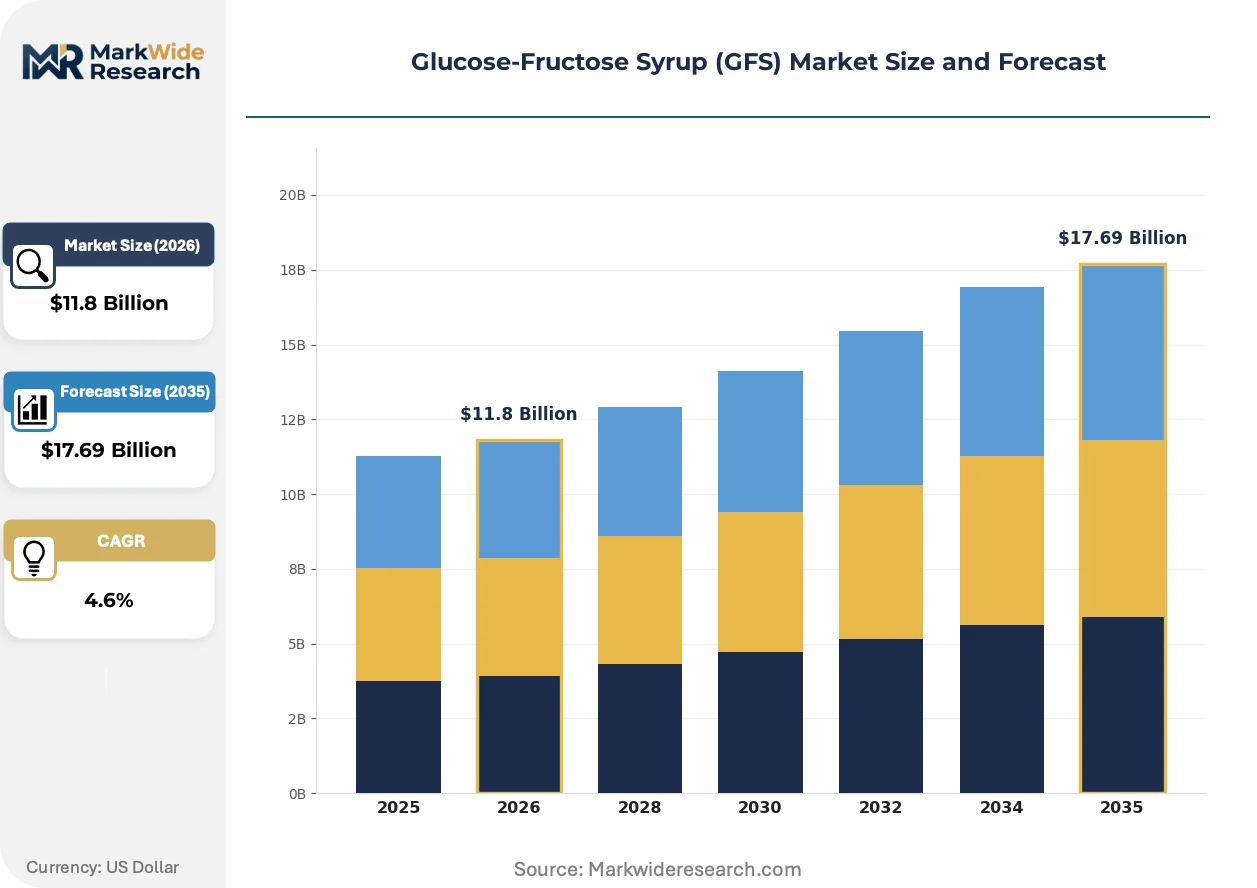
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $17.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Fructose Corn Syrup, Liquid Glucose, Oligosaccharides, Maltodextrin End User: Food & Beverage, Confectionery, Bakery, Dairy Application: Sweetener, Flavor Enhancer, Thickener, Humectant Grade: Food Grade, Industrial Grade, Pharmaceutical Grade, Others |
| Companies Covered | Tate & Lyle PLC, Global Sweeteners Holdings Limited, Cargill Incorporated, Tereos S.A., AGRANA Beteiligungs AG, Archer Daniels Midland Company, Roquette Frères, Südzucker AG, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glucose-Fructose Syrup (GFS) Market Trends and Innovations
Continuous processing architectures and carbon-intensity tracking are displacing batch operations and generic commodity positioning. Facilities that integrate real-time monitoring with certification documentation are capturing preferential offtake from multinational brand owners.
Immobilized enzyme reactor systems with ceramic carrier matrices are rewriting process economics for high-fructose syrup conversion. Beverage manufacturers in Mexico and Indonesia are retrofitting procurement specifications to favor suppliers deploying these systems, compressing margin structures for facilities still operating soluble enzyme batch protocols.
REACH authorization requirements for specific catalyst residues are tightening purity specifications for glucose derivatives entering European cosmetic and pharmaceutical channels. German and Dutch formulators are now requiring third-party testing documentation for every lot, shifting competitive advantage toward integrated producers with in-house analytical capabilities.
Consolidated buying desks at multinational food conglomerates are compressing supplier rosters and extending payment terms. Tier-one syrup procurement in Brazil and Thailand now flows through three-to-five-year framework agreements with volume commitments and indexed pricing, displacing spot market transactions that previously dominated regional trade.
Glucose-Fructose Syrup (GFS) Market Segmentation
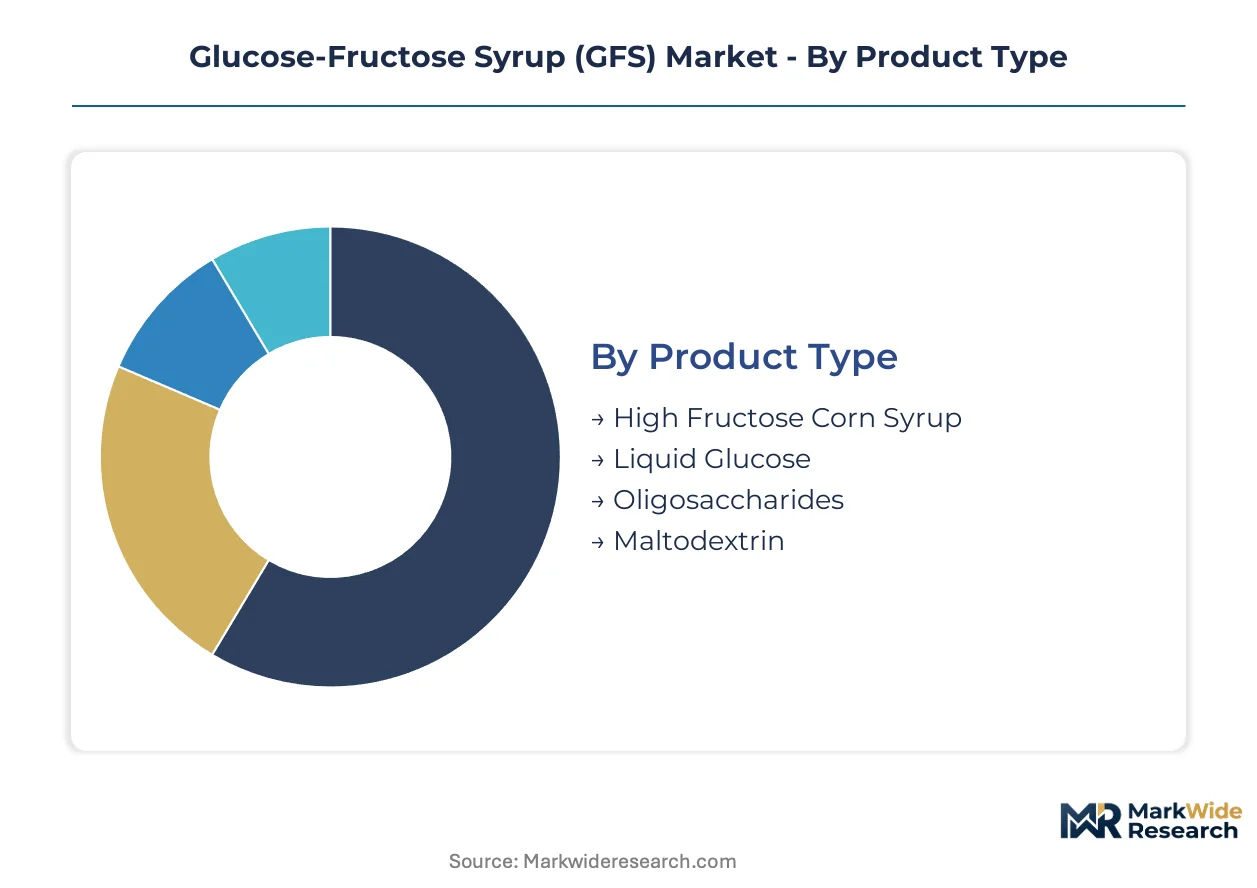
Segmentation in the Glucose-Fructose Syrup market separates bulk commodity flows from precision-formulated specialty streams. Each category carries distinct margin structures, certification requirements, and customer concentration patterns that reshape competitive positioning across supply chains.
Product Type:
Integration depth varies sharply—some syrups ship as standalone sweetener inputs while others embed into compound ingredient systems for downstream formulation.
- High Fructose Corn Syrup:This enzymatically isomerized starch hydrolysate typically contains 42-55% fructose content, optimized for beverage sweetness intensity and freezing-point depression. Carbonated drink bottlers in Mexico and Indonesia are retrofitting procurement specifications to favor suppliers deploying immobilized enzyme reactor systems. The segment absorbs the largest volume flows but faces margin compression from natural sweetener substitution in premium beverage categories.
- Liquid Glucose:A partially hydrolyzed starch syrup with lower dextrose equivalent, valued for viscosity control and moisture retention in baked goods. Injectable and excipient applications in pharmaceutical manufacturing command margin premiums five to seven times above food-grade equivalents. Purity investments here reward producers with in-house analytical capabilities and REACH-compliant documentation.
- Oligosaccharides:Short-chain carbohydrate fractions with prebiotic functional claims, increasingly specified by dairy formulators seeking fiber enrichment labeling.
- Maltodextrin:Spray-dried starch hydrolysate used as carrier and bulking agent in powdered beverage and sports nutrition applications.
Volume placements concentrate in High Fructose Corn Syrup; the faster expansion belongs to Liquid Glucose pharmaceutical grades.
End User:
Customer scale and formulation sophistication create tiered demand patterns—multinational conglomerates negotiate multi-year frameworks while regional processors operate on spot procurement.
- Food & Beverage:The dominant consumption channel spanning carbonated soft drinks, processed juices, and functional beverages. Procurement desks at consolidated multinationals now demand three-to-five-year framework agreements with volume commitments and indexed pricing, displacing spot market transactions in Brazil and Thailand.
- Confectionery:Hard candies, chewing gum, and chocolate formulations requiring precise crystallization control and moisture management. Output expansion in China's Shandong and Jilin provinces is securing dedicated feedstock for glucose-fructose syrup used in packaged sweets.
- Bakery:Bread and pastry applications where humectant properties extend shelf life and improve crumb structure.
- Dairy:Ice cream and flavored milk systems utilizing syrup for freezing-point depression and body enhancement.
Food & Beverage commands the dominant procurement volumes; Confectionery is climbing the fastest on Asia-Pacific capacity expansion.
Application:
Functional role determines specification stringency—sweetener applications tolerate wider parameter bands than pharmaceutical or cosmetic channels.
- Sweetener:Primary caloric contribution in beverages and desserts, with fructose-glucose ratio tuned to sweetness intensity targets. Reformulation mandates from Brussels under EU Green Deal carbon accounting are forcing capital redeployment toward energy recovery systems in production facilities serving this segment.
- Humectant:Moisture retention in baked goods and meat products, representing the fastest-expanding functional segment as clean-label shelf-life extension gains priority. REACH authorization requirements for specific catalyst residues are tightening purity specifications for glucose derivatives entering European cosmetic and pharmaceutical channels.
- Flavor Enhancer:Maillard reaction facilitation and taste modulation in savory and roasted flavor systems.
- Thickener:Viscosity building in sauces, dressings, and confectionery centers without gelatin or starch clouding.
Sweetener applications anchor the volume base; Humectant functionality is gaining share fastest on bakery industry reformulation.
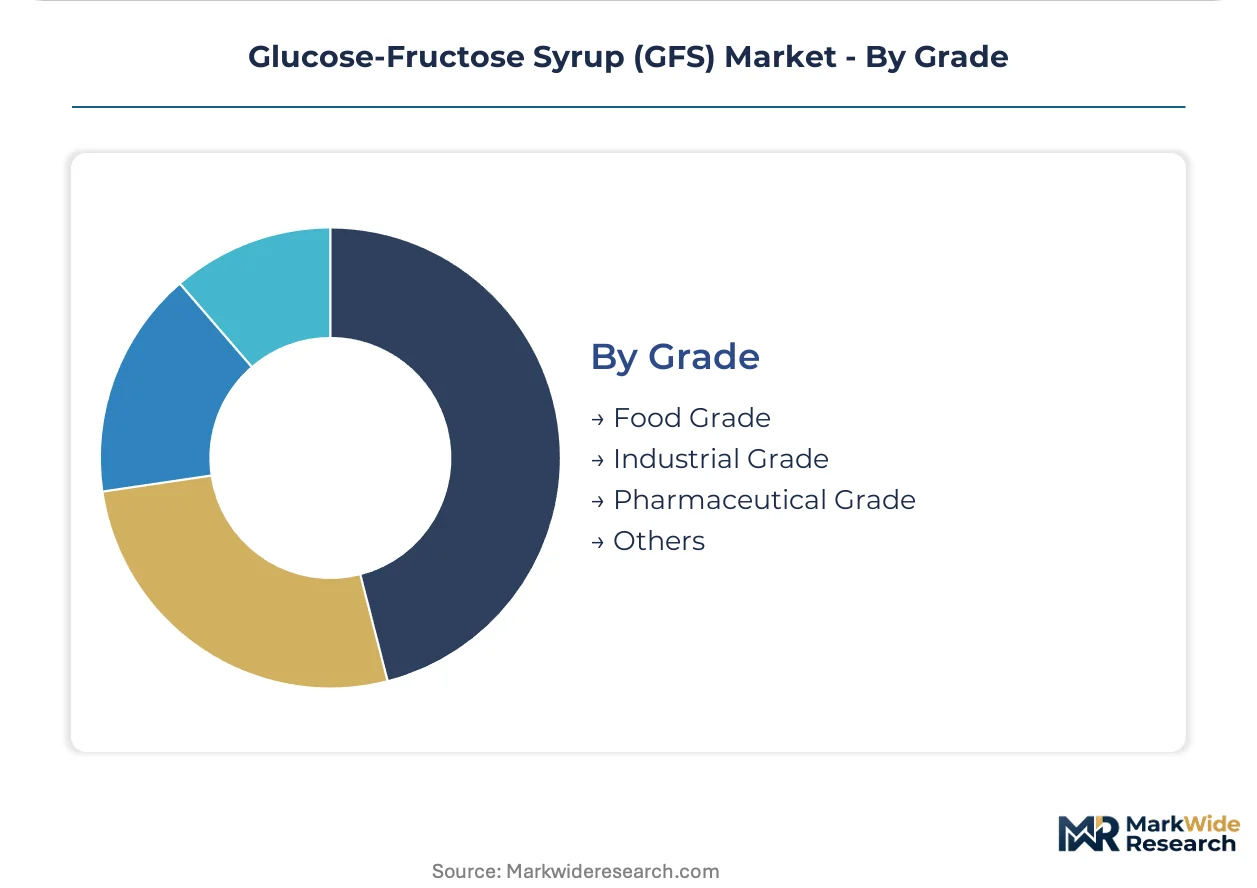
Grade:
Certification tier separates commodity margin pools from specialty premium capture, with analytical documentation requirements escalating sharply across the spectrum.
- Food Grade:Standard specifications for general-purpose sweetening and texturizing, governed by FDA food additive regulations and EPA wastewater discharge standards in North American production economics.
- Pharmaceutical Grade:Injectable and excipient purity standards with lot-specific third-party testing documentation now required by German and Dutch formulators. Multi-jurisdiction certification timelines for new starch sources extend product launch cycles by eighteen to thirty months.
- Industrial Grade:Lower-purity streams for fermentation feedstock and chemical intermediate applications.
- Others:Cosmetic and specialty industrial specifications with customized impurity profiles.
Food Grade shipments dominate tonnage; Pharmaceutical Grade carries the steepest expansion trajectory on purity premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the dominant share of glucose-fructose syrup demand through its starch-processing infrastructure and confectionery manufacturing scale. Procurement patterns across four additional markets reveal how regional regulations and industrial clustering reshape supply chain configurations.
China
Shandong and Jilin provinces anchor starch-processing capacity additions that feed glucose-fructose syrup into packaged sweets and functional beverage production. SAMR enforcement of GB standards on sweetener labeling tightens documentation requirements for both domestic and imported syrup streams. Zhengzhou-based manufacturers cluster around enzymatic conversion facilities serving northern China's dairy and bakery formulators.
United States
Midwest corn-belt concentration supplies maize feedstock to high-fructose syrup producers serving carbonated beverage bottlers and processed food manufacturers. EPA wastewater discharge standards govern production economics at facilities along the Mississippi River corridor. Iowa and Illinois processing plants leverage captive corn-milling infrastructure to manage input cost volatility from drought-exposed growing regions.
Germany
Beet-sugar diversification into glucose derivatives anchors European supply security for pharmaceutical-grade and specialty food applications. EFSA sweetness evaluations and REACH compliance requirements shape formulation choices for exports into cosmetic and pharmaceutical channels. Mannheim and Hamburg harbor zones concentrate refining capacity with integrated analytical laboratories for lot-specific third-party testing documentation.
Brazil
São Paulo-state beverage conglomerates negotiate three-to-five-year framework agreements with volume commitments and indexed pricing that displace spot market transactions. ANVISA sweetener regulations align with Mercosur technical standards for cross-border syrup trade. Campinas industrial corridor hosts blending facilities that distribute into Argentina and Chile through preferential tariff arrangements.
India
Processed dairy and traditional sweet categories drive formulation opportunities as FSSAI clarifies glucose-fructose syrup labeling standards. Maharashtra and Gujarat starch processors expand capacity to serve domestic confectionery and bakery demand previously met through imports. Mumbai-Pune industrial belt concentrates spray-drying infrastructure for maltodextrin and liquid glucose derivatives targeting pharmaceutical excipient specifications.
Glucose-Fructose Syrup (GFS) Market Competitive Landscape
Capacity expansion dominates the current landscape as producers retrofit enzymatic processing lines and secure captive starch supply. The vendor base concentrates among integrated agribusiness conglomerates with backward control over corn and wheat milling, regional beet-sugar processors diversifying into glucose derivatives, and specialty ingredient formulators serving pharmaceutical channels. Three archetypes define competitive positioning: scale-driven commodity suppliers, purity-focused pharmaceutical-grade specialists, and sustainability-certified providers bundling carbon documentation. Geographic expansion through framework agreements and technology licensing for immobilized enzyme systems represent the dominant competitive moves.
Within the integrated agribusiness tier, Cargill Incorporated and Archer Daniels Midland Company exemplify scale-driven positioning through captive corn-milling infrastructure. Tate & Lyle PLC occupies the specialty-grade vector, representing pharmaceutical and premium food application focus. Südzucker AG anchors the European beet-sugar diversification archetype, with glucose derivative production integrated into continental supply security strategies.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Global Sweeteners Holdings Limited |
| Cargill Incorporated |
| Tereos S.A. |
| AGRANA Beteiligungs AG |
| Archer Daniels Midland Company |
| Roquette Frères |
| Südzucker AG |
| Ingredion Incorporated |
| Others |
Pricing and Supply Chain Analysis
Immobilized enzyme reactor systems with ceramic carrier matrices are compressing conversion economics for high-fructose syrup producers while simultaneously concentrating procurement leverage among facilities with capital-intensive retrofit capabilities. Batch operators lacking fixed-bed infrastructure face margin erosion as Mexican and Indonesian beverage manufacturers rewrite supplier specifications to favor continuous-process certification.
Pricing Analysis
Service-bundling now separates certified low-carbon documentation from base commodity quotes, with ISCC PLUS verification and lot-specific analytical reports commanding premium positioning. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade specifications reflects purity investment differentials and REACH compliance overhead. Cost compression in standard food-grade streams is intensifying because consolidated multinational buying desks extend payment terms and demand indexed pricing over three-to-five-year frameworks. Regional processors and spot-market dependent facilities exhibit highest price sensitivity, while injectable-grade pharmaceutical buyers tolerate steep premiums for third-party tested documentation.
Supply Chain Analysis
Regional distribution centers in Campinas, Mannheim harbor zones, and Zhengzhou industrial corridors form hub-and-spoke patterns that aggregate syrup flows from captive starch-processing clusters. Supply concentrates in China, the United States, and Germany, with Shandong province, Iowa corn-belt facilities, and beet-sugar diversification plants in Mannheim anchoring respective regional networks. Raw material dependencies rest on maize feedstock, wheat starch, and beet-sugar processing streams, with enzyme catalyst supply and refrigerant systems for cooling loops as critical production inputs. Single-source vulnerability in specialized enzyme carrier manufacturing creates chokepoint exposure for immobilized reactor operators. Distribution runs through framework agreements with volume commitments, displacing spot transactions across Brazil, Thailand, and Indonesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized process engineer scarcity and eighteen-to-thirty-month multi-jurisdiction certification timelines constrain capacity expansion, propping pricing power for incumbent producers with qualified technical staff and existing regulatory approvals.
For Market Incumbents: Extend analytical laboratory capabilities to capture pharmaceutical-grade documentation premiums, while securing captive starch supply through backward integration into corn-milling or beet-processing infrastructure. Natural sweetener substitution in North American premium beverages and EU F-Gas Regulation retrofit requirements threaten legacy margin pools; enzyme immobilization technology licensing offers defensive revenue streams.
For New Entrants and Emerging Players: FSSAI sweetener code expansion in India opens a window for formulation partnerships in processed dairy and traditional sweet categories previously constrained by regulatory ambiguity. White-space targets include pharmaceutical excipient specifications in Maharashtra-Gujarat corridor and ISCC PLUS-certified supply bundles for brand owners facing Scope 3 disclosure requirements. Go-to-market positioning through carbon-accounting documentation bundling differentiates against commodity incumbents.
For Investors and Strategic Acquirers: Re-rating potential sits with pharmaceutical-grade specialists given REACH authorization requirements and German-Dutch formulator demand for lot-specific testing documentation. Long-term viability favors integrated producers with in-house analytical capabilities and low-carbon certification infrastructure. Watch enzyme immobilization technology adoption rates as inflection indicator for competitive cost positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Immobilized Enzyme Reactor Deployment | Fixed-bed ceramic carrier systems cut conversion costs and extend catalyst life for high-fructose syrup lines. |
| Pharmaceutical-Grade Purity Investment | Injectable and excipient specifications command five-to-seven-fold margin premiums over food-grade equivalents. |
| ISCC PLUS Certification Acquisition | Carbon footprint documentation bundles meet multinational brand owner Scope 3 disclosure requirements. |
| Captive Starch Supply Integration | Backward control over corn-milling or beet-processing secures feedstock cost advantages against drought volatility. |
| Multi-Jurisdiction Regulatory Approval | Simultaneous FDA, EFSA, and national regulator clearances extend product launch cycles but lock out competitors. |
Research Methodology
Independent corroboration across regulatory filings, customs trade databases, and industry association publications underwrites the qualitative findings presented in this study. Primary interviews with plant managers at enzymatic conversion facilities, procurement leads at beverage conglomerates, technical R&D directors in starch processing, and distribution channel partners in key supply corridors informed operational and competitive assessments. Secondary validation drew from EPA wastewater discharge records, EFSA sweetness evaluations, SAMR GB standard enforcement reports, and SEC filings of publicly traded agribusiness conglomerates. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic and regulatory scenario analysis.
Rate-of-change decomposition across volume and value dimensions structured the analytical framework over the projection horizon. Segmentation modeling captured product type tiers, end-user industry concentrations, functional application roles, and certification grade specifications alongside regional production hub clustering. CAGRs derived from fitted growth curves applied to disclosed capacity expansions, import-export flow analysis, and end-use demand elasticity parameters. Forecast inputs incorporated enzyme technology adoption trajectories, EU carbon border adjustment implementation schedules, and FSSAI regulatory clarity timelines.
The model assumes a particular technology adoption path; alternative pathways for immobilized enzyme reactor diffusion or natural sweetener substitution acceleration would alter the outlook. Forecasts reflect documented assumptions regarding starch feedstock availability, regulatory enforcement intensity, and certification uptake rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Maltitol Market
Sweeteners
South America Stevia Market
Sweeteners
Natural Malt Sweeteners Market
Sweeteners
Low-Fat Sugar Market
Sweeteners
Dextrates Market
Sweeteners
Japan Allulose Market
Sweeteners
Italy Food Sweetener Market
Sweeteners
Muscovado Sugar Market
Sweeteners
Sugar Syrups Market
Sweeteners
Isomaltulose Market
Sweeteners
Digestion Resistant Maltodextrin Market
Sweeteners
Agave Nectar Market
Sweeteners
Crystalline Fructose Market
Sweeteners
Low-Calorie Sweetener Market
Sweeteners
Europe Low-Calorie Sweeteners Market
Sweeteners
Galactose Market