
 Agave Syrup Market | 2026-2036
Agave Syrup Market Size, Share, and Industry Trends Forecast 2026-2036
Agave Syrup Market Analysis
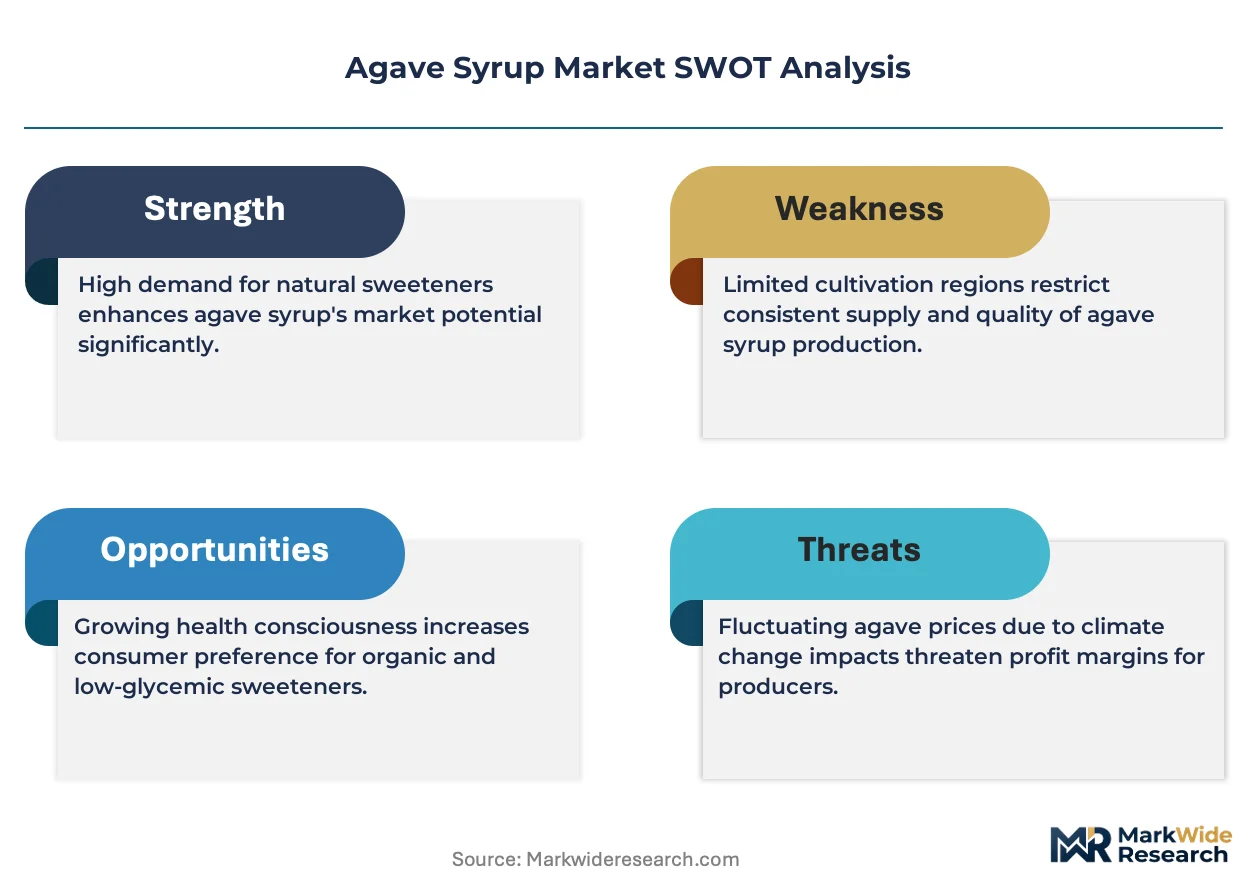
Private-label formulation services is rewriting margin distribution across the agave syrup value chain, pulling profitability away from bulk commodity trading and toward customized blending and flavor-profile development. Madhava Natural Sweeteners leverages its vertical integration from Jalisco farming cooperatives through U.S. bottling facilities to capture value at multiple stages. The Hain Celestial Group anchors its position through shelf-space dominance in North American natural grocery channels. Sisana Sweeteners differentiates via organic certification depth and European distribution partnerships.
Agave syrup is a viscous liquid sweetener extracted from the core of Agave tequilana and related species, containing primarily fructose and glucose with a glycemic index lower than sucrose, produced through enzymatic hydrolysis of inulin-rich sap followed by filtration and thermal concentration. Its primary commercial purpose is to serve as a clean-label sweetener in beverages, baked goods, and condiments where manufacturers seek to reduce refined sugar content while maintaining solubility and browning characteristics. Organic agave syrup commands premium positioning as consumers scrutinize pesticide residues and farming practices, while light agave syrup dominates volume in beverage applications due to its neutral flavor profile and minimal color contribution. Dark agave syrup occupies a smaller but expanding niche in craft baking and sauce formulations where caramel notes add product differentiation.
The U.S. FDA governs agave syrup labeling under its sweetener and food additive frameworks, while Mexico's Ministry of Economy enforces denomination-of-origin protections that restrict "agave" labeling to products sourced from designated Mexican states. These regulatory structures shape import documentation burdens, organic certification requirements, and competitive access for non-Mexican suppliers attempting market entry. Stakeholders must monitor evolving clean-label enforcement patterns and denomination-of-origin expansion negotiations to anticipate supply constraints and pricing volatility in certified grades.
Market Dynamics
Clean-label beverage reformulation is compressing procurement cycles for certified organic agave grades, forcing manufacturers to pre-qualify Mexican-origin suppliers before Mexico's Ministry of Economy completes denomination-of-origin documentation audits.
Growth Catalysts
- Denominator-of-Origin Enforcement:Mexico's Ministry of Economy tightened provenance verification rules, compelling U.S. beverage manufacturers to document Jalisco and Guanajuato sourcing. This regulatory pressure accelerates formal channel migration away from undocumented suppliers.
- Functional Beverage Expansion:Carbonated and functional drink producers now specify light agave syrup for its neutral flavor profile and low glycemic index positioning. This end-use vertical absorbs volume previously allocated to high-fructose corn syrup.
- Enzymatic Hydrolysis Refinement:Filtered inulin-to-fructose conversion technology reduces thermal degradation and color formation. Producers capture premium positioning through cleaner sensory profiles in organic certification tiers.
Market Restraints
- Blue Agave Supply Concentration:Over 80% of certified cultivation sits within Jalisco's designated municipalities. Climate stress and harvest-cycle timing create recurring raw material volatility for processors lacking multi-year cooperative contracts.
- Input Cost Escalation:Organic certification compliance, water access fees, and labor-intensive jimador harvesting inflate farmgate pricing. These structural cost layers compress margins for traders without backward integration into farming cooperatives.
- Refined Sugar Substitution Economics:Sucrose and beet sugar maintain 60-70% cost advantages in bulk industrial applications. Price-sensitive bakery and confectionery segments retain conventional sweeteners despite clean-label pressure from retail channels.
Strategic Opportunities
- European Distribution Gap:Organic certification depth remains underdeveloped in German and Scandinavian retail channels. Producers with dual EU-organic and USDA-organic credentials access shelf-space expansion in natural grocery formats.
- Dark Grade Sauce Formulation:Caramel-note agave variants penetrate craft barbecue and hot sauce segments. These applications command 25-40% price premiums over light grades through flavor differentiation.
- IRA Clean Energy Alignment:U.S. biofuel tax incentives for renewable feedstocks create alternative offtake pathways for agave processing byproducts. Distillers and syrup producers monetize bagasse and spent agave through biogas or cellulosic ethanol channels.
Industry Challenges
- Organic Certification Timeline Compression:USDA National Organic Program transition periods and Mexico's organic equivalence verification create 18-24 month approval windows. New entrants face working capital strain during pre-revenue qualification phases.
- Jimador Skill Scarcity:Traditional agave harvesting requires manual piña extraction expertise that resists mechanization. Aging practitioner populations in Jalisco constrain harvest throughput during peak seasonal windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agave Syrup Market |
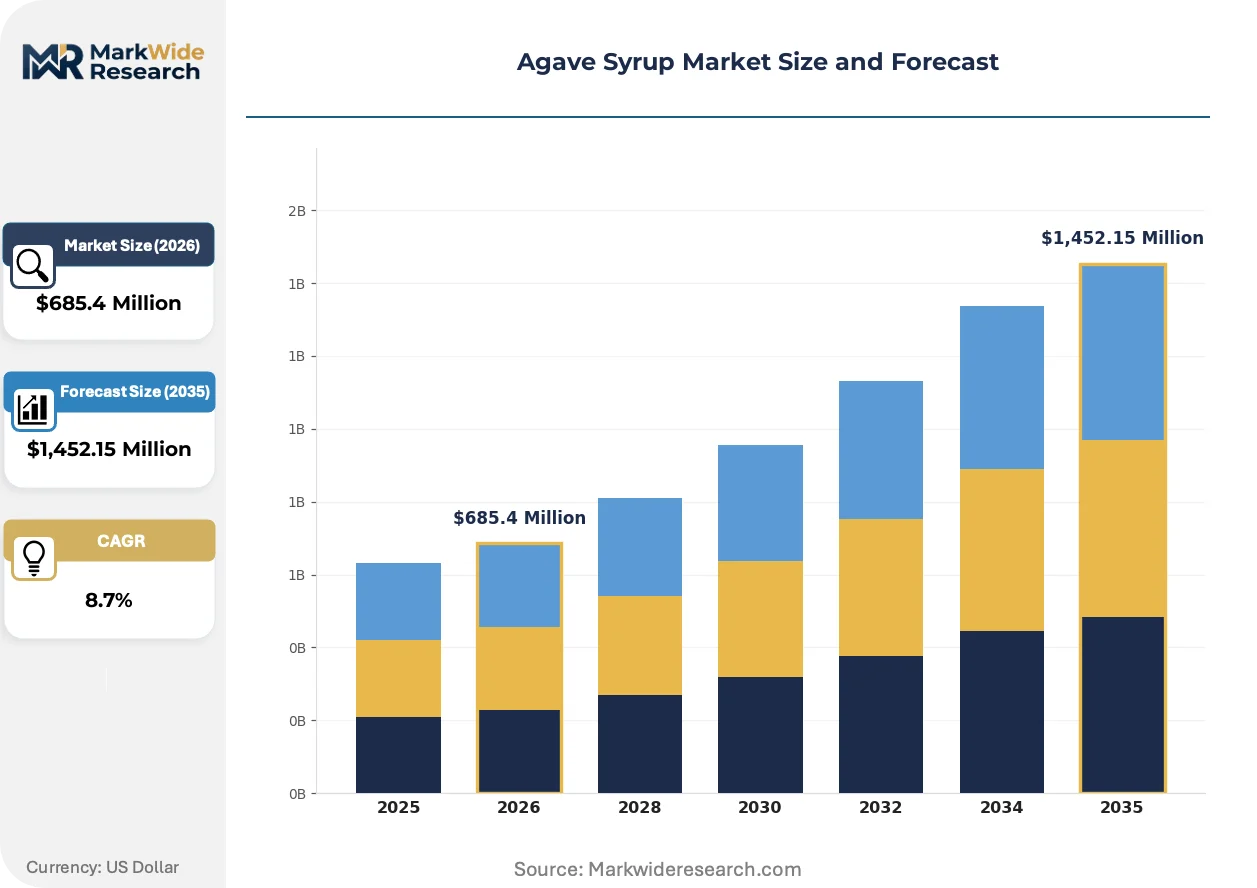
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Agave Syrup, Raw Agave Syrup, Light Agave Syrup, Dark Agave Syrup End Use: Beverages, Bakery, Desserts, Sauces Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Wholesale Packaging Type: Bottles, Jars, Bulk Containers, Tetra Packs |
| Companies Covered | Madhava Natural Sweeteners, Malt Products Corporation, The IIDEA Company, Wholesome Sweeteners Inc., Agave Sweetener Company, Dandy Lions Limited, Sisana Sweeteners, The Hain Celestial Group, SunOpta Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agave Syrup Market Emerging Trajectories
Processing technology and regulatory documentation requirements are restructuring competitive advantage around provenance verification and enzymatic efficiency rather than commodity scale.
Membrane filtration systems are migrating from thermal concentration methods in premium agave syrup production. Beverage manufacturers with dedicated clean-label lines specify sub-50°C processing to preserve fructose integrity and avoid Maillard browning. This technology shift compresses acceptable supplier pools to processors with capital-intensive cold-chain infrastructure.
REACH chemical registration requirements in Europe now capture agave-derived inulin extracts imported for functional food applications. EFSA novel food consultations extend market entry timelines for hydrolyzed agave fiber ingredients. German and Dutch importers are consolidating procurement through pre-registered suppliers to avoid batch-by-batch customs detention.
Certification-driven preference shifts now dominate North American retail procurement. Natural grocery chains mandate third-party organic and non-GMO verification before shelf placement. Private-label formulation services capture margin previously retained by bulk commodity traders through customized brix specifications and flavor-profile matching.
Agave Syrup Market Segmentation
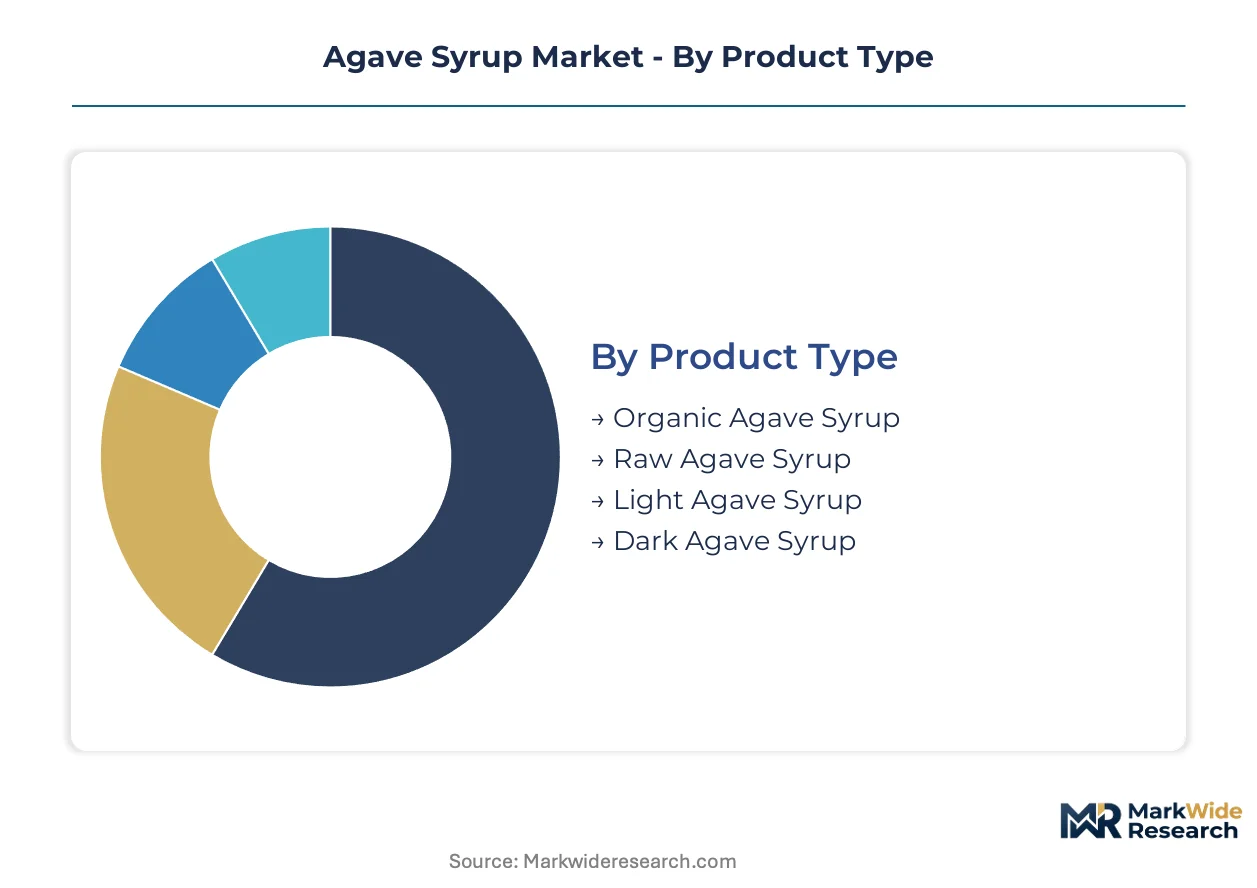
Segmentation in the agave syrup market reveals how certification grades, end-use specifications, and channel economics create divergent margin pools. Manufacturers must align production assets with the precise technical and documentation requirements of each segment tier.
Product Type:
Mature commodity grades compete alongside emerging premium certifications for shelf space and procurement contracts.
- Organic Agave Syrup:USDA National Organic Program certification requires three-year transition periods for Jalisco farmland and prohibits synthetic pesticide use. U.S. beverage manufacturers now mandate this grade for clean-label reformulation, with Mexico's Ministry of Economy denomination-of-origin audits adding documentation layers that filter out non-compliant suppliers.
- Light Agave Syrup:Minimal thermal processing preserves neutral flavor and water-white color through sub-50°C membrane filtration. Carbonated and functional drink producers specify this grade for its solubility and non-competing taste profile, displacing high-fructose corn syrup in volume terms.
- Raw Agave Syrup:Enzymatic hydrolysis at temperatures below 45°C retains inulin fragments and trace minerals for raw-food positioning.
- Dark Agave Syrup:Extended thermal concentration develops Maillard reaction products and caramel notes for craft baking applications.
Light agave syrup retains volume leadership; organic agave syrup holds the steepest expansion curve.
End Use:
Application-driven procurement cycles separate high-velocity beverage specifications from lower-frequency food manufacturing orders.
- Beverages:Carbonated soft drinks, functional waters, and ready-to-drink teas specify light agave for brix consistency and cold-solubility. Reformulation timelines compressed by clean-label retail mandates force pre-qualified Mexican supplier relationships.
- Bakery:Browning reaction requirements and moisture retention specifications favor dark agave grades in artisan bread and cookie production.
- Desserts:Frozen dairy and confection applications balance sweetness intensity with freezing-point depression.
- Sauces:Viscosity and sheen requirements in barbecue and hot sauce formulations create niche demand for caramel-note variants.
Beverage applications absorb the largest procurement volumes; sauce formulations generate the highest per-unit premiums.
Distribution Channel:
Channel structure determines documentation burdens, with direct wholesale requiring provenance verification that retail intermediaries often absorb.
- Wholesale:Bulk tanker and drum shipments to beverage manufacturers and food processors demand batch-level organic certificates and Mexico Ministry of Economy export permits. Direct relationships with Jalisco processing cooperatives bypass distributor markups but require dedicated logistics infrastructure.
- Supermarkets:Natural grocery chains mandate third-party non-GMO verification and shelf-stable packaging formats for center-store placement.
- Health Food Stores:Smaller case volumes with higher service expectations for raw and specialty grades.
- Online Retail:Direct-to-consumer bottles and subscription formats emphasize origin storytelling and subscription economics.
Wholesale channels move the greatest tonnage; online retail posts the most rapid growth trajectory.
Packaging Type:
Packaging economics separate industrial efficiency from retail presentation requirements.
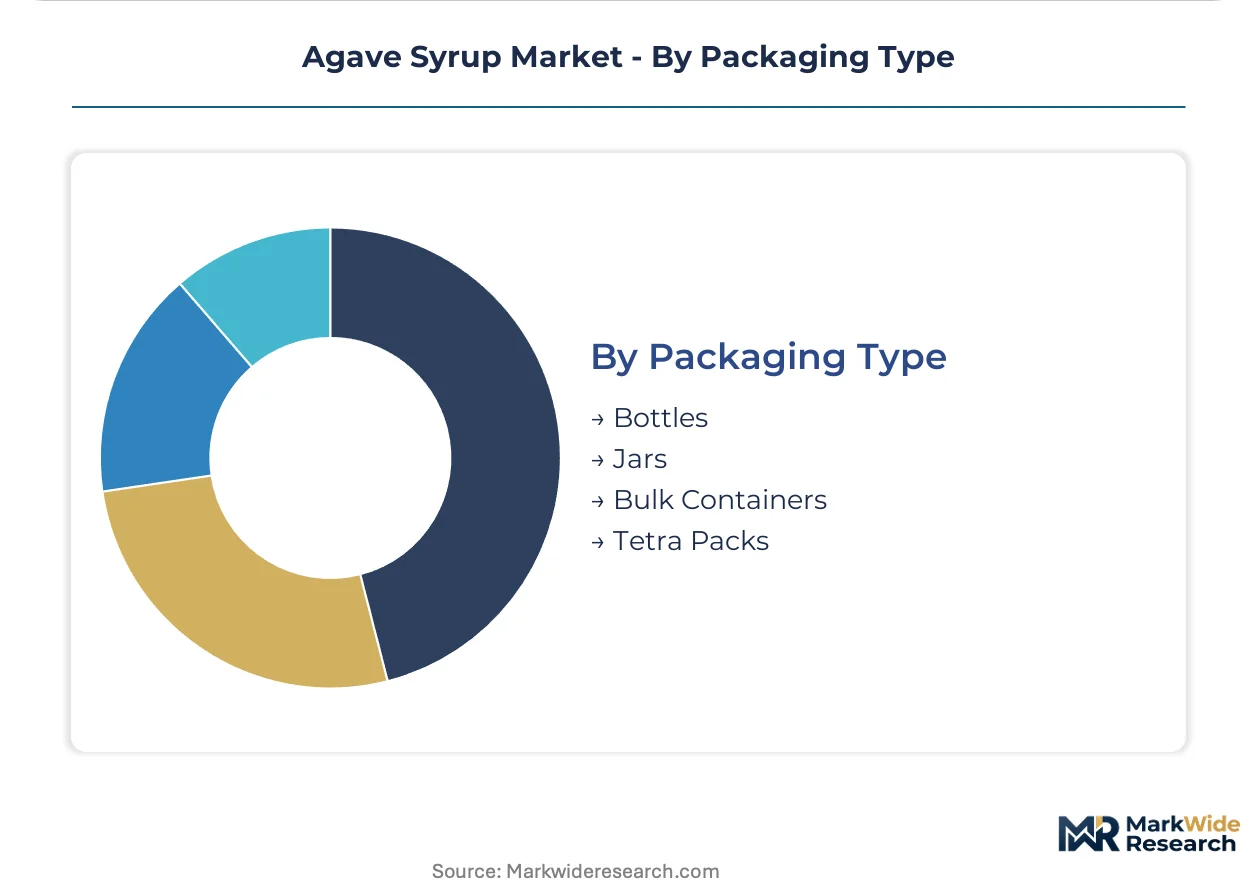
- Bulk Containers:Intermediate bulk containers and stainless steel totes serve beverage manufacturers with dedicated filling lines. Returnable container programs with Jalisco processors reduce per-unit packaging costs for high-volume buyers.
- Bottles:PET and glass formats for retail shelves require label compliance with FDA sweetener classification and organic seal placement.
- Jars:Wide-mouth glass for spoonable applications in baking and breakfast segments.
- Tetra Packs:Aseptic cartons for foodservice and institutional volumes with extended ambient shelf life.
Bulk containers dominate procurement by weight; bottles capture the widest retail penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States prioritizes clean-label beverage reformulation with certified organic grades, while European buyers emphasize REACH-registered inulin extracts for functional food applications. Mexico's domestic market absorbs dark agave grades for traditional culinary uses distinct from export specifications.
United States
Beverage manufacturers in California and Texas drive procurement of light agave syrup for carbonated drink reformulation. The FDA governs sweetener labeling frameworks that mandate ingredient disclosure for high-fructose positioning. Los Angeles and Austin processing clusters handle bulk importation from Jalisco cooperatives with dedicated organic certification pipelines.
Mexico
Jalisco's designated municipalities concentrate over 80% of certified blue agave cultivation for syrup and tequila dual-use. The Ministry of Economy enforces denomination-of-origin rules that restrict "agave" labeling to products sourced from specific states. Guadalajara anchors processing infrastructure where enzymatic hydrolysis facilities convert inulin-rich sap to finished syrup grades.
Germany
Natural grocery chains in Berlin and Hamburg mandate dual EU-organic and USDA-organic credentials for shelf placement. REACH chemical registration requirements capture agave-derived inulin extracts, extending market entry timelines through EFSA novel food consultations. Munich-based importers consolidate procurement through pre-registered suppliers to avoid customs detention.
United Kingdom
London's specialty food distributors emphasize origin storytelling for premium dark agave grades targeting craft baking segments. The Food Standards Agency applies retained EU novel food regulations to hydrolyzed agave fiber ingredients. Manchester processing facilities blend Mexican-origin syrup with local packaging for retail private-label contracts.
Canada
Health Canada and the PMRA govern pesticide residue limits for imported organic agave through the Safe Food for Canadians Regulations. Toronto and Vancouver natural product distributors specify non-GMO verification for center-store placement. British Columbia beverage startups specify raw agave grades for functional drink positioning below 45°C processing thresholds.
Agave Syrup Market Vendor Landscape
Capability concentration sits with vertically integrated processors controlling Jalisco farming cooperatives; scale advantage sits with North American natural grocery channel anchors with shelf-space dominance. The vendor base structures across three tiers: organic-certified specialists with Mexican-origin documentation, private-label formulation services with customized blending capacity, and commodity traders lacking backward integration. Dominant competitive moves include strategic partnerships with Jalisco processing cooperatives and portfolio diversification into dark agave grades for sauce formulation premiums.
Within the vertically integrated tier, Madhava Natural Sweeteners exemplifies cooperative-backed supply chain control from Jalisco through U.S. bottling infrastructure. The Hain Celestial Group occupies a position as a natural grocery channel anchor with North American shelf-space concentration. Sisana Sweeteners represents the European-facing archetype through organic certification depth and distribution partnerships in German and Scandinavian markets.
| Leading Market Players |
|---|
| Madhava Natural Sweeteners |
| Malt Products Corporation |
| The IIDEA Company |
| Wholesome Sweeteners Inc. |
| Agave Sweetener Company |
| Dandy Lions Limited |
| Sisana Sweeteners |
| The Hain Celestial Group |
| SunOpta Inc. |
| Others |
Supply Flow & Price Mechanics
Jalisco-to-Houston freight corridors absorb rising fuel surcharges and customs documentation costs, compressing margins for processors lacking cooperative-backed supply contracts while amplifying price spreads between certified organic and conventional agave syrup grades.
Pricing Analysis
Long-term offtake contracts with Jalisco farming cooperatives dominate procurement for North American beverage manufacturers, locking in volume commitments against spot-market volatility. Three-tier pricing structure across organic-certified premium, conventional light-grade standard, and dark-grade economy levels separates buyers by documentation burden and thermal processing intensity. Pricing pressure stems from organic certification compliance costs and water access fees inflating farmgate baselines. Carbonated drink producers exhibit highest price sensitivity due to high-fructose corn syrup substitution economics, while craft sauce formulators absorb premiums for caramel-note dark grades.
Supply Chain Analysis
Contract manufacturing concentration sits with Jalisco-based enzymatic hydrolysis facilities and Guadalajara-area thermal concentration processors holding certified organic capacity. Raw agave piña supply draws from Jalisco, Guanajuato, and Michoacán cultivation zones under Mexico's denomination-of-origin enforcement. Supply chain risk centers on single-source vulnerability from jimador labor scarcity constraining harvest throughput during peak seasonal windows. Distribution runs through direct wholesale tanker shipments to U.S. beverage bottling clusters and natural grocery channel intermediaries demanding third-party verification documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label beverage reformulation represents an early-cycle expansion story, with functional drink penetration creating dedicated procurement channels that outpace conventional sweetener displacement timelines.
For Market Incumbents: Harden cooperative contract structures with Jalisco farming collectives against climate-stress harvest volatility. Deepen enzymatic hydrolysis capacity for sub-50°C membrane filtration specifications that beverage manufacturers now mandate. Secure shelf-space anchor positions in natural grocery channels before private-label formulation services capture margin migration.
For New Entrants and Emerging Players: Establish a beachhead in German and Scandinavian natural grocery channels where dual EU-organic and USDA-organic credentials remain underdeveloped. Target dark agave sauce formulation segments commanding flavor-differentiation premiums over light grades. Pursue co-manufacturing partnerships with REACH-registered European importers to bypass EFSA novel food consultation delays.
For Investors and Strategic Acquirers: Mexico's Ministry of Economy denomination-of-origin audit expansion reshapes the acquisition landscape toward documented provenance capabilities. Vertically integrated processors with Jalisco cooperative relationships offer superior long-term viability against commodity traders lacking backward integration. Watch for organic certification timeline compression signals indicating working capital strain among pre-revenue entrants.
| Strategic Initiative | Industry Significance |
|---|---|
| Cooperative Contract Structuring | Multi-year agreements with Jalisco farming collectives lock in raw material access against harvest volatility. |
| Cold-Chain Processing Investment | Sub-50°C membrane filtration capacity captures beverage manufacturer specifications for clean-label lines. |
| Dual Organic Certification | USDA-EU organic credentials unlock German and Scandinavian natural grocery shelf placement. |
| Dark Grade Formulation Development | Caramel-note variants penetrate craft barbecue and hot sauce segments at 25-40% price premiums. |
| REACH Registration Completion | Pre-registered inulin extract status avoids EFSA novel food delays and German customs detention. |
Methodological Framework
Cross-validation between executive interviews and trade documentation anchors the qualitative findings. Primary fieldwork engaged beverage formulation directors, natural grocery category buyers, Jalisco cooperative managers, FDA regulatory affairs specialists, and Mexican Ministry of Economy export certification officers. Secondary sources incorporated FDA sweetener labeling guidance, Mexico's denomination-of-origin registry filings, EFSA novel food consultation records, and USDA National Organic Program transition databases. Bottom-up volume modeling triangulated against top-down consumption estimates across certification tiers.
Calibration against historical price spreads and import volume trajectories refined projection outputs across the analysis window. Segmentation dimensions spanned organic certification grade, thermal processing intensity, end-use application, and distribution channel documentation burden. CAGRs derived from trend extrapolation of clean-label reformulation adoption curves and functional beverage launch velocities. Industry-specific inputs included jimador labor availability indices and Jalisco rainfall pattern correlations.
Stress conditions across organic certification approval timelines, jimador workforce attrition, and EU REACH registration delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about clean-label retail mandate enforcement intensity and denomination-of-origin audit expansion scope. Quarterly review of FDA sweetener classification updates and Mexico Ministry of Economy export permit processing times is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Australia Food Sweetener Market
Sweeteners
Beetroot Molasses Market
Sweeteners
Australia Allulose Market
Sweeteners
Brazil Food Sweetener Market
Sweeteners
Digestion Resistant Maltodextrin Market
Sweeteners
Dry Molasses Market
Sweeteners
Monk Fruit Sugar Market
Sweeteners
Africa and Middle East Sugarcane Syrup Market
Sweeteners
North America Sugar Substitutes Market
Sweeteners
Europe Food Sweetener Market
Sweeteners
Tagatose Market
Sweeteners
Natural Stevia Market
Sweeteners
High-Intensity Sweeteners Market
Sweeteners
North America Starch Sweetener Market
Sweeteners
Stevia Market
Sweeteners
Global Cane Molasses Market