
 United States Food Sweetener Market | 2026-2036
United States Food Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
United States Food Sweetener Market Analytics
Foodservice distribution is narrowing as large institutional buyers consolidate procurement contracts around fewer approved suppliers. Tate & Lyle PLC leverages its specialty sweetener portfolio to secure preferred vendor status with major quick-service restaurant chains. Cargill, Incorporated anchors Midwest supply security through its integrated corn wet milling and stevia extraction infrastructure. Südzucker AG competes via refined sugar logistics dominance along Eastern seaboard port terminals.
Food sweeteners encompass caloric and non-caloric substances added to food and beverage matrices to impart sweetness, typically measured by sucrose equivalence values and thermal stability profiles under pasteurization conditions. These compounds function as flavor modulators, preservation aids, and bulking agents across industrial food manufacturing. Sucrose and high fructose corn syrup retain volume leadership in beverages and confectionery applications, though margin compression intensifies in these mature categories. Aspartame occupies a contracting but defended position in carbonated soft drinks as label-conscious consumers migrate toward stevia and monk fruit alternatives. Granular and liquid forms dominate industrial procurement, with powdered formats gaining traction in bakery dry mixes.
The FDA governs sweetener safety through GRAS determinations and food additive petitions, while the USDA administers sugar import quotas and domestic price support mechanisms that constrain supply elasticity. The EPA regulates corn wet milling effluent discharge, directly affecting high fructose corn syrup production economics in Iowa and Illinois processing zones. State-level sugar-sweetened beverage taxes in Philadelphia, Seattle, and San Francisco are fragmenting demand patterns and accelerating reformulation timelines. Stakeholders must monitor pending FDA guidance on allulose labeling and the USDA's biennial sugar program reauthorization to calibrate capacity investments and sweetener blend strategies.
Market Dynamics
The FDA's added sugars line-item disclosure on nutrition labels is forcing beverage and packaged food manufacturers to accelerate reformulation timelines, compressing supplier qualification cycles and reshaping procurement criteria across the sweetener value chain.
Growth Catalysts
- Clean-label mandates:USDA school meal nutrition standards are driving K-12 foodservice operators toward naturally derived alternatives, expanding stevia and monk fruit procurement volumes.
- Beverage reformulation clusters:California's Los Angeles and San Francisco Bay Area innovation hubs concentrate plant-based and reduced-sugar product development, generating concentrated demand for specialty sweetener technical support.
- State-level tax incentives:Philadelphia, Seattle, and San Francisco sugar-sweetened beverage taxes are accelerating manufacturer transitions to low-calorie blends ahead of federal action.
Market Restraints
- Corn wet milling concentration:High fructose corn syrup production clusters in Iowa and Illinois processing zones, creating geographic supply vulnerability to EPA effluent discharge enforcement actions.
- Stevia leaf supply volatility:Raw material sourcing depends on concentrated cultivation regions subject to climate variability and agricultural input cost swings.
- GRAS petition timelines:FDA novel sweetener safety determinations extend 18-36 months, freezing commercialization pathways for emerging fermentation-derived compounds.
Strategic Opportunities
- Allulose regulatory clarity:Pending FDA guidance on reduced-calorie labeling would unlock bakery and confectionery applications currently constrained by carbohydrate counting ambiguity.
- Midwest co-manufacturing partnerships:Cargill's integrated corn wet milling and stevia extraction infrastructure creates captive supply opportunities for regional brand owners seeking supply security.
- Foodservice distributor consolidation:Narrowing approved supplier lists at major quick-service restaurant chains create preferred vendor positions for specialty sweetener portfolios with technical service capabilities.
Industry Challenges
- Reformulation technical gaps:Beverage manufacturers struggle to replicate sucrose mouthfeel and bulking functions in reduced-sugar matrices without process engineering investments.
- Dual certification complexity:Organic and non-GMO verification requirements for clean-label positioning extend supplier audit timelines and fragment procurement pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Food Sweetener Market |
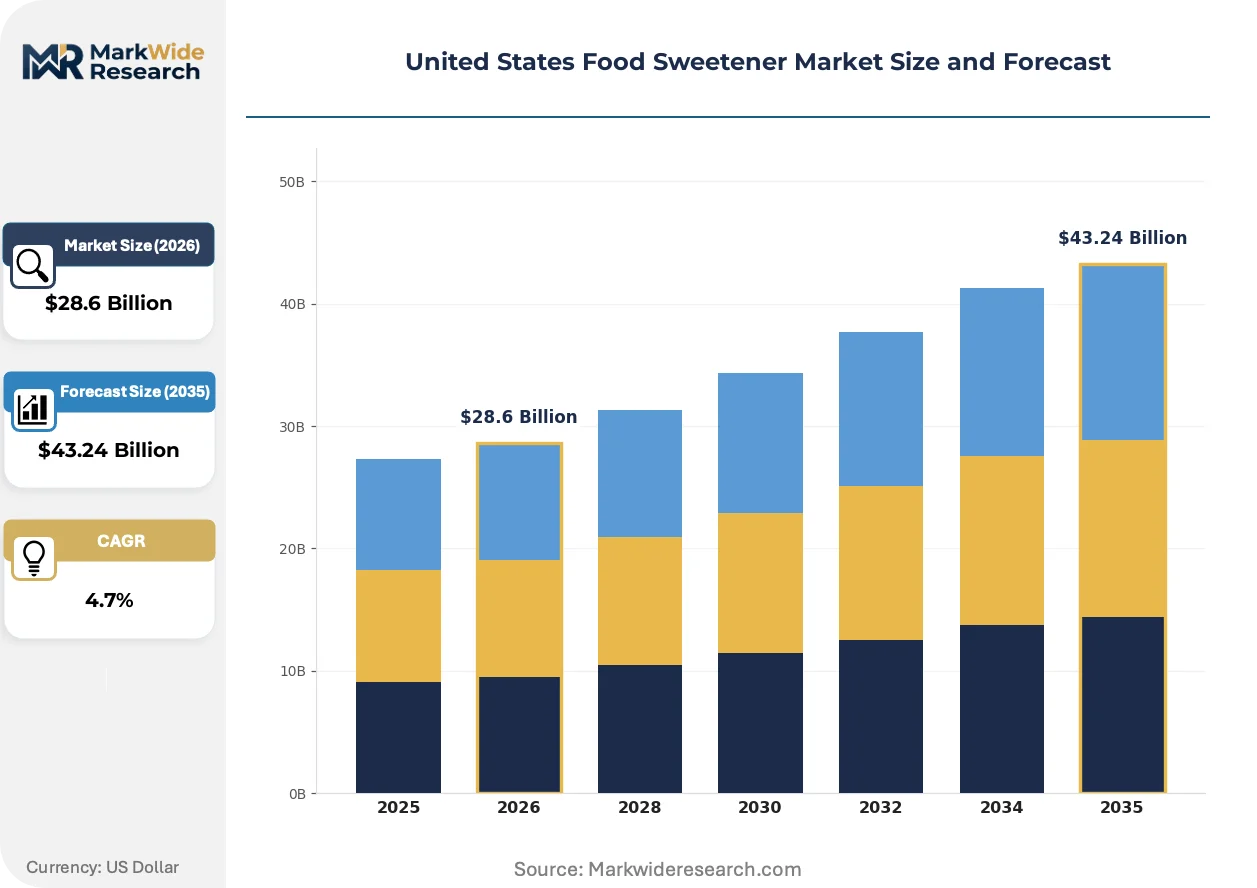
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sucrose, Glucose, High Fructose Corn Syrup, Aspartame Application: Beverages, Bakery, Dairy Products, Confectionery Form: Granular, Liquid, Powdered, Syrup Customer Type: Retail, Food Service, Industrial, Home Use |
| Companies Covered | Tate & Lyle PLC, Südzucker AG, Cargill, Incorporated, Ajinomoto Co. Inc., Roquette Frères, Archer Daniels Midland Company, ASR Group International, Inc., Stevia First Corporation, Ingredion Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Food Sweetener Market Evolving Landscape
Sweetener technology is fragmenting across multiple pathways simultaneously, with fermentation-derived compounds, plant extracts, and modified natural sugars competing for formulation space based on taste performance, thermal stability, and regulatory status rather than cost alone.
Enzymatically produced allulose is migrating from niche sports nutrition applications into mainstream bakery and frozen dessert formulations. National retail chains are adopting the ingredient for reduced-calorie private label lines. The shift is compressing erythritol market share in clean-label positioning as formulators prioritize superior browning and freezing point depression performance.
USDA biennial sugar program reauthorization debates are creating policy uncertainty for domestic beet and cane sugar processors. Price support mechanism adjustments directly alter high fructose corn syrup competitiveness in beverage applications. Midwest refiners are hedging through expanded specialty sweetener distribution partnerships to offset commodity margin compression.
Quick-service restaurant chains are consolidating procurement around fewer approved suppliers with integrated technical service capabilities. Large institutional buyers now demand formulation support, sensory validation, and supply continuity guarantees as table stakes. This concentration is most visible along the Eastern seaboard, where port terminal logistics dominance determines competitive positioning for imported refined sugar and plant extract alternatives.
United States Food Sweetener Market Segmentation
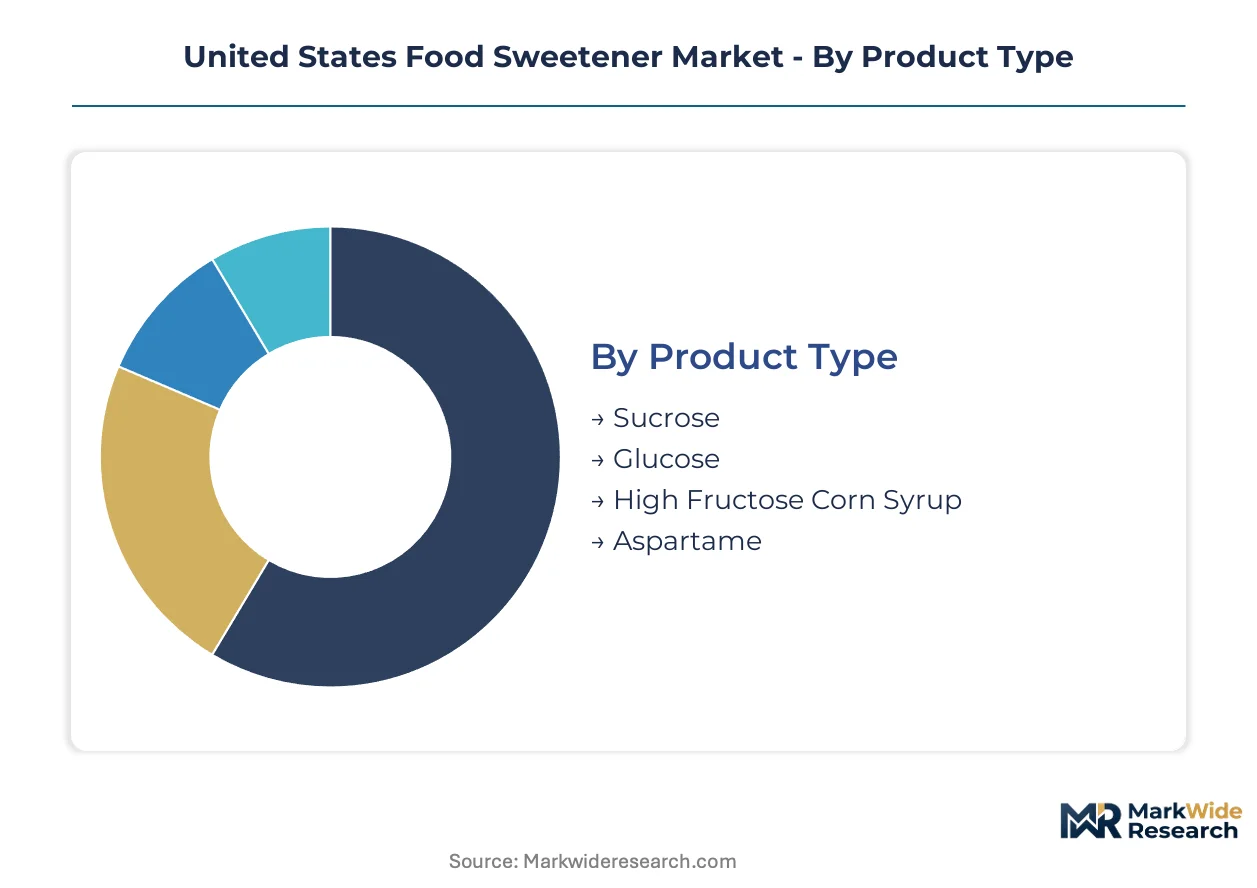
Sweetener procurement patterns diverge sharply across product categories, with industrial buyers prioritizing bulk thermal stability while retail channels emphasize clean-label positioning. Application-specific formulation requirements create distinct specification tiers that reshape supplier qualification criteria.
Product Type:
Use-case spectrum spans commodity caloric sweeteners for volume beverage production to precision high-intensity compounds for reduced-sugar reformulation.
- High Fructose Corn Syrup:Enzymatically processed corn starch yielding 42-55% fructose concentrations. Demand concentrates in Midwest beverage manufacturing corridors where Cargill's integrated wet milling infrastructure secures supply continuity for carbonated soft drink bottlers facing state-level sugar tax pressures.
- Sucrose:Refined beet and cane sugar standardized to 99.9% purity with defined crystal size distributions. Procurement clusters along Eastern seaboard port terminals where Südzucker AG leverages logistics dominance for confectionery and bakery manufacturers requiring precise browning control.
- Glucose:Monosaccharide derived from starch hydrolysis, valued for moisture retention and freezing point depression in frozen dessert applications.
- Aspartame:Dipeptide methyl ester providing 200x sucrose sweetness intensity, defending position in diet carbonated beverages despite clean-label migration.
Established volume favors high fructose corn syrup; emerging adoption favors aspartame alternatives.
Application:
Cost tier separation distinguishes mass-market beverage commodity procurement from premium confectionery specialty ingredient sourcing.
- Beverages:Largest consumption category spanning carbonated soft drinks, juices, and functional drinks. California's Los Angeles and San Francisco Bay Area innovation hubs concentrate reformulation activity as manufacturers accelerate low-calorie transitions ahead of FDA added sugars disclosure enforcement.
- Bakery:Sweeteners function as fermentation substrates, moisture retainers, and Maillard reaction precursors. Dry mix manufacturers in Chicago and Minneapolis metropolitan areas drive powdered format demand for distribution efficiency.
- Confectionery:Hard candy, chocolate, and chewing gum applications requiring precise crystallization control and hygroscopic stability.
- Dairy Products:Flavored milk, yogurt, and ice cream segments where sweetness modulation balances with protein stability under pasteurization.
Volume concentration sits with beverages; margin expansion favors bakery specialty formulations.
Form:
Supply chain configuration varies from bulk liquid tanker delivery to precision-packaged retail formats.
- Liquid:Pumpable syrups and solutions for continuous-process manufacturing. High fructose corn syrup dominates this format for beverage bottling operations in Iowa and Illinois processing zones.
- Granular:Free-flowing crystals for dry blending applications. Confectionery manufacturers along the Eastern seaboard prefer this form for controlled dissolution rates.
- Powdered:Fine-milled particles for instant solubility in beverage dry mixes and tabletop packets.
- Syrup:Viscous concentrated solutions for artisanal bakery and foodservice portion control.
Industrial procurement favors liquid; retail channel growth favors powdered convenience formats.
Customer Type:
Specification complexity escalates from commodity home use to certified industrial supply agreements.
- Industrial:Large-scale food manufacturers with validated supplier lists and technical service requirements. Tate & Lyle PLC secures preferred vendor status through integrated formulation support for quick-service restaurant chain procurement consolidation.
- Food Service:Institutional buyers including K-12 operators responding to USDA school meal nutrition standards with stevia and monk fruit transitions.
- Retail:Branded consumer packaged goods with clean-label positioning demands.
- Home Use:Tabletop sweetener consumers with price-sensitive, convenience-driven purchase patterns.
Contract security favors industrial accounts; organic certification complexity favors retail differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of New Orleans anchors Gulf Coast sugar import logistics, while Midwest rail networks connect Iowa corn wet milling infrastructure to Chicago distribution hubs. These transport arteries concentrate sweetener manufacturing capacity across distinct processing corridors.
California
Los Angeles and San Francisco Bay Area innovation clusters drive plant-based and reduced-sugar product development for beverage manufacturers. The state's sugar-sweetened beverage tax in San Francisco accelerates reformulation timelines. FDA added sugars disclosure enforcement concentrates technical support demand in these metro areas.
Midwest Corn Belt
Iowa and Illinois processing zones host integrated corn wet milling infrastructure supplying high fructose corn syrup to carbonated soft drink bottlers. EPA effluent discharge regulations directly affect production economics in these counties. Cargill's captive supply chains secure procurement contracts for regional brand owners.
Eastern Seaboard
Port terminals from Philadelphia to Baltimore concentrate refined sugar import logistics for confectionery manufacturers. Südzucker AG leverages this infrastructure for beet sugar distribution to New York and New Jersey bakery operations. State-level sugar taxes in Philadelphia fragment demand patterns.
Pacific Northwest
Seattle's sugar-sweetened beverage tax accelerates low-calorie blend transitions ahead of federal action. The metro area's foodservice distribution networks supply K-12 operators responding to USDA school meal nutrition standards. Stevia and monk fruit procurement volumes expand through regional distributors.
Southeast Processing Corridor
Florida and Georgia cane sugar refineries supply bulk liquid syrups to Atlanta beverage bottling operations. Port of Savannah logistics connect to Caribbean raw sugar sources. ASR Group International maintains distribution dominance for industrial accounts requiring precise crystallization control.
United States Food Sweetener Market Competitive Landscape
On the supply side, the industry is consolidating around integrated processors with captive raw material sourcing and technical service capabilities. Large institutional buyers narrow approved supplier lists, compressing procurement pools. Three archetypes dominate: commodity caloric sweetener refiners, specialty high-intensity extract producers, and fermentation-derived novel compound developers. Capacity expansion and strategic partnerships represent the dominant competitive moves.
Among integrated agribusiness conglomerates, Cargill, Incorporated and Archer Daniels Midland Company exemplify the commodity processing archetype through Midwest corn wet milling dominance. Tate & Lyle PLC occupies a position within the specialty formulation tier, leveraging technical service capabilities to secure preferred vendor status with quick-service restaurant chains. Südzucker AG anchors European-origin refined sugar logistics along Eastern seaboard terminals.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Südzucker AG |
| Cargill, Incorporated |
| Ajinomoto Co. Inc. |
| Roquette Frères |
| Archer Daniels Midland Company |
| ASR Group International, Inc. |
| Stevia First Corporation |
| Ingredion Incorporated |
| Others |
Value Network & Pricing Analysis
Midwest corn wet milling concentration in Iowa and Illinois processing zones anchors commodity sweetener supply, concentrating margin pools with integrated agribusiness conglomerates while fragmenting pricing power among downstream beverage bottlers facing state-level sugar tax pressures.
Pricing Analysis
Volume-discount tiering structures separate contract-based industrial procurement from spot-market foodservice transactions. Three-tier pricing stratifies across premium specialty formulations with technical service bundles, standard refined sugar and high fructose corn syrup contracts, and economy-grade commodity spot purchases. Cost compression in standard-tier caloric sweeteners is intensifying because of corn price volatility and EPA effluent compliance costs. Quick-service restaurant chains exhibit lowest price sensitivity due to reformulation switching costs, while tabletop retail consumers show highest elasticity.
Supply Chain Analysis
USDA sugar import quota administration functions as a de facto export-control regime limiting refined sugar flows from Brazil and Mexico into domestic markets. Raw material sourcing draws from Midwest corn starch, Florida and Georgia cane sugar, and concentrated stevia leaf cultivation regions in China and Paraguay. Single-source vulnerability concentrates in stevia extraction capacity tethered to climate-dependent agricultural zones. Distribution runs through bulk liquid tanker networks for beverage manufacturers and rail-served port terminals for Eastern seaboard confectionery processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against fermentation-derived novel sweeteners and plant-extract alternatives that threaten established caloric sweetener volume positions.
For Market Incumbents: Pre-empt clean-label migration by accelerating captive stevia and monk fruit extraction capacity in Paraguay and California agricultural zones. Secure preferred vendor status through integrated formulation support for quick-service restaurant chains consolidating approved supplier lists. Defensive patent positioning around allulose browning technology blocks fermentation-derived competitor entry into bakery applications. For New Entrants and Emerging Players: Pacific Northwest K-12 foodservice distribution presents underpenetrated white-space as USDA school meal nutrition standards mandate natural sweetener transitions ahead of national compliance curves. Target stevia-monk fruit blend formulations for institutional procurement channels seeking dual certification simplicity. Go-to-market leverage rests on regional distributor partnerships bypassing incumbent technical service bundling. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fermentation-derived novel compound manufacturing as GRAS petition timelines extend facility depreciation periods. Long-term viability favors acquisition targets with backward-integrated agricultural sourcing and validated supplier status with narrowing quick-service restaurant approved lists. Watch FDA allulose labeling guidance publication as inflection signal unlocking bakery and confectionery application expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stevia Cultivation | Cargill's Paraguay agricultural partnerships secure leaf supply against climate volatility in China. |
| Technical Service Capability Expansion | Tate & Lyle's formulation support teams lock in preferred vendor status with narrowing quick-service chains. |
| Fermentation-Derived Compound Commercialization | Roquette Frères' allulose production capacity captures bakery browning performance premiums. |
| Regional Co-Manufacturing Partnerships | Midwest brand owners leverage Cargill's integrated wet milling infrastructure for supply security. |
| Clean-Label Certification Investment | Organic and non-GMO verification extends supplier audit timelines but fragments procurement pools favoring certified incumbents. |
Research Methodology
A standing panel of beverage formulation directors, corn wet milling plant managers, quick-service restaurant procurement executives, and foodservice distribution channel heads provided ongoing calibration. Primary interviews combined with secondary validation against USDA sugar program administrative data, FDA GRAS petition filings, EPA effluent discharge records, and state-level sugar-sweetened beverage tax revenue reports. Bottom-up volume modeling triangulated against top-down value aggregation across product type, application, form, and customer type segmentation dimensions.
Scenario-bracketing framed demand projections across the analysis window, modeling base-case, accelerated-reformulation, and extended-regulatory-timeline pathways. Segmentation dimensions included caloric versus non-caloric product type, beverage versus bakery versus confectionery application, liquid versus granular versus powdered form, and industrial versus foodservice versus retail customer tier. CAGRs derived from elasticity-adjusted volume projections incorporating FDA added sugars disclosure enforcement timelines and state tax expansion patterns.
Macroeconomic conditions sit as an overlay; deviation in corn futures pricing, agricultural input cost inflation, or biofuel policy shifts would shift the trajectory. Forecasts reflect assumptions regarding GRAS petition approval timelines, USDA sugar program reauthorization continuity, and EPA effluent enforcement intensity. Material shifts in FDA allulose labeling guidance or federal sugar-sweetened beverage tax legislation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Starch Glucose Syrup Market
Sweeteners
Dextrose Syrup Market
Sweeteners
Europe Food Sweetener Market
Sweeteners
China Allulose Market
Sweeteners
North America Food Sweetener Market
Sweeteners
Intensive Sweeteners Market
Sweeteners
India Cane Sugar Market
Sweeteners
Reduced Sugar Products Market
Sweeteners
Sorbitol Market
Sweeteners
D-Mannose Market
Sweeteners
Muscovado Sugar Market
Sweeteners
Mannitol Market
Sweeteners
Australia Food Sweetener Market
Sweeteners
Raw Beetroot Sugar Market
Sweeteners
China Saccharin Market
Sweeteners
Polyol Sweeteners Market