
 Europe Plant-Derived and Synthetic Sugar Market | 2026-2036
Europe Plant-Derived and Synthetic Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
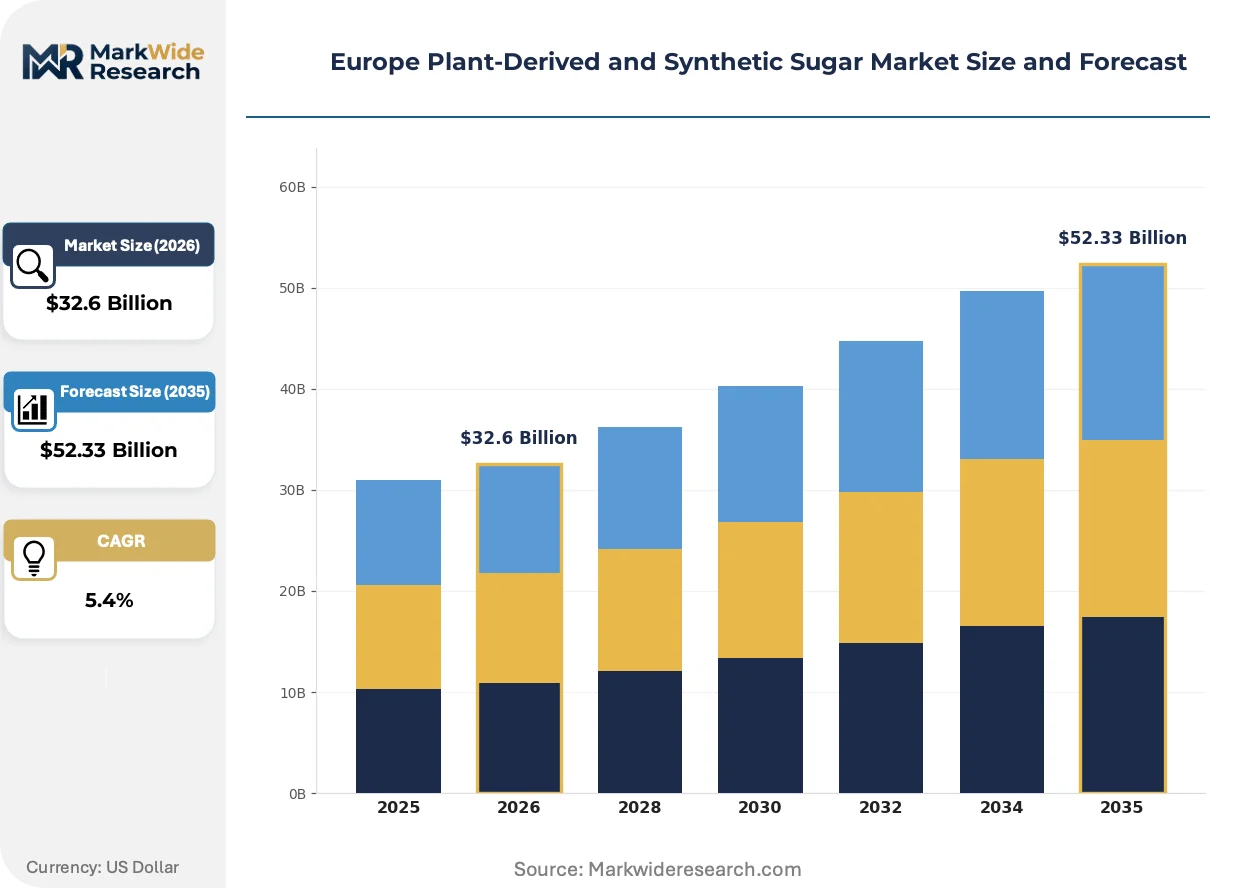
Europe Plant-Derived and Synthetic Sugar Market Foresight
Premium-grade sweetener specifications is unwinding conventional commodity trading patterns across European supply chains. Südzucker AG leverages its beet sugar refining infrastructure to maintain integrated control from agricultural sourcing to industrial distribution. Tate & Lyle PLC specializes in reformulation partnerships with beverage producers seeking clean-label sugar reduction. Cargill Incorporated dominates bulk high-fructose syrup supply to Central European food manufacturers through its Maize processing network.
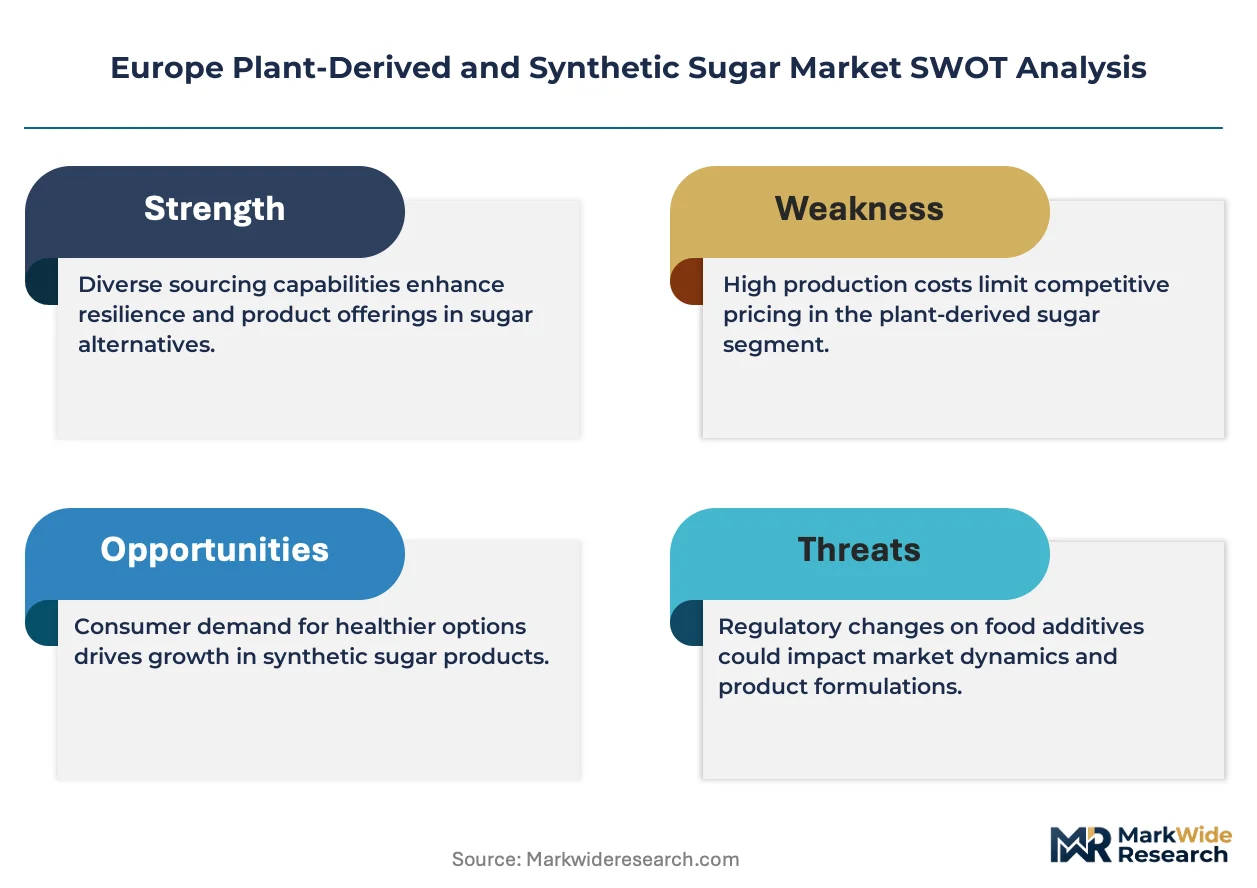
Europe Plant-Derived and Synthetic Sugar encompasses carbohydrate-based sweetening agents extracted from agricultural feedstocks such as sugar beet, sugar cane, and corn starch, alongside chemically synthesized alternatives including aspartame, sucralose, and acesulfame potassium, typically specified by purity grades, particle size distributions, and dissolution rates for industrial batch consistency. These inputs serve primarily as taste-modulating functional ingredients in mass-market food and beverage manufacturing, where they influence viscosity, browning kinetics, and shelf stability beyond mere sweetness delivery. Natural Sweeteners currently anchors the largest value pool as clean-label positioning drives reformulation budgets at major food manufacturers, while Sugar Alcohols competes for share in confectionery applications where dental health claims and reduced glycemic impact support premium positioning. Artificial Sweeteners occupies a mature trajectory in carbonated beverages, though regulatory scrutiny from EFSA on acceptable daily intake levels constrains expansion into new application categories.
EFSA maintains active re-evaluation protocols for high-intensity sweeteners that directly condition product approval timelines and reformulation investment cycles across the continent. REACH compliance requirements for synthetic sweetener precursors add registration cost burdens that favor established producers with dedicated regulatory affairs capabilities over new entrants. The EU Green Deal's sugar beet sustainability criteria and emerging CSRD disclosure obligations will reshape agricultural contracting practices and Scope 3 emissions tracking. Stakeholders must monitor EFSA's pending opinions on novel sweetener blends and pre-emptively audit supply chain documentation against tightening due diligence standards.
Market Dynamics
EFSA's re-evaluation protocols for high-intensity sweeteners are compressing product approval timelines and forcing reformulation investment cycles across European food and beverage supply chains.
Growth Catalysts
- EU Farm to Fork Strategy:Mandatory sugar reduction targets for processed foods are accelerating clean-label reformulation programs at major manufacturers.
- Beverage sector concentration:Carbonated and functional drink producers across Germany and France are expanding R&D budgets for alternative sweetener integration.
- Sugar beet sustainability criteria:EU Green Deal agricultural standards are redirecting procurement toward certified regenerative supply chains.
Market Restraints
- Input cost volatility:Natural gas prices directly condition beet sugar processing economics and margin stability at Central European refineries.
- Regulatory friction:REACH compliance requirements for synthetic sweetener precursors impose registration burdens that favor incumbent producers with dedicated regulatory affairs teams.
- Substitution threat:Stevia-derived glycosides and monk fruit extracts are capturing clean-label positioning budgets that previously flowed to sugar alcohols.
Strategic Opportunities
- Poland confectionery expansion:Dental health claims and reduced glycemic impact positioning open premium segments in sugar-free chocolate and gum applications.
- CSRD disclosure obligations:Emerging corporate sustainability reporting requirements create first-mover advantages for suppliers with audited Scope 3 emissions documentation.
- Enzymatic conversion advances:Converging biotechnology and membrane filtration technologies enable novel rare sugar production at commercial scale.
Industry Challenges
- Reformulation technical gaps:Food manufacturers face acute shortages of formulation chemists trained in bulking agent replacement and browning kinetics modification.
- Certification timeline compression:Novel Food approvals under EFSA procedures extend 18-24 months, delaying product launch windows.
- Legacy equipment incompatibility:High-intensity sweetener dosing precision requirements force capital-intensive retrofitting of existing blending infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Plant-Derived and Synthetic Sugar Market |
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $52.33 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Sweeteners, Artificial Sweeteners, Sugar Alcohols, High-Fructose Syrups Application: Beverages, Bakery Products, Confectionery, Dairy End User: Food Manufacturers, Beverage Producers, Retailers, Restaurants Distribution Channel: Online Retail, Supermarkets, Wholesale Distributors, Convenience Stores |
| Companies Covered | Symrise AG, Tereos Starch and Sweeteners, Ingredion Incorporated, Roquette Freres, Tate & Lyle PLC, Cargill Incorporated, The Archer Daniels Midland Company, Associated British Foods PLC, Südzucker AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Plant-Derived and Synthetic Sugar Market Shifts & Advancements
Biotechnology-enabled rare sugar production and tightening nutritional labeling mandates are restructuring competitive advantage around precision fermentation capabilities and regulatory anticipation.
Precision fermentation platforms for allulose and tagatose production are miniaturizing unit economics previously constrained by agricultural feedstock dependency. Scandinavian dairy and bakery manufacturers are piloting these ingredients at commercial scale. The technology is miniaturizing cost differentials between plant-extracted and biomanufactured rare sugars.
EFSA's systematic re-evaluation of aspartame and sucralose acceptable daily intakes is forcing beverage formulators toward blended sweetener architectures. Manufacturers are diversifying ingredient portfolios to reduce single-compound exposure risks. Carbonated soft drink producers in Germany and Spain are accelerating stevia-sugar hybrid development programs.
Retail buyer concentration through private-label expansion is compressing supplier negotiation leverage. Discounters Aldi and Lidl are consolidating sweetener procurement across national boundaries. This pattern is most visible in Germany, where centralized buying offices now dictate specification standards for pan-European product lines.
Europe Plant-Derived and Synthetic Sugar Market Segmentation
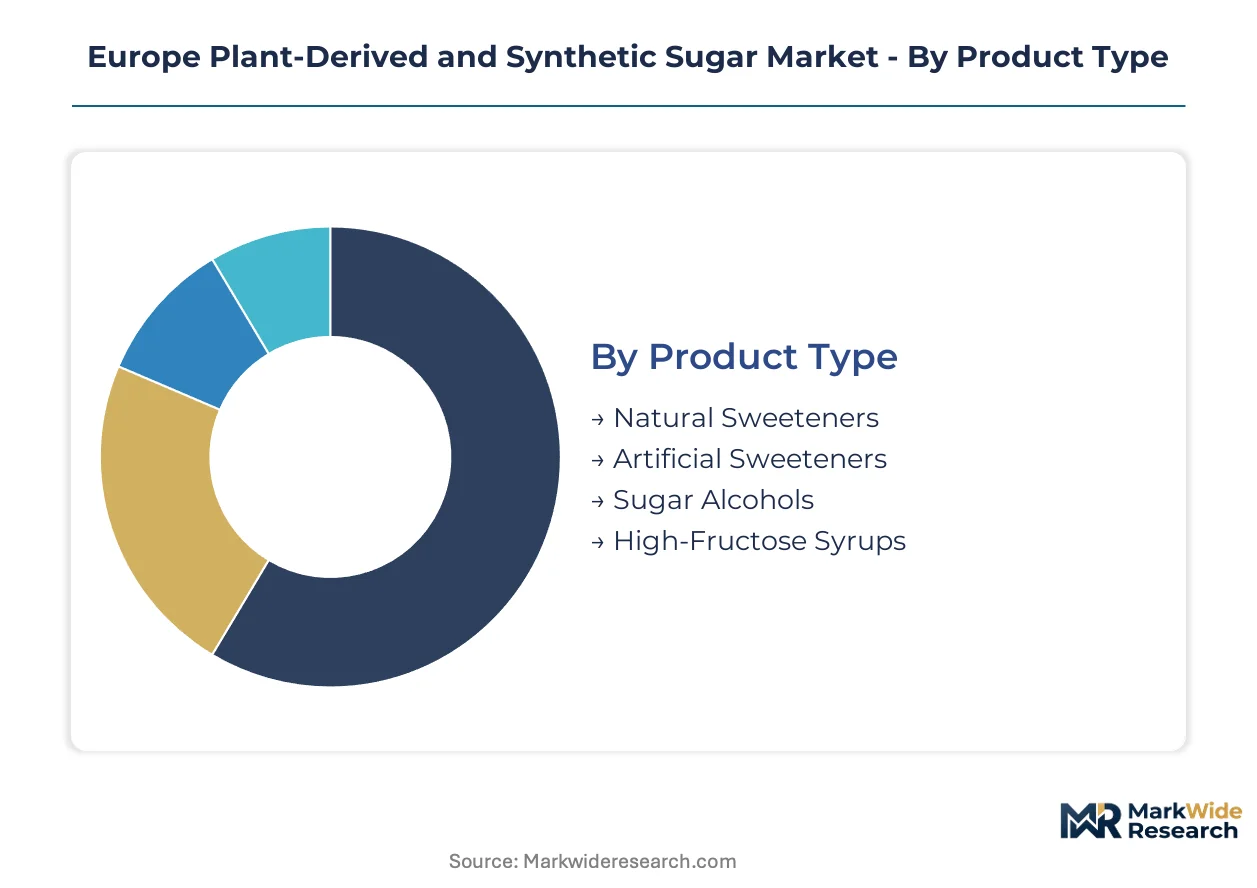
Sweetener procurement patterns diverge sharply across European food and beverage supply chains. EFSA classification schemes and clean-label positioning requirements create distinct specification tiers that reshape manufacturer sourcing decisions and distributor inventory strategies.
Product Type:
EFSA's Novel Food approval pathways and acceptable daily intake protocols segment the competitive landscape by regulatory burden intensity.
- Natural Sweeteners:Stevia glycosides and monk fruit extracts command premium positioning in German and French reformulation programs. Beverage manufacturers in these markets allocate R&D budgets toward blended architectures that reduce synthetic compound exposure risks under tightening EFSA scrutiny.
- Artificial Sweeteners:Aspartame, sucralose, and acesulfame potassium face systematic re-evaluation of daily intake thresholds. Carbonated drink producers across Spain and Italy are diversifying away from single-compound dependencies toward hybrid sweetener systems.
- Sugar Alcohols:Xylitol and erythritol dominate Polish and Czech confectionery applications where dental health claims support premium pricing.
- High-Fructose Syrups:Maize-derived bulk supply concentrates in Central European processing corridors serving industrial bakery and beverage contracts.
Established volume favors high-fructose syrups; emerging adoption favors natural sweeteners.
Application:
Reformulation technical requirements and browning kinetics specifications segment demand by functional complexity.
- Beverages:Carbonated and functional drink producers face acute bulking agent replacement challenges when reducing added sugars. German manufacturers lead investment in precision dosing infrastructure compatible with high-intensity sweetener integration.
- Bakery Products:Maillard reaction control and moisture retention properties constrain sugar substitution options. French and Italian artisanal producers prioritize rare sugars that preserve crust color development and shelf stability.
- Confectionery:Sugar-free chocolate and gum applications in Poland and Scandinavia leverage sugar alcohols for glycemic impact positioning.
- Dairy:Fermented product categories require sweetener systems compatible with live culture viability and post-acidification stability.
Beverage applications absorb the steepest R&D investment; dairy segments face the tightest formulation constraints.
End User:
Procurement scale and specification authority concentrate demand across distinct buyer categories with diverging technical capabilities.
- Food Manufacturers:Pan-European bakery and confectionery groups maintain captive formulation teams that direct supplier qualification protocols.
- Beverage Producers:Multinational carbonated drink and functional beverage companies centralize sweetener sourcing through Hamburg and Rotterdam trading desks.
- Retailers:Aldi and Lidl buying offices in Germany dictate private-label specification standards across national boundaries.
- Restaurants:Foodservice operators concentrate bulk granulated sugar procurement through regional distribution cooperatives.
Food manufacturers command the deepest technical integration; retailers exert the strongest price leverage.
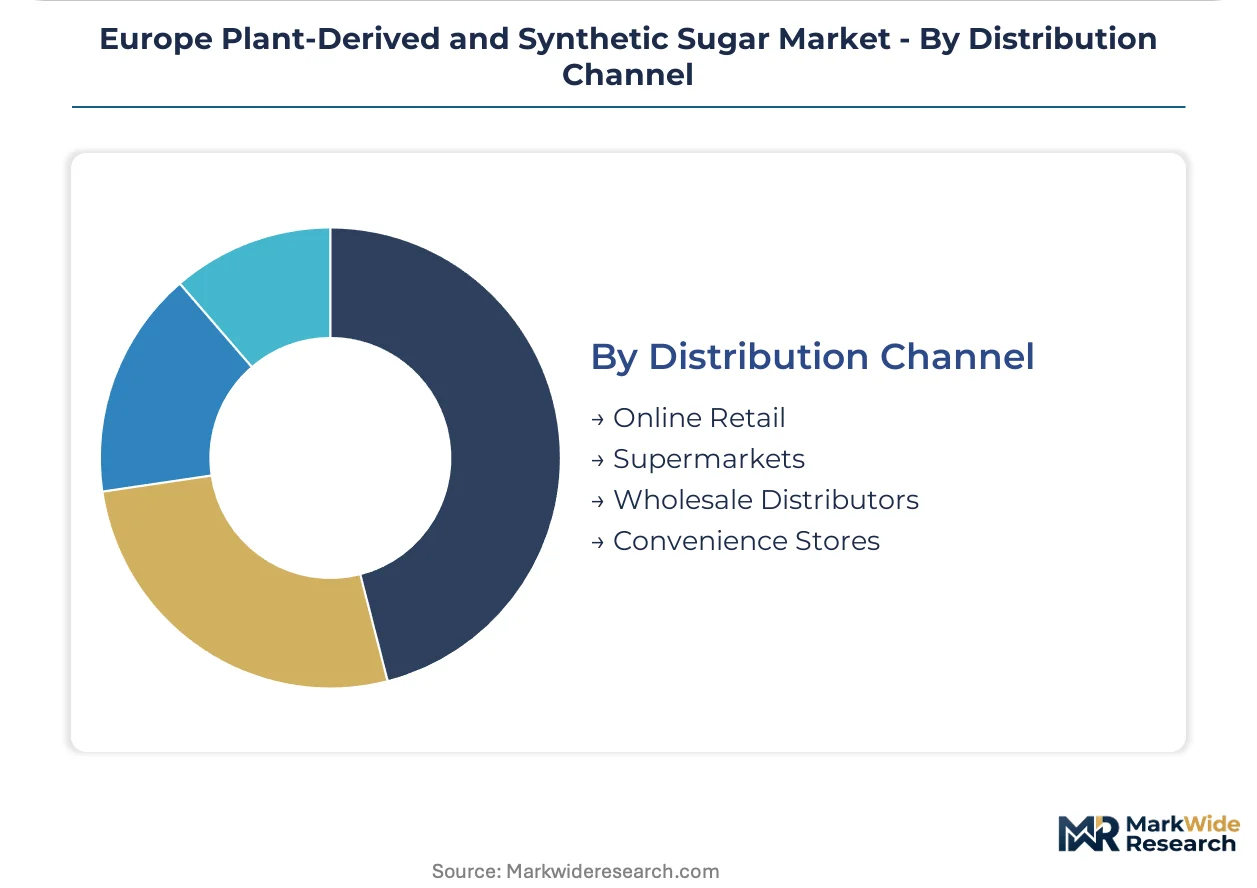
Distribution Channel:
Order frequency and lot size requirements segment logistics infrastructure by handling economics and traceability obligations.
- Online Retail:Direct-to-consumer specialty sweetener sales concentrate in Scandinavian markets with advanced e-grocery penetration.
- Supermarkets:Granulated and liquid sugar SKUs face intense private-label substitution pressure across German and French retail banners.
- Wholesale Distributors:Industrial sweetener supply chains run through Antwerp and Hamburg bulk handling terminals serving Central European food manufacturing clusters.
- Convenience Stores:Single-serve and small-format sugar products serve immediate consumption demand in urban transit corridors.
Wholesale distributors anchor industrial volume; online retail expands fastest in specialty segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beet sugar refineries cluster along the Rhine-Ruhr corridor and northern France, while maize processing plants anchor Central European high-fructose syrup supply. This geographic split conditions cross-border trade flows and regulatory compliance burdens across the continent.
Germany
Beverage manufacturers in Hamburg and Cologne are accelerating stevia-sugar hybrid development programs. The country's Federal Ministry of Food and Agriculture enforces strict sugar reduction targets aligned with the EU Farm to Fork Strategy. The Mannheim-Ludwigshafen chemical corridor hosts multiple synthetic sweetener precursor facilities facing REACH registration pressures.
France
Artisanal bakery producers in Paris and Lyon prioritize rare sugars that preserve Maillard reaction control and crust color development. ANSM monitors food additive safety alongside EFSA harmonized standards. The Picardy beet belt supplies raw material to refineries serving pan-European industrial contracts.
United Kingdom
Functional drink startups in London and Manchester are diversifying sweetener portfolios to reduce single-compound exposure risks. The Food Standards Agency implements post-Brexit divergence from EFSA timelines on novel food approvals. The Thames estuary handles bulk granulated sugar imports from tropical cane origins.
Poland
Confectionery manufacturers in Warsaw and Wrocław leverage xylitol and erythritol for dental health claims in sugar-free chocolate and gum. The country's national food safety regulator aligns with EFSA re-evaluation protocols for high-intensity sweeteners. The Silesian industrial zone processes maize-derived syrups for Central European bakery contracts.
Netherlands
Trading houses in Rotterdam and Amsterdam dictate specification standards for high-fructose syrup distributed across German and Belgian manufacturing clusters. The Dutch Food and Consumer Product Safety Authority enforces EU Green Deal sugar beet sustainability criteria. The port of Rotterdam anchors bulk sweetener handling infrastructure serving northwest European demand.
Europe Plant-Derived and Synthetic Sugar Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across European sweetener supply chains. The market structure consolidates around integrated agricultural processors and specialized ingredient formulators with divergent capital intensity requirements. Three archetypes dominate: beet sugar refiners with captive agricultural sourcing, maize processors controlling high-fructose syrup bulk supply, and reformulation specialists partnering with beverage manufacturers on clean-label architectures. Competitive moves concentrate on backward integration into regenerative agriculture certification and portfolio diversification toward rare sugars via precision fermentation licensing.
Among integrated European processors, Südzucker AG and Tate & Lyle PLC occupy positions exemplifying divergent strategic paths. Südzucker anchors the agricultural-integrated archetype through beet sugar refining infrastructure spanning Germany and Central Europe. Tate & Lyle represents the reformulation-partnership model, engaging beverage producers on sugar reduction technical services. Cargill Incorporated sits within the global commodity trader archetype, leveraging Maize processing networks to supply Central European food manufacturers with bulk high-fructose syrups.
| Leading Market Players |
|---|
| Symrise AG |
| Tereos Starch and Sweeteners |
| Ingredion Incorporated |
| Roquette Freres |
| Tate & Lyle PLC |
| Cargill Incorporated |
| The Archer Daniels Midland Company |
| Associated British Foods PLC |
| Südzucker AG |
| Others |
Supply & Pricing Matrix
EU Green Deal sugar beet sustainability criteria gate both supplier qualification and price differentiation simultaneously. Certification tiers separate regenerative-sourced feedstocks from conventional supply, embedding compliance costs into premium positioning while compressing margins at the commodity tier.
Pricing Analysis
EFSA Novel Food approval pathways dictate the pricing tier structure across European sweetener markets. Three-tier pricing stratifies across pharmaceutical-grade, food-grade, and industrial-grade purity specifications. Price differentiation hinges on certification burden intensity and dissolution rate consistency. Cost compression in bulk high-fructose syrups intensifies as Central European maize processors expand capacity. Retail buying offices at German discounters exhibit highest price sensitivity; beverage formulators seeking clean-label positioning show lowest sensitivity.
Supply Chain Analysis
Rhine-Ruhr corridor beet processing infrastructure anchors supply concentration across Germany, France, and Belgium. Raw material flows draw from Picardy beet belts, Ukrainian agricultural zones, and Brazilian cane origins. Single-source vulnerability concentrates in natural gas-dependent refining operations. Distribution runs through Rotterdam and Hamburg bulk terminals serving pan-European manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European sweetener markets are cycling through a reformulation-driven recovery phase. EU Farm to Fork Strategy sugar reduction mandates are resetting demand baselines across beverage and confectionery verticals.
For Market Incumbents: Fortify backward integration into regenerative agriculture certification to preempt CSRD disclosure obligations. Lock in long-term offtake agreements with beet cooperatives before sustainability criteria tighten. Defend against stevia-sugar hybrid substitution by accelerating rare sugar production licensing. For New Entrants and Emerging Players: Differentiate on enzymatic conversion capabilities for allulose and tagatose production. Target Polish confectionery applications where dental health claims command premium positioning. Pursue precision fermentation partnerships with Scandinavian dairy manufacturers as the primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed reformulation specialists holding EFSA regulatory affairs capabilities. Five-to-ten year viability hinges on portfolio diversification beyond artificial sweetener exposure. Watch EFSA pending opinions on novel sweetener blends as the critical inflection signal for valuation recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Enables commercial allulose production independent of agricultural feedstock volatility. |
| Regenerative Agriculture Certification | Secures preferential contracting terms under EU Green Deal sugar beet sustainability criteria. |
| Reformulation Partnership Programs | Locks in multi-year technical service contracts with German beverage manufacturers. |
| Rare Sugar Patent Licensing | Generates royalty streams from enzymatic conversion technologies licensed to Central European processors. |
| Scope 3 Emissions Auditing Infrastructure | Creates first-mover advantage for CSRD disclosure compliance across agricultural supply chains. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA Novel Food registers, EU customs trade databases, and corporate sustainability disclosures. Input sources span formulation chemists at German beverage manufacturers, procurement leads at French bakery groups, regulatory affairs directors at sweetener suppliers, and trading desk managers at Rotterdam bulk terminals. Bottom-up volume estimates triangulate against top-down macroeconomic indicators across the analysis window.
Segmentation dimensions modeled include sweetener origin category, application functional requirements, end-user procurement scale, and distribution channel handling economics. CAGRs derive from trend extrapolation of reformulation investment cycles and regulatory approval timelines. Forecast inputs incorporate EFSA re-evaluation protocol schedules and EU Green Deal implementation trajectories throughout the projection horizon.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or accelerated biotechnology cost reduction would require recalibration. Forecasts reflect documented assumptions regarding EFSA approval timelines and agricultural input cost stabilization. Practitioners should keep alternative scenarios live as EFSA novel sweetener opinions and natural gas price volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Russia Food Sweetener Market
Sweeteners
Muscovado Sugar Market
Sweeteners
Saccharin Market
Sweeteners
Methyl Glucose Market
Sweeteners
Tapioca Maltodextrin Market
Sweeteners
Middle East and Africa Food Sweetener Market
Sweeteners
Polyphenol Sweetener Market
Sweeteners
Digestion Resistant Maltodextrin Market
Sweeteners
Saudi Arabia Allulose Market
Sweeteners
Turbinado Sugar Market
Sweeteners
Japan Food Sweetener Market
Sweeteners
Low-Fat Sugar Market
Sweeteners
North America Food Sweetener Market
Sweeteners
Monk Fruit Sugar Market
Sweeteners
Europe Food Sweetener Market
Sweeteners
Xylose Market