
 Refined Cane Sugar Market | 2026-2036
Refined Cane Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
Refined Cane Sugar Market Analytics
Single-serve and portion-controlled packaging is broadening buyer choice across household and food service channels. Südzucker AG leverages its European milling network to sustain bulk supply contracts with industrial bakers. Cargill anchors North American distribution through integrated logistics infrastructure that controls terminal-to-plant delivery. Tereos competes in liquid sugar systems by specializing in just-in-time tanker shipments to beverage manufacturers.
Refined cane sugar denotes sucrose extracted from sugarcane stalks through diffusion, purification, crystallization, and drying to achieve minimum polarization standards, typically serving as a standardized sweetener, bulking agent, and preservative across food manufacturing. Granulated sugar occupies the dominant share of value given its ubiquity in baking and confectionery, while liquid sugar is gaining traction among beverage producers seeking process automation and reduced handling costs. Powdered sugar commands premium positioning in specialty bakery applications where particle size consistency determines finished product texture.
The FDA governs refined sugar labeling under the Nutrition Facts panel overhaul, pressing manufacturers toward transparency on added sugars content that influences reformulation decisions. REACH and EFSA frameworks in Europe enforce purity specifications and contaminant thresholds that shape import acceptance criteria for tropical-origin supply. Brazil's RenovaBio program and India's FSSAI fortification directives each redirect cane allocation and product standardization priorities. Stakeholders must monitor how biofuel policy intersects with food-grade sucrose availability to calibrate long-term procurement and inventory strategies.
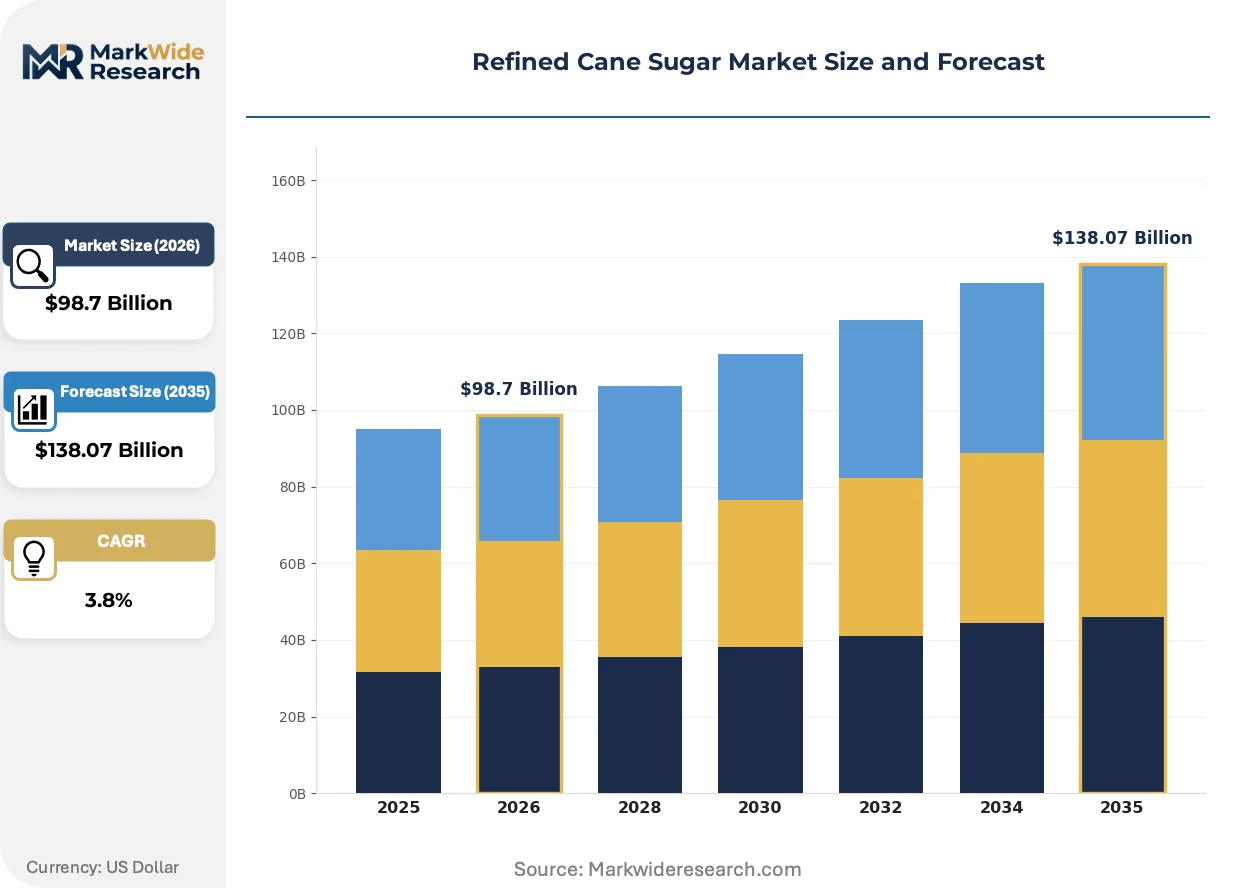
Market Dynamics
Brazil's RenovaBio program is redirecting cane crush capacity toward ethanol production, tightening refined sugar export availability and forcing buyers to recalibrate procurement strategies around alternative supply origins.
Growth Catalysts
- RenovaBio Mandates:Brazil's biofuel blending requirements are accelerating ethanol investment, reducing refined sugar export volumes and elevating prices for remaining supply.
- Liquid Sugar Adoption:Beverage manufacturers across Southeast Asia are automating production lines with bulk liquid sugar systems that eliminate bag handling and dissolution steps.
- Fortification Directives:India's FSSAI standards for micronutrient-enriched sugar are opening premium positioning for processors capable of integrated vitamin A delivery.
Market Restraints
- Raw Cane Cost Volatility:Weather-driven yield fluctuations in Maharashtra and Uttar Pradesh compress margins for refiners locked into long-term fixed-price contracts.
- Export Concentration Risk:Thailand's 12% share of global refined exports creates vulnerability when El Niño patterns disrupt crushing schedules.
- High-Intensity Sweetener Substitution:Stevia and monk fruit extract formulations in reduced-sugar beverages displace sucrose volumes in carbonated soft drink categories.
Strategic Opportunities
- Vietnam Confectionery Expansion:Industrial park clusters near Ho Chi Minh City are scaling chocolate and candy output, generating unmet demand for bulk granulated supply.
- Carbon Border Adjustments:The EU Green Deal's CBAM mechanism rewards Brazilian mills with verified low-carbon ethanol co-production, creating preferential access for certified sugar.
- Direct-to-Bakery Distribution:Tanker-based liquid sugar delivery bypasses traditional distributor markups for mid-sized European industrial bakeries.
Industry Challenges
- Specialized Engineering Talent Scarcity:Crystallization process optimization and continuous pan automation require expertise concentrated among retiring Brazilian and Indian technical specialists.
- Legacy ERP Integration Friction:Real-time inventory tracking for just-in-time tanker logistics conflicts with installed SAP systems at multinational beverage bottlers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refined Cane Sugar Market |
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $138.07 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granulated Sugar, Powdered Sugar, Liquid Sugar, Brown Sugar Application: Baking, Beverage Production, Confectionery, Food Preservation End User: Household, Food Service, Food Processing, Bakery Distribution Channel: Online Retail, Supermarkets, wholesalers, Direct Sales |
| Companies Covered | Südzucker AG, Cargill, Tereos, Raizen S.A., Wilmar International, Louis Dreyfus Company B.V., Associated British Foods plc, Cosan SA, ASR Group International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refined Cane Sugar Market Evolving Landscape
Digital traceability platforms and automated handling systems are compressing traditional supply chain layers while regulatory carbon accounting reshapes origin preferences for industrial buyers.
Membrane filtration technology for direct production of liquid sugar is converging with beverage manufacturers' continuous processing lines. Coca-Cola and Pepsi bottlers in Mexico and Indonesia are retrofitting plants for bulk tanker receipt. This convergence is eliminating 25-kilogram bag handling and dissolution tanks from facility footprints.
REACH purity specifications and EFSA contaminant thresholds are tightening acceptance criteria for tropical-origin refined sugar. European importers now require third-party laboratory certification for pesticide residues and heavy metals. Brazilian and Thai exporters are investing in dedicated food-grade processing lines to maintain EU market access.
Industrial bakeries and confectioners are consolidating procurement through regional cooperative purchasing agreements. These buying alliances negotiate directly with mill groups, bypassing traditional commodity traders. The shift is most visible in Germany's Mittelstand bakery sector and Spain's biscuit manufacturing clusters.
Refined Cane Sugar Market Segmentation
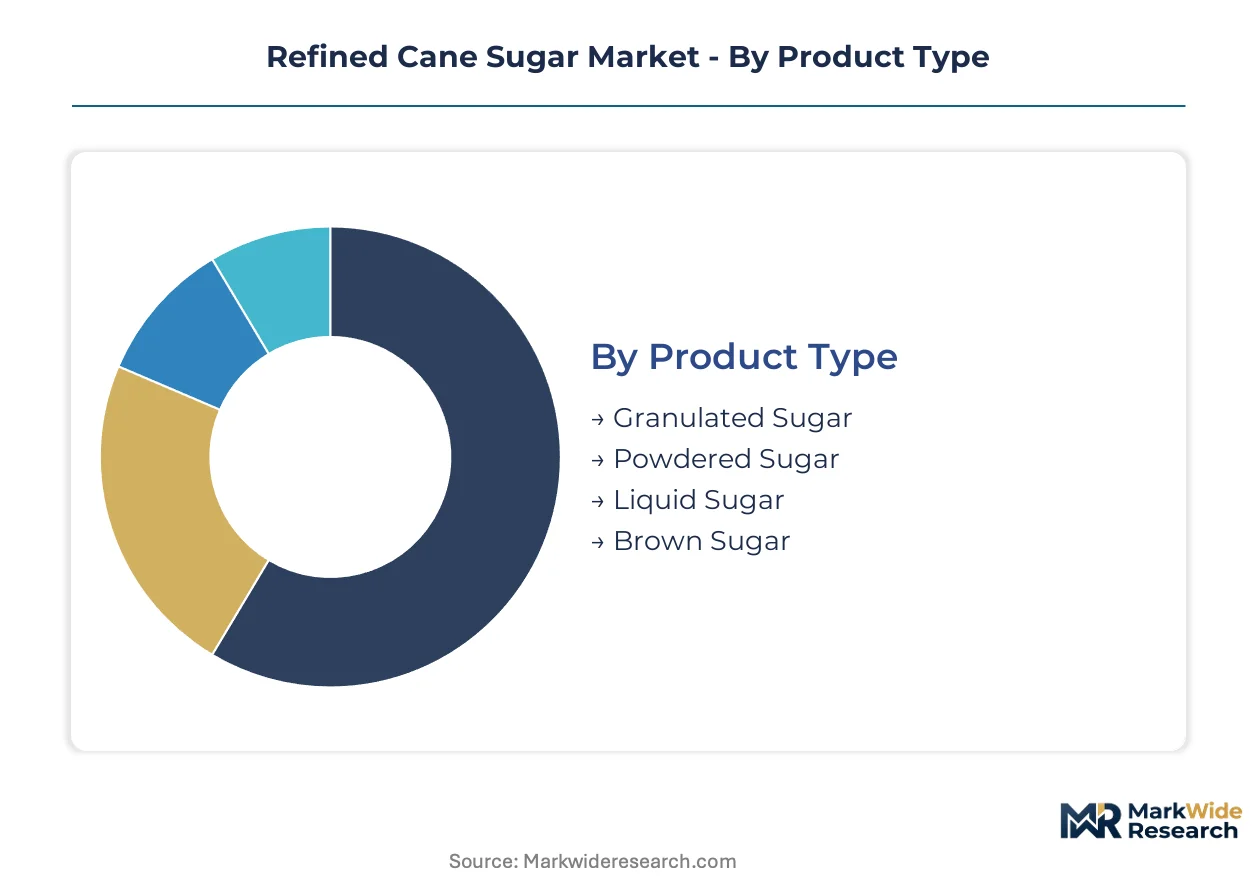
Refined cane sugar procurement patterns diverge sharply across product formats and end-use channels, with industrial buyers prioritizing handling efficiency while household segments emphasize packaging convenience. Understanding these fracture lines enables suppliers to align crystallization investments and logistics infrastructure with specific demand pockets.
Product Type:
Manufacturing equipment replacement cycles favor formats that reduce labor and floor space requirements, driving differential upgrade timelines across sugar processing lines.
- Granulated Sugar:Standard crystalline sucrose with 99.9% polarization serves as the baseline sweetener across industrial baking and home cooking. Demand concentrates in European industrial bakeries where bulk pneumatic conveying systems eliminate bag handling labor.
- Liquid Sugar:Invert sugar solutions and sucrose syrups dissolve instantly without heating, enabling continuous beverage processing. Southeast Asian bottlers in Thailand and Vietnam are retrofitting plants for bulk tanker receipt to automate production lines.
- Powdered Sugar:Finely milled sucrose with anti-caking agents for specialty bakery glazing.
- Brown Sugar:Centrifugal soft sugar retaining molasses for flavor-forward confectionery applications.
Granulated sugar sits at the top of the volume ranking, with liquid sugar climbing the fastest.
Application:
Cost tier differentiation separates commodity-grade from specialty-grade specifications, with premium certifications commanding measurable price spreads in each use case.
- Beverage Production:Liquid sugar systems integrate directly with carbonation and blending equipment, eliminating dissolution tanks. Mexican and Indonesian bottlers are standardizing on 67 Brix tanker deliveries to compress facility footprints.
- Confectionery:Precise particle size and color specifications determine finished product texture and appearance. Chocolate manufacturers near Ho Chi Minh City are scaling output and demanding consistent bulk granulated supply.
- Baking:Creaming and fermentation performance depends on crystal size distribution in bread and pastry formulations.
- Food Preservation:Osmotic pressure from high sucrose concentrations inhibits microbial growth in jams and canned fruits.
Beverage production commands the largest absolute volume, with confectionery expanding most quickly.
End User:
Customer type determines packaging format and delivery frequency, with food processors negotiating annual contracts while households respond to shelf-ready unit pricing.
- Food Processing:Large-scale manufacturers source through direct mill contracts with quarterly price adjustments. Südzucker AG sustains bulk supply agreements with industrial bakers across its European milling network.
- Food Service:Restaurants and institutional kitchens require portion-controlled packets and pourable canisters for operational consistency.
- Bakery:Artisan and industrial bakers prioritize consistent moisture content for dough rheology control.
- Household:Retail consumers select based on brand recognition and packaging convenience for pantry storage.
Food processing dominates procurement volumes, with food service gaining share fastest.
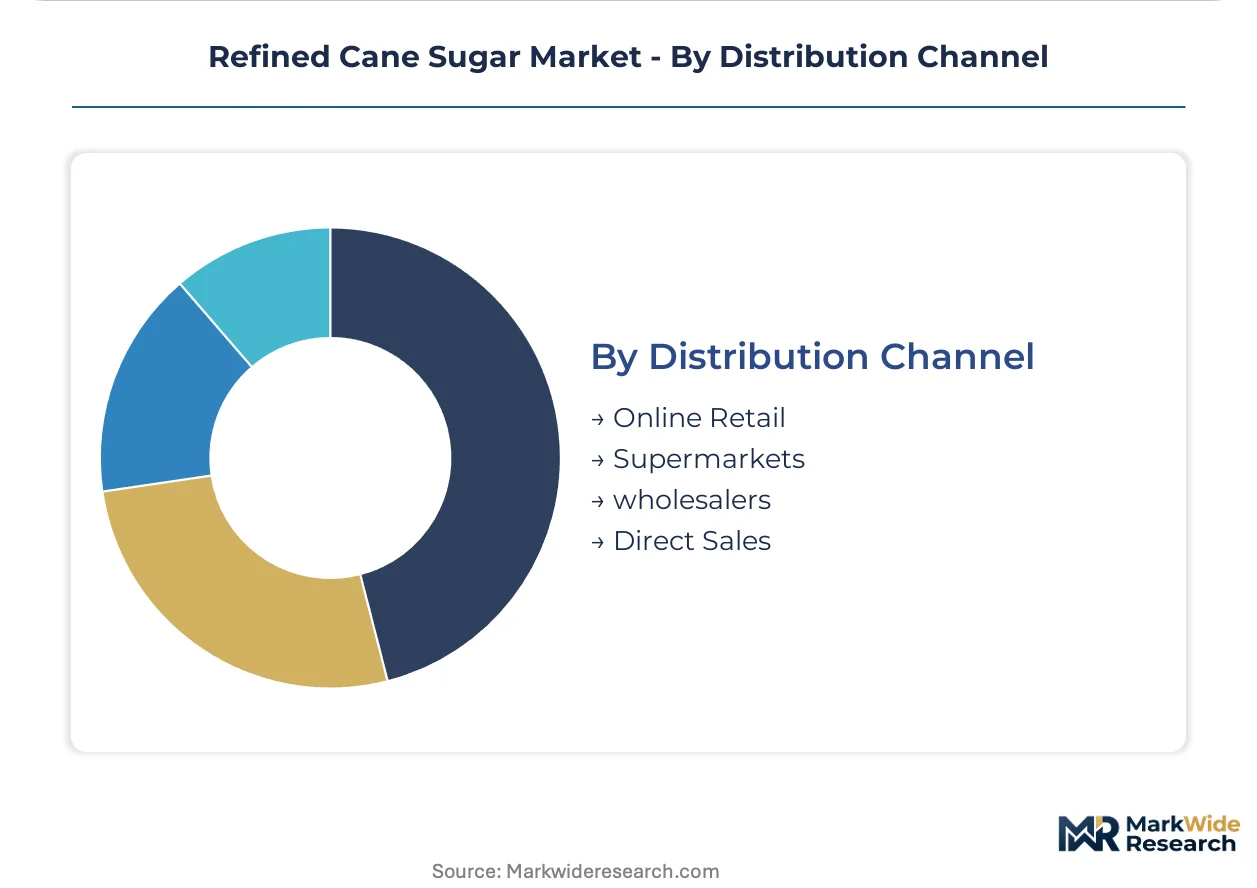
Distribution Channel:
Supply concentration in Brazilian and Thai export corridors shapes channel selection, with direct sales favoring origin-proximate buyers and retail channels serving fragmented end markets.
- Direct Sales:Mill-to-plant contracts eliminate intermediary margins for high-volume industrial buyers. Cargill anchors North American distribution through terminal-to-plant logistics infrastructure.
- Wholesalers:Regional distributors aggregate smaller food manufacturer orders and manage inventory buffers.
- Supermarkets:Retail chains stock branded consumer packages with promotional pricing cycles.
- Online Retail:E-commerce platforms serve specialty and bulk household orders with delivery scheduling.
Direct sales lead volume throughput, with online retail climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refined cane sugar production traces its industrial origins to colonial sugar plantations in Brazil and the Caribbean, where Portuguese and Dutch processing techniques established the crystallization standards still governing global trade today.
Brazil
São Paulo state's sugar-ethanol complex diverts crush capacity toward biofuel under RenovaBio mandates, tightening food-grade sucrose export volumes. ANVISA enforces contaminant thresholds that shape mill investment in dedicated food-grade processing lines. The Ribeirão Preto cluster hosts integrated crush-to-refine operations serving European and Asian buyers.
Thailand
Khon Kaen and Kanchanaburi provinces anchor Southeast Asia's largest export-oriented refining base, supplying Vietnamese and Indonesian beverage bottlers. El Niño-driven harvest volatility compresses crushing schedules and export reliability. The Eastern Economic Corridor near Laem Chabang port concentrates bulk liquid sugar terminal infrastructure for just-in-time tanker loading.
India
Maharashtra and Uttar Pradesh mills face margin pressure from weather-driven yield swings and FSSAI fortification mandates requiring integrated vitamin A delivery systems. The FSSAI directives open premium positioning for processors capable of micronutrient enrichment. Nashik industrial bakeries and Pune confectionery clusters scale procurement through cooperative purchasing agreements bypassing traditional traders.
Germany
Saxony-Anhalt and Bavaria host Europe's most concentrated beet-to-cane refining infrastructure, with Südzucker AG sustaining bulk supply contracts across the Mittelstand bakery sector. REACH purity specifications and EFSA contaminant thresholds enforce third-party laboratory certification for tropical-origin imports. The Munich-Stuttgart corridor anchors industrial bakery demand for standardized granulated supply with pneumatic conveying systems.
United States
Louisiana and Florida cane belts supply Gulf Coast refineries, while FDA Nutrition Facts panel overhauls press reformulation transparency on added sugars content. Cargill's terminal-to-plant logistics infrastructure controls North American distribution through integrated rail and barge networks. Chicago and Atlanta metropolitan areas concentrate food processing demand for liquid sugar systems in carbonated beverage bottling.
Refined Cane Sugar Market Competitive Landscape
Premium-margin players sit above commodity-margin players across crystallization technology and certification tiers, with integrated crush-to-refine operations commanding price spreads over toll refiners. The vendor base stratifies into three strategic archetypes: multinational agribusiness conglomerates with terminal infrastructure, cooperative mill groups with origin-proximate logistics, and specialized liquid sugar system providers with just-in-time tanker capabilities. Dominant competitive moves include backward integration into cane crushing assets and geographic expansion through port terminal acquisitions.
Within the multinational infrastructure tier, Südzucker AG anchors European bulk supply relationships through its milling network, while Cargill exemplifies North American distribution control via integrated logistics. Tereos occupies a position among liquid sugar specialists competing on just-in-time tanker delivery systems. These three entities represent distinct competitive archetypes: integrated European refiner, Americas-focused agribusiness infrastructure, and beverage-centric liquid sugar system provider.
| Leading Market Players |
|---|
| Südzucker AG |
| Cargill |
| Tereos |
| Raizen S.A. |
| Wilmar International |
| Louis Dreyfus Company B.V. |
| Associated British Foods plc |
| Cosan SA |
| ASR Group International Inc. |
| Others |
Value Network & Pricing Analysis
Membrane filtration technology for direct liquid sugar production is compressing crystallization economics while concentrating supply control among Brazilian and Thai exporters capable of continuous processing investment. This manufacturing transition simultaneously elevates capital barriers for new entrants and tightens price premiums for food-grade certification tiers.
Pricing Analysis
Contract-based long-term offtake agreements dominate industrial procurement, with price differentiation anchored in REACH purity certification and RenovaBio carbon intensity scores. Cost compression in standard-grade granulated supply is intensifying because Brazilian mills divert crush capacity toward ethanol co-production. Food processing buyers exhibit highest price sensitivity due to quarterly contract renegotiation clauses, while specialty confectioners accept premium spreads for particle-size consistency guarantees.
Supply Chain Analysis
EU food-grade certification gating restricts market access to Brazilian, Thai, and Indian mills with dedicated processing lines and third-party laboratory validation. Raw cane supply draws from São Paulo state's sugar-ethanol complex, Khon Kaen province crushing clusters, and Maharashtra cooperative mills. Single-source vulnerability concentrates in Thailand's 12% global export share when El Niño patterns disrupt harvest schedules. Distribution runs through integrated terminal-to-plant logistics networks controlled by multinational agribusiness infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The refined cane sugar market reads as a late-cycle quality story where beverage manufacturer automation and EU carbon border adjustments are redirecting procurement toward certified low-carbon liquid sugar systems.
For Market Incumbents: To counter ethanol diversion under Brazil's RenovaBio mandates, deepen backward integration into captive cane crushing assets in São Paulo and Ribeirão Preto corridors while securing ANVISA-certified food-grade processing lines. Prioritize tanker-based logistics infrastructure for just-in-time beverage manufacturer contracts.
For New Entrants and Emerging Players: Launch via direct-to-bakery distribution models bypassing traditional commodity traders in Germany's Mittelstand bakery sector and Vietnam's Ho Chi Minh City confectionery clusters. Target liquid sugar system retrofit opportunities among Southeast Asian bottlers seeking automated bulk tanker receipt.
For Investors and Strategic Acquirers: Valuations sit cheapest among cooperative mill groups with origin-proximate logistics but underinvested certification infrastructure. Long-term viability hinges on carbon intensity verification capabilities for EU Green Deal CBAM compliance. Monitor RenovaBio credit pricing as inflection indicator for Brazilian food-grade sucrose export availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cane Crushing | Captive supply from São Paulo mills secures volume under RenovaBio diversion pressure. |
| Liquid Sugar System Retrofit | Bulk tanker receipt eliminates bag handling for Coca-Cola and Pepsi bottlers in Mexico. |
| Carbon Intensity Certification | Verified low-carbon ethanol co-production unlocks preferential EU CBAM market access. |
| Direct-to-Bakery Distribution | Tanker delivery bypasses distributor markups for mid-sized European industrial bakeries. |
| Micronutrient Fortification Investment | Integrated vitamin A delivery systems capture FSSAI premium positioning in India. |
Research Methodology
Direct dialogue with sugar mill operations directors, beverage procurement managers, industrial bakery supply chain leads, and EU import certification specialists grounded qualitative findings in operational reality. Secondary validation drew from ANVISA regulatory filings, FSSAI fortification directives, customs and trade flow databases, and SEC disclosures from listed agribusiness conglomerates. Bottom-up volume modeling and top-down macroeconomic triangulation converged on segment-level estimates.
Output projections across the analysis window reflect a demand-side build from beverage automation adoption curves, confectionery capacity expansion in Vietnam, and bakery cooperative purchasing consolidation in Germany. Segmentation dimensions encompassed product format, end-use application, customer type, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted price-volume relationships and crush-to-refine capacity utilization assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained El Niño disruption or accelerated RenovaBio mandate expansion. Model outputs reflect documented assumptions on ethanol-sugar price parity and EU carbon border adjustment implementation timelines. A model refresh is warranted upon material change in Brazilian biofuel policy or Thai export reliability metrics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
China Saccharin Market
Sweeteners
Specialty Sweeteners Market
Sweeteners
Sucrose Esters Market
Sweeteners
Dry Molasses Market
Sweeteners
Global Cane Molasses Market
Sweeteners
Tagatose Market
Sweeteners
United Kingdom Food Sweetener Market
Sweeteners
Polyphenol Sweetener Market
Sweeteners
Nutritive Sweeteners Market
Sweeteners
Food Sweetener Market
Sweeteners
Argentina Food Sweetener Market
Sweeteners
Xylitol Market
Sweeteners
Glucose, Dextrose, and Maltodextrin Market
Sweeteners
Spain Food Sweetener Market
Sweeteners
Allulose Market
Sweeteners
Middle East and Africa Sugar Substitutes Market