
 Global Food and Beverage Processing Equipment Market | 2026-2036
Global Food and Beverage Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Food and Beverage Processing Equipment Market Intelligence
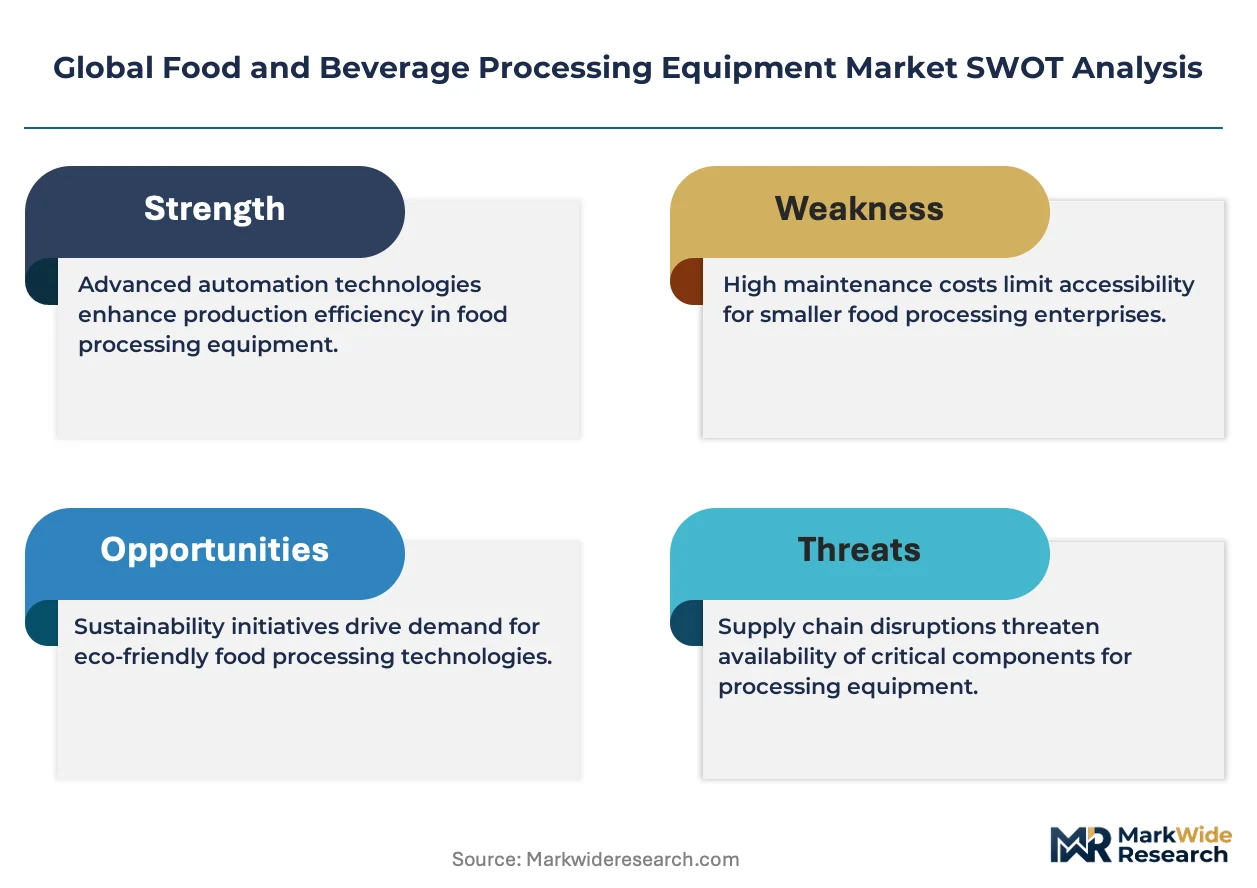
Stainless steel is realigning equipment economics as food-grade alloys replace carbon-steel components in high-acid processing environments. Bühler AG leverages its Swiss manufacturing base to dominate grain and chocolate processing systems. GEA Group anchors its position through captive supply of hygienic pump technologies for dairy applications. Tetra Laval competes via integrated aseptic filling and packaging architectures that reduce downstream contamination risk.
Food and beverage processing equipment encompasses mechanical, thermal, and control systems engineered to transform raw agricultural inputs into packaged consumables, typically operating at pressures up to 10 bar and temperatures ranging from cryogenic freezing to 140°C sterilization cycles, with surface finishes meeting Ra 0.8 μm hygiene standards. Pasteurizers and homogenizers command mature margin pools in dairy processing, while IoT-integrated sensor networks represent the fastest-expanding technology tier as real-time HACCP monitoring becomes standard. Fillers sustain structural importance in carbonated beverage bottling where throughput rates above 80,000 bottles per hour determine capital allocation decisions.
FDA food safety modernization rules and EU MDR compliance for processing machinery with integrated measurement functions are tightening material traceability and clean-in-place validation requirements across export-oriented facilities. China's SAMR food production licensing and GB standards for stainless steel contact surfaces are reshaping supplier qualification protocols for equipment entering Asian markets. Stakeholders must weigh energy-efficient system retrofits against full line replacements as carbon accounting penetrates procurement criteria.
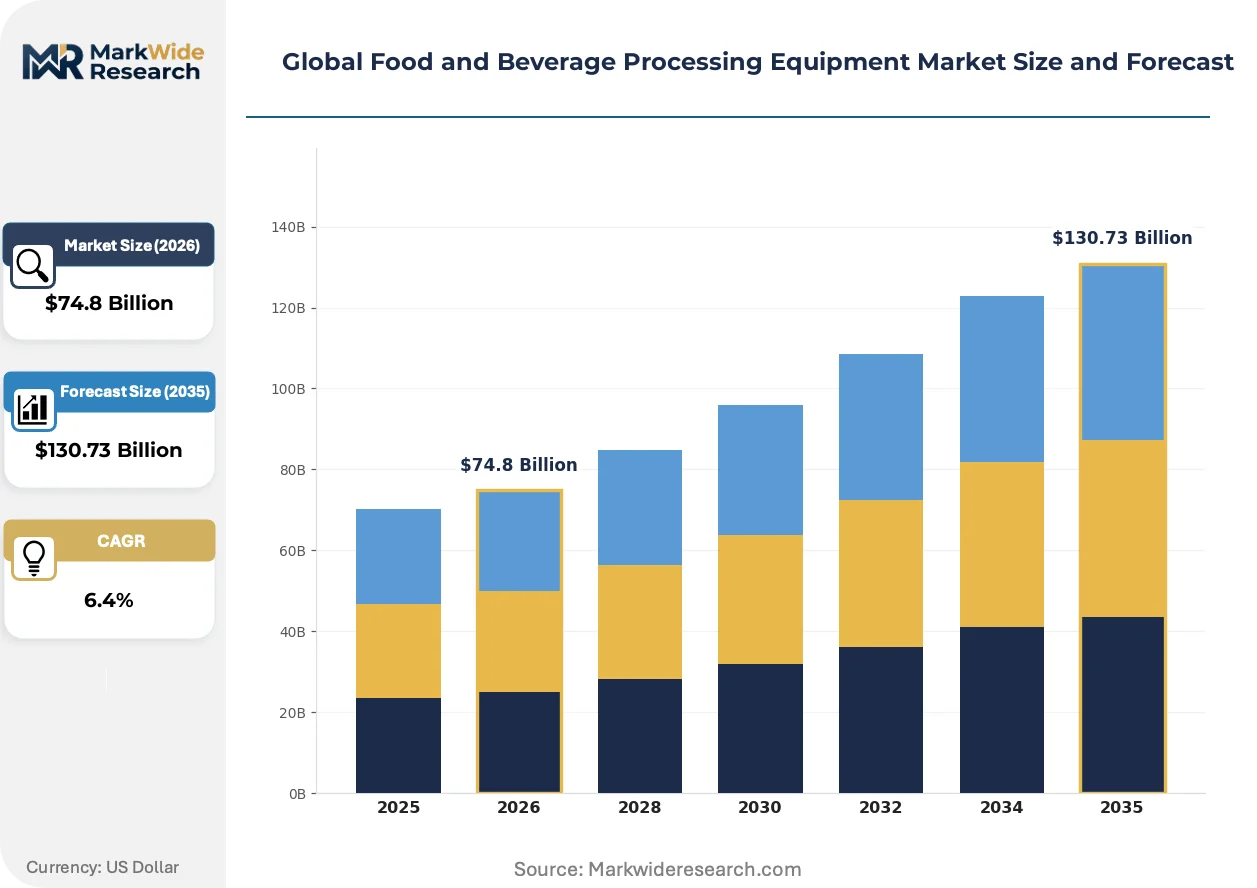
Market Dynamics
Automated pasteurizer fleets are expanding across dairy processing networks as cold-chain integrity mandates tighten, forcing capital redeployment toward hygienic pump technologies and aseptic filling architectures that reduce downstream contamination exposure.
Growth Catalysts
- EU F-Gas Regulation:Equipment upgrade cycles across European dairy and beverage facilities are accelerating as phasedown schedules for hydrofluorocarbon refrigerants force replacement of legacy thermal systems.
- IoT-integrated sensor networks:Real-time HACCP monitoring is becoming standard specification in export-oriented plants, pulling demand for control systems with embedded predictive maintenance capabilities.
- German precision engineering clusters:Turnkey processing line exports to emerging markets are concentrating procurement decisions around Stuttgart and Munich supplier networks.
Market Restraints
- Nickel price volatility:Food-grade 316L stainless steel input costs fluctuate with LME nickel contracts, compressing margins on long-lead equipment orders.
- REACH compliance documentation:Material traceability requirements for processing machinery create administrative friction for Asian suppliers seeking European market access.
- Technical skill concentration:Clean-in-place validation expertise resides primarily with Swiss and German engineering services, creating bottlenecked implementation timelines.
Strategic Opportunities
- India FSSAI modernization:Food production licensing reforms are opening import pathways for automated filling and packaging lines previously blocked by local content mandates.
- Carbon accounting penetration:Energy-efficient retrofit specifications are displacing full line replacement decisions in mature European facilities.
- Blockchain-IoT convergence:Immutable batch records tied to sensor telemetry are creating premium pricing tiers for equipment with integrated data integrity architectures.
Industry Challenges
- Control systems integration:Legacy SCADA architectures in established dairy plants resist seamless interfacing with modern IoT sensor networks, extending commissioning timelines.
- CE-MDR dual certification:Processing machinery with integrated measurement functions faces overlapping validation requirements that delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Food and Beverage Processing Equipment Market |
| Market Size in 2026 | $74.8 Billion |
| Market Size in 2035 | $130.73 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mixers, Pasteurizers, Homogenizers, Fillers, Separators Technology: Automation, Robotics, IoT Integration, Energy-efficient Systems, Sensor Technology Application: Dairy Processing, Brewing, Meat & Poultry, Confectionery, Snack Production End User: Food Processors, Beverage Manufacturers, Contract Packagers, Research Institutes, Culinary Schools |
| Companies Covered | Bühler AG, JBT Corporation, Tetra Laval, KHS GmbH, SPX FLOW, GEA Group, Alfa Laval, Marel, KRONES, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Food and Beverage Processing Equipment Market Strategic Shifts & Innovations
Equipment architectures are reconfiguring around data-centric operating models where real-time batch traceability and predictive hygiene monitoring displace scheduled maintenance paradigms.
Electropolished 316L stainless steel surfaces with Ra 0.8 μm finishes are converging with automated weld inspection systems to eliminate manual verification bottlenecks in high-acid processing environments. Juice and sauce manufacturers in California and São Paulo are specifying these combined material-quality architectures in new capital requests. The convergence is compressing supplier qualification timelines from 18-month validation cycles toward 90-day equipment acceptance protocols.
China's SAMR food production licensing and GB standards for stainless steel contact surfaces are reshaping supplier qualification protocols for equipment entering Asian markets. Domestic certification requirements now mandate third-party metallurgical testing that duplicates European REACH documentation. Multinational dairy processors are responding by pre-qualifying dual-certified component suppliers in Shanghai and Tianjin free-trade zones.
After-sales service unbundling is fragmenting traditional full-service contracts into discrete modules for spare parts, remote diagnostics, and on-site technical intervention. Carbonated beverage bottlers in Mexico and Indonesia are selecting à la carte maintenance tiers based on line criticality rather than uniform coverage. This pattern is most visible in high-throughput facilities above 60,000 bottles per hour where downtime costs justify premium remote monitoring subscriptions.
Global Food and Beverage Processing Equipment Market Segmentation
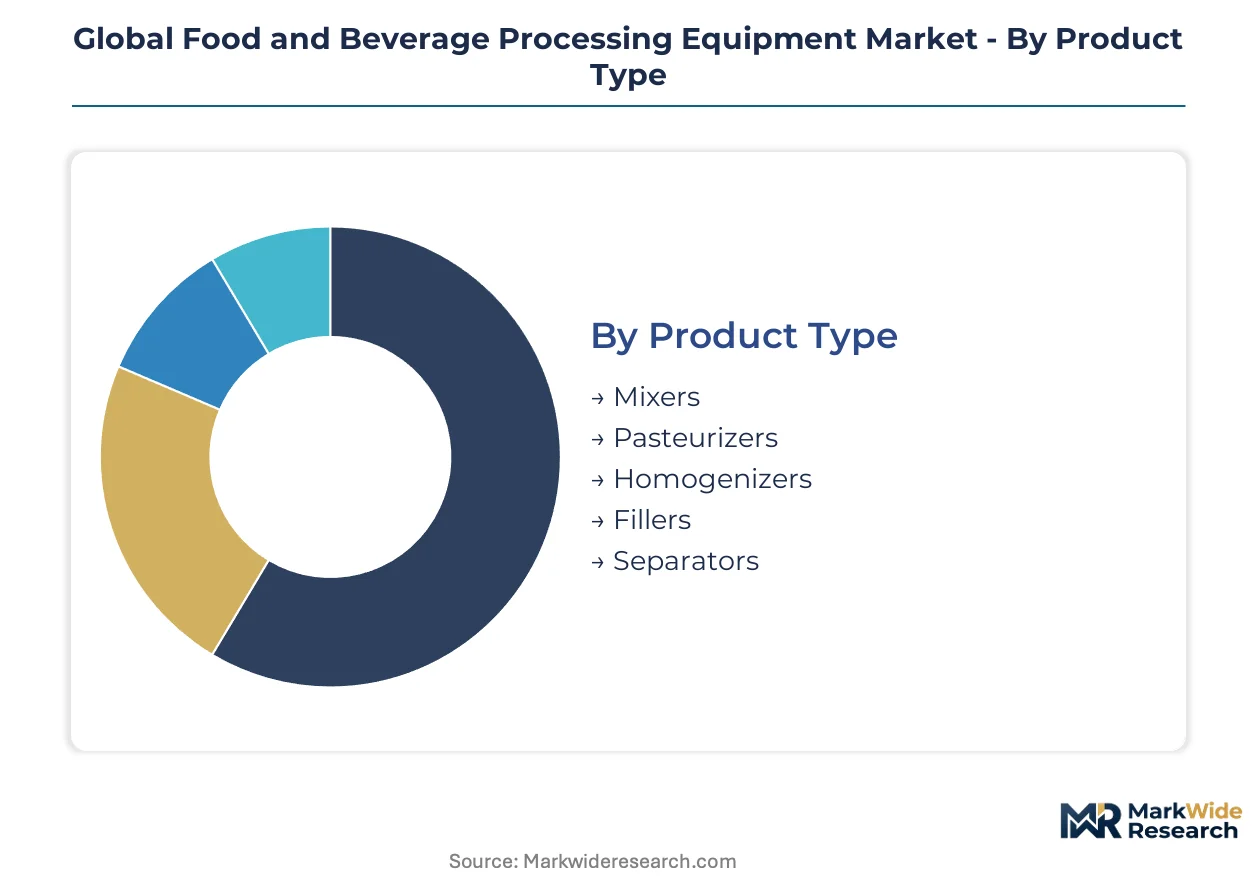
Equipment segmentation in food and beverage processing reveals divergent margin structures across thermal systems versus control architectures. Procurement patterns increasingly favor integrated technology stacks over standalone mechanical units.
Product Type:
Volume concentration sits with mature processing equipment where standardization compresses pricing, while premium tiers attach to precision thermal systems with validated clean-in-place protocols.
- Pasteurizers:Thermal processing units operating at 72-85°C for HTST protocols or 135-150°C for UHT cycles, with plate heat exchanger configurations dominating dairy retrofit decisions. Demand clusters in German and Dutch dairy cooperatives upgrading to meet EU F-Gas refrigerant phaseout schedules.
- Homogenizers:High-pressure valve systems operating at 100-250 bar to reduce fat globule diameter below 2 μm, essential for extended shelf-life milk products. Italian and Spanish mozzarella processors are expanding homogenizer capacity to serve export markets requiring 45-day refrigerated distribution windows.
- Mixers:Batch and continuous configurations for ingredient dispersion, with scraped-surface designs specified for high-viscosity sauces and dressings.
- Fillers:Volumetric and gravimetric dispensing systems, with aseptic rotary designs commanding premium positioning in extended-shelf-life juice applications.
- Separators:Centrifugal clarifiers and cream separators, with disc-stack geometries standard in whey protein concentration lines.
Today's leader: Pasteurizers. Tomorrow's challenger: Homogenizers.
Technology:
Application context determines technology stack selection, with export-oriented facilities prioritizing traceability architectures over standalone automation.
- IoT Integration:Sensor networks with embedded HACCP logging, cloud-connected predictive maintenance modules, and API-ready SCADA interfaces. Brazilian orange juice processors and Thai coconut water bottlers are mandating IoT-ready equipment to satisfy Walmart and Costco supplier audit requirements.
- Automation:Programmable logic controllers with recipe management systems, reducing changeover times in multi-SKU facilities. US craft brewers in Colorado and Oregon are automating cellar operations to maintain consistency across distributed taproom networks.
- Robotics:Articulated arm systems for palletizing and pick-and-place operations, with collaborative robot deployments accelerating in mid-scale bakeries.
- Energy-efficient Systems:Heat recovery modules and variable-frequency drives, specified under corporate carbon reduction commitments.
- Sensor Technology:Inline refractometers, turbidity probes, and metal detection arrays for real-time quality verification.
Current procurement prioritizes IoT Integration. Automation offers the steepest expansion trajectory as labor costs rise in Eastern European processing zones.
Application:
Margin profiles diverge sharply between regulated dairy environments and artisanal brewing segments with shorter validation cycles.
- Dairy Processing:Integrated lines spanning raw milk reception through packaged goods, with 3-A sanitary standards and EHEDG certification mandatory for export eligibility. Australian and New Zealand processors are consolidating toward fewer, larger facilities with 500,000+ liter daily throughput.
- Brewing:Mash tuns, lauter systems, and fermentation tanks, with craft segment demand fragmenting across 10-50 hectoliter brewhouse configurations. UK and German microbreweries are specifying skid-mounted systems to accelerate licensing timelines.
- Meat & Poultry:Grinding, mixing, and forming equipment with USDA-FSIS compliant sanitary design, expanding in Brazilian and Thai export processing zones.
- Confectionery:Tempering, enrobing, and depositing systems, with precision temperature control critical for cocoa butter polymorphism management.
- Snack Production:Extruders, fryers, and seasoning application systems, with oil filtration recovery technologies gaining specification in North American potato chip facilities.
Dairy Processing commands current capital allocation. Brewing represents the fastest-climbing application as premium beverage portfolios expand.
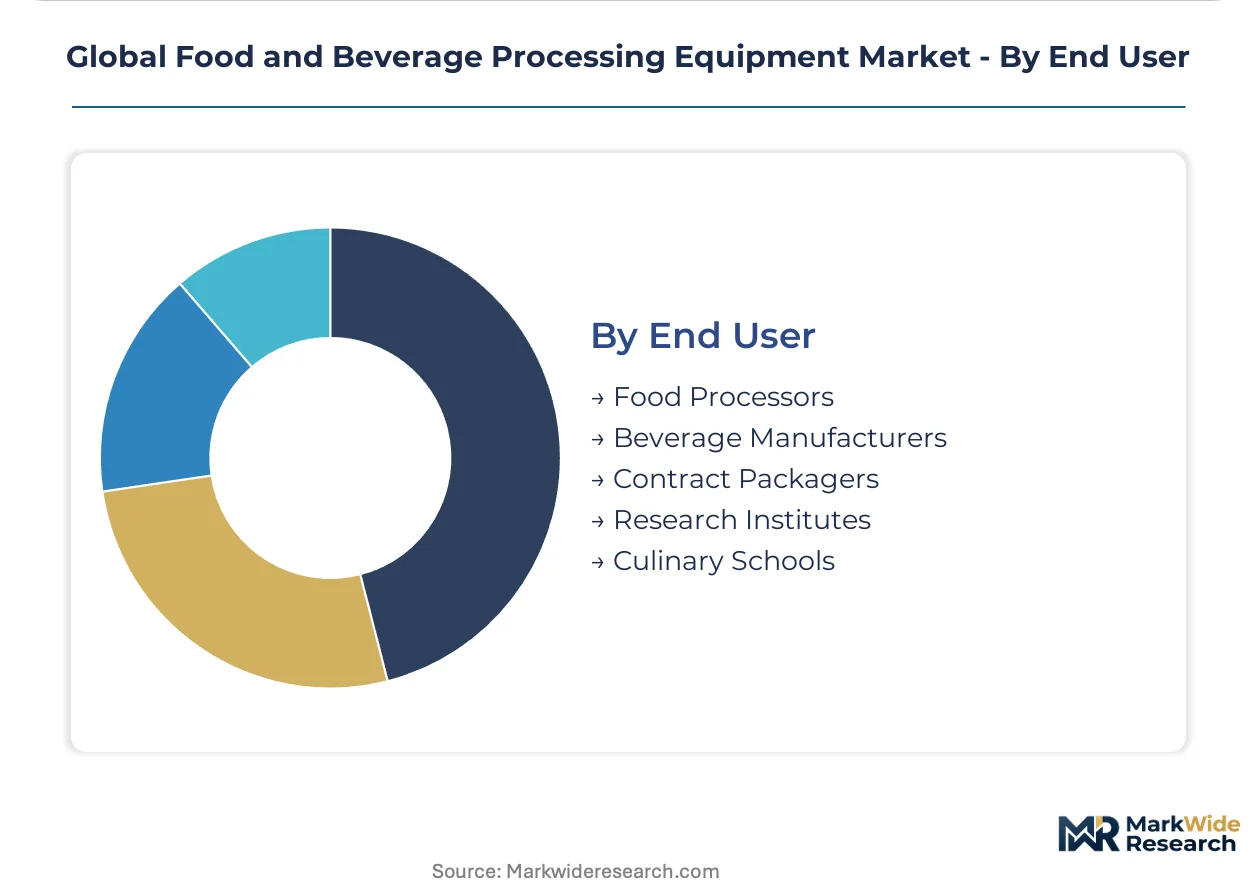
End User:
Customer scale determines service model economics, with enterprise processors internalizing maintenance capabilities that contract packagers must outsource.
- Food Processors:Integrated manufacturing operations with captive engineering teams, specifying equipment with 20-year lifecycle support commitments. Nestlé and Unilever procurement frameworks are standardizing on suppliers with dual-certified European and Chinese service networks.
- Beverage Manufacturers:Carbonated soft drink, juice, and bottled water operations, with Coca-Cola and PepsiCo franchised bottlers driving standardization toward common equipment platforms.
- Contract Packagers:Toll manufacturing operations serving multiple brand owners, requiring rapid format changeover capabilities and flexible line configurations.
- Research Institutes:Pilot-scale systems for product development and process optimization, with university food science departments in California and Wageningen specifying tabletop processing units.
- Culinary Schools:Training equipment with simplified controls and enhanced safety interlocks, primarily sourced through educational distributor channels.
Food Processors anchor present demand. Contract Packagers are gaining share fastest as brand owners divest manufacturing assets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering clusters around Stuttgart and Munich supply turnkey processing lines to emerging markets, anchoring European equipment export flows. Dairy cooperatives in the Netherlands and Denmark upgrade automated pasteurizer fleets to meet EU F-Gas refrigerant phaseout mandates. Brazilian orange juice processors and Thai coconut water bottlers mandate IoT-ready equipment to satisfy North American retail audit requirements.
United States
California juice processors and Wisconsin dairy cooperatives drive capital deployment toward electropolished 316L stainless steel systems with Ra 0.8 μm finishes. FDA food safety modernization rules tighten material traceability and clean-in-place validation requirements across export-oriented facilities. The Pacific Northwest craft brewing corridor specifies skid-mounted brewhouse configurations to accelerate state licensing timelines.
Germany
Baden-Württemberg and Bavaria host precision engineering clusters supplying turnkey processing lines to India and Southeast Asia. EU F-Gas Regulation phasedown schedules for hydrofluorocarbon refrigerants force replacement of legacy thermal systems in dairy and beverage facilities. Stuttgart-based hygienic pump technology providers anchor captive supply relationships with multinational dairy processors.
China
Yangtze River Delta free-trade zones in Shanghai and Tianjin pre-qualify dual-certified component suppliers for multinational dairy processors. SAMR food production licensing and GB standards for stainless steel contact surfaces mandate third-party metallurgical testing duplicating European REACH documentation. Domestic equipment buyers increasingly specify automated filling lines previously blocked by local content mandates.
India
Maharashtra and Gujarat food processors expand automated filling and packaging capacity following FSSAI production licensing reforms. Import pathways for European turnkey lines opened after local content mandate relaxation. Mumbai-based contract packagers select à la carte maintenance tiers based on line criticality rather than uniform coverage models.
Brazil
São Paulo orange juice processors mandate IoT-integrated sensor networks to satisfy Walmart and Costco supplier audit requirements. ANVISA sanitary standards align with FDA modernization rules for export eligibility. Minas Gerais dairy cooperatives expand homogenizer capacity to serve markets requiring 45-day refrigerated distribution windows.
Global Food and Beverage Processing Equipment Market Key Industry Players
Capacity expansion dominates the current landscape as European and Asian fabricators scale electropolishing and automated weld inspection capabilities to compress 18-month validation cycles toward 90-day acceptance protocols. The vendor base stratifies across three archetypes: Swiss-German precision engineering houses with captive hygienic technologies, Nordic specialists in thermal and separation systems, and diversified industrial conglomerates with integrated packaging architectures. Geographic expansion and technology licensing represent the dominant competitive moves, with established players establishing dual-certified service networks in Chinese free-trade zones.
Among Swiss-German precision engineering houses, Bühler AG and GEA Group exemplify the integrated technology stack archetype combining mechanical processing systems with captive component supply. Tetra Laval occupies a distinct position bridging aseptic filling equipment with packaging architectures. These three anchors illustrate how competitive positioning increasingly depends on validated clean-in-place protocols and dual-certification pathways for Asian market entry rather than standalone equipment specifications.
| Leading Market Players |
|---|
| Bühler AG |
| JBT Corporation |
| Tetra Laval |
| KHS GmbH |
| SPX FLOW |
| GEA Group |
| Alfa Laval |
| Marel |
| KRONES |
| Others |
Cost & Logistics Intelligence
Multinational dairy processors with captive engineering teams command project-based pricing leverage that compresses margins on long-lead equipment orders. Their procurement frameworks standardize on suppliers with dual-certified European and Chinese service networks, forcing tiered pricing stratification across premium, standard, and economy performance tiers.
Pricing Analysis
Input-cost pass-through from LME nickel contracts drives volatility in food-grade 316L stainless steel component pricing. Three-tier pricing structure across premium, standard, and economy levels separates EHEDG-validated systems from basic sanitary configurations. Cost compression in standard-tier thermal equipment is intensifying because Asian fabricators are scaling electropolishing capabilities. Contract packagers with outsourced maintenance functions exhibit highest price sensitivity, while integrated food processors prioritize lifecycle support commitments over upfront capital expenditure.
Supply Chain Analysis
Reverse-logistics flows for refurbishment and remanufacturing of high-pressure homogenizer valve assemblies concentrate in Stuttgart and Munich engineering clusters. Component fabrication draws from Germany, Switzerland, and Chinese free-trade zones in Shanghai and Tianjin. Supply chain risk centers on single-source vulnerability for precision hygienic pump technologies held by Swiss-German precision engineering houses. Distribution runs through turnkey processing line integrators serving emerging market dairy cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU F-Gas refrigerant phasedown schedules accelerate European upgrade cycles while India's FSSAI modernization opens import pathways at lower compliance cost structures.
For Market Incumbents: Hedge against margin erosion in standard-tier pasteurizers by deepening captive supply of hygienic pump technologies and accelerating dual-certification investments for SAMR and REACH compliance. Defensive consolidation through pre-qualified component supplier networks in Yangtze River Delta free-trade zones mitigates Asian market entry friction. For New Entrants and Emerging Players: Launch via à la carte aftermarket service modules targeting Mumbai-based contract packagers with discrete remote diagnostics and spare parts tiers. White-space concentration sits with IoT-integrated sensor networks for Brazilian orange juice processors facing Walmart supplier audit mandates. Skid-mounted brewhouse configurations for UK microbreweries offer fastest penetration pathway. For Investors and Strategic Acquirers: Precision engineering houses with validated clean-in-place protocols are the most active acquirer in this space, consolidating automated weld inspection capabilities to compress validation cycles. Long-term viability over a multi-year horizon rests on blockchain-IoT convergence for immutable batch records. Monitor CE-MDR dual certification timelines as inflection indicator for European market entry delays.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | REACH and SAMR alignment unlocks multinational dairy processor procurement frameworks. |
| Electropolishing Capacity Expansion | Ra 0.8 μm finish capabilities compress supplier qualification toward 90-day acceptance protocols. |
| IoT Sensor Network Integration | Real-time HACCP logging satisfies Walmart and Costco supplier audit requirements in São Paulo. |
| Aftermarket Service Unbundling | Discrete maintenance tiers match downtime cost profiles in high-throughput Mexican bottling facilities. |
| Heat Recovery Module Deployment | Energy-efficient retrofits displace full line replacements under corporate carbon reduction commitments. |
Research Approach
Multiple input streams — primary interviews with plant engineers and OEM procurement teams, secondary validation through customs records and SEC filings, and technical documentation from 3-A sanitary standards — were reconciled across bottom-up and top-down triangulation. Conversations with maintenance directors, aftermarket service heads, and dairy cooperative technical managers informed equipment lifecycle assumptions. Trade data from German engineering export associations and Chinese SAMR certification databases anchored regional demand calibration.
Data-stream reconciliation across the projection horizon applied multi-dimensional segmentation modeling across equipment type, technology tier, application vertical, and end-user scale. CAGRs were derived from installed base growth rates and replacement cycle analysis. Forecast inputs incorporated EU F-Gas phasedown schedules, FSSAI licensing reform implementation timelines, and nickel price volatility bands.
Forecast precision tightens around the base case; tail outcomes carry wider variance under acute LME nickel price spikes or extended CE-MDR dual certification delays. Practitioners should monitor ANVISA-FDA alignment progress and blockchain-IoT pilot deployments for early signals of premium pricing tier expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Distillation Analyzer Market
Food Processing Equipment
Smart Bread Machine Market
Food Processing Equipment
Industrial Food Slicers Market
Food Processing Equipment
Food Extruder Market
Food Processing Equipment
Plastic Processing Machinery Market
Food Processing Equipment
Brewing Thermometer Market
Food Processing Equipment
Ice Flaking Machine Market
Food Processing Equipment
Global Starch Recovery Systems Market
Food Processing Equipment
Automatic Deboner Market
Food Processing Equipment
Mixer Settler Market
Food Processing Equipment
Coconut Crushers Market
Food Processing Equipment
Commercial Mixer Market
Food Processing Equipment
Convection Ovens Market
Food Processing Equipment
North America Cold Storage Market
Food Processing Equipment
Philippines Cold Storage Warehouse Market
Food Processing Equipment
Individual Quick Freezing Market