
 Sugar Free Lifesavers Market | 2026-2036
Sugar Free Lifesavers Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar Free Lifesavers Market Analytics
The EU Green Deal's Farm to Fork strategy is restructuring sugar-reduction targets across European food manufacturing. Nestlé S.A. leverages its zero-sugar R&D pipeline to anchor premium positioning in pharmacy and wellness channels. Perfetti Van Melle dominates hard-candy formats through specialized sugar-alcohol stabilization technology that extends shelf stability without crystallization defects.
Sugar free lifesavers denote confectionery products formulated with non-nutritive sweeteners such as sorbitol, xylitol, or stevia glycosides in place of sucrose, manufactured via controlled cooling and aeration processes to achieve characteristic dissolution profiles. These products serve consumers managing glycemic response, dental caries risk, or caloric intake restriction. The hard candy segment leads volume due to lower production complexity and longer ambient stability, while the mint flavor profile captures disproportionate margin pools through breath-freshening functional claims and higher pharmacy channel penetration. Online retailers represent the fastest-growing distribution channel as subscription-based replenishment models gain traction among diabetic and ketogenic-diet adherents.
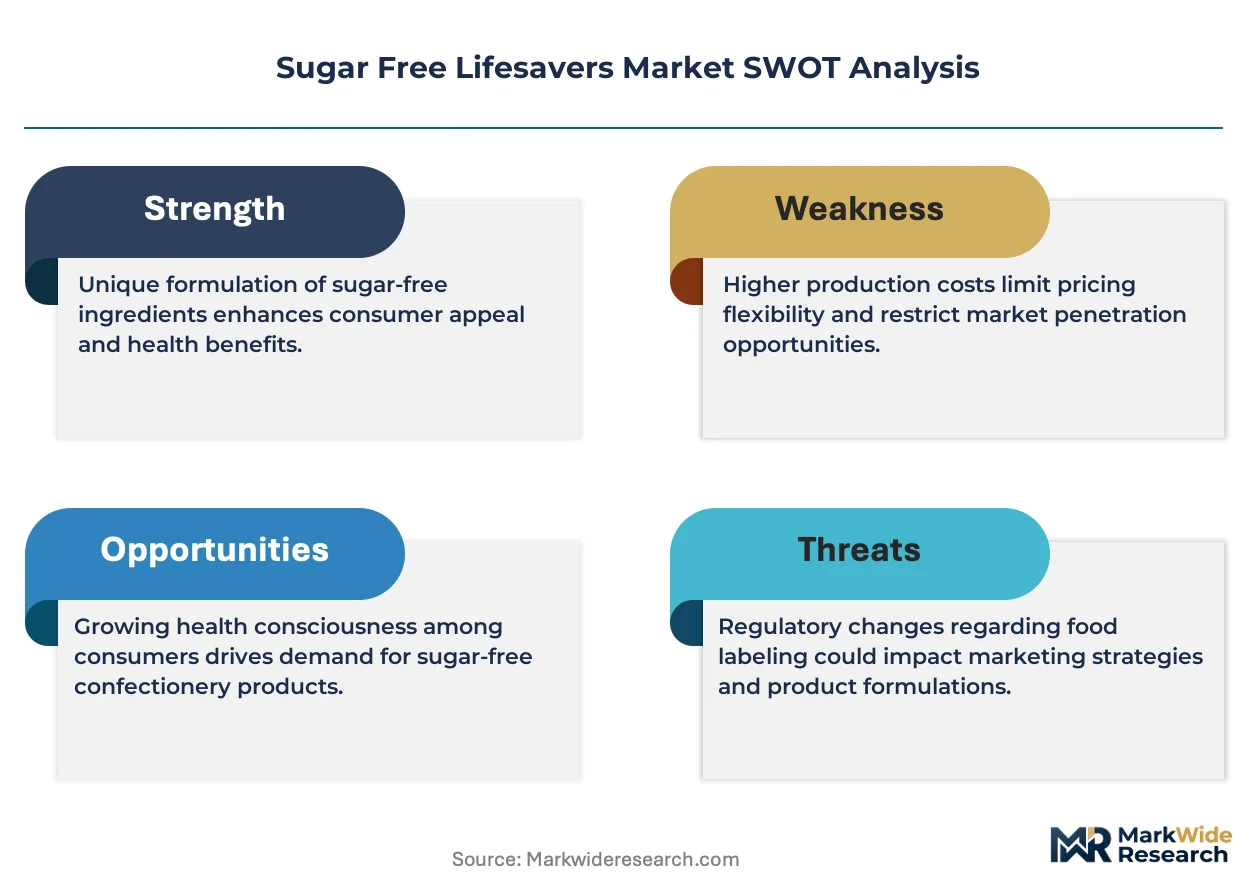
FDA nutrition labeling mandates, EU Health Claims Regulation enforcement, and WHO sugar intake guidelines collectively constrain permissible sweetness claims and drive reformulation investments. The F-Gas Regulation indirectly pressures cooling-dependent manufacturing by restricting hydrofluorocarbon-based refrigeration systems used in candy conditioning tunnels. Stakeholders must monitor evolving sweetener safety assessments and dual-listing requirements across pharmacy and food retail channels to anticipate compliance cost trajectories.
Market Dynamics
Reformulation investments driven by WHO sugar intake guidelines and FDA nutrition labeling mandates are compressing profit margins while accelerating product line turnover across confectionery portfolios.
Growth Catalysts
- EU Nutrition and Health Claims Regulation:Germany's sugar-reduction mandates are forcing retailer shelf-space reallocation toward reduced-calorie confectionery, expanding distribution access for compliant products.
- Ketogenic-diet adherence:Subscription-based replenishment models targeting diabetic consumers through online channels are generating recurring revenue streams with lower customer acquisition costs.
- Pharmacy channel penetration:Breath-freshening functional claims in mint flavor profiles are capturing disproportionate margin pools through wellness-oriented retail positioning.
Market Restraints
- Sugar-alcohol input volatility:Sorbitol and xylitol supply chains face price instability due to corn-derived feedstock fluctuations and biofuel competition for agricultural inputs.
- F-Gas Regulation compliance:Hydrofluorocarbon-based refrigeration restrictions are forcing capital-intensive retooling of candy conditioning tunnels across European manufacturing facilities.
- Crystallization defect risk:Technical limitations in sugar-alcohol stabilization technology create batch inconsistency that elevates quality control costs for hard-candy formats.
Strategic Opportunities
- Steavia glycoside adoption:Plant-derived sweetener convergence with clean-label positioning is opening premium pricing tiers in natural-product retail channels.
- Dual-listing requirements:Pharmacy and food retail channel overlap is creating bundled distribution opportunities for products with glycemic management claims.
- Cooling-dependent manufacturing:Aeration process innovations that reduce energy intensity are qualifying operations for EU Green Deal Farm to Fork strategy incentives.
Industry Challenges
- Sweetener safety assessment timelines:Evolving EFSA and FDA evaluations of non-nutritive additives are extending product approval cycles and delaying market entry.
- Legacy system integration:Reformulation R&D pipelines require coordination between food science and pharmaceutical compliance teams with mismatched workflow protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar Free Lifesavers Market |
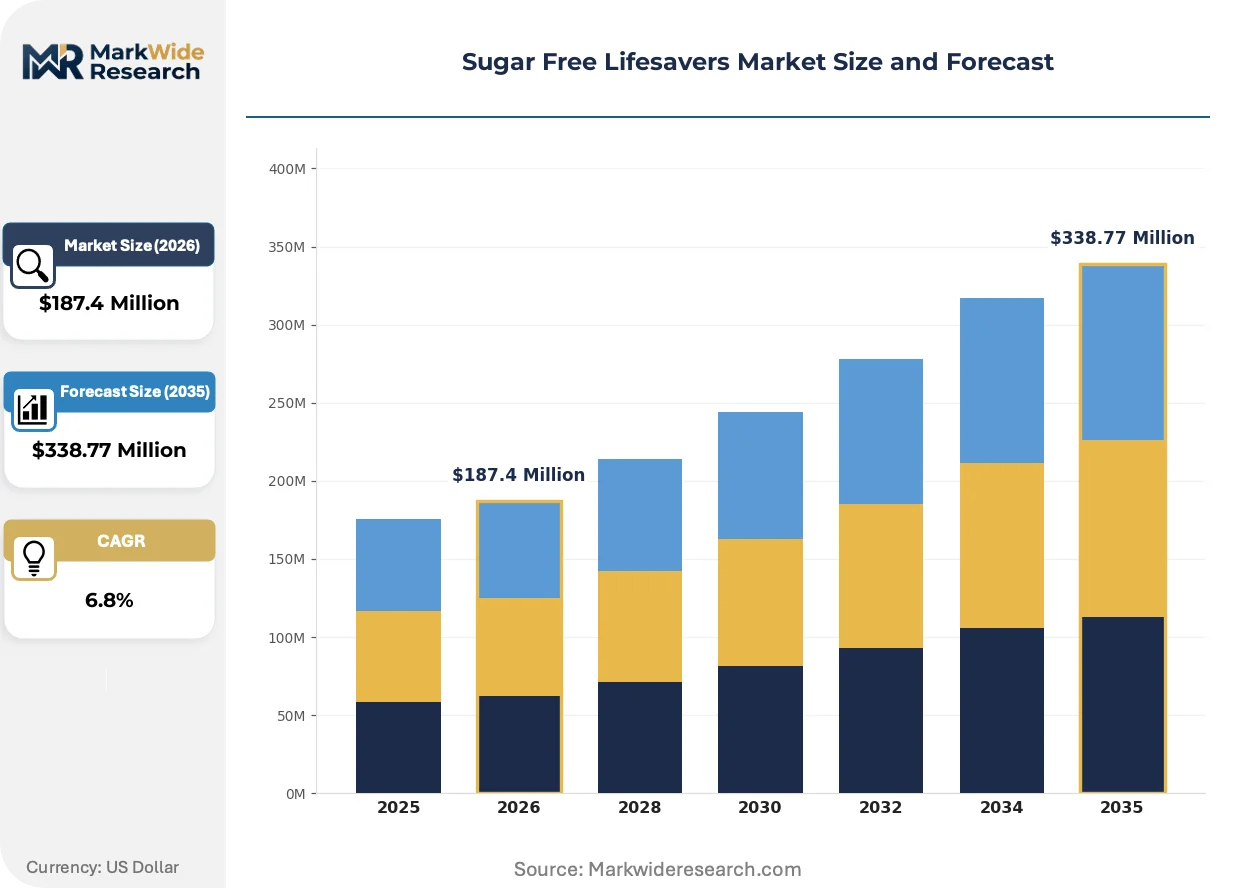
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Candy, Chewy, Hard, Gum Flavor Profile: Fruit, Mint, Chocolate, Tropical Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Drugstores End User: Adults, Children, Health Conscious, Diabetics |
| Companies Covered | Perfetti Van Melle, The Hershey Company, Nestlé S.A., Mars Incorporated, Mondelez International, PepsiCo, Wrigley Company, Ricola Ltd, Lotte Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar Free Lifesavers Market Evolving Landscape
Controlled cooling and aeration processes are being re-engineered to accommodate novel sweetener blends while preserving dissolution profiles that define consumer sensory expectations.
Stevia glycoside extraction and purification technology is converging with enzymatic modification processes to eliminate bitter aftertaste artifacts. Ketogenic-diet adherents and diabetic consumers are adopting these reformulated products at accelerating rates through direct-to-subscription channels. This convergence is compressing the premium pricing window for legacy sugar-alcohol formulations while enabling clean-label repositioning.
The FDA's updated nutrition labeling requirements for added sugars are mandating transparency that exposes hidden sweetener loads in competing products. Industrial consequence includes accelerated reformulation timelines and elevated R&D expenditure allocations. Hard-candy manufacturers serving the US market are responding by front-of-pack calorie callouts and pharmacy channel exclusivity arrangements.
Subscription-based replenishment models are displacing impulse-purchase patterns in convenience retail. Online retailers and specialized diabetic supply platforms are capturing diabetic and ketogenic-diet adherents through auto-ship programs with personalized flavor rotation. This behavioral shift is most visible in Germany and the United States where health-tracking app integrations enable consumption-pattern optimization.
Sugar Free Lifesavers Market Segmentation
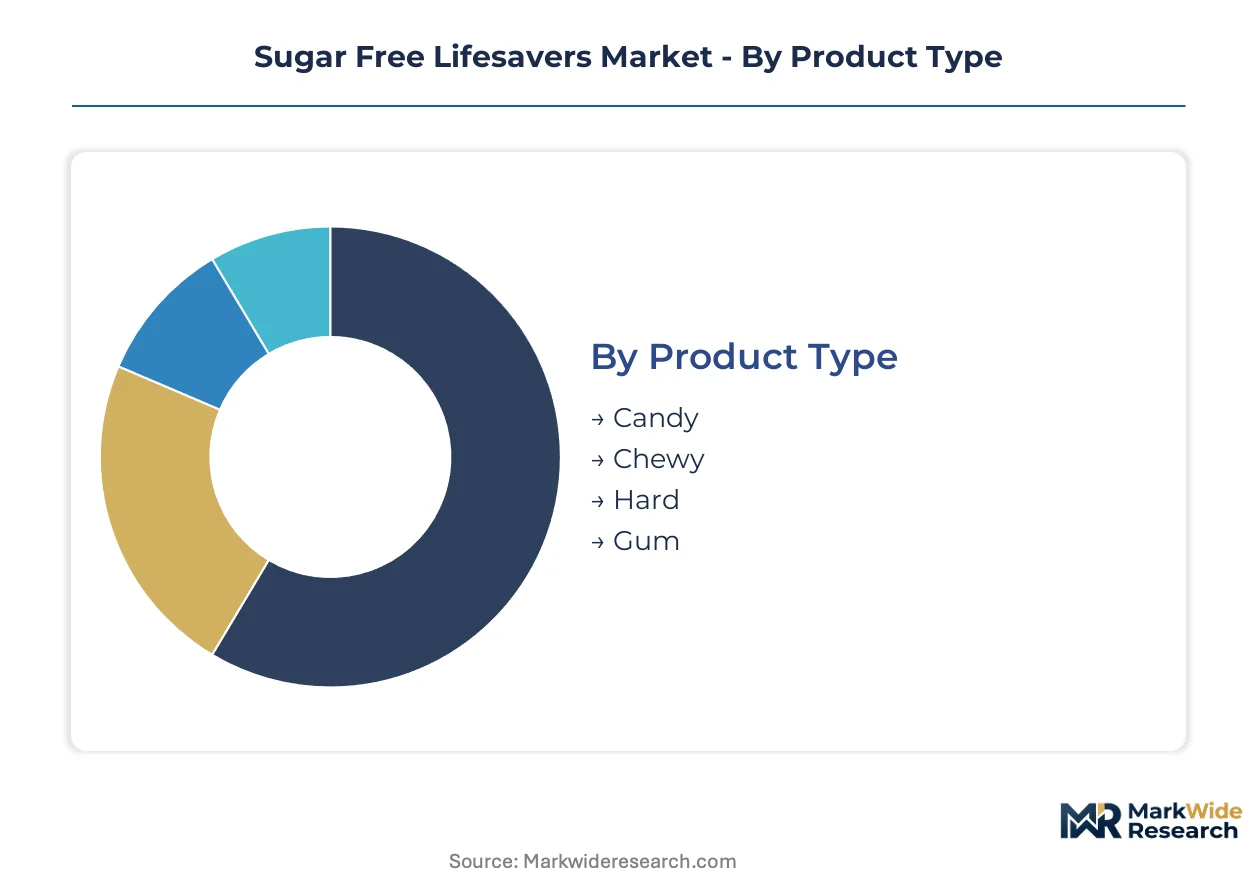
Segmentation in sugar-free confectionery determines capital allocation across formulation technologies, cooling infrastructure, and channel-specific packaging lines. Manufacturers prioritize segments with pharmacy channel access and subscription-model compatibility over impulse-retail formats.
Product Type:
Hard candy production demands the lowest capital intensity due to simplified aeration and conditioning tunnel requirements, while chewy formats require specialized extrusion and moisture-barrier packaging investments.
- Hard:Controlled cooling processes crystallize sugar-alcohol matrices into stable glassy structures with extended ambient shelf life. Demand concentrates among diabetic consumers in Germany seeking pharmacy-channel breath-freshening products with glycemic management claims.
- Candy:Compressed tablet formats integrate sorbitol and xylitol through direct compaction, minimizing thermal processing. Wellness-oriented adults in the United States drive procurement through online subscription platforms with auto-replenishment algorithms.
- Chewy:Requires hydrocolloid stabilization and moisture-retentive packaging to prevent sugar-alcohol recrystallization.
- Gum:Demands specialized gum-base compounding and sustained-release sweetener encapsulation systems.
Most installed capacity flows through Hard. Expansion is steepest in Candy.
Flavor Profile:
Flavor selection governs raw material sourcing geography, with mint oils concentrating in specific growing regions and tropical extracts requiring extended supply chains from equatorial suppliers.
- Mint:Menthol and peppermint oil formulations deliver breath-freshening functional claims that command pharmacy channel placement. Health-conscious adults in Germany and the United States generate disproportionate margin capture through wellness retail positioning and dual-listing arrangements.
- Fruit:Berry and citrus profiles rely on natural and nature-identical flavor systems with clean-label positioning potential. Children and parental purchasers in the United States favor these formats for reduced-calorie lunchbox inclusion.
- Chocolate:Requires fat-compatible sweetener systems and tempering process adaptation for sugar-alcohol stability.
- Tropical:Pineapple and mango extracts source from Southeast Asian supply chains with seasonal availability constraints.
Mint captures the highest per-unit margins. Fruit is climbing the fastest among flavor investments.
Distribution Channel:
Channel selection determines packaging format, case configuration, and promotional spend allocation, with pharmacy and online channels requiring distinct compliance documentation and fulfillment infrastructure.
- Drugstores:Pharmacy channel placement demands glycemic management claim substantiation and dual-listing compliance across food and pharmaceutical regulatory frameworks. Diabetic consumers in Germany drive volume through pharmacy loyalty programs and insurance-adjacent purchasing.
- Online Retailers:Subscription-based replenishment models auto-ship personalized flavor rotations to ketogenic-diet adherents. Health-tracking app integrations in the United States enable consumption-pattern optimization and recurring revenue capture.
- Supermarkets:Front-of-pack calorie callouts and shelf-space competition require trade spend concentration.
- Convenience Stores:Impulse-purchase patterns favor single-serve packaging and checkout-adjacent placement.
Supermarkets retain the largest volume footprint. Online Retailers show the steepest expansion trajectory.
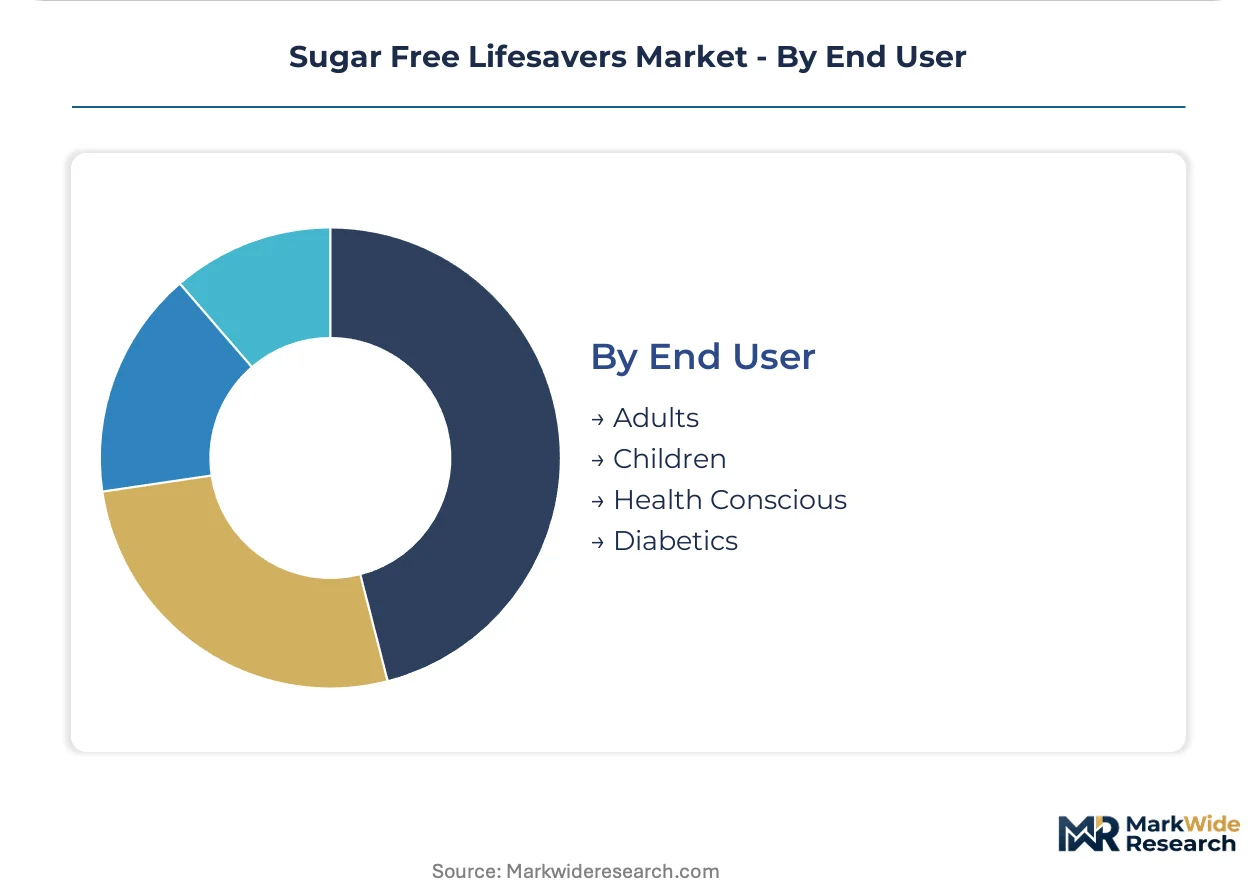
End User:
End-user targeting shapes formulation intensity, with diabetic and health-conscious segments requiring stricter glycemic response documentation and cleaner label architectures.
- Health Conscious:Caloric restriction and clean-label preferences drive stevia glycoside adoption and natural flavor positioning. Adults in Germany respond to EU Nutrition and Health Claims Regulation enforcement with verified reduced-sugar product selection.
- Diabetics:Glycemic index testing and medical-adjacent positioning require coordination with pharmacy channels and healthcare provider education. Subscription models in the United States target this segment with auto-ship compliance and flavor rotation.
- Adults:Workplace and social breath-freshening occasions favor portable hard-candy formats.
- Children:Parental gatekeeping limits sugar-alcohol content due to laxative effect concerns at high doses.
Adults represent the largest addressable population. Health Conscious is gaining share fastest among targeted segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized food scientists and pharmaceutical compliance officers cluster in Germany and the United States, anchoring reformulation expertise and dual-listing regulatory navigation for sugar-free confectionery.
United States
Ketogenic-diet adherents and diabetic consumers drive subscription-based replenishment through online retailers with health-tracking app integrations. FDA nutrition labeling mandates for added sugars are forcing front-of-pack transparency investments. Chicago and Minneapolis host major confectionery R&D facilities where aeration process innovations reduce energy intensity.
Germany
Health-conscious adults respond to sugar-reduction mandates with verified reduced-calorie product selection through pharmacy loyalty programs. EU Nutrition and Health Claims Regulation enforcement under the Farm to Fork strategy is accelerating retailer shelf-space reallocation. Cologne and Munich concentrate hard-candy manufacturing where sugar-alcohol stabilization technology extends shelf stability.
United Kingdom
Wellness-oriented retail positioning captures disproportionate margins through breath-freshening functional claims in mint formats. EFSA evaluations of non-nutritive sweeteners are extending product approval cycles for reformulated lines. Slough and York house conditioning tunnel operations adapting to F-Gas Regulation refrigeration restrictions.
Japan
Aging diabetic populations and workplace breath-freshening occasions sustain demand for portable hard-candy formats with glycemic management documentation. METI industrial standards coordinate with PMDA guidance on functional food positioning. Nagoya and Osaka clusters specialize in stevia glycoside extraction and purification technology for clean-label repositioning.
India
Urban health-conscious adults and parental purchasers favor reduced-calorie lunchbox formats for children despite sugar-alcohol content concerns. FSSAI labeling requirements are tightening permissible sweetness claims across domestic and imported confectionery. Mumbai and Bengaluru concentrate contract manufacturing for export-oriented natural flavor systems.
Sugar Free Lifesavers Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the sugar-free confectionery value chain. The vendor base concentrates around multinational confectionery conglomerates with integrated R&D pipelines and specialized sugar-alcohol stabilization capabilities. Three strategic archetypes dominate: diversified multinationals leveraging zero-sugar R&D across pharmacy and wellness channels, hard-candy specialists commanding shelf-stability technology, and regional players exploiting local sweetener supply chains. Competitive moves center on portfolio diversification into stevia glycoside formulations and strategic partnerships with online subscription platforms.
Within the diversified multinational tier, Nestlé S.A. and Mars Incorporated exemplify integrated food science and pharmaceutical compliance coordination. Perfetti Van Melle occupies a specialized position representing hard-candy format expertise through proprietary conditioning tunnel technology. These three anchors demonstrate how reformulation investments and dual-listing regulatory navigation separate premium positioning from commodity confectionery competition.
| Leading Market Players |
|---|
| Perfetti Van Melle |
| The Hershey Company |
| Nestlé S.A. |
| Mars Incorporated |
| Mondelez International |
| PepsiCo |
| Wrigley Company |
| Ricola Ltd |
| Lotte Group |
| Others |
Value Network & Pricing Analysis
Clean-label certification divergence separates stevia glycoside formulations commanding pharmacy-channel premiums from sorbitol-based commodity tiers competing on unit economics, with this bifurcation driving parallel supply chain investments in natural-extraction infrastructure versus corn-derived feedstock hedging.
Pricing Analysis
Bundled subscription services versus unbundled transactional purchases define the pricing architecture. Three-tier pricing structure across premium, standard, and economy levels reflects stevia purity grades, EU Health Claims Regulation certification status, and pharmacy channel exclusivity arrangements. Pricing pressure stems from sugar-alcohol input volatility as corn markets compete with biofuel demand. Diabetic consumers through subscription platforms exhibit lowest price sensitivity, while convenience retail purchasers show highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Chinese stevia glycoside extraction capacity and Brazilian xylitol fermentation facilities. Corn-derived sorbitol feeds from United States agricultural processing, while peppermint oil concentrates in Pacific Northwest growing regions. Tariff exposure on natural sweetener imports threatens margin stability for clean-label formulations. Distribution runs through pharmacy wholesale networks and direct-to-consumer fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in stevia glycoside adoption as reformulation cost curves flatten and pharmacy-channel premiums widen, with aeration process efficiency gains compressing manufacturing overhead.
For Market Incumbents: Anchor pharmacy channel positioning through dual-listing compliance investments that lock out commodity competitors. Deepen backward integration into stevia glycoside extraction to secure supply against Chinese capacity constraints. Expand conditioning tunnel automation in Cologne and Minneapolis facilities to offset F-Gas Regulation compliance costs. For New Entrants and Emerging Players: Direct-to-subscription platforms targeting ketogenic-diet adherents offer the most penetrable entry vector with lower customer acquisition costs than retail shelf-space competition. Auto-replenishment algorithm partnerships with health-tracking apps enable recurring revenue capture without legacy distribution infrastructure. Focus initial formulation on compressed tablet formats with minimal thermal processing requirements. For Investors and Strategic Acquirers: Consolidation pressure builds where sugar-alcohol stabilization technology scarcity meets pharmacy channel access requirements. Five-to-ten year viability favors acquirers of specialized conditioning tunnel operators with proprietary crystallization defect prevention. Watch EFSA stevia glycoside safety assessment timelines as inflection indicators for clean-label tier repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Stevia Glycoside Formulation Expansion | Captures EU Green Deal Farm to Fork incentive eligibility and pharmacy premium positioning. |
| Subscription Platform Partnership | Locks in diabetic consumer lifetime value through health-tracking app integration. |
| Conditioning Tunnel Retrofit | Qualifies European manufacturing for F-Gas Regulation compliance without production interruption. |
| Dual-Listing Regulatory Investment | Enables simultaneous pharmacy and food retail channel access in Germany. |
| Aeration Process Efficiency R&D | Reduces energy intensity to meet EU carbon reduction targets while preserving dissolution profiles. |
Research Methodology
Multiple input streams — regulatory filings, trade flow databases, and channel inventory audits — were reconciled through structured interviews with confectionery R&D directors, pharmacy category buyers, sugar-alcohol procurement leads, and EU regulatory affairs specialists. Secondary validation drew from FDA nutrition labeling guidance documents, EFSA sweetener safety assessments, F-Gas Regulation implementation notices, and customs records tracking sorbitol and xylitol cross-border movements. Bottom-up volume estimates from manufacturing capacity utilization were triangulated against top-down demand projections from subscription platform transaction data.
Data-stream reconciliation across product type, flavor profile, distribution channel, and end-user segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate modeling that weighted pharmacy channel expansion, online subscription adoption curves, and reformulation investment cycles. Industry-specific inputs included EU Nutrition and Health Claims Regulation enforcement timelines and F-Gas Regulation compliance cost trajectories for cooling-dependent manufacturing.
The model assumes a particular technology adoption path; alternative pathways for enzymatically modified stevia glycosides would alter the outlook if bitter aftertaste elimination accelerates faster than baseline projections. Forecasts reflect assumptions regarding regulatory stability, sweetener safety assessment continuity, and pharmacy channel access durability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Dextrose Syrup Market
Sweeteners
Europe Sugar Substitute Market
Sweeteners
Sucrose Acetate Isobutyrate Market
Sweeteners
Germany Food Sweetener Market
Sweeteners
North America Low-Calorie Sweeteners Market
Sweeteners
Compressible Sugar Market
Sweeteners
Oligofructose Market
Sweeteners
Middle East and Africa Food Sweetener Market
Sweeteners
Italy Food Sweetener Market
Sweeteners
Floral Nectar Market
Sweeteners
Australia Food Sweetener Market
Sweeteners
Corn Sweeteners Market
Sweeteners
France Food Sweetener Market
Sweeteners
Aspartame Market
Sweeteners
Global Alternative Sweeteners Market
Sweeteners
Dry Molasses Market