
 Organic Palm Sugar Market | 2026-2036
Organic Palm Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Palm Sugar Market Outlook
Specialty shop distribution in Western Europe is narrowing as supermarket chains consolidate shelf space for certified organic sweeteners. Big Tree Farms leverages its direct-trade relationships with Indonesian cooperatives to secure consistent supply volumes. Windmill Organics competes through private-label manufacturing for European health-food retailers. Navitas Organics anchors its position with North American e-commerce channels and premium branding.
Organic palm sugar denotes the crystallized sap of Borassus flabellifer or Arenga pinnata palms, harvested and evaporated without synthetic additives at temperatures below 120 degrees Celsius to preserve sucrose, glucose, and fructose ratios. The product serves as a low-glycemic-index sweetener in commercial food production and direct consumer use. Granulated formats dominate current volume owing to handling convenience in industrial baking and home kitchens. Liquid variants represent the fastest-growing product type as beverage manufacturers reformulate with pourable natural sweeteners. The confectionery application segment sits at a mature growth phase with stable margin pools in artisanal chocolate production.
The USDA National Organic Program and EU Organic Regulation govern certification standards that determine market access for imported palm sugar into the United States and European Union respectively. Indonesia's Ministry of Agriculture operates its own organic certification scheme that exporters must align with destination-country equivalency agreements. Stakeholders must monitor evolving equivalency negotiations between Southeast Asian producer nations and major import jurisdictions to anticipate supply chain qualification shifts.
Market Dynamics
The organic palm sugar market pivots on EU Organic Regulation equivalency negotiations, which determine whether Indonesian cooperatives retain access to European food manufacturers or face exclusion from the bloc's clean-label supply chains.
Growth Catalysts
- Clean-label reformulation:European confectionery producers are substituting refined cane sugar with low-glycemic palm sugar in artisanal chocolate lines to meet retailer sustainability criteria.
- EU Organic Regulation alignment:Indonesia's Ministry of Agriculture certification scheme now maps to destination-country protocols, accelerating exporter qualification timelines for German specialty food manufacturers.
- Smallholder cooperative consolidation:Java and Sumatra processing clusters aggregate harvests from village-level collectors, achieving the scale and traceability required by North American e-commerce channels.
Market Restraints
- Input cost volatility:Arenga pinnata sap yields fluctuate with monsoon patterns, compressing margins for crystalline producers during drought cycles in eastern Indonesia.
- Supply concentration risk:Export-grade organic certification concentrates among fewer than twelve Indonesian cooperatives, creating single-source vulnerability for European importers.
- Substitution threat:Coconut sugar from Philippine processors competes on price and glycemic positioning, diverting procurement budgets from palm sugar in beverage reformulation projects.
Strategic Opportunities
- Underpenetrated liquid formats:German beverage manufacturers represent untapped demand for pourable palm sugar syrup in functional drink lines.
- USDA National Organic Program expansion:American natural food retailers are requesting dedicated organic palm sugar SKUs as cane sugar alternatives face scrutiny from diabetic consumer segments.
- Direct-to-brand trade channels:Indonesian cooperatives are bypassing commodity traders, establishing captive supply relationships with North American premium sweetener brands.
Industry Challenges
- Certification timeline compression:EU Organic Regulation equivalency audits now require eighteen-month field observation cycles, delaying new cooperative market entry.
- Temperature-controlled logistics gaps:Crystalline product integrity demands sub-30-degree Celsius container transit from Sumatra ports to Rotterdam, straining reefer capacity during peak harvest windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Palm Sugar Market |
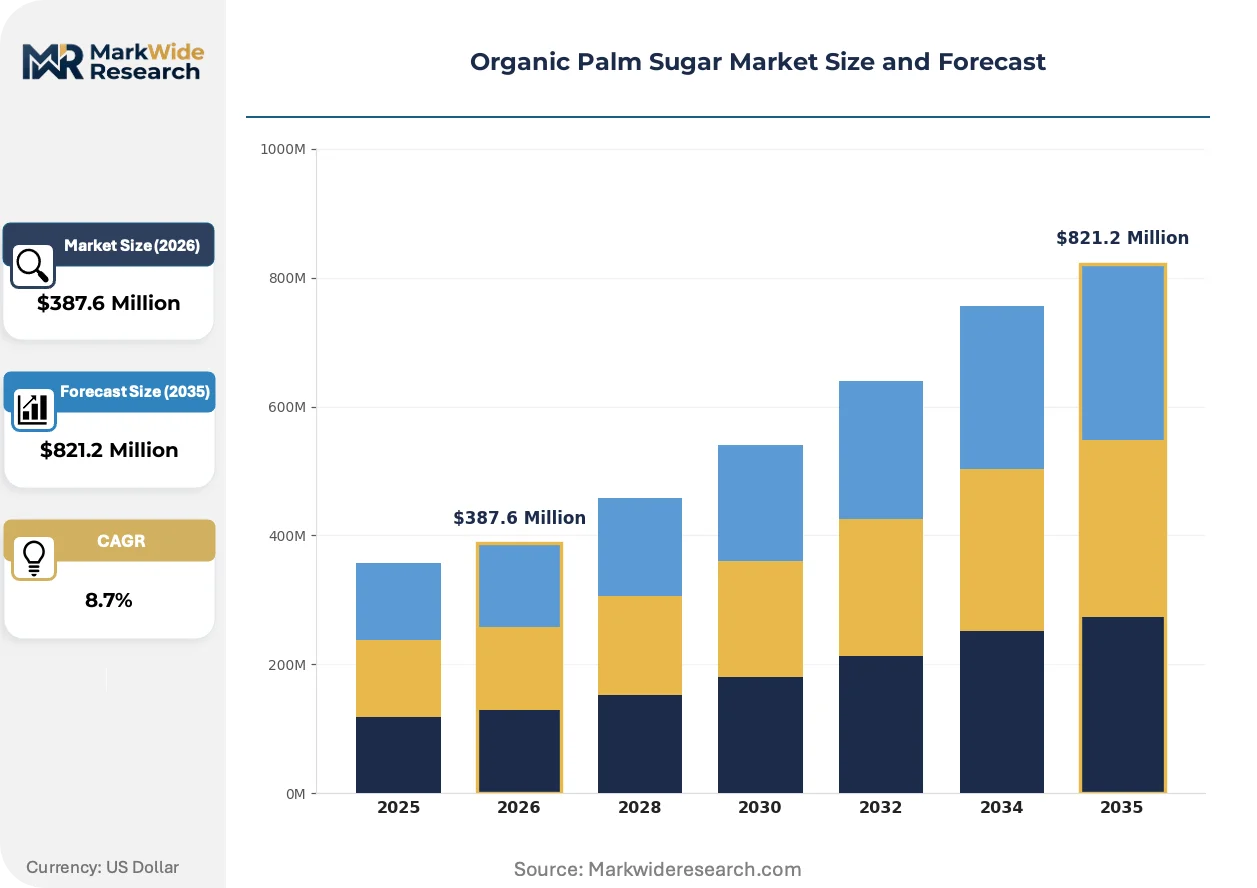
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granulated, Powdered, Liquid, Cubes Application: Beverages, Baking, Sauces, Confectionery Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops End User: Households, Food Manufacturers, Restaurants, Cafes |
| Companies Covered | Big Tree Farms, Palm Nectar Organics, Windmill Organics, Nature's Way, Coconut Palm Sugar, Sweet Tree, Bali Nutra, Navitas Organics, Wholesome Sweeteners, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Palm Sugar Market Strategic Shifts
Evaporation technology and certification digitization are compressing the gap between harvest and shelf, while procurement patterns shift from commodity trading toward fixed-volume partnerships with named cooperatives.
Solar-powered low-temperature evaporators now process Borassus flabellifer sap at sub-100-degree Celsius thresholds, preserving fructose-glucose ratios superior to conventional kiln methods. German organic chocolate manufacturers specify this equipment in supplier qualification documents. The technology is rendering obsolete the fuelwood-dependent processing infrastructure that dominated Java's cottage industry for decades.
EU Organic Regulation Article 29 mandates blockchain-traceable batch documentation for imported sweeteners, effective for all new supplier registrations. Indonesian exporters must deploy farm-to-port digital tagging systems to satisfy German customs inspections. Smallholder cooperatives in Sumatra are absorbing compliance costs through processor advance-payment structures.
Retail buyers in North American natural food channels now require living-wage certifications layered atop organic credentials, extending audit scope beyond agricultural practice into cooperative governance. E-commerce pure-play brands are displacing traditional importer-distributor relationships, contracting directly with Java-based processors for private-label crystalline product. This pattern concentrates most visibly in California-based subscription wellness box services.
Organic Palm Sugar Market Segmentation
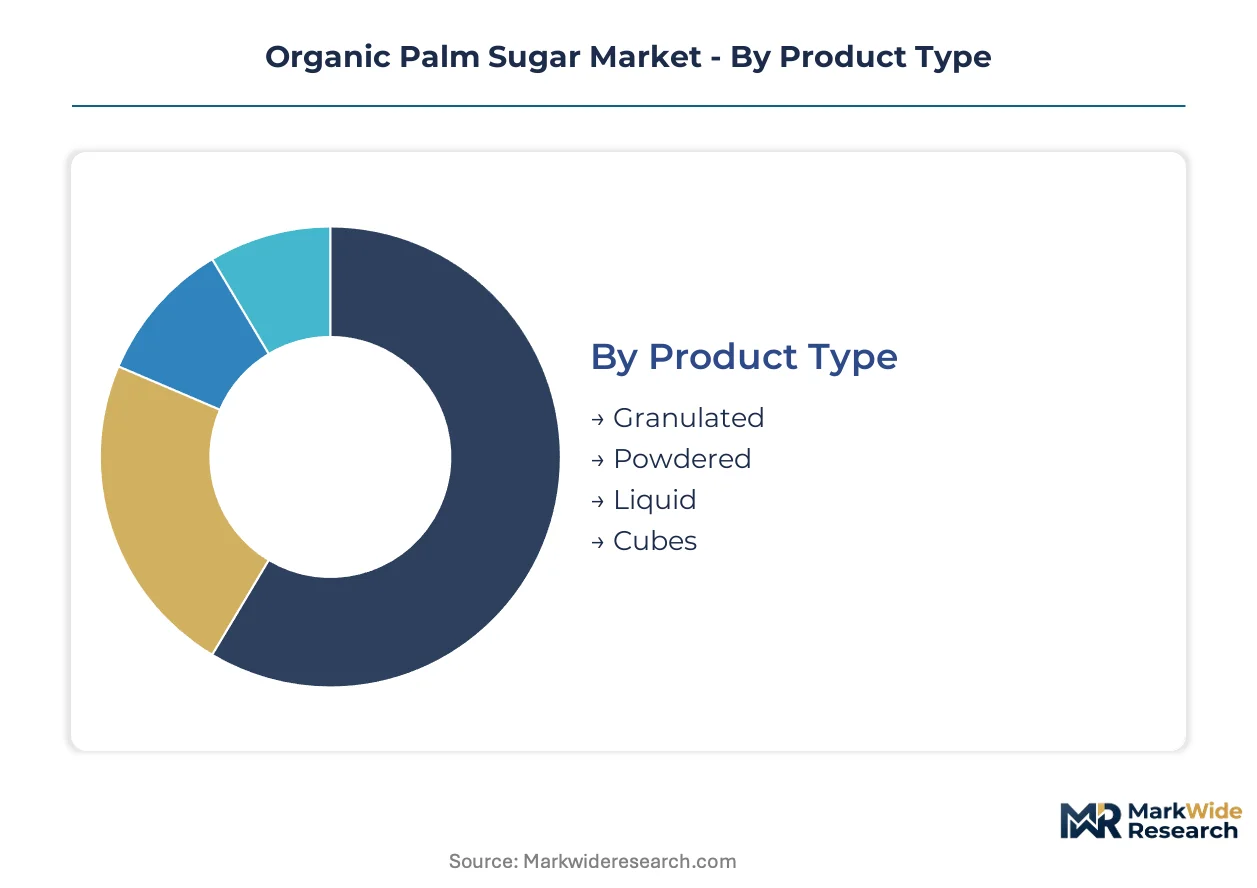
Organic palm sugar demand fragments across crystalline and liquid formats with divergent inventory velocities. Understanding these turnover patterns enables processors to align evaporator capacity with channel-specific shelf-life requirements.
Product Type:
Inventory cycles vary sharply across formats, with industrial-scale crystalline products turning monthly while artisanal liquid variants face seasonal demand spikes.
- Granulated:Coarse crystalline structure formed through controlled evaporation at sub-120-degree Celsius thresholds preserves sucrose-glucose-fructose ratios for industrial baking. German confectionery manufacturers specify this grade for clean-label chocolate formulations requiring precise dissolution rates. Java-based cooperatives ship containerized volumes to Rotterdam for European supermarket private-label programs.
- Liquid:Unrefined syrup with 75-85 percent dissolved solids content serves beverage reformulation where pourable viscosity matters. North American functional drink brands in California source directly from Sumatra processors for subscription wellness box services. Temperature-controlled logistics from port to warehouse compresses effective shelf windows.
- Powdered:Fine-milled crystalline product below 200-micron particle size dissolves rapidly in cold beverages. Indonesian exporters grind granulated stock to specification for Japanese matcha beverage manufacturers.
- Cubes:Molded crystalline blocks target café table-service applications in European specialty coffee chains. Small-batch production in Bali village cooperatives limits export-scale availability.
Granulated formats anchor the volume base while liquid variants gain share at the steepest rate.
Application:
Margin structures diverge across use cases, with industrial-scale beverage contracts commanding volume discounts while artisanal confectionery tolerates premium positioning.
- Beverages:Pourable liquid and fine-powder grades enable clean-label reformulation in functional drink lines. German manufacturers specify organic palm sugar for probiotic kombucha production to meet retailer sustainability scorecards.
- Confectionery:Low-glycemic-index positioning drives substitution for refined cane sugar in artisanal chocolate. Sumatra cooperatives achieve price premiums through direct-trade relationships with European bean-to-bar producers.
- Baking:Granulated crystalline product withstands high-temperature Maillard reactions in commercial pastry production. Indonesian exporters blend batch sizes to meet North American industrial baker consistency requirements.
- Sauces:Liquid syrup provides viscosity and caramel notes in Asian cooking sauce formulations. Java processors supply calibrated Brix levels for Malaysian condiment manufacturers.
Confectionery commands the highest per-kilogram realization while beverage applications drive absolute volume expansion.
Distribution Channel:
Channel concentration is accelerating as supermarket chains consolidate shelf space and displace fragmented specialty retail.
- Supermarkets:Centralized procurement by European grocery chains now specifies blockchain-traceable organic credentials. German retailers demand eighteen-month field documentation under EU Organic Regulation Article 29 compliance.
- Online Retail:E-commerce pure-play brands contract directly with Indonesian processors, bypassing traditional importer-distributor markups. California-based subscription services source private-label crystalline product from Java cooperatives.
- Health Stores:Independent natural food retailers stock premium-positioned SKUs with living-wage certifications layered atop organic credentials. North American chains require cooperative governance audits extending beyond agricultural practice.
- Specialty Shops:Artisanal food boutiques in Western European cities curate small-batch Indonesian origin products. Shelf space compression limits new supplier entry.
Supermarket channels dominate procurement volumes while online retail expands most quickly through direct-trade disintermediation.
End User:
Customer scale determines specification granularity, with industrial buyers demanding batch consistency that household consumers disregard.
- Food Manufacturers:Industrial-scale buyers specify crystalline particle size distribution and moisture content tolerances. German chocolate producers qualify suppliers through on-site evaporator equipment audits.
- Households:Retail-packaged granulated product in 500-gram formats targets diabetic consumer segments seeking low-glycemic alternatives. North American natural food retailers dedicate shelf space to certified organic SKUs.
- Restaurants:High-volume kitchens source 25-kilogram sacks through foodservice distributors. Indonesian exporters maintain Rotterdam bonded warehouse stock for just-in-time European delivery.
- Cafes:Specialty coffee chains specify molded cube formats for table-service presentation. Limited production capacity in Bali constrains supply security.
Food manufacturers anchor procurement volumes while household direct-to-consumer channels climb the fastest through e-commerce platform expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Tanjung Priok in Jakarta anchors Indonesia's export infrastructure, moving containerized crystalline product to Rotterdam and Long Beach. This maritime backbone determines seasonal availability windows for European and North American buyers.
Indonesia
Java and Sumatra processing clusters aggregate smallholder harvests for export-grade certification. The Ministry of Agriculture's organic scheme aligns with EU Organic Regulation equivalency protocols. Surabaya-based cooperatives now deploy blockchain-traceable batch documentation to satisfy German customs requirements.
Germany
Specialty food manufacturers in Bavaria and North Rhine-Westphalia expand procurement for clean-label confectionery lines. EU Organic Regulation Article 29 mandates eighteen-month field observation cycles for new supplier registration. Hamburg's port logistics handle temperature-controlled reefer containers from Indonesian exporters.
United States
California-based subscription wellness services source private-label crystalline product directly from Java cooperatives. The USDA National Organic Program governs import certification standards for retail shelf placement. Los Angeles and San Francisco distribution hubs bypass traditional importer-distributor markups through e-commerce channels.
Netherlands
Rotterdam serves as the European consolidation point for Indonesian containerized shipments. The Dutch Food and Consumer Product Safety Authority enforces EU Organic Regulation compliance at port of entry. Amsterdam-based traders manage bonded warehouse stock for just-in-time delivery to German chocolate manufacturers.
United Kingdom
London health-food retailers demand living-wage certifications layered atop organic credentials for premium SKU placement. The UK Organic Regulation maintains equivalency with EU standards post-Brexit. Manchester and Birmingham distribution centers handle private-label volumes for supermarket chains.
Organic Palm Sugar Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream. The organic palm sugar market structures around direct-trade cooperatives, private-label manufacturers, and e-commerce pure-play brands. Three archetypes dominate: Indonesian-based direct-trade aggregators, European private-label processors, and North American premium-brand distributors. Capacity expansion and certification digitization represent the dominant competitive moves as players compress harvest-to-shelf timelines.
Within the direct-trade tier, Big Tree Farms and Windmill Organics exemplify divergent sourcing strategies. Big Tree Farms occupies a position anchored in Indonesian cooperative relationships, while Windmill Organics represents the European private-label manufacturing archetype. Navitas Organics sits within the North American premium-brand distributor category, emphasizing e-commerce channel control.
| Leading Market Players |
|---|
| Big Tree Farms |
| Palm Nectar Organics |
| Windmill Organics |
| Nature's Way |
| Coconut Palm Sugar |
| Sweet Tree |
| Bali Nutra |
| Navitas Organics |
| Wholesome Sweeteners |
| Others |
Value Chain & Pricing Dynamics
Java and Sumatra processing clusters concentrate export-grade organic certification among fewer than twelve cooperatives, anchoring margin pools in Rotterdam bonded warehouses and German chocolate manufacturer qualification documents. This upstream concentration transfers pricing power downstream to importers who control temperature-controlled reefer capacity during peak harvest windows.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EU Organic Regulation Article 29 compliant batches from equivalency-pending stock and conventional kiln-dried product. Price differentiation hinges on certification tier and volume scale, with German industrial buyers commanding discounts on containerized crystalline shipments. Pricing pressure stems from Philippine coconut sugar substitution in beverage reformulation projects. Household retail segments exhibit highest price sensitivity, while artisanal confectionery tolerates premium positioning for direct-trade provenance.
Supply Chain Analysis
Single-source vulnerability among certified Indonesian cooperatives dominates supply chain risk assessment for European importers. Geographic concentration centers on Indonesia, with Rotterdam and Hamburg serving as downstream consolidation points. Raw material dependencies include Arenga pinnata sap yields, monsoon-dependent harvest cycles, and fuelwood-to-solar evaporator transition costs. Distribution runs through bonded warehouse stock for just-in-time delivery to German manufacturers and California e-commerce fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Living-wage certification audits and blockchain-traceable batch documentation represent faster-expanding service layers than crystalline product manufacturing itself. Recurring compliance revenue streams attach to each harvest cycle as EU Organic Regulation Article 29 mandates eighteen-month field observation periods.
For Market Incumbents: Entrench cooperative relationships through advance-payment structures that absorb smallholder compliance costs. Defend against Philippine coconut sugar substitution by securing exclusive liquid format capacity for German beverage manufacturers. Prioritize evaporator equipment audits as a qualification lever to lock in German chocolate producer procurement. For New Entrants and Emerging Players: Pursue underpenetrated liquid syrup demand from California functional drink brands seeking pourable low-glycemic sweeteners. Target direct-to-brand trade channels that bypass Rotterdam commodity traders. Anchor go-to-market strategy through subscription wellness box services requiring private-label crystalline product with living-wage credentials. For Investors and Strategic Acquirers: Capital is best deployed toward Indonesian cooperatives with existing EU Organic Regulation equivalency alignment and installed solar evaporator capacity. Long-term viability rests on certification digitization infrastructure that compresses harvest-to-shelf timelines. Monitor equivalency negotiation outcomes between Indonesia's Ministry of Agriculture and EU regulatory bodies as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain-Traceable Certification Deployment | EU Organic Regulation Article 29 mandates digital batch documentation for German customs clearance. |
| Solar Evaporator Capacity Expansion | Sub-100-degree Celsius processing preserves fructose-glucose ratios specified by German chocolate manufacturers. |
| Direct-to-Brand Trade Channel Establishment | California subscription wellness services bypass Rotterdam importer-distributor markups through cooperative contracts. |
| Liquid Format Production Scale-Up | German beverage manufacturers represent untapped demand for pourable palm sugar syrup in functional drink lines. |
| Living-Wage Certification Layering | North American health-food retailers now require cooperative governance audits extending beyond agricultural practice. |
Study Parameters
A standing panel of cooperative processing managers, German specialty food procurement leads, Rotterdam bonded warehouse operators, and California e-commerce brand founders provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with Indonesian Ministry of Agriculture certification officers and European importer-distributor executives. Secondary validation drew from EU Organic Regulation equivalency documentation, USDA National Organic Program import records, Indonesian customs export data, and German retailer sustainability scorecards. Bottom-up cooperative capacity assessments triangulated against top-down channel volume estimates.
Scenario-bracketing framed projections across conservative, baseline, and accelerated adoption paths over the analysis window. Segmentation dimensions modeled include product format granularity, application use case, distribution channel structure, and end-user scale tier. CAGRs derived from evaporator capacity installation rates, certification timeline compression curves, and channel shift velocity indicators. Forecast inputs incorporated monsoon pattern variability effects on Arenga pinnata sap yields and EU-Indonesia equivalency negotiation status.
Macroeconomic conditions sit as an overlay; deviation in container shipping rates, euro-dollar exchange volatility, or European clean-label regulatory stringency would shift the trajectory. Forecasts reflect documented assumptions on cooperative consolidation pace and solar evaporator adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Caramelized Sugars Market
Sweeteners
South America Stevia Market
Sweeteners
Rare Sugar Market
Sweeteners
Middle East and Africa Sugar Substitutes Market
Sweeteners
United States Xylitol Market
Sweeteners
Sucrose Acetate Isobutyrate Market
Sweeteners
South Africa Food Sweetener Market
Sweeteners
Brazil Food Sweetener Market
Sweeteners
North America Low-Calorie Sweeteners Market
Sweeteners
Egypt Food Sweetener Market
Sweeteners
Sweet Modulator Market
Sweeteners
North America High-Intensity Sweeteners Market
Sweeteners
Saccharin Market
Sweeteners
Sugar Beet Juice Extract Market
Sweeteners
D-Mannose Market
Sweeteners
Global Plant-Derived and Synthetic Sugar Market