
 Plant Based Beverages Market | 2026-2036
Plant Based Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Based Beverages Market Intelligence
A shift from single-source to multi-source ingredient procurement is rebalancing supply chain resilience for major producers. This strategic change mitigates risks associated with crop failures and price volatility for key inputs like almonds and oats. Oatly Group AB leverages its strong brand identity and specialized focus on oat-based formulations. Danone S.A. competes across a diversified portfolio that includes soy, almond, and coconut beverages. The Hain Celestial Group, Inc. positions its brands within the organic and natural food channels, targeting health-conscious consumers.
Plant-based beverages are non-dairy liquids derived from processing plant materials such as cereals, legumes, nuts, or seeds. The manufacturing process typically involves extraction, filtration, and homogenization to create a stable emulsion with a consistency that often mimics dairy milk. These products serve as alternatives for individuals with lactose intolerance, dairy allergies, or those following vegan or flexitarian diets. Oat milk represents the fastest-growing product category, valued for its creamy texture and favorable environmental profile. While supermarkets remain the primary distribution channel, online retail platforms are enabling smaller, specialized brands to reach a wider audience.
Regulatory frameworks established by bodies like the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) shape market access. These agencies govern labeling, particularly the use of terms like "milk," and require substantiation for any health claims made on packaging. In India, the FSSAI sets standards for product composition and safety. Future success for manufacturers depends on navigating these evolving labeling regulations while securing a consistent supply of high-quality raw materials.
Market Dynamics
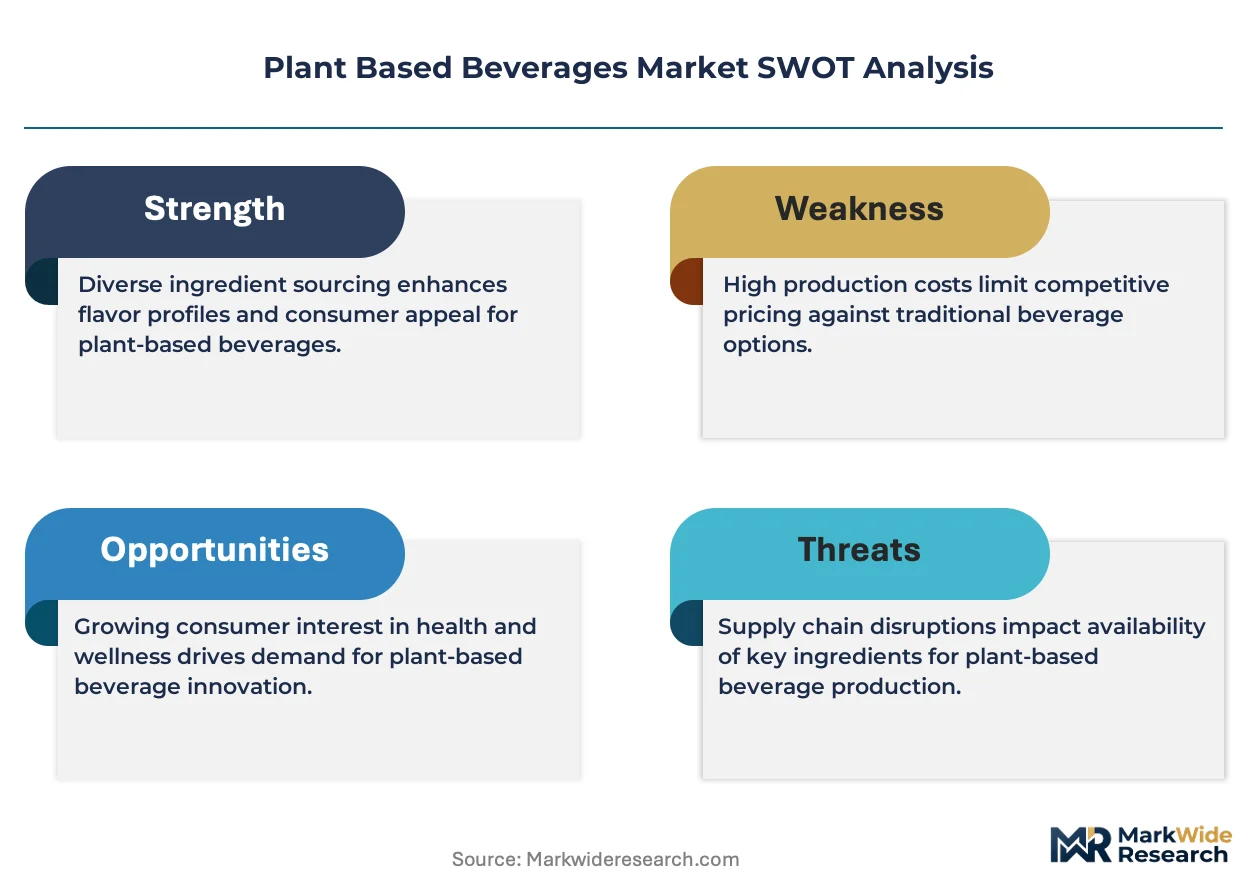
The central dynamic shaping the plant-based beverage market is the interplay between advancing processing technologies and evolving global food regulations. Manufacturers leverage innovations like UHT processing to enter new markets, while simultaneously navigating complex labeling laws from bodies like the FDA and EFSA.
Growth Catalysts
- UHT Processing Technology:Advances in ultra-high temperature processing are extending product shelf life and ensuring stability without refrigeration. This improvement facilitates wider distribution through ambient supply chains, expanding access beyond major urban centers.
- Shifting Dietary Patterns:A documented rise in lactose intolerance and the mainstream adoption of flexitarian diets, particularly within the cafe and restaurant segment, directly fuels consumer demand for dairy alternatives in markets like the United States and Germany.
- Online Retail Expansion:The growth of e-commerce and direct-to-consumer platforms enables smaller, niche brands to bypass traditional supermarket gatekeepers. This channel diversification fosters innovation and increases consumer choice.
Market Restraints
- Raw Material Price Volatility:The market is exposed to price fluctuations for key agricultural inputs such as almonds, soy, and especially oats. These shifts, driven by weather events and crop yields, directly impact production costs and final product pricing.
- Regulatory Labeling Friction:Strict regulations from the FDA and EFSA governing the use of dairy-related terms like "milk" on plant-based product labels create marketing hurdles and can confuse consumers, potentially slowing adoption.
- Sensory Profile Gaps:Despite improvements, achieving the taste, texture, and mouthfeel of conventional dairy milk remains a significant technical barrier for certain plant bases. This sensory gap can limit repeat purchases among mainstream consumers.
Strategic Opportunities
- Geographic Expansion:Significant growth potential exists in markets with nascent plant-based sectors, including regions in Latin America and Southeast Asia. These areas present white-space opportunities beyond the currently concentrated markets of North America, Europe, and China.
- Functional Fortification:Incorporating functional ingredients such as probiotics, adaptogens, and higher levels of protein allows brands to create value-added products. This strategy targets health-conscious consumers seeking benefits beyond simple dairy replacement.
- Hybrid Product Development:Blending multiple plant sources, such as oat and pea or soy and coconut, can create novel products with superior nutritional profiles and sensory characteristics, addressing specific consumer preferences for creaminess or protein content.
Industry Challenges
- Supply Chain Consistency:Establishing and maintaining a consistent, high-quality supply of raw materials, particularly for organic and non-GMO variants, is a persistent operational challenge. This requires sophisticated sourcing and quality assurance programs.
- Cross-Border Regulatory Compliance:Navigating the divergent food safety and labeling standards set by authorities like the FDA, EFSA, and India's FSSAI complicates international expansion. Each jurisdiction requires specific compliance efforts, increasing costs.
- Production Scaling Costs:Expanding manufacturing capacity for plant-based beverages requires significant capital expenditure. Specialized equipment for extraction, homogenization, and aseptic packaging represents a substantial financial hurdle for new entrants and growing firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Based Beverages Market |
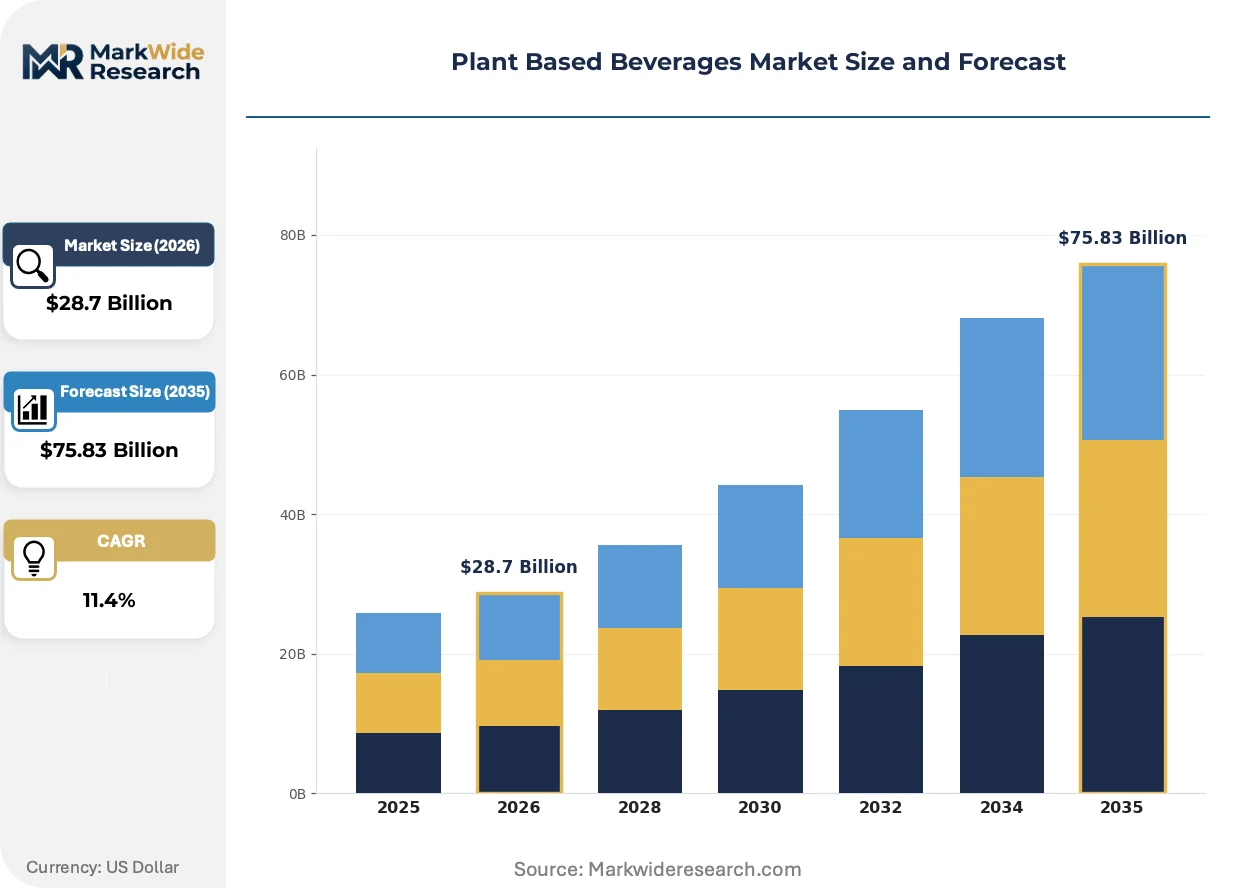
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $75.83 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nut Milk, Soy Milk, Oat Milk, Coconut Water End User: Retail Consumers, Health Enthusiasts, Cafes, Restaurants Packaging Type: Bottles, Tetra Packs, Cans, Pouches Distribution Channel: Supermarkets, Online Retail, Health Stores, Convenience Stores |
| Companies Covered | The Hain Celestial Group, Inc., Oatly Group AB, Danone S.A., The Coca-Cola Company, PepsiCo Inc., Blue Diamond Growers, Inc., SunOpta Inc., Nestlé S.A., Califia Farms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Based Beverages Market Strategic Shifts & Innovations
Formulation science is advancing to create plant-based beverages that not only mimic dairy but also deliver targeted nutritional and functional benefits. This evolution is driven by both technological breakthroughs in ingredient processing and a deeper understanding of consumer sensory preferences across different applications.
Precision Fermentation Precision fermentation is a bioprocess that uses microorganisms to produce specific functional proteins, such as whey and casein, without animal inputs. Food technology companies and innovative CPG firms are integrating these identical-to-dairy proteins into their formulations. This technology is modularizing product development, enabling the creation of plant-based drinks with authentic dairy-like textures and functionalities.
Labeling and Health Claim Scrutiny The European Food Safety Authority (EFSA) is increasing its review of health and nutrition claims made on plant-based food packaging. This action compels manufacturers to provide robust scientific evidence to substantiate any marketing claims related to specific health outcomes. The oat and soy beverage segments are particularly impacted, prompting greater investment in clinical research to validate product benefits.
Portfolio Consumption Behavior Consumers are progressively adopting a portfolio purchasing strategy, buying different types of plant-based beverages for distinct purposes, such as oat milk for coffee and almond milk for cereals. This trend disrupts traditional single-source brand loyalty, favoring companies that offer a diverse range of products. This behavior is most prominent in major metropolitan areas in the United States and Germany, where retail assortments are expanding to meet this demand.
Plant Based Beverages Market Segmentation
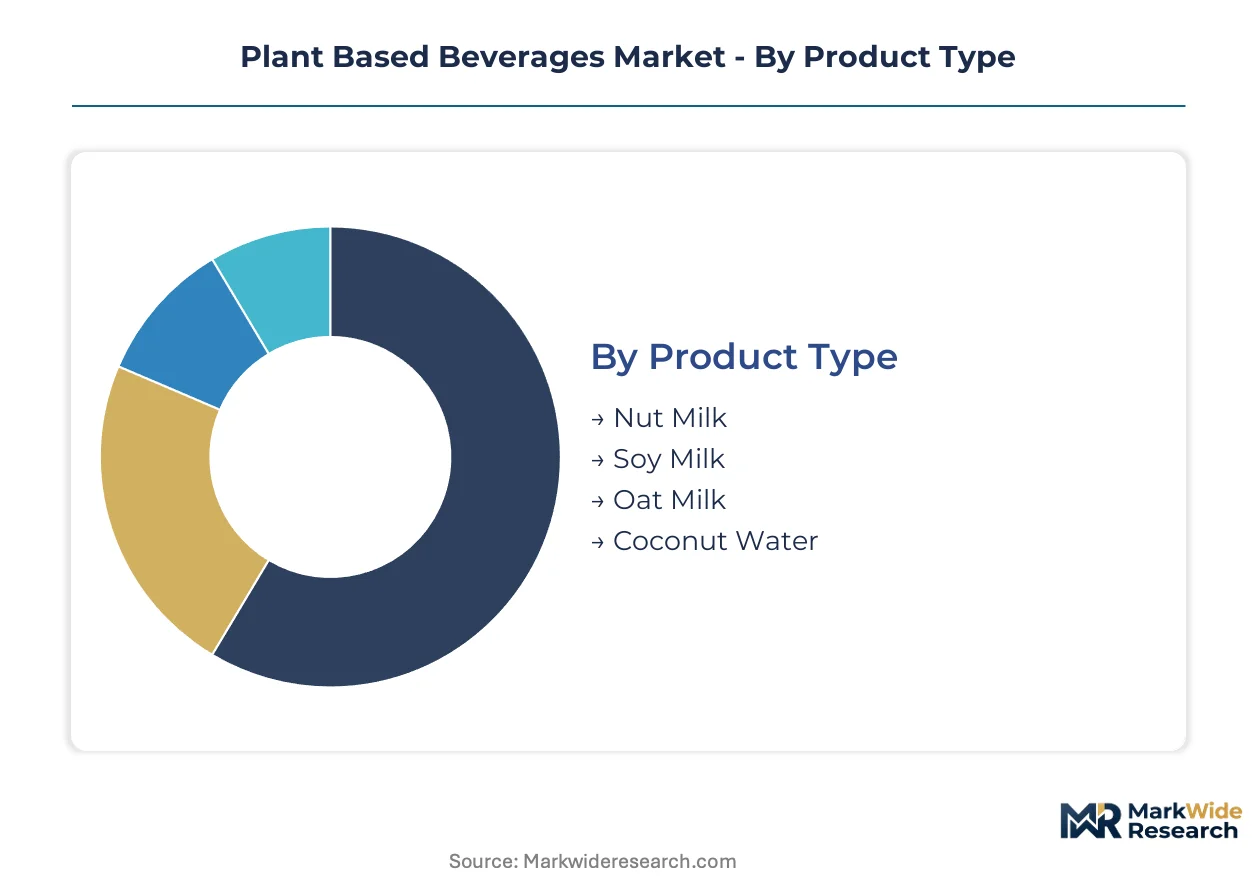
The plant-based beverages market segmentation reflects diverse product offerings and varied consumer preferences across distinct usage occasions. Understanding these segments is critical for manufacturers to tailor product development and target specific distribution channels effectively.
Product Type:
Product types differentiate based on their primary plant source, influencing sensory profiles and nutritional composition for consumers. These beverages are often consumed as standalone drinks or integrated into various food and beverage preparations.
- Oat Milk:This product is derived from oats, offering a naturally creamy texture and a mild, slightly sweet flavor profile. Oat milk is gaining significant traction in coffee shops and cafes across the United States and Germany due to its frothing capabilities and neutral taste.
- Nut Milk:This category encompasses beverages made from various nuts, with almond milk being a prominent example, characterized by its light texture and subtly nutty flavor. Demand for almond milk concentrates in urban centers like those in China and the US, driven by calorie-conscious consumers and those seeking dairy alternatives for cereals.
- Soy Milk:Produced from soybeans, soy milk provides a high-protein dairy alternative with a distinct, often earthy flavor. It remains a foundational segment, particularly in Asian markets, valued for its nutritional density and versatility in cooking.
- Coconut Water:This segment includes the clear liquid found inside young coconuts, known for its natural electrolytes and refreshing taste. It appeals to health-conscious consumers seeking natural hydration, especially in warmer climates.
Volume placements concentrate in Nut Milk; Oat Milk represents the fastest-growing trajectory.
End User:
End-user segmentation identifies the primary consumer groups and commercial entities driving demand, each with specific purchasing behaviors and product requirements. This differentiation highlights where the plant-based beverage products ultimately find their application.
- Cafes, Restaurants:This commercial segment integrates plant-based beverages into prepared drinks like lattes and smoothies, and as dairy alternatives in menu items. Establishments in major European cities and the United States frequently stock multiple options to cater to diverse dietary needs.
- Retail Consumers:Individual consumers purchase plant-based beverages for home consumption, using them in cereals, cooking, or as standalone drinks. This segment forms the largest volume base, with buying decisions influenced by brand, price, and perceived health benefits in markets like Germany.
- Health Enthusiasts:This niche group actively seeks plant-based options for specific nutritional benefits, such as protein content, low sugar, or fortification with vitamins. Their purchasing decisions are often driven by detailed ingredient lists and functional claims.
Demand from Retail Consumers drives significant volume, while Cafes, Restaurants represents a high-growth niche.
Packaging Type:
Packaging type influences product shelf life, distribution logistics, and consumer convenience, directly impacting market penetration and environmental considerations. The choice of packaging often reflects the product's intended shelf stability and target distribution channel.
- Tetra Packs:These aseptic carton packages provide extended shelf life for UHT-processed beverages without refrigeration, facilitating wider distribution. Tetra packs are prevalent in ambient supply chains across Europe and Asia, supporting bulk purchasing.
- Bottles:Plastic or glass bottles are common for refrigerated plant-based beverages, often conveying a premium or fresh image. This format is popular in convenience stores and supermarkets in the United States for grab-and-go options.
- Cans:Aluminum cans offer portability and recyclability, frequently used for single-serve portions or specialized functional beverages. They are gaining popularity in the ready-to-drink segment.
- Pouches:Flexible pouches provide a lightweight and convenient packaging solution, often targeting children's beverages or on-the-go consumption. This format reduces material usage compared to rigid containers.
The majority of units are shipped in Tetra Packs, with Bottles gaining traction for convenience.
Distribution Channel:
Distribution channels define the pathways through which plant-based beverages reach the end consumer, impacting market accessibility and brand visibility. The concentration of supply within these channels shapes market reach and consumer purchasing habits.
- Supermarkets:These large retail outlets serve as the primary distribution channel, offering a wide assortment of brands and product types to a broad consumer base. Supermarkets in Germany and the United States dedicate significant shelf space to plant-based alternatives.
- Online Retail:E-commerce platforms enable direct-to-consumer sales and provide market access for smaller, specialized brands, expanding consumer choice. This channel is experiencing rapid growth, particularly in major urban centers of China and Europe.
- Health Stores:Specialized health food stores cater to consumers seeking organic, non-GMO, or specific dietary products, often stocking niche and premium plant-based beverages. These stores provide curated selections for health-conscious shoppers.
- Convenience Stores:These smaller retail formats offer quick access to single-serve plant-based beverages, catering to immediate consumption needs. Their widespread presence supports impulse purchases and on-the-go consumption.
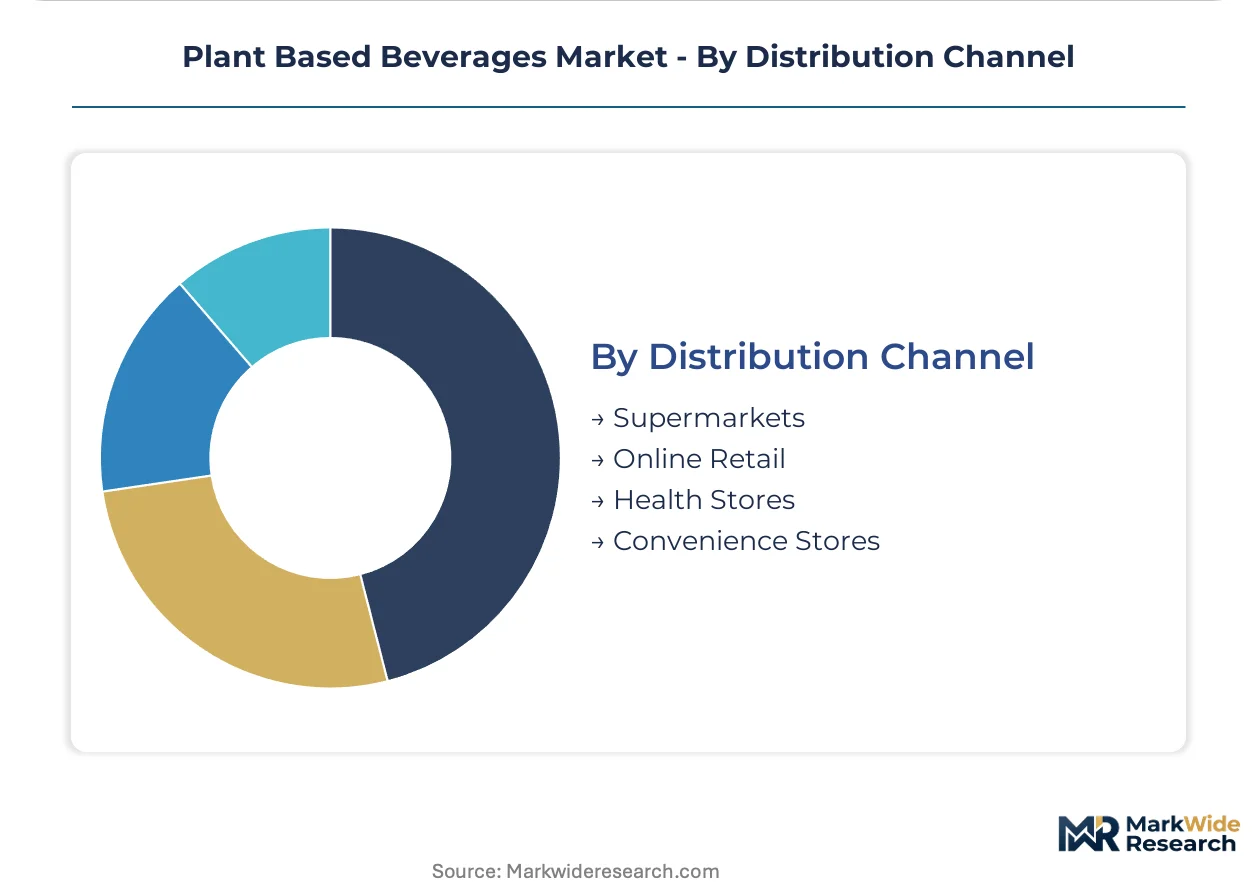
Traditional sales channels are anchored by Supermarkets, while Online Retail offers new market access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for plant-based beverages concentrates in major urban centers globally. Consumers in these areas increasingly seek dairy alternatives due to health consciousness and dietary shifts. This trend drives market expansion, particularly in established and emerging economies.
United States
Demand for plant-based beverages in the United States stems from rising lactose intolerance and flexitarian diets. The U.S. Food and Drug Administration (FDA) governs labeling, particularly for terms like "milk," influencing product marketing. Major metropolitan areas like New York City and Los Angeles show high adoption rates, driven by diverse retail and cafe offerings.
Germany
German consumers increasingly adopt plant-based options for environmental and health reasons, especially within the cafe segment. The European Food Safety Authority (EFSA) scrutinizes health claims, requiring robust scientific evidence from manufacturers. Berlin and Hamburg are key consumption hubs, where retail assortments expand to meet varied consumer preferences.
China
China's market for plant-based beverages is expanding due to urbanization and a growing middle class seeking diverse dietary choices. The State Administration for Market Regulation (SAMR) sets standards for food safety and product composition. Shanghai and Beijing exhibit strong demand for nut milk and soy milk, reflecting evolving consumer preferences.
India
India experiences growing demand for plant-based alternatives driven by health awareness and traditional vegetarian diets. The Food Safety and Standards Authority of India (FSSAI) establishes product composition and safety standards for market access. Urban centers such as Mumbai and Delhi are seeing increased availability of specialized plant-based options.
Brazil
Brazilian consumers are increasingly adopting plant-based beverages, influenced by global health trends and sustainability concerns. ANVISA, Brazil's health surveillance agency, regulates food labeling and product composition for these alternatives. São Paulo and Rio de Janeiro lead in consumption, with supermarkets expanding their dairy-free sections.
Plant Based Beverages Market Key Industry Players
Portfolio diversification dominates the current landscape, with major producers actively expanding their plant-based offerings across various ingredient types. The market structure features a dynamic mix of established food and beverage giants alongside specialized plant-based innovators. Strategic archetypes include large conglomerates leveraging extensive distribution networks, and niche brands focusing on specific plant sources or functional benefits. Capacity expansion through new production facilities and strategic partnerships for raw material sourcing are also common competitive moves.
Among companies diversifying their portfolios, Danone S.A. exemplifies a multi-source approach, offering soy, almond, and coconut beverages. Oatly Group AB occupies a position as a specialized innovator, anchoring the oat milk segment with its strong brand identity. The Hain Celestial Group, Inc. sits within the organic and natural food channels, targeting health-conscious consumers with its range of plant-based products. These players represent different strategic vectors, from broad market penetration to niche segment leadership.
| Leading Market Players |
|---|
| The Hain Celestial Group, Inc. |
| Oatly Group AB |
| Danone S.A. |
| The Coca-Cola Company |
| PepsiCo Inc. |
| Blue Diamond Growers, Inc. |
| SunOpta Inc. |
| Nestlé S.A. |
| Califia Farms |
Cost & Logistics Intelligence
EU Green Deal mandates for sustainable sourcing gate access to premium-tier plant-based beverage markets, simultaneously driving up costs for certified raw materials.
Pricing Analysis
Volume-driven pricing characterizes the mainstream plant-based beverage market, while premium offerings command higher margins. Brand premium and organic certification drive significant price differentiation. Pricing pressure stems from raw material price volatility, particularly for oats and almonds. Retail consumers exhibit high price sensitivity, whereas cafes and restaurants prioritize consistent quality and frothing capabilities.
Supply Chain Analysis
Regional distribution centers facilitate efficient product movement from manufacturing hubs to consumption points, utilizing a hub-and-spoke model. Raw material supply concentrates in agricultural regions like the United States (almonds), Europe (oats), and Southeast Asia (coconuts). Commodity price volatility for key agricultural inputs presents a significant structural risk. Downstream distribution runs through large supermarkets and online retail platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consistent access to high-quality raw materials, particularly organic oats, creates a supply constraint in the plant-based beverage market. This bottleneck often props up pricing for premium-tier products.
For Market Incumbents: Acquire specialized ingredient processing facilities to secure upstream supply of key plant proteins and starches. This move mitigates raw material price volatility and protects against margin pressure from emerging ingredient technologies. Invest in UHT processing capacity expansion within strategic geographic markets like Southeast Asia to outmaneuver smaller regional players. Diversifying raw material sourcing reduces single-crop failure risk.
For New Entrants and Emerging Players: A significant price-point gap exists between established premium brands and undifferentiated economy options, presenting an entry opportunity. Target underpenetrated regional markets in Latin America with novel hybrid plant-based formulations. A direct-to-consumer online retail strategy allows for rapid market feedback and avoids traditional gatekeepers. Focus on functional fortification with probiotics for health-conscious consumers.
For Investors and Strategic Acquirers: Widespread adoption of precision fermentation for dairy-identical proteins is the leading indicator that the plant-based beverage market is entering a new phase of technological disruption. Long-term viability (5-10 years) favors companies with proprietary ingredient technology and robust supply chain control. Target innovative CPG firms specializing in novel plant sources or functional ingredients for strategic acquisition. Watch for regulatory approvals of new protein sources as a key inflection point.
| Strategic Initiative | Industry Significance |
|---|---|
| Brand Extension into Hybrid Formulations | Creates novel products with superior nutritional profiles and sensory characteristics for diverse consumer preferences. |
| Investment in Precision Fermentation | Secures proprietary production of dairy-identical proteins, reducing reliance on traditional plant sources. |
| Geographic Expansion into Latin America | Captures new consumer segments in a region with nascent plant-based sectors and growing health awareness. |
| Direct-to-Consumer Platform Development | Bypasses traditional retail channels, enabling niche brands to reach a wider, specialized audience. |
| Strategic Partnerships for Raw Material Sourcing | Mitigates risks associated with crop failures and price volatility for key agricultural inputs like oats. |
Research Approach
Multi-period observation of consumption patterns, regulatory filings, and patent activity anchored the trend analysis, supplemented by interviews with CPG brand managers, food scientists, and retail category buyers. Secondary validation involved reviewing EFSA reports, FDA guidance documents, and industry association publications. A rigorous bottom-up and top-down triangulation process ensured data consistency and accuracy.
Segment-weighting across product type, end-user, packaging, and distribution channel formed the basis of the quantitative model over the projection horizon. Compound annual growth rates were derived by analyzing historical growth trajectories and projected market dynamics. Industry-specific inputs included UHT processing adoption rates and raw material yield forecasts.
Inputs from publicly available financial reports and academic studies were available through the study window; gaps in proprietary sales data introduce uncertainty bands. Forecasts reflect assumptions regarding consumer preference shifts and technological advancements. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Europe Beverage Market
Beverages
Relaxation Beverages Market
Beverages
Dairy Based Beverages Market
Beverages
Orange Juice Market
Beverages
Crystal Boba Market
Beverages
North America Dairy Beverages Market
Beverages
Sparkling Juice Drinks Market
Beverages
Nitro-Infused Cola Market
Beverages
Double Valve Moka Pots Market
Beverages
Packaged Coconut Water Market
Beverages
Global Squash Drinks Market
Beverages
Hydrogen Water Bottle Market
Beverages
Fermented Foods and Beverages Market
Beverages
Fruit and Vegetable Juice Market
Beverages
Middle East Energy Drinks Market
Beverages
Asia-Pacific Bottled Water Market