
 France Food Sweetener Market | 2026-2036
France Food Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
France Food Sweetener Market Foresight
Supermarket private-label sweetener assortments is reconfiguring how national brands defend shelf space in France. Cargill Incorporated leverages its European starch processing network to secure bulk supply contracts with domestic beverage producers. Tereos S.A. anchors its competitive position through beet sugar extraction facilities located in northern France. Roquette Freres SA specializes in plant-based polyol production, giving it distinct exposure to the clean-label movement.
Food sweeteners encompass caloric and non-caloric substances—sucrose, high-purity steviol glycosides, synthetic dipeptides, and sugar alcohols—that impart sweetness to processed foods and beverages, typically measured by sucrose equivalence and thermal stability under pasteurization conditions. Their primary commercial purpose centers on enabling recipe reformulation without sensory compromise. Sucrose still occupies the largest share of value sold through French distribution channels, though stevia extracts gain velocity among beverage applications seeking botanical positioning. Erythritol competes aggressively in confectionery segments where cooling effects and dental health claims resonate with formulation teams.
ANSES evaluates sweetener safety dossiers alongside EFSA guidance, while EU REACH and F-Gas Regulation frameworks indirectly shape processing chemistry investments. These layered standards compel suppliers to maintain dual certification portfolios for domestic and export-qualified production lines. Stakeholders must monitor pending EU-wide added-sugar labeling revisions that will force reformulation timelines across French bakery and dairy categories.
Market Dynamics
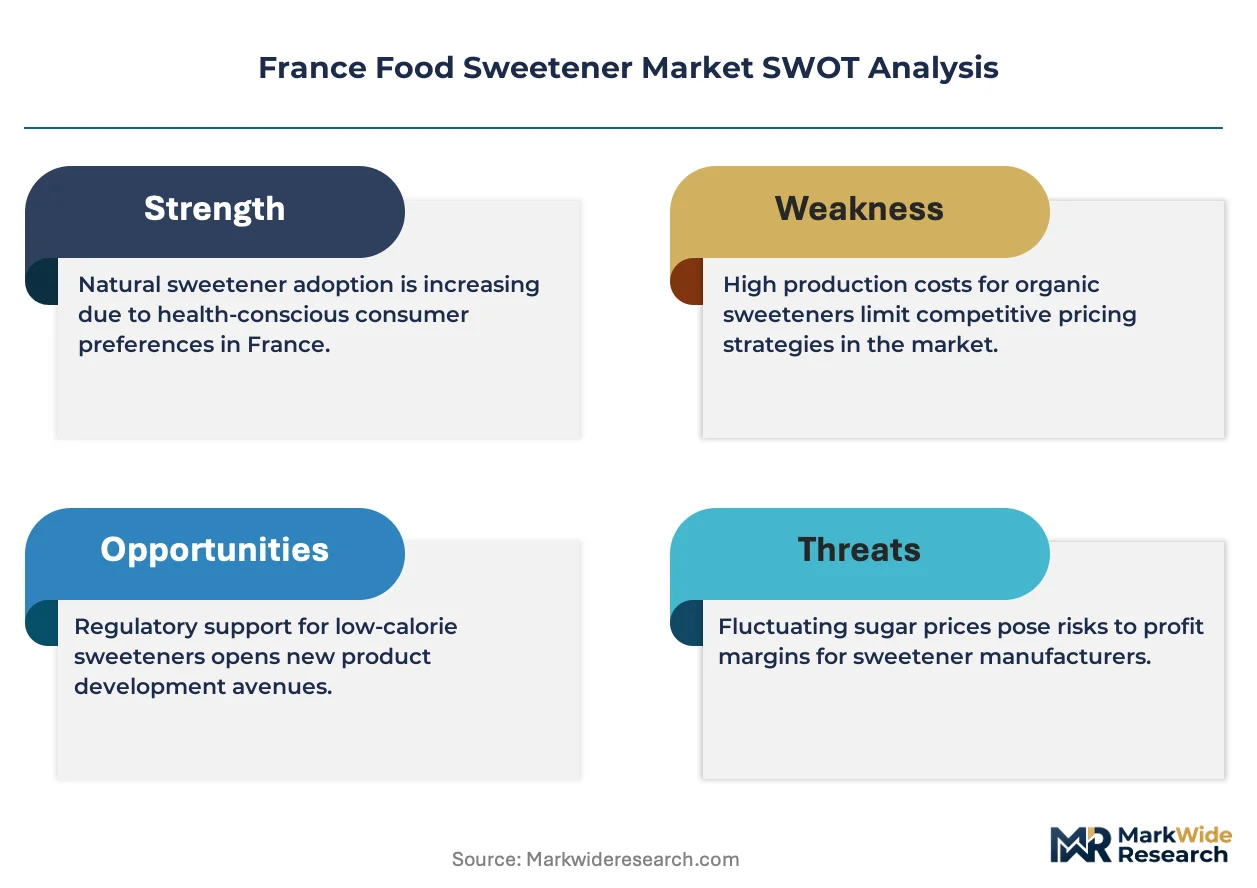
Reformulation pressure from EU-wide added-sugar labeling revisions is compressing timelines for French bakery and dairy producers, forcing simultaneous investment in novel sweetener pipelines and sensory testing infrastructure.
Growth Catalysts
- EFSA Novel Food approvals:Accelerated safety dossier evaluations under EU frameworks enable faster commercialization of steviol glycoside variants for beverage applications.
- ANSES reformulation mandates:French food safety protocols compel manufacturers to document sugar reduction pathways, creating institutional demand for technical sweetener alternatives.
- Ile-de-France headquarters concentration:Proximity of major food and beverage decision centers to Paris accelerates pilot-to-scale transitions for new sweetener formulations.
Market Restraints
- Beet sugar harvest volatility:Northern French extraction facilities face yield fluctuations tied to climate patterns, creating input cost instability for sucrose-dependent producers.
- Novel sweetener sensory limitations:Bitter aftertaste profiles in high-purity stevia extracts restrict dosage levels in delicate applications like dairy desserts.
- EU REACH compliance burdens:Chemical processing investments for synthetic dipeptides face extended authorization timelines, delaying capacity expansion decisions.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur specialty foods:Artisan confectionery producers in southern France seek regional botanical positioning through locally sourced sweetener alternatives.
- Clean-label polyol convergence:Roquette Freres SA leverages plant-based fermentation expertise to capture dental health claims in sugar-free gum formulations.
- EU Green Deal bioeconomy incentives:Funding streams for sustainable processing infrastructure favor beet-to-polyol conversion investments over petrochemical routes.
Industry Challenges
- Sensory scientist talent scarcity:Formulation teams struggle to recruit specialists capable of bridging analytical chemistry with consumer preference mapping for reduced-sugar products.
- Dual certification complexity:Maintaining parallel production lines for domestic ANSES-qualified and export-EFSA-standard outputs strains quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Food Sweetener Market |
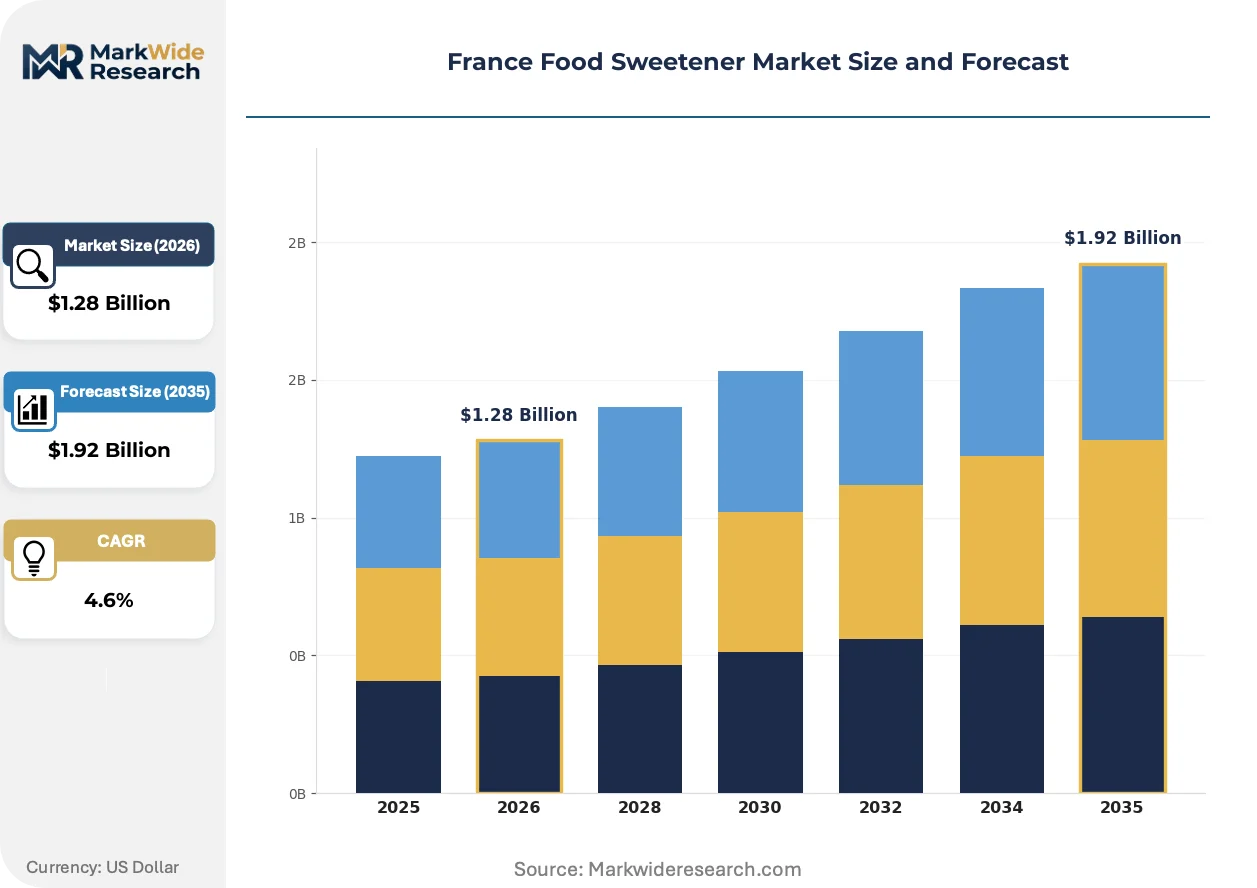
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $1.92 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Sucrose, High Fructose Corn Syrup, Stevia, Aspartame, Sucralose, Erythritol Application: Confectionery, Beverage, Bakery, Dairy Products, Frozen Desserts, Sauces & Dressings End User: Food Manufacturers, Beverage Producers, Pastry Shops, Catering Services, Meal Providers, Specialty Food Outlets Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Wholesale Distributors, Health Food Stores, Direct Sales |
| Companies Covered | DuPont, PureCircle Limited, Cargill Incorporated, GLG Life Tech Corporation, NutraSweet Company, Tate & Lyle PLC, Tereos S.A., Roquette Freres SA, Ingredion Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Food Sweetener Market Shifts & Advancements
Digital tools are penetrating sensory evaluation workflows while regulatory frameworks tighten around processing transparency. These forces are reshaping how French sweetener suppliers validate claims and manage supply chain documentation.
Enzymatic bioconversion of beet sugar into rare sugars like allulose is digitizing quality control protocols across Tereos S.A. facilities. French beverage formulators are piloting these ingredients at accelerated rates. The technology is digitizing batch consistency monitoring, compressing release timelines from weeks to days.
EU F-Gas Regulation amendments are restricting fluorinated greenhouse gas use in cooling systems deployed during polyol crystallization. Industrial consequence includes retrofitting investments for sugar alcohol producers. Northern French beet processing clusters are responding by migrating to ammonia-based refrigeration architectures ahead of phase-down deadlines.
Direct procurement contracts between Occitanie dairy cooperatives and regional sweetener distributors are displacing traditional broker-mediated purchasing. This channel compression concentrates volume commitments among fewer supplier relationships. The shift is most visible in yogurt and fromage frais categories where reformulation cycles have shortened to six-month intervals.
France Food Sweetener Market Segmentation
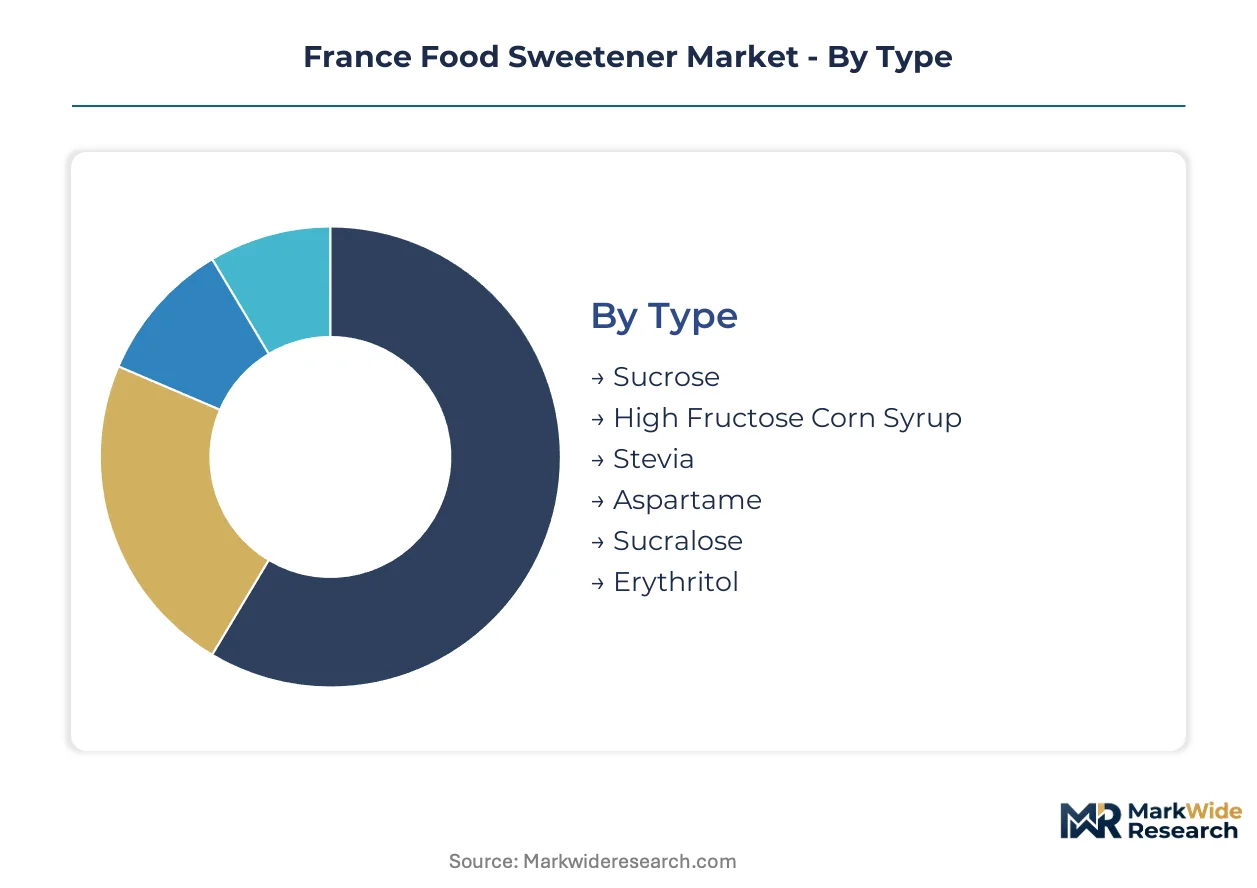
Segmentation in the France Food Sweetener Market reflects divergent technical requirements across reformulation scenarios. Sweetener selection hinges on thermal stability, sucrose equivalence, and regulatory clearance status under ANSES protocols. Distribution channel fragmentation further complicates procurement strategies for regional producers.
Type:
Mature caloric sweeteners dominate volume flows while novel non-caloric alternatives accelerate through beverage reformulation pipelines.
- Sucrose:Extracted primarily from northern French beet sugar operations, this crystalline disaccharide serves as the reference standard for sweetness intensity measurement. Bakery and confectionery manufacturers in Ile-de-France maintain deep formulation familiarity with its thermal browning behavior and moisture retention properties.
- Stevia:High-purity steviol glycosides extracted from Stevia rebaudiana leaves deliver zero-calorie sweetness with botanical positioning appeal. Beverage producers across the Paris basin pilot these extracts at accelerated rates, though bitter aftertaste constraints limit dosage in delicate dairy applications.
- High Fructose Corn Syrup:Enzymatically processed starch derivative with enhanced sweetness intensity and humectant properties.
- Aspartame:Synthetic dipeptide sweetener requiring phenylketonuria labeling under EU frameworks.
- Sucralose:Chlorinated sugar derivative with exceptional thermal stability for baked goods applications.
- Erythritol:Fermented sugar alcohol with cooling effect and dental health claim eligibility.
Sucrose retains volume leadership; Stevia holds the steepest expansion curve.
Application:
Application diversity stretches from high-heat processing environments to cold-fill beverage systems, each imposing distinct sweetener performance thresholds.
- Beverage:Carbonated and functional drink producers face the most aggressive reformulation timelines under pending EU added-sugar labeling revisions. Ile-de-France headquarters concentration enables rapid pilot-to-scale transitions for novel sweetener formulations, with stevia-erythritol blends gaining particular traction.
- Confectionery:Hard candies and chewing gum formulations exploit sugar alcohols for dental health positioning and cooling sensory effects. Roquette Freres SA supplies plant-based polyols to this segment from northern French fermentation facilities.
- Bakery:Maillard reaction requirements and moisture management complicate sugar substitution in croissant and viennoiserie production.
- Dairy Products:Yogurt and fromage frais categories demand clean-label positioning without fermentation interference.
- Frozen Desserts:Freezing point depression and scoopability requirements favor specific polyol combinations.
- Sauces & Dressings:Viscosity stability and shelf-life extension drive sweetener selection in emulsified systems.
Beverage commands the most active reformulation investment; Confectionery offers the clearest premium positioning pathway.
End User:
End user scale determines procurement sophistication, from multinational beverage contracts to artisan pastry shop spot purchasing.
- Food Manufacturers:Industrial-scale bakeries and prepared food operations negotiate bulk supply agreements with Tereos S.A. and Cargill Incorporated for standardized ingredient streams. These buyers maintain dedicated sensory testing infrastructure to validate reformulation outcomes.
- Beverage Producers:Carbonated drink and functional beverage specialists concentrate decision-making in Ile-de-France, leveraging proximity to ANSES for regulatory consultation on novel sweetener dossiers.
- Pastry Shops:Artisan producers in Provence-Alpes-Côte d'Azur seek regional botanical differentiation through specialty sweetener sourcing.
- Catering Services:Volume-driven institutional feeding operations prioritize cost stability over clean-label positioning.
- Meal Providers:Ready-meal manufacturers balance sugar reduction claims with microwave-reheating performance requirements.
- Specialty Food Outlets:Health-focused retailers curate niche sweetener assortments for diabetic and keto-positioned consumer segments.
Food Manufacturers anchor bulk volume flows; Beverage Producers drive technical innovation adoption.
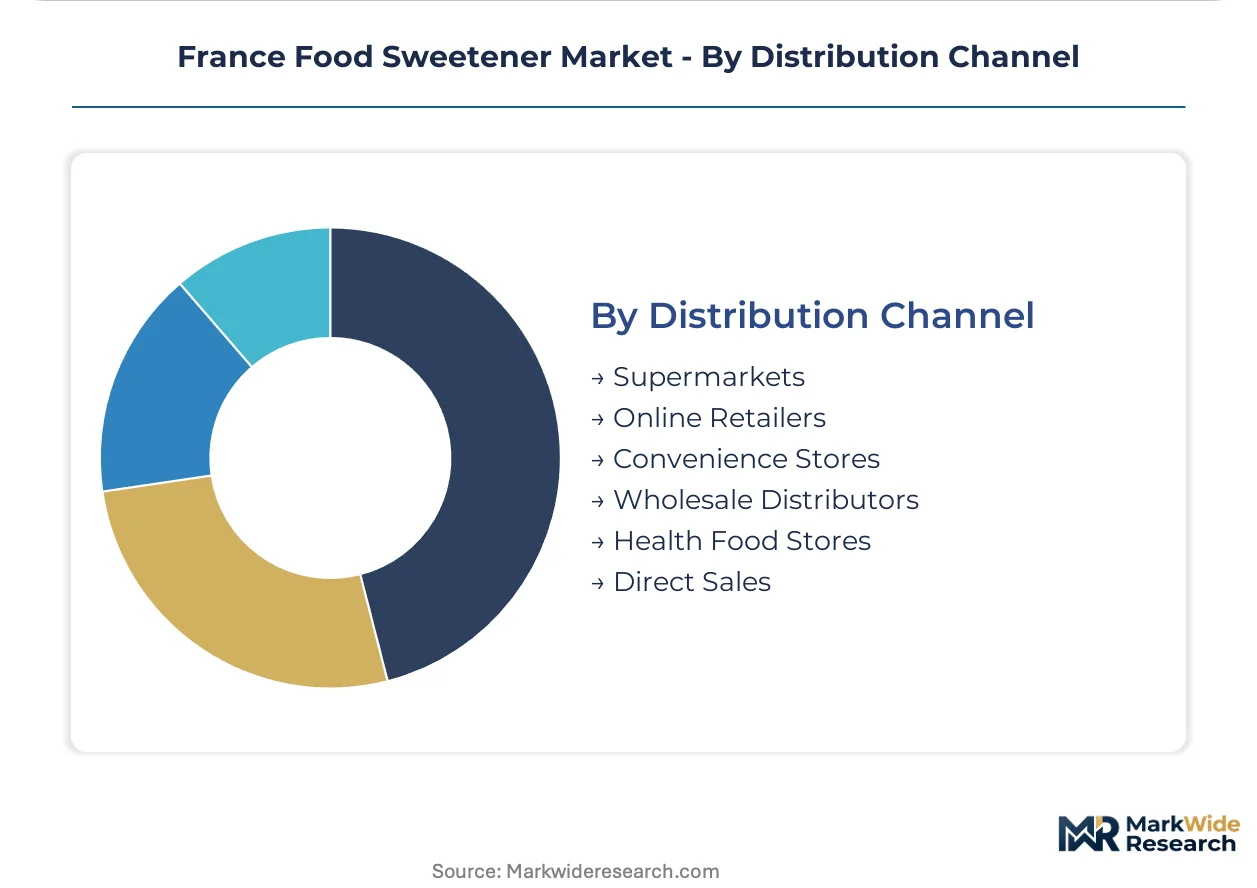
Distribution Channel:
Channel structure reflects the tension between consolidated wholesale efficiency and fragmented retail access for specialty ingredients.
- Wholesale Distributors:Bulk ingredient flows to industrial food and beverage operations move through specialized distributors with temperature-controlled storage capabilities. These intermediaries maintain dual certification documentation for ANSES-qualified and export-EFSA-standard product lines.
- Supermarkets:Private-label sweetener assortments from Carrefour and Intermarché reconfigure how national brands defend shelf space, with reformulated reduced-sugar variants gaining linear meter allocation.
- Online Retailers:Direct-to-consumer channels serve specialty diet segments with monk fruit and allulose products not yet scaled through conventional retail.
- Convenience Stores:Impulse-oriented single-serve sweetener packets target on-the-go beverage customization.
- Health Food Stores:Organic and non-GMO certified alternatives command premium positioning in urban centers.
- Direct Sales:Tereos S.A. and Roquette Freres SA negotiate direct procurement contracts with Occitanie dairy cooperatives, displacing traditional broker-mediated purchasing.
Wholesale Distributors retain industrial volume leadership; Online Retailers expand most quickly into specialty segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Seine-Nord Europe Canal project will eventually link Paris basin industrial zones to Belgian and Dutch port networks, positioning northern France as a multimodal sweetener distribution hub. This infrastructure underwrites the country's role in European ingredient flows.
Île-de-France
Carbonated and functional beverage headquarters cluster near Paris, driving accelerated pilot-to-scale transitions for novel sweetener formulations. ANSES maintains its primary offices here, enabling rapid regulatory consultation on steviol glycoside dossiers. Roquette Freres SA operates formulation laboratories in the region to serve dairy and confectionery clients.
Hauts-de-France
Tereos S.A. anchors beet sugar extraction operations across northern France, supplying sucrose to industrial bakeries and prepared food manufacturers. EU F-Gas Regulation amendments are forcing ammonia-based refrigeration retrofits at polyol crystallization facilities. The Lille metropolitan area concentrates quality assurance specialists managing dual ANSES-EFSA certification protocols.
Auvergne-Rhône-Alpes
Lyon-based food ingredient distributors serve reformulation programs across the Rhône corridor, connecting Roquette's plant-based polyol production to confectionery manufacturers. The region's chemical engineering heritage supports enzymatic bioconversion research into rare sugars. Clermont-Ferrand hosts sensory testing infrastructure for reduced-sugar dairy applications.
Provence-Alpes-Côte d'Azur
Artisan confectionery producers in southern France seek regional botanical differentiation through specialty sweetener sourcing. Direct procurement contracts between Occitanie dairy cooperatives and regional distributors are displacing traditional broker-mediated purchasing. Nice and Marseille function as entry points for Mediterranean-sourced stevia and monk fruit extracts.
Occitanie
Yogurt and fromage frais producers in this region have compressed reformulation cycles to six-month intervals under EU added-sugar labeling pressure. Toulouse-area food science clusters develop clean-label polyol applications for dental health claims. Local cooperatives negotiate volume commitments directly with Tereos S.A. and Cargill Incorporated, bypassing wholesale intermediaries.
France Food Sweetener Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the France Food Sweetener Market. The supplier base exhibits moderate consolidation around beet sugar extraction and starch processing operations, with fragmentation persisting in botanical extract and synthetic dipeptide segments. Three archetypes dominate: agricultural commodity processors with captive raw material supply, fermentation-based polyol specialists leveraging plant-based positioning, and global ingredient distributors managing dual-certification logistics. Competitive moves center on backward integration into beet cultivation contracts and enzymatic bioconversion capacity expansion.
Among agricultural commodity processors, Tereos S.A. and Cargill Incorporated exemplify the scale-driven archetype with integrated European starch and sugar networks. Roquette Freres SA occupies a distinct position as a fermentation specialist emphasizing plant-based polyol production for clean-label applications. These three companies represent the primary competitive anchors shaping procurement relationships with French beverage and dairy manufacturers.
| Leading Market Players |
|---|
| DuPont |
| PureCircle Limited |
| Cargill Incorporated |
| GLG Life Tech Corporation |
| NutraSweet Company |
| Tate & Lyle PLC |
| Tereos S.A. |
| Roquette Freres SA |
| Ingredion Incorporated |
| Others |
Supply & Pricing Matrix
The Seine-Nord Europe Canal corridor links northern French beet processing zones to Belgian and Dutch port networks, concentrating freight cost advantages among Tereos S.A. and Cargill Incorporated while forcing smaller distributors into price-competitive secondary sourcing. This logistics geography creates tiered procurement power where volume buyers extract preferential terms and regional formulators absorb basis risk.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates French sweetener procurement. Premium tiers attach to ANSES-certified novel extracts and organic polyol grades; standard tiers cover conventional beet sucrose and HFCS; economy tiers serve institutional catering with unbranded bulk supply. Price compression runs through standard tiers as supermarket private-label programs force national brand discounting. Beverage producers in Ile-de-France demonstrate lowest price sensitivity due to reformulation urgency; artisan pastry shops in Provence-Alpes-Côte d'Azur show highest elasticity, substituting toward regional botanical alternatives when sucrose spikes.
Supply Chain Analysis
Tariff exposure between EU and Brazilian cane sugar suppliers dominates supply chain risk planning for French distributors. Raw material flows draw from northern French beet cultivation, Belgian starch processing, and Spanish stevia extraction facilities. Single-source vulnerability concentrates in high-purity steviol glycoside supply where PureCircle Limited and GLG Life Tech Corporation control refined output. Distribution runs through temperature-controlled wholesale networks serving industrial bakeries and dairy cooperatives, with direct sales displacing broker intermediation in Occitanie and Provence-Alpes-Côte d'Azur.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France Food Sweetener Market rewards upstream control over sensory science capabilities and dual-certification infrastructure—assets currently concentrated among agricultural processors with captive beet supply. Formulation expertise scarcity creates acquisition premiums for teams bridging analytical chemistry with consumer preference validation.
For Market Incumbents: Pre-empt displacement by locking multi-year beet cultivation contracts in Hauts-de-France before EU Green Deal bioeconomy subsidies attract new entrants. Expand enzymatic bioconversion capacity for rare sugars like allulose to capture beverage reformulation pipelines ahead of sensory limitation constraints on stevia dosage. Defend against Roquette Freres SA's plant-based positioning by securing dental health claim eligibility for proprietary polyol blends. For New Entrants and Emerging Players: Build out regional botanical extraction capabilities in Provence-Alpes-Côte d'Azur to serve artisan confectionery demand for locally sourced clean-label positioning. Target Occitanie dairy cooperatives with direct procurement models that bypass wholesale distributor margins and compress reformulation cycle support to under six months. Enter through monk fruit and allulose specialty channels where online retail penetration outpaces conventional shelf access. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underperforming food ingredient divisions holding EFSA-qualified production lines but lacking French market distribution. Long-term viability hinges on enzymatic processing IP and ANSES regulatory relationships rather than commodity sucrose exposure. Watch for EU-wide added-sugar labeling enforcement as inflection signal accelerating reformulation contract velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Beet Cultivation | Tereos S.A. secures input cost stability against climate yield volatility in northern France. |
| Enzymatic Bioconversion Capacity Expansion | Roquette Freres SA captures rare sugar demand from beverage producers seeking thermal-stable alternatives. |
| Dual Certification Infrastructure Investment | Cargill Incorporated maintains parallel ANSES-EFSA production lines for export-qualified output streams. |
| Direct Procurement Channel Development | Occitanie dairy cooperatives displace wholesale intermediaries through volume commitments with starch processors. |
| Sensory Testing Laboratory Acquisition | Ile-de-France headquarters proximity accelerates pilot-to-scale transitions for novel sweetener formulations. |
Research Methodology
The analysis maps sucrose extraction, steviol glycoside processing, synthetic dipeptide manufacturing, and polyol fermentation sub-sectors, each validated through formulation scientists at beverage producers, procurement directors at dairy cooperatives, and regulatory affairs specialists navigating ANSES protocols. Primary interviews with Roquette Freres SA technical directors and Tereos S.A. supply chain managers combined with secondary validation against EU F-Gas Regulation amendments, EFSA novel food approval databases, and French customs trade flows. Bottom-up volume estimates from individual facility capacities triangulate against top-down market sizing from distribution channel audits.
Assumptions held EU added-sugar labeling revision timelines and ANSES evaluation protocols constant across the projection horizon while varying beet harvest yield scenarios and stevia extract purity breakthroughs. Segmentation dimensions modeled include sweetener type, application heat-stability requirements, end-user scale tier, and distribution channel certification complexity. CAGRs derive from regression against historical reformulation adoption curves and EU Green Deal incentive disbursement patterns. Forecast inputs incorporate enzymatic bioconversion yield improvements and ammonia-based refrigeration retrofit adoption at northern French crystallization facilities.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Asian stevia extractors or sudden EFSA approval accelerations for novel sweeteners would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Xylose Market
Sweeteners
North America Starch Sweetener Market
Sweeteners
Vietnam Food Sweetener Market
Sweeteners
Muscovado Sugar Market
Sweeteners
Europe Sugar Substitute Market
Sweeteners
Global Starch Sweetener Market
Sweeteners
China Allulose Market
Sweeteners
South America Low-Calorie Sweeteners Market
Sweeteners
Crystalline Fructose Market
Sweeteners
Steviol Glycoside Market
Sweeteners
Fructose Market
Sweeteners
Palm Sugar Market
Sweeteners
Sugar Market
Sweeteners
Germany Food Sweetener Market
Sweeteners
Maltol and Ethyl Maltol Market
Sweeteners
Sanding Sugar Market