
 Europe Starch Sweetener Market | 2026-2036
Europe Starch Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Starch Sweetener Market Foresight
The capital-intensity divergence between integrated wet-milling operators and toll-based refiners is bifurcating competitive returns across the Europe Starch Sweetener Market. Cargill Incorporated leverages its Maize Processing footprint to sustain captive supply chains from grain intake through syrup refining. Roquette Frères differentiates through pea and potato starch diversification, while Tate & Lyle PLC anchors its position in specialty texturants and modified glucose systems.
Europe starch sweeteners comprise glucose syrups, maltodextrins, dextrose, and high fructose variants produced through enzymatic hydrolysis of corn, wheat, or potato starch, with DE values ranging from 20 to 100 depending on intended functionality. These ingredients serve primarily as bulk sweeteners, humectants, and texture modifiers in processed foods where sucrose replacement or process stability is required. Liquid sweeteners dominate volume throughput in beverage applications, while maltodextrin captures expanding demand in sports nutrition and infant formula where controlled digestibility matters. Bakery applications favor dry sweeteners for shelf-life extension, though confectionery margins concentrate in specialized glucose-fructose blends.
EMA food additive evaluations, EU Green Deal agricultural reform targets, and national sugar tax regimes in the United Kingdom, France, and Ireland collectively reshape formulation choices and ingredient sourcing across the value chain. REACH compliance for processing aids and the F-Gas Regulation's energy-efficiency mandates further constrain plant economics and technology refresh cycles. Stakeholders must monitor regulatory divergence between EU-wide harmonization and member-state sugar taxation to anticipate demand migration across sweetener categories and end-use segments.
Market Dynamics
EU Green Deal sugar reduction mandates are forcing simultaneous reformulation across beverage, bakery, and confectionery verticals, compressing procurement cycles and rewiring supplier relationships toward integrated starch processors capable of delivering clean-label glucose and fructose systems at scale.
Growth Catalysts
- EU Green Deal agricultural reform targets:Binding sugar reduction timelines in processed foods are accelerating demand for isoglucose and maltodextrin as functional sucrose replacements in Germany's industrial bakery corridor.
- High fructose syrup adoption:Beverage manufacturers across France and Benelux are expanding procurement of reduced-sugar formulations using enzymatically refined fructose variants with controlled DE values.
- Clean-label mandates:EFSA evaluations favoring minimally processed ingredients are concentrating sweetener sourcing among wet-milling operators with captive grain supply chains.
Market Restraints
- Input cost volatility:Maize and wheat price swings at Rotterdam and Hamburg grain terminals transmit directly to syrup refining economics, squeezing toll-based refiners without backward integration into origination.
- Regulatory friction:REACH compliance for enzymatic processing aids and F-Gas Regulation energy-efficiency mandates constrain plant refresh cycles and capital deployment timelines.
- Substitution threat:Stevia and monk fruit extracts are capturing premium beverage formulations where caloric reduction takes priority over bulk sweetening functionality.
Strategic Opportunities
- Poland and Eastern Europe:Underpenetrated industrial bakery and confectionery processing clusters present volume expansion potential as supply chains extend beyond Germany's saturated corridor.
- Sports nutrition application:Maltodextrin demand for controlled-release carbohydrate systems in endurance formulations is outpacing traditional food uses.
- CSRD disclosure requirements:Scope 3 emissions tracking is creating procurement preference for wet-millers with verified supply chain traceability from farm to syrup.
Industry Challenges
- Enzyme engineering talent scarcity:Specialized biochemists capable of optimizing amylase and glucoamylase conversion efficiency command premium compensation, constraining process innovation at mid-scale refiners.
- Capex intensity for F-Gas compliance:Refrigeration system retrofits and heat recovery installations require substantial capital outlays that disadvantage toll-based operators against integrated competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Starch Sweetener Market |
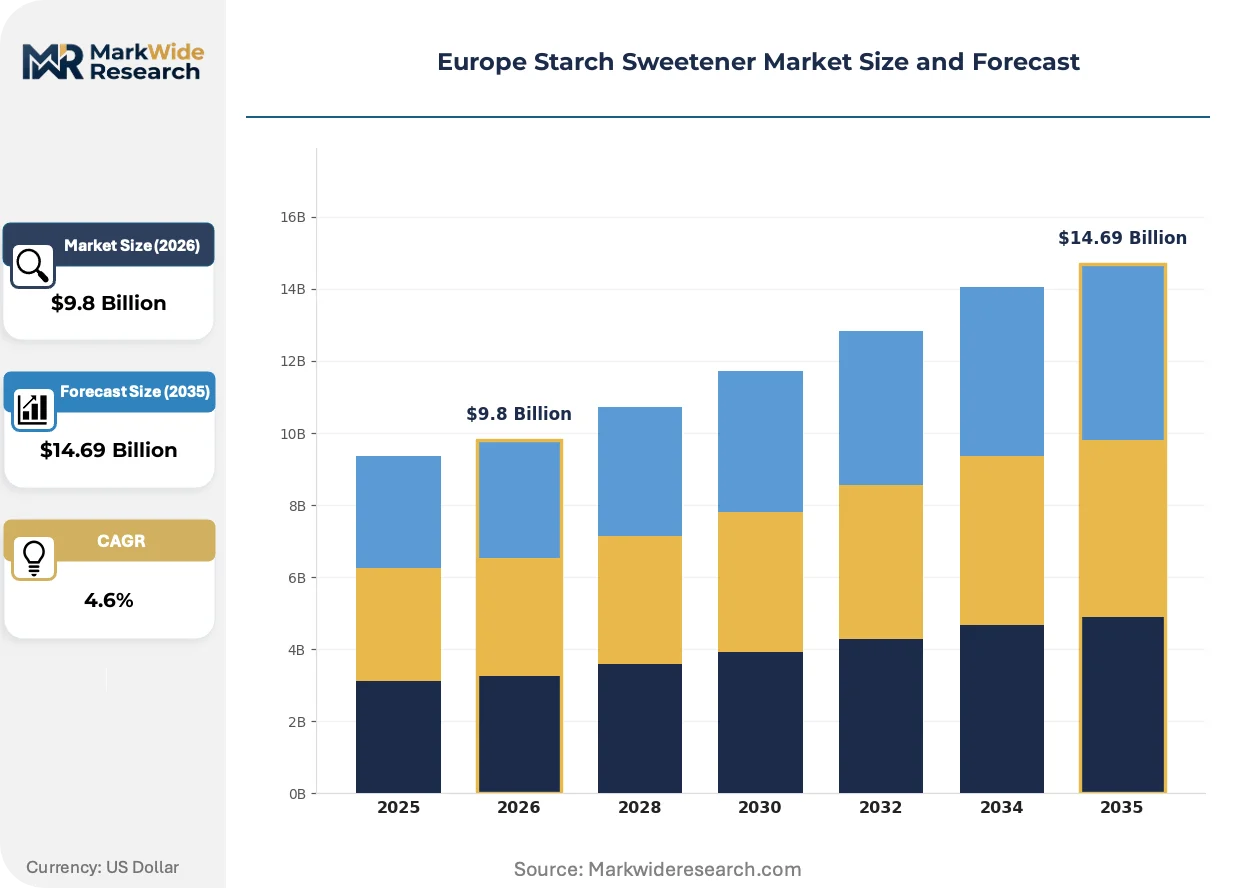
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Sweeteners, Dry Sweeteners, High Fructose Syrup, Maltodextrin Application: Beverages, Bakery, Confectionery, Dairy End User: Food Manufacturers, Beverage Companies, Confectioners, Retail Distribution Channel: Direct Sales, Retail Stores, Online Channels, Distributors |
| Companies Covered | Cargill Incorporated, The Archer Daniels Midland Company, Ingredion Inc., Tate & Lyle PLC, Tereos SA, Uniglad Ingredients UK Ltd, Roquette Frères, AGRANA Beteiligungs-AG, Sedamyl, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Starch Sweetener Market Shifts & Advancements
Enzymatic precision is displacing traditional acid hydrolysis across European starch processing, enabling tighter DE control and cleaner label positioning. Wet-millers are retrofitting continuous bioreactor systems to capture efficiency gains and regulatory compliance simultaneously.
Precision enzymatic hydrolysis is decomposing the historic trade-off between conversion efficiency and product purity in glucose syrup production. German and Dutch beverage formulators are adopting DE-specific maltodextrin fractions at accelerated rates. This technology is decomposing cost structures for mid-tier refiners still reliant on batch acid conversion, compressing their margin recovery timelines.
REACH authorization requirements for processing aids are tightening substance approval timelines for enzymes used in starch conversion. Industrial users face reformulation delays when preferred biocatalysts enter sunset review. Benelux beverage processors are pre-qualifying alternative enzyme suppliers to hedge authorization uncertainty.
Buyer concentration among pan-European beverage and bakery groups is compressing supplier negotiation cycles and unbundling technical service from commodity supply contracts. Direct procurement teams at multinational formulators are displacing traditional distributor networks for standard glucose and fructose grades. This pattern is most visible in France and Germany where three buyers account for disproportionate volume allocation.
Europe Starch Sweetener Market Segmentation
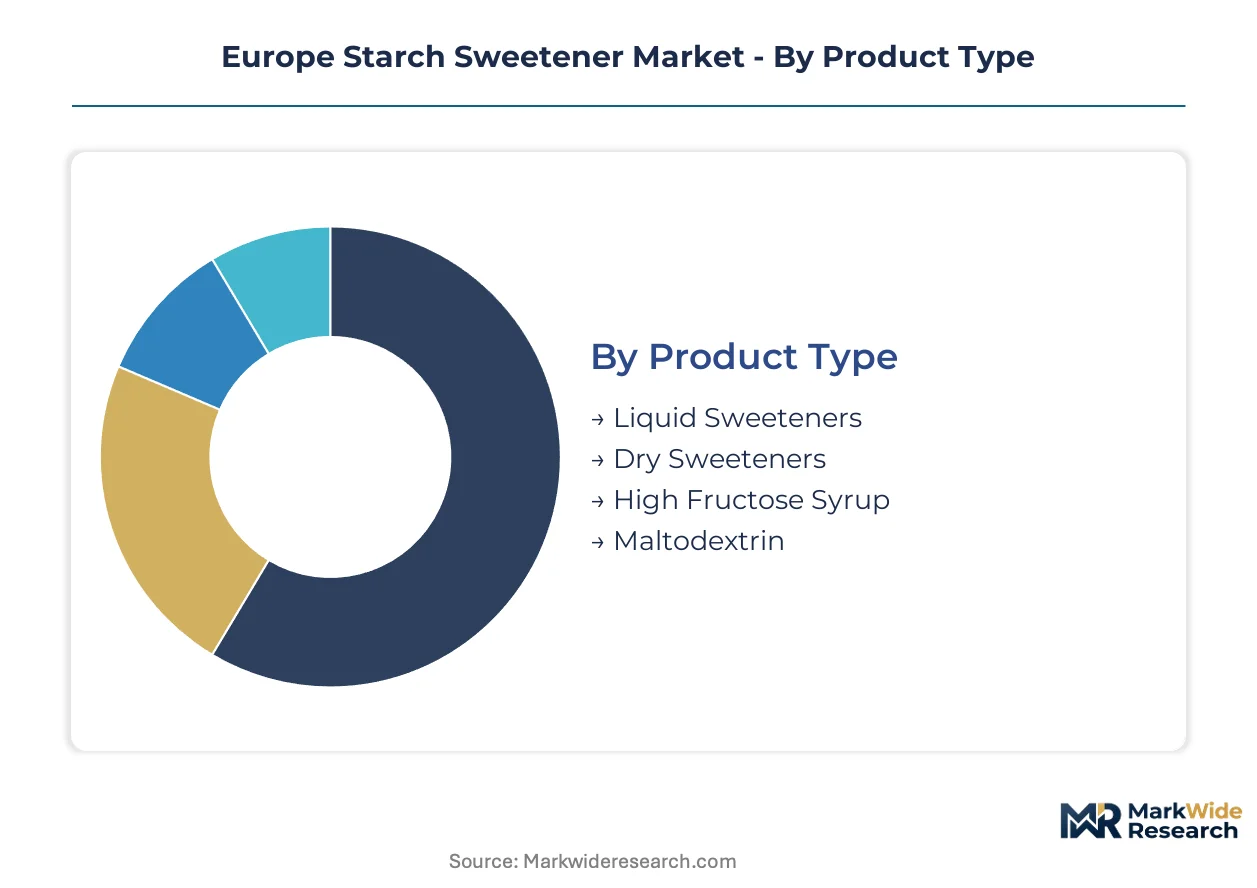
Margin pools across the Europe Starch Sweetener Market concentrate in high-specification liquid formulations and specialized maltodextrin fractions. Segmentation reveals how wet-milling operators allocate capacity between commodity glucose syrups and premium functional ingredients.
Product Type:
Margins concentrate in enzymatically refined fractions where DE precision commands formulation premiums over standard glucose commodities.
- Liquid Sweeteners:Glucose syrups with DE values from 38 to 64 serve as the workhorse bulk sweetener across beverage and bakery applications. German industrial bakers in the North Rhine-Westphalia corridor source DE 42-43 glucose for optimal fermentation control and moisture retention in extended shelf-life products.
- Maltodextrin:Controlled hydrolysis produces DE 10-20 fractions with specific dextrose equivalent ranges for sports nutrition and infant formula. French endurance nutrition brands specify DE 12-15 maltodextrin for glycemic index management, driving capacity expansion at Roquette's Lestrem facility.
- High Fructose Syrup:Enzymatic isomerization yields 42% or 55% fructose content for reduced-sugar beverage formulations. Benelux processors favor this grade for clean-label positioning under EU Green Deal sugar reduction timelines.
- Dry Sweeteners:Spray-dried glucose and dextrose monohydrate provide shelf-stable alternatives for confectionery dusting and dry mix applications. Powdered formats reduce transportation costs for inland European processors distant from liquid syrup terminals.
Liquid Sweeteners hold installed capacity. Maltodextrin is rotating up the share rankings.
Application:
Volume throughput concentrates in beverage processing clusters where reformulation cycles accelerate procurement frequency.
- Beverages:High fructose and glucose syrups constitute the primary caloric base for carbonated soft drinks, fruit nectars, and energy drinks. French bottlers in the Île-de-France region are expanding isoglucose procurement to meet ANSM sugar reduction guidance without sacrificing mouthfeel.
- Bakery:Glucose syrups and maltodextrin control moisture, extend shelf life, and enable Maillard browning in industrial bread and pastry. Germany's industrial bakery corridor from Hamburg to Munich consumes disproportionate volumes of DE 38-42 glucose for standardized product consistency.
- Confectionery:Specialized glucose-fructose blends prevent sucrose crystallization in hard candies and fondants. Belgian chocolate and confectionery houses source specific viscosity grades for enrobing and center-fill applications.
- Dairy:Maltodextrin and glucose syrups replace sucrose in flavored yogurts and ice cream while controlling freezing point depression. Dutch dairy processors leverage starch sweeteners for clean-label reformulations targeting German retail channels.
Beverages maintain the largest demand base. Bakery is expanding most quickly as sugar tax regimes tighten.
End User:
Procurement power concentrates among pan-European formulators with direct technical service requirements.
- Food Manufacturers:Industrial bakeries, sauce producers, and prepared meal companies source standard glucose and maltodextrin grades through annual contracts. German and Polish meat processors use glucose syrups in cured and marinated products for color stabilization.
- Beverage Companies:Multinational bottlers and regional mineral water brands drive specification innovation for reduced-calorie lines. Direct procurement teams at French beverage groups are displacing traditional distributor relationships for high fructose grades.
- Confectioners:Artisan and industrial chocolate houses demand precise viscosity control and crystallization inhibition. Belgian praline manufacturers specify low-DE glucose syrups for extended shelf stability in export markets.
- Retail:Private-label grocery chains and food service distributors source packaged sweeteners for consumer and small commercial use. German discounters are expanding own-brand maltodextrin offerings for home baking and sports nutrition segments.
Food Manufacturers command the deepest supplier relationships. Beverage Companies are gaining procurement sophistication fastest.
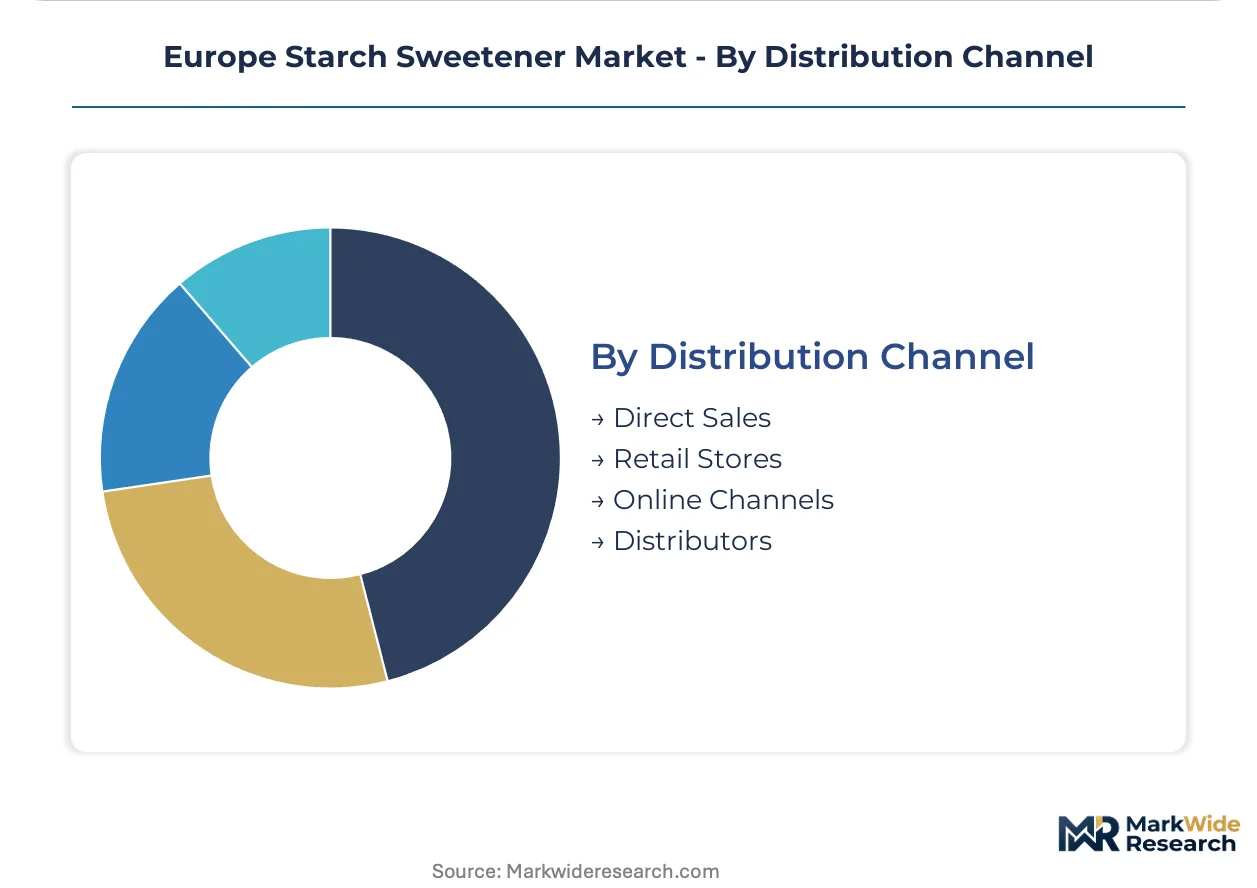
Distribution Channel:
Channel economics bifurcate between bulk liquid logistics and packaged dry goods handling.
- Direct Sales:Wet-milling operators deliver liquid sweeteners via dedicated tanker fleets to large beverage and bakery plants. Cargill's European network maintains direct pipeline connections to major German and French formulators.
- Distributors:Regional chemical and ingredient distributors aggregate smaller orders for mid-scale food processors. Benelux distributors specialize in just-in-time maltodextrin delivery to sports nutrition startups.
- Online Channels:E-commerce platforms serve artisan food producers and research institutions requiring small-batch specialty grades. Dutch ingredient marketplaces are expanding DE-specific glucose offerings for craft confectioners.
- Retail Stores:Cash-and-carry outlets and agricultural cooperatives supply small bakeries and food service operators with packaged dry sweeteners. French bakery supply chains maintain counter-stock glucose and dextrose for neighborhood patisseries.
Direct Sales anchors volume throughput. Distributors are consolidating regional coverage most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement elasticity varies sharply across Europe, with Benelux beverage processors least price-sensitive due to reformulation urgency, while Polish industrial bakers remain highly sensitive to glucose syrup differentials. This divergence reshapes supplier negotiation leverage and contract structures.
Germany
Industrial bakery corridors from Hamburg to Munich consume disproportionate volumes of DE 38-42 glucose for fermentation control and shelf-life extension. The EU Green Deal sugar reduction targets accelerate reformulation timelines for processed bread and pastry. North Rhine-Westphalia's concentrated baking infrastructure sources directly from wet-milling operators with captive grain intake.
France
Beverage manufacturers in Île-de-France expand high fructose syrup procurement for reduced-sugar carbonated and nectar formulations. ANSM sugar reduction guidance tightens formulation windows without sacrificing mouthfeel characteristics. The Lestrem industrial cluster anchors specialized maltodextrin capacity for sports nutrition brands specifying DE 12-15 fractions.
Netherlands
Dairy processors leverage starch sweeteners for clean-label ice cream and yogurt reformulations targeting German retail channels. REACH compliance requirements for enzymatic processing aids constrain substance approval timelines. Rotterdam's liquid logistics hub enables just-in-time glucose delivery to multinational formulators with direct procurement teams.
Belgium
Confectionery houses demand precise viscosity grades for chocolate enrobing and praline center-fill applications. EFSA evaluations favoring minimally processed ingredients concentrate sourcing among integrated wet-millers. The Flanders processing cluster sources low-DE glucose syrups for extended export shelf stability.
Poland
Underpenetrated industrial bakery and confectionery clusters present volume expansion potential as supply chains extend westward. National sugar tax regimes remain less stringent than Western European counterparts, preserving sucrose cost advantages. Warsaw and Łódź meat processors utilize glucose syrups for cured product color stabilization.
Europe Starch Sweetener Market Competitive Landscape
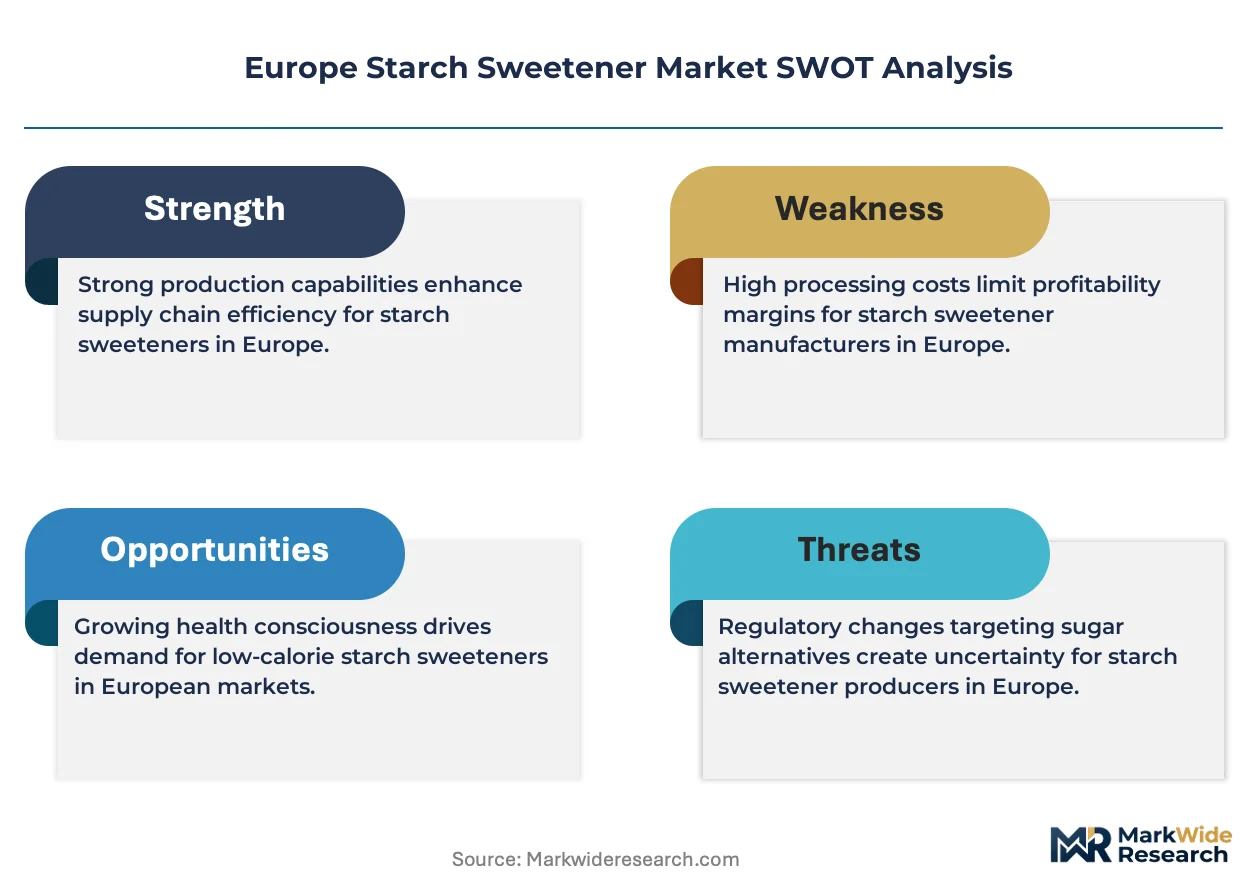
A small set of integrated leaders sits above a broader specialist tier, with capital-intensity divergence bifurcating competitive returns across wet-milling and toll-based models. Three strategic archetypes dominate: grain-originating processors with captive supply chains, diversified starch specialists leveraging pea and potato inputs, and modified glucose system providers targeting premium texturant applications. Capacity expansion and portfolio diversification constitute the dominant competitive moves, as mid-scale refiners face margin compression from enzymatic precision investments.
Among integrated wet-milling operators, Cargill Incorporated anchors the grain-originating archetype with Maize Processing footprint extending from intake through syrup refining. Roquette Frères exemplifies the diversified starch specialist position through pea and potato starch differentiation strategies. Tate & Lyle PLC occupies the premium functional tier, anchoring specialty texturant and modified glucose system supply relationships with multinational formulators.
| Leading Market Players |
|---|
| Cargill Incorporated |
| The Archer Daniels Midland Company |
| Ingredion Inc. |
| Tate & Lyle PLC |
| Tereos SA |
| Uniglad Ingredients UK Ltd |
| Roquette Frères |
| AGRANA Beteiligungs-AG |
| Sedamyl |
| Others |
Supply & Pricing Matrix
Capacity utilization at Rotterdam and Hamburg grain terminals shapes margin recovery timelines for wet-milling operators versus toll-based refiners across the Europe Starch Sweetener Market. Scale concentration among integrated processors with captive grain intake establishes price floors that mid-scale competitors cannot match without backward integration into origination.
Pricing Analysis
After-sales technical service contracts and formulation support agreements drive lifetime value beyond commodity syrup supply. Three-tier pricing structure across premium enzymatic fractions, standard glucose grades, and economy maltodextrin separates Cargill's Maize Processing network from regional toll refiners. Price differentiation hinges on DE precision certification and volume scale commitments from pan-European beverage formulators. Cost compression in standard glucose grades is intensifying because German industrial bakers are consolidating procurement around fewer suppliers with direct tanker delivery. Polish meat processors show highest price sensitivity due to less stringent sugar tax regimes preserving sucrose alternatives.
Supply Chain Analysis
Germany and France anchor wet-milling capacity for glucose syrup refining and high fructose production serving Benelux beverage processors. Maize and wheat grain flows from Rotterdam terminals, enzymatic processing aids under REACH authorization, and specialized amylase biocatalysts feed conversion economics. Single-source vulnerability concentrates in German industrial bakery corridors where three buyers command disproportionate volume allocation. Distribution runs through dedicated tanker fleets for liquid sweeteners and regional chemical distributors for packaged maltodextrin grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs supplier-buyer relationships as direct procurement teams at multinational formulators displace traditional distributor networks. Interoperability between CSRD emissions tracking systems and wet-miller supply chain traceability creates new procurement preference hierarchies.
For Market Incumbents: Shield margin position by deepening backward integration into Polish and Eastern European grain origination to offset Rotterdam price volatility. Prioritize F-Gas Regulation compliance investments ahead of regulatory deadlines to strand mid-scale refiner capacity. The substitution threat from stevia and monk fruit extracts in premium beverage formulations demands accelerated specialty maltodextrin R&D at Roquette's Lestrem facility. For New Entrants and Emerging Players: Anchor in Poland's underpenetrated industrial bakery and confectionery clusters where national sugar tax regimes preserve glucose syrup cost advantages against Western European benchmarks. Target sports nutrition applications for controlled-release maltodextrin systems where DE 12-15 specifications command formulation premiums. Pursue just-in-time distributor partnerships with Benelux beverage startups rather than direct sales infrastructure. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors wet-milling operators with verified Scope 3 emissions tracking and captive grain supply chains over toll-based refining models. Long-term viability across the analysis window rests on enzymatic precision capabilities and REACH-compliant processing aid portfolios. Watch enzyme engineering talent scarcity as the inflection signal — specialized biochemist compensation premiums indicate which processors can sustain conversion efficiency gains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | Cargill's Maize Processing network secures captive supply from Polish and Eastern European intake terminals. |
| Enzymatic Precision Technology Investment | Continuous bioreactor retrofits at German wet-milling facilities capture efficiency gains and regulatory compliance. |
| CSRD-Compliant Supply Chain Traceability | Verified farm-to-syrup emissions tracking creates procurement preference among pan-European beverage formulators. |
| Specialty Maltodextrin Capacity Expansion | Roquette's Lestrem facility targets DE 12-15 fractions for French endurance nutrition brands. |
| Direct Procurement Team Engagement | Multinational formulators in Île-de-France displace distributor relationships for high fructose grades. |
Research Methodology
Cross-validation between primary interviews with wet-milling plant managers, beverage procurement directors, and bakery R&D leads and secondary validation anchors the qualitative findings. Stakeholder roles span enzymatic biochemists at processing facilities, distribution channel partners in Benelux, technical service heads at ingredient suppliers, and regulatory affairs specialists navigating REACH authorization. Secondary sources include EFSA additive evaluations, EU Green Deal agricultural reform documentation, customs data from Rotterdam and Hamburg terminals, and SEC filings from publicly traded processors. Bottom-up capacity modeling and top-down demand triangulation from end-use consumption patterns reconcile volume estimates.
Sensitivity analysis across input cost scenarios and regulatory implementation timelines tests forecast robustness. Segmentation dimensions span product type, application vertical, end-user procurement sophistication, and distribution channel structure. CAGRs derive from installed capacity utilization trends and reformulation cycle frequency across the projection horizon. Industry-specific inputs include enzyme conversion efficiency benchmarks and F-Gas Regulation compliance cost curves.
Material uncertainties — maize price volatility at Rotterdam, REACH sunset reviews for preferred biocatalysts, and member-state sugar tax divergence — sit outside the modeled envelope. Forecasts reflect assumptions about EU Green Deal implementation pacing and clean-label mandate enforcement consistency. Recalibration cycles align with material shifts in EMA food additive evaluations and national sugar reduction guidance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Vietnam Food Sweetener Market
Sweeteners
Monk Fruit Sweetener Market
Sweeteners
D Psicose Market
Sweeteners
Sucrose Esters Market
Sweeteners
Global Stevia Sugar Blends Market
Sweeteners
Dextrose Syrup Market
Sweeteners
Galactose Market
Sweeteners
Natural Caloric Sweeteners Market
Sweeteners
Argentina Food Sweetener Market
Sweeteners
India Cane Sugar Market
Sweeteners
Indonesia Food Sweetener Market
Sweeteners
Tagatose Market
Sweeteners
D-Mannose Market
Sweeteners
Middle East and Africa Food Sweetener Market
Sweeteners
Starch Glucose Syrup Market
Sweeteners
Date Sugar Market