
 Malaria Vaccine Market | 2026-2036
Malaria Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Malaria Vaccine Market Intelligence
WHO prequalification is restructuring the cost-of-entry calculus for malaria vaccine developers by mandating stringent stability, efficacy, and cold-chain standards before procurement eligibility. GlaxoSmithKline leverages decades of RTS,S manufacturing expertise to sustain supply commitments across African immunization programs. Serum Institute of India anchors high-volume, low-cost production capacity that competes on price in Gavi-negotiated tenders. BioNTech differentiates through mRNA platform adaptability, positioning rapid antigen redesign against emerging parasite strains.
A malaria vaccine is a biological preparation containing attenuated parasites, recombinant proteins, or nucleic acid constructs formulated to elicit protective immunity against Plasmodium falciparum or Plasmodium vivax infection, typically requiring adjuvant systems and cold-chain storage at two to eight degrees Celsius. Its primary purpose is preventing clinical malaria in endemic regions, reducing severe disease burden, and supporting elimination campaigns in high-transmission zones. Recombinant vaccines occupy the fastest-expanding segment as platform technologies enable precise antigen targeting and scalable manufacturing. Public health programs dominate distribution channels, though private clinics in urban Nigerian and Kenyan centers represent an emerging margin pool for premium-priced traveler vaccines.
FDA and EMA guidelines on adjuvant safety and lot-to-lot consistency shape clinical trial design and manufacturing standards for developers seeking Western market access, while WHO prequalification determines eligibility for UN agency procurement across endemic countries. National regulators in Ghana, Kenya, and Nigeria adopt WHO standards to accelerate local registration, streamlining market entry for prequalified products. Stakeholders must monitor parasite resistance patterns and regulatory harmonization progress across African medicines agencies to anticipate formulation updates and procurement policy shifts.
Market Dynamics
WHO prequalification mandates are compressing the developer landscape by forcing costly cold-chain validation and lot-to-lot consistency protocols that only scaled manufacturers can absorb.
Growth Catalysts
- Gavi procurement guarantees:Advance market commitments from the vaccine alliance de-risk manufacturing scale-up for prequalified suppliers across endemic African markets.
- Recombinant protein platforms:Precision antigen engineering enables rapid strain adaptation without live-attenuated production complexity.
- Nigeria:Federal Ministry of Health integration of malaria vaccines into routine immunization schedules creates predictable demand pull.
Market Restraints
- Adjuvant supply concentration:QS-21 and MPL analog sourcing depends on captive botanical extraction capacity concentrated in select temperate zones.
- Cold-chain infrastructure gaps:Last-mile storage at two to eight degrees Celsius fails across rural Kenyan and Ghanaian distribution nodes.
- Parasite antigenic variation:Circumsporozoite protein polymorphisms reduce field efficacy against regional Plasmodium falciparum strains.
Strategic Opportunities
- Thermostable formulations:Excipient innovations eliminating frozen storage open procurement eligibility for health posts lacking cold-chain equipment.
- Traveler vaccination clinics:Premium-priced pre-departure immunization for European and North American visitors to endemic zones builds margin outside Gavi tenders.
- Plasmodium vivax candidates:Relapse-prevention vaccines address the neglected vivax burden across Southeast Asian and Latin American markets.
Industry Challenges
- Regulatory divergence:WHO prequalification timelines misalign with FDA and EMA adjuvant safety review cycles, delaying multi-jurisdiction filings.
- Clinical trial site access:Seasonal transmission windows in target geographies compress enrollment windows and extend study duration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaria Vaccine Market |
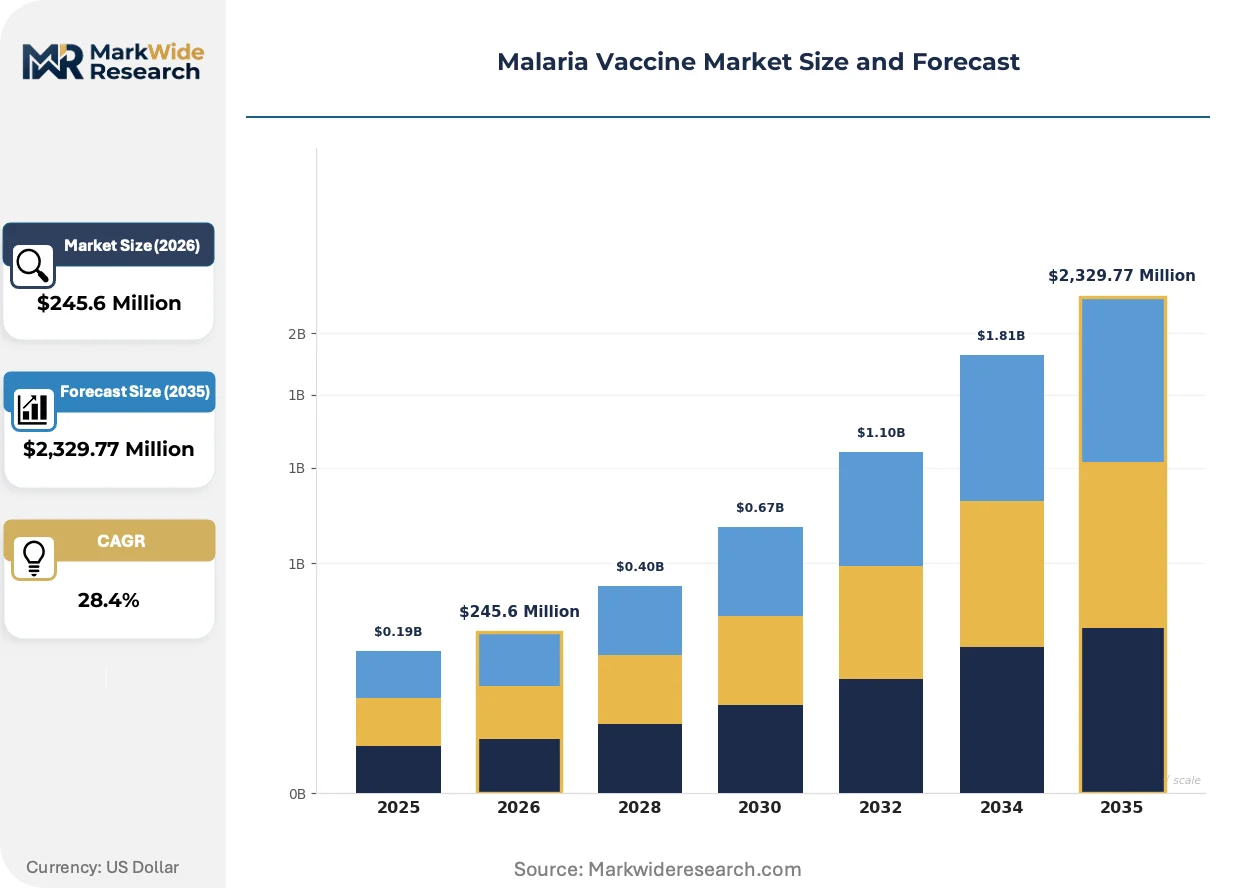
| Market Size in 2026 | $245.6 Million |
| Market Size in 2035 | $2,329.77 Million |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Live Attenuated, Inactivated, Subunit, Recombinant Application: Travelers, At-Risk Populations, Health Workers, Pediatric Usage Administration Route: Intramuscular, Subcutaneous, Oral, Intranasal Distribution Channel: Public Health Programs, Private Clinics, Hospitals, Pharmacies |
| Companies Covered | GlaxoSmithKline, Merck, Pfizer, Sanofi, Bharat Biotech, Serum Institute of India, BioNTech, Novavax, Janssen Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaria Vaccine Market Strategic Shifts & Innovations
mRNA platform adaptability is redirecting R&D investment away from recombinant cell culture toward synthetic manufacturing that compresses antigen redesign cycles.
Nucleic acid delivery systems are consolidating competitive positioning among developers seeking rapid response to emerging parasite variants. African immunization programs are piloting mRNA candidates alongside protein-based alternatives to diversify supply security. This platform shift is compressing the traditional ten-year development timeline toward compressed validation cycles.
WHO prequalification standards are tightening stability documentation requirements for adjuvanted formulations. Developers must now submit real-time thermal degradation data across thirty-six months rather than accelerated studies. Sub-Saharan procurement eligibility hinges on this extended validation, favoring manufacturers with legacy stability databases.
Public health programs are unbundling vaccine procurement from delivery service contracts. Ghana and Kenya now tender supply separately from cold-chain logistics, enabling specialized distributors to compete on last-mile performance. This separation is fragmenting vendor relationships and compressing margins for integrated suppliers.
Malaria Vaccine Market Segmentation
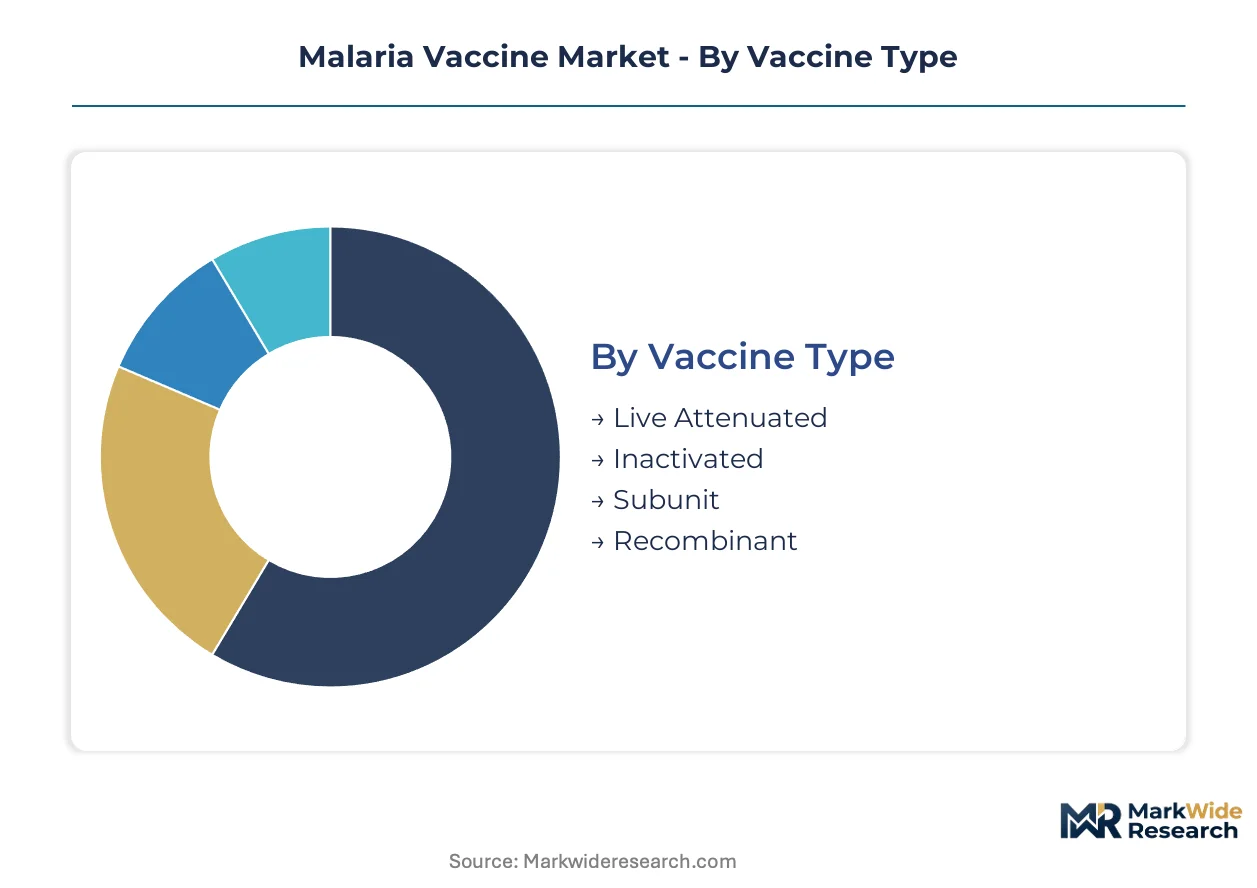
Segmentation in malaria vaccines determines which development pathways unlock procurement eligibility. WHO prequalification standards vary sharply across vaccine architectures, channeling R&D investment toward platforms that can demonstrate stability under tropical field conditions.
Vaccine Type:
WHO prequalification mandates divergent stability documentation for each platform, with recombinant protein and subunit candidates facing accelerated thermal degradation protocols that live-attenuated formulations bypass through lyophilization.
- Recombinant:Precision antigen engineering enables circumsporozoite protein targeting without whole-parasite cultivation. Demand concentrates in Gavi-negotiated tenders across Nigeria, Ghana, and Kenya where national control programs prioritize scalable, thermostable supply. Cold-chain requirements at two to eight degrees Celsius limit last-mile reach.
- Subunit:Purified protein fragments formulated with AS01 or Matrix-M adjuvants elicit humoral immunity against specific life-cycle stages. Pediatric immunization programs in sub-Saharan Africa drive procurement volume, though adjuvant sourcing concentration creates supply vulnerability.
- Live Attenuated:Chemically or radiation-attenuated sporozoites confer cellular immunity through controlled infection.
- Inactivated:Whole-parasite preparations destroyed by chemical or physical methods retain immunogenicity without replication risk.
Leading the category by volume: Recombinant. Growing fastest: Subunit.
Application:
Cost tier stratification separates mass immunization programs from premium-priced traveler segments, with pediatric usage commanding lowest per-dose pricing under Gavi volume guarantees.
- Pediatric Usage:Routine immunization schedules in endemic countries target children under five years, the demographic bearing highest severe malaria burden. Nigeria's Federal Ministry of Health integration creates predictable demand pull through existing health facility networks.
- Travelers:Pre-departure immunization for European and North American visitors to endemic zones commands 15-20x pricing multiples over public program supply. Urban clinics in Nairobi and Lagos capture this margin pool.
- At-Risk Populations:Pregnant women and semi-immune adults in high-transmission zones receive targeted campaigns.
- Health Workers:Frontline staff in malaria-endemic regions require protection to sustain elimination program staffing.
Pediatric usage dominates procurement tonnage. Traveler vaccination delivers steepest margin expansion.
Administration Route:
Supply concentration in injectable delivery systems favors intramuscular and subcutaneous platforms with established cold-chain infrastructure, while oral and intranasal alternatives remain preclinical.
- Intramuscular:Deltoid or anterolateral thigh injection of adjuvanted formulations generates strongest antibody titers. WHO prequalified products from Serum Institute of India and GSK deploy this route across African immunization programs.
- Subcutaneous:Lower-dose antigen delivery reduces reactogenicity in pediatric populations. Kenyan and Ghanaian health posts favor this route for community health worker administration.
- Oral:Enteric-coated sporozoite formulations bypass injection requirements entirely.
- Intranasal:Mucosal delivery targets IgA-mediated protection at parasite entry sites.
Intramuscular administration anchors current supply. Subcutaneous delivery is gaining share fastest in community-based programs.
Distribution Channel:
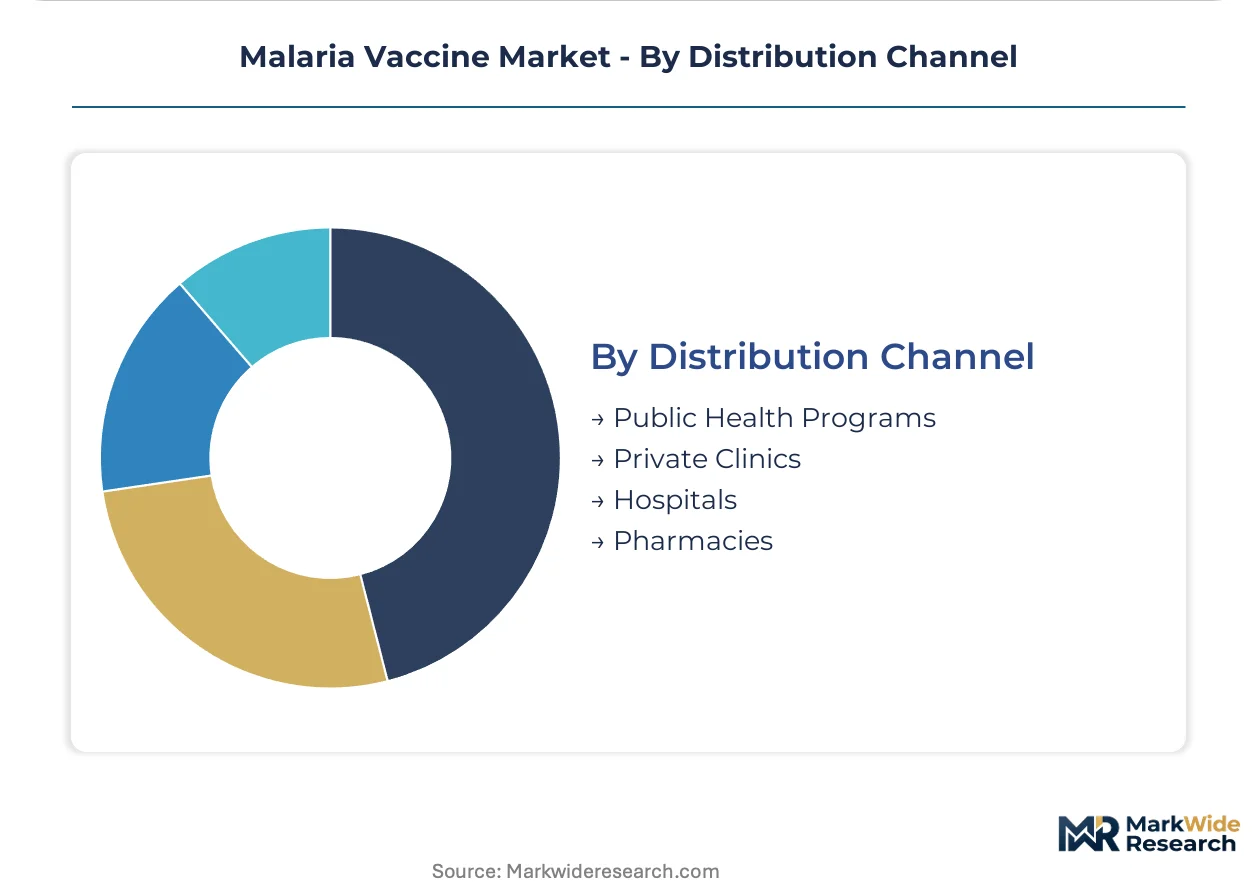
Customer type fragmentation separates institutional procurement from retail pharmacy access, with public health programs capturing volume and private clinics extracting premium pricing.
- Public Health Programs:Gavi-funded national immunization schedules coordinate centralized procurement through UNICEF Supply Division. Cold-chain logistics unbundling in Ghana and Kenya enables specialized last-mile distributors to compete on performance.
- Private Clinics:Urban Nigerian and Kenyan centers serve expatriate communities and affluent domestic travelers with premium-priced, rapid-schedule immunization outside routine campaign calendars.
- Hospitals:Tertiary referral centers manage severe malaria cases and administer vaccines to admitted at-risk patients.
- Pharmacies:Retail drug stores in Lagos and Nairobi pilot over-the-counter traveler vaccination with pharmacist-administered dosing.
Public health programs lead by procurement volume. Private clinics deliver fastest margin growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nigeria, Ghana, and Kenya concentrate procurement demand through Gavi-funded national immunization programs, while manufacturing capacity clusters in India and Europe serve these endemic markets through WHO-prequalified supply chains.
Nigeria
Federal Ministry of Health integration of malaria vaccines into routine immunization schedules generates predictable demand pull through existing health facility networks. The National Agency for Food and Drug Administration and Control adopts WHO prequalification standards to accelerate local registration of imported vaccines. Lagos and Abuja anchor cold-chain distribution hubs where UNICEF Supply Division coordinates centralized procurement.
Ghana
Expanded Programme on Immunization campaigns target children under five years in high-transmission northern regions. The Food and Drugs Authority harmonizes regulatory requirements with WHO standards to streamline market entry for prequalified suppliers. Accra and Kumasi concentrate private clinic networks serving traveler vaccination demand at premium pricing multiples.
Kenya
National Malaria Control Programme coordinates subcutaneous vaccine administration through community health worker networks in rural distribution nodes. The Pharmacy and Poisons Board enforces stability documentation requirements for adjuvanted formulations entering the market. Nairobi anchors both public sector procurement and private urban clinics capturing expatriate traveler segments.
India
Serum Institute of India anchors high-volume, low-cost recombinant protein production capacity competing in Gavi-negotiated tenders. The Central Drugs Standard Control Organization mandates stringent cold-chain validation protocols for export-oriented manufacturing. Pune and Hyderabad concentrate biologics production clusters serving African immunization programs.
United Kingdom
GlaxoSmithKline leverages decades of RTS,S manufacturing expertise from European supply bases to sustain commitments across African markets. The Medicines and Healthcare products Regulatory Agency shapes clinical trial design standards that influence WHO prequalification timelines. London and Cambridge anchor R&D clusters developing next-generation subunit candidates.
Malaria Vaccine Market Key Industry Players
European pharmaceutical conglomerates anchor one tier through legacy recombinant platforms and established WHO prequalification portfolios; Indian biologics specialists hold a second tier through high-volume, low-cost manufacturing capacity competing on Gavi tender pricing. The developer landscape compresses around scaled manufacturers capable of absorbing extended stability validation costs and cold-chain infrastructure investments. Three strategic archetypes dominate: platform technology innovators pursuing mRNA adaptability, established recombinant producers defending supply commitments, and emerging market manufacturers competing on procurement price. Competitive intensity concentrates on thermostable formulation development and last-mile distribution partnerships.
Within the established recombinant tier, GlaxoSmithKline and Serum Institute of India exemplify divergent geographic positioning—European heritage manufacturing against South Asian volume production. BioNTech occupies a position representing platform technology disruption through synthetic manufacturing approaches. These three anchors illustrate how competitive advantage separates across legacy supply relationships, cost-optimized scale, and rapid antigen redesign capability.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Merck |
| Pfizer |
| Sanofi |
| Bharat Biotech |
| Serum Institute of India |
| BioNTech |
| Novavax |
| Janssen Pharmaceuticals |
| Others |
Cost & Logistics Intelligence
QS-21 saponin pricing volatility cascades through adjuvant-dependent formulation tiers, compressing margins for subunit vaccines while thermostable recombinant platforms capture procurement premiums through reduced cold-chain burden.
Pricing Analysis
Volume procurement through Gavi tenders trades at fifteen-to-twenty-fold discounts against traveler clinic premiums. Price differentiation rests on WHO prequalification status and cold-chain requirement stringency, with AS01-adjuvanted products commanding premium positioning over Matrix-M alternatives. Cost compression in pediatric supply intensifies as Serum Institute of India and GSK compete on tender pricing. Public health programs exhibit extreme price sensitivity; private clinics in Lagos and Nairobi demonstrate minimal elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Chilean and Bolivian botanical extraction capacity for QS-21 saponin adjuvants. Manufacturing concentration clusters in India, the United Kingdom, and Germany for recombinant protein production. Raw material dependencies include captive saponin supply, lipid nanoparticle formulations, and specialized cell culture media. Tariff exposure on adjuvant imports into African markets threatens cost structures. Distribution runs through UNICEF Supply Division coordination with specialized last-mile cold-chain operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
WHO prequalification mandates erect a cost-of-compliance barrier that favors scaled manufacturers with legacy stability databases and validated cold-chain infrastructure, marginalizing development-stage entrants lacking capital reserves for extended validation cycles.
For Market Incumbents: To counter mRNA platform disruption from BioNTech and Novavax, GSK and Serum Institute of India should deepen backward integration into adjuvant sourcing through captive botanical extraction partnerships in temperate zones. Capacity addition in thermostable formulation manufacturing across Indian and European production hubs preserves procurement eligibility as WHO stability documentation requirements tighten. For New Entrants and Emerging Players: Urban traveler vaccination clinics in Nairobi, Lagos, and Accra represent an underserved buyer archetype with minimal price sensitivity and rapid immunization scheduling demands. Southeast Asian Plasmodium vivax markets offer white-space penetration opportunity outside Gavi tender competition. A direct-to-clinic distribution model bypassing centralized procurement channels enables margin capture unavailable to volume suppliers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale recombinant manufacturers with pending WHO prequalification submissions in India and Europe. Long-term viability over a five-to-ten-year window hinges on thermostable formulation portfolios and established African distribution partnerships. The signal to watch is regulatory harmonization progress across African medicines agencies as an inflection indicator for procurement policy consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Submission | Unlocks Gavi-negotiated tender eligibility across Nigerian, Ghanaian, and Kenyan national programs. |
| Thermostable Formulation Development | Eliminates frozen storage requirements, expanding procurement access to rural health posts lacking cold-chain infrastructure. |
| Adjuvant Backward Integration | Captive QS-21 sourcing from Chilean extraction partnerships insulates against supply concentration risk. |
| Traveler Clinic Distribution Partnership | Premium pricing multiples in urban Nigerian and Kenyan centers build margin outside volume tenders. |
| Plasmodium Vivax Pipeline Expansion | Addresses neglected relapse-prevention demand across Southeast Asian and Latin American markets. |
Research Approach
FDA filings, EMA submissions, and WHO prequalification databases formed the secondary backbone, supplemented by ClinicalTrials.gov records and Gavi procurement disclosures. Primary interviews with vaccine development executives, regulatory affairs leads at African national control programs, and UNICEF Supply Division procurement managers validated demand assumptions. Bottom-up modeling of pediatric immunization schedules across Nigeria, Ghana, and Kenya was triangulated against top-down Gavi funding allocation analysis.
Historical trendline analysis of recombinant protein and mRNA platform adoption informed projection frameworks across the analysis window. Segmentation dimensions included vaccine architecture, administration route, patient population, and regional regulatory cluster. CAGRs were derived from logistic diffusion modeling of immunization program penetration rates, incorporating WHO prequalification timeline assumptions and cold-chain infrastructure rollout forecasts as industry-specific inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to parasite antigenic variation, adjuvant supply disruptions, and regulatory harmonization delays across African medicines agencies. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Research
North America Biobanks Market
Medical Research
Epigenetics Market
Medical Research
Global Human Liver Models Market
Medical Research
Global in Vitro Lung Model Market
Medical Research
Precision Medicine Market
Medical Research
US Academic Medical Centers Market
Medical Research
Organoids and Spheroids Market
Medical Research
Methicillin-Resistant Staphylococcus Aureus (MRSA) Drugs Market
Medical Research
Medical Device Contract Research Organization Market
Medical Research
Cancer Mouse Models Market
Medical Research
Human Osteoblasts Market
Medical Research
Global Mice Model Market
Medical Research
Global Patient Derived Xenograft Models Market
Medical Research
Placenta Market
Medical Research
PDX Models Market
Medical Research
Epigenomics Market