
 Rapid Diagnostics Market | 2026-2036
Rapid Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Rapid Diagnostics Market Intelligence
Software-defined assay interpretation is pivoting the commercial model from capital-heavy instrument sales toward recurring revenue streams. Abbott leverages its integrated digital platform to sustain instrument placement through consumable lock-in across cardiovascular and infectious disease panels. Roche anchors its competitive position through proprietary chemistry systems that dominate high-throughput laboratory workflows. Danaher differentiates via operational excellence and channel control across its life sciences and diagnostics operating companies.
Rapid diagnostics encompass portable analytical systems engineered to deliver qualitative or quantitative results within minutes to hours, typically employing immunoassay chemistry with detection limits ranging from picograms to nanograms per milliliter for clinical decision-making at or near the patient site. Molecular diagnostics and immunoassays lead product category revenue, with lateral flow and biosensor technologies capturing margin pools through simplified workflows that reduce operator training requirements. Point-of-care facilities and diagnostic labs represent the primary end-user battleground, while infectious disease applications maintain structural importance despite diversification into cardiometabolic and oncology screening.
FDA premarket review pathways and WHO prequalification standards shape product development priorities and market access timelines for manufacturers targeting regulated jurisdictions. The EU In Vitro Diagnostic Regulation imposes stringent clinical evidence requirements that favor established players with dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving reimbursement frameworks for decentralized testing models and assess how CLIA-waived assay expansion reshapes competitive dynamics between centralized laboratories and distributed care networks.
Market Dynamics
Software-defined assay interpretation is compressing the traditional instrument-consumable economic model, forcing manufacturers to defend placement through digital lock-in rather than hardware differentiation.
Growth Catalysts
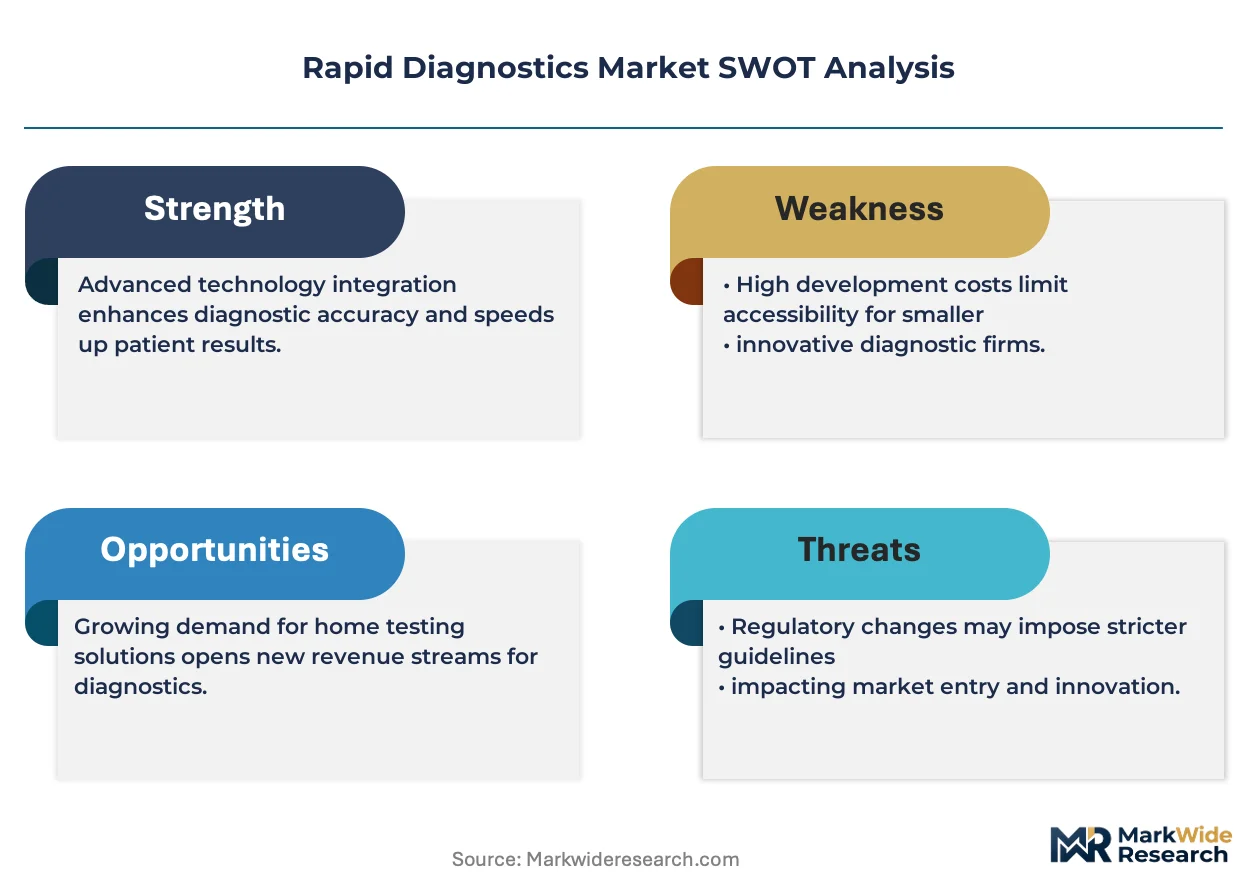
- FDA Emergency Use Authorization pathways:Compressed validation timelines for novel infectious disease assays enable faster market entry for multiplex respiratory panels during outbreak windows.
- India's National Health Mission:Decentralized testing infrastructure expansion under Ayushman Bharat drives procurement volume for CLIA-waived immunoassay systems in district hospitals.
- CRISPR-based biosensors:Isothermal amplification chemistry reduces cold-chain dependencies, opening deployment in primary care settings lacking laboratory infrastructure.
Market Restraints
- EU In Vitro Diagnostic Regulation clinical evidence requirements:Stringent post-market surveillance obligations impose documentation burdens that favor established players with dedicated regulatory affairs infrastructure.
- Nitrocellulose membrane supply concentration:Three Asian manufacturers control over 70% of raw material for lateral flow cassettes, creating input cost volatility during demand spikes.
- Optical detection component lead times:CMOS image sensor allocation constraints from consumer electronics demand extend instrument production cycles by 8-14 weeks.
Strategic Opportunities
- Sub-Saharan Africa community health worker networks:Underpenetrated rural clinics present white space for solar-powered, ambient-temperature-stable molecular platforms.
- WHO prequalification program expansion:Accelerated review timelines for HIV and malaria diagnostics create regulatory tailwind for manufacturers targeting procurement by Global Fund and PEPFAR.
- AI-assisted image interpretation:Smartphone-based result capture and machine learning classification converge to enable untrained operator use in pharmacy and retail clinic channels.
Industry Challenges
- Multiplex assay development complexity:Cross-reactivity management in respiratory panel design extends R&D timelines and increases clinical validation costs for novel target combinations.
- Interoperability with legacy LIS infrastructure:Point-of-care instruments require custom HL7 interface development for each hospital network, fragmenting deployment resources.
- CLIA-waived certification pathway navigation:FDA categorization decisions for novel chemistry formats create uncertainty in commercial launch timing and sales force training requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rapid Diagnostics Market |
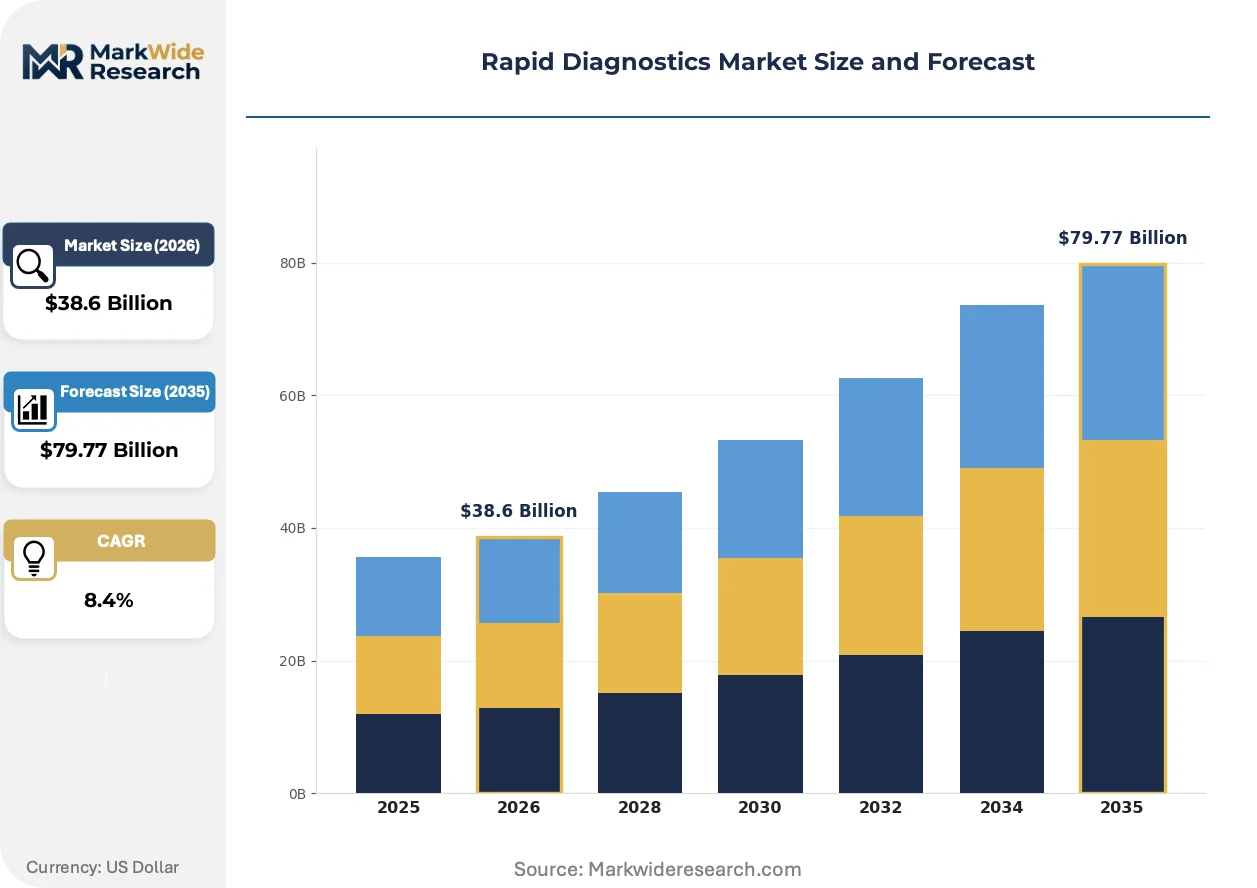
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $79.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoassays, Molecular Diagnostics, Clinical Chemistry, Hematology, Microbiology, Serology Application: Infectious Diseases, Genetic Testing, Cardiometabolic Disorders, Oncology, Drug Abuse Testing, Fertility Screening End User: Diagnostic Labs, Research Institutes, Blood Banks, Ambulatory Care Centers, Point-of-Care Facilities, Public Health Agencies Technology: PCR, ELISA, Lateral Flow Assay, Biosensors, Microfluidics, Nanotechnology |
| Companies Covered | Abbott, Roche, Danaher, Becton Dickinson and Company, Siemens Healthineers, QuidelOrtho, bioMérieux, Thermo Fisher Scientific, ACON Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rapid Diagnostics Market Strategic Shifts & Innovations
Digital connectivity and miniaturized detection hardware are collapsing the distance between sample collection and actionable result, redefining where diagnostic decisions occur.
Electrochemical biosensor arrays with printed electrode configurations are electrifying the cost structure of quantitative immunoassays. Community health centers and pharmacy chains across Southeast Asia are adopting these platforms for diabetes and cardiovascular monitoring. The technology is electrifying margin pools previously captured by centralized laboratory analyzers, compressing the addressable market for high-throughput chemistry systems in primary care settings.
REACH regulation restrictions on persistent organic pollutants in electronic components are forcing redesigns of instrument housings and printed circuit boards. Manufacturers serving European markets must substitute halogenated flame retardants with phosphorus-based alternatives, adding 12-18 months to product development cycles. In vitro diagnostic instrument lines with EU MDR certification are experiencing delayed variant launches as technical documentation undergoes notified body review.
Hospital procurement committees are unbundling instrument placement from exclusive consumable contracts, demanding competitive bidding on reagent volumes. Group purchasing organizations are consolidating diagnostic spend across health system networks, compressing supplier margins on routine panels. This pattern is most visible in United States integrated delivery networks, where centralized laboratory oversight is extending purchasing authority to point-of-care coordinators.
Rapid Diagnostics Market Segmentation
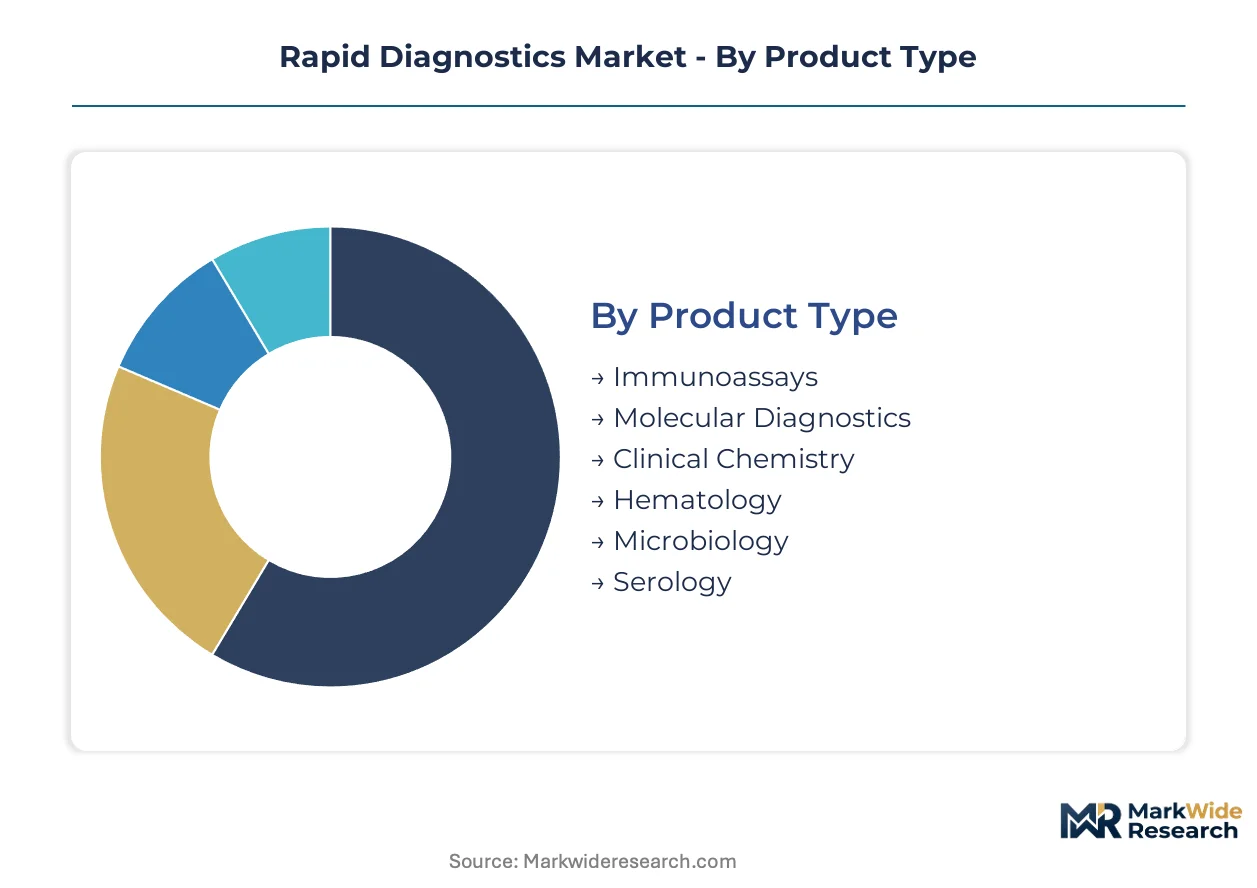
Segmentation in rapid diagnostics reveals distinct technology maturity curves and replacement dynamics. Upgrade cycles vary dramatically across chemistry platforms, with digital-enabled systems commanding shorter refresh intervals than legacy immunoassay hardware.
Product Type:
Replacement cycles accelerate where digital connectivity and cloud-based result management redefine instrument obsolescence timelines.
- Immunoassays:Lateral flow and membrane-based detection systems dominate decentralized testing infrastructure. District hospitals across India deploy these platforms under national health mission procurement, prioritizing ambient-temperature stability and minimal operator training.
- Molecular Diagnostics:Isothermal amplification and CRISPR-enabled biosensors reduce cold-chain dependencies for field deployment. Demand concentrates in primary care settings lacking laboratory infrastructure, where solar-powered platforms address electricity intermittency.
- Clinical Chemistry:Handheld analyzers for electrolyte and metabolite panels serve pharmacy clinic networks.
- Hematology:Compact cell counters support maternal health screening in rural clinics.
- Microbiology:Rapid antibiotic susceptibility testing addresses antimicrobial stewardship programs.
- Serology:Multiplex antibody detection platforms serve blood bank screening protocols.
Immunoassays sit at the top of the volume ranking, with molecular diagnostics climbing the fastest.
Application:
Cost tier stratification separates premium multiplex panels from single-target commodity assays in procurement frameworks.
- Infectious Diseases:Respiratory and sexually transmitted infection panels command the highest test frequency in point-of-care settings. FDA emergency use authorization pathways compress validation timelines for novel assay combinations during outbreak windows.
- Cardiometabolic Disorders:BNP and troponin rapid tests enable emergency department triage decisions. Ambulatory care centers across Southeast Asia adopt electrochemical biosensor arrays for diabetes monitoring, displacing centralized laboratory volumes.
- Genetic Testing:Carrier screening and pharmacogenomic assays serve specialist clinic networks.
- Oncology:Liquid biopsy platforms target community hospital oncology units.
- Drug Abuse Testing:Workplace and forensic screening panels serve occupational health providers.
- Fertility Screening:Hormone monitoring assays support obstetric clinic workflows.
Infectious diseases maintains the steepest expansion trajectory among application segments, while cardiometabolic screening gains share fastest in primary care channels.
End User:
Customer type determines interface complexity requirements and regulatory certification pathways.
- Point-of-Care Facilities:CLIA-waived instruments with smartphone connectivity serve pharmacy chains and retail clinics. AI-assisted image interpretation enables untrained operator use, collapsing the distance between sample collection and actionable result.
- Diagnostic Labs:High-throughput analyzers with proprietary chemistry systems dominate centralized workflows. Hospital procurement committees increasingly unbundle instrument placement from exclusive consumable contracts.
- Research Institutes:Custom assay development platforms support biomarker discovery programs.
- Blood Banks:Serological screening systems integrate with donor management software.
- Ambulatory Care Centers:Compact platforms serve urgent care and specialty clinic networks.
- Public Health Agencies:WHO prequalified systems target Global Fund and PEPFAR procurement.
Point-of-care facilities anchor procurement volume, with public health agencies expanding most quickly through international development financing.
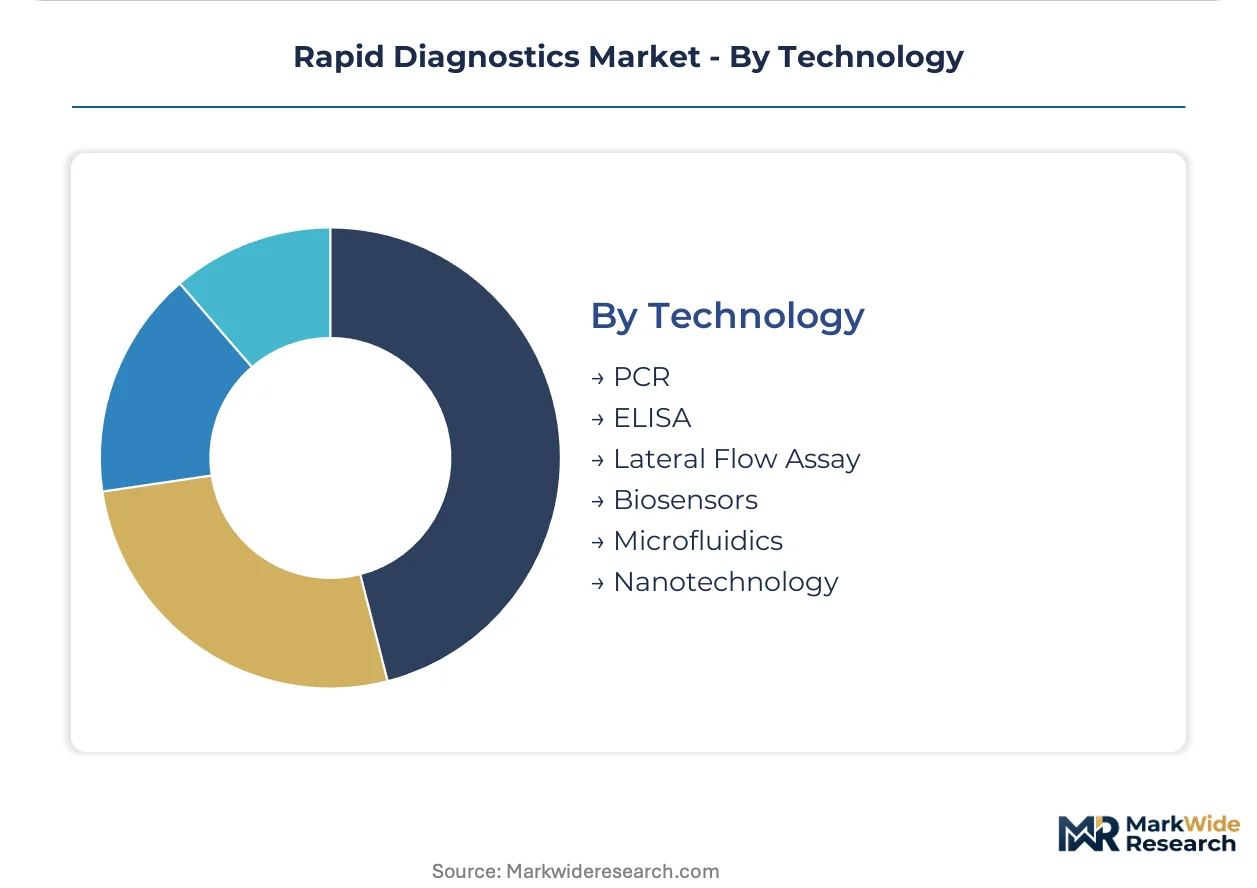
Technology:
Supply concentration in optical detection components and membrane substrates shapes platform economics.
- Lateral Flow Assay:Nitrocellulose membrane-based cassettes deliver qualitative results with minimal infrastructure requirements. Three Asian manufacturers control over 70% of raw material supply, creating input cost volatility during demand spikes.
- Biosensors:Printed electrode configurations electrify the cost structure of quantitative immunoassays. Community health centers adopt these platforms for cardiovascular monitoring, compressing margins for centralized chemistry analyzers.
- PCR:Thermocycler miniaturization enables field-deployable nucleic acid detection.
- ELISA:Microplate-based systems retain laboratory market share for batch processing.
- Microfluidics:Lab-on-chip architectures integrate sample preparation with detection.
- Nanotechnology:Quantum dot and gold nanoparticle enhancement improve detection limits.
Lateral flow assays command the largest installed base, with biosensor platforms gaining share fastest through electrochemical detection adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's decentralized testing infrastructure under Ayushman Bharat contrasts sharply with Germany's centralized laboratory networks governed by EU MDR compliance timelines. The divergence reflects fundamentally different healthcare delivery architectures and regulatory postures.
United States
Emergency departments drive troponin and BNP rapid test consumption for cardiac triage decisions. FDA emergency use authorization pathways compress validation timelines for multiplex respiratory panels during outbreak windows. The Boston-Cambridge corridor concentrates molecular diagnostics R&D facilities alongside major academic medical centers.
Germany
High-throughput laboratory analyzers dominate procurement through integrated delivery networks. EU In Vitro Diagnostic Regulation imposes stringent clinical evidence requirements that favor established players with dedicated regulatory affairs infrastructure. The Rhine-Ruhr metropolitan region anchors diagnostic instrument manufacturing clusters serving European hospital networks.
India
District hospitals expand CLIA-waived immunoassay procurement under National Health Mission decentralization mandates. CDSCO streamlined approval pathways accelerate market entry for WHO-prequalified HIV and malaria diagnostics. Karnataka's Bangalore-Tumkur corridor hosts contract manufacturing facilities supplying nitrocellulose membrane components to lateral flow cassette producers.
China
Primary care settings lacking laboratory infrastructure drive demand for solar-powered, ambient-temperature-stable molecular platforms. NMPA regulatory harmonization with international standards accelerates approval timelines for novel isothermal amplification chemistries. The Yangtze River Delta manufacturing belt concentrates electrochemical biosensor production for diabetes monitoring exports.
Brazil
Community health worker networks in underserved rural clinics present deployment opportunities for smartphone-connected result interpretation systems. ANVISA prequalification alignment with WHO standards facilitates Global Fund procurement for infectious disease screening. São Paulo state's metropolitan region concentrates diagnostic distributor networks serving the Mercosur trade bloc.
Rapid Diagnostics Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors defending placement through consumable lock-in while component suppliers capture margin pools in membrane and sensor substrates. The vendor base concentrates among diversified life sciences conglomerates with dedicated diagnostics operating companies and mid-scale specialists focused on single chemistry formats. Three strategic archetypes dominate: vertically integrated platform vendors, modular component specialists, and regional contract manufacturers serving procurement-heavy public health programs. Competitive dynamics center on M&A activity targeting complementary chemistry capabilities and strategic partnerships securing raw material supply commitments.
Within the diversified conglomerate tier, Abbott and Roche exemplify platform-centric positioning through proprietary instrument-consumable ecosystems, while Danaher occupies a position emphasizing operational excellence across multiple diagnostics operating companies. These three anchors represent contrasting defensive strategies against software-defined assay interpretation compressing traditional hardware differentiation.
| Leading Market Players |
|---|
| Abbott |
| Roche |
| Danaher |
| Becton Dickinson and Company |
| Siemens Healthineers |
| QuidelOrtho |
| bioMérieux |
| Thermo Fisher Scientific |
| ACON Laboratories |
| Others |
Cost & Logistics Intelligence
Electrochemical biosensor miniaturization is collapsing the cost economics of quantitative immunoassays while simultaneously concentrating production expertise in the Yangtze River Delta manufacturing belt. This technology transition rewards manufacturers with captive electrode printing capabilities and squeezes margin pools for instrument vendors dependent on outsourced optical detection modules.
Pricing Analysis
Capacity additions in China's electrochemical sensor foundries are reshaping price floors for handheld analyzers across Southeast Asian pharmacy networks. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared CLIA-waived systems from CE-marked professional-use instruments and uncertified consumer-grade devices. Cost compression in the economy tier intensifies because nitrocellulose membrane supply volatility forces contract manufacturers to absorb input spikes. Public health procurement committees exhibit highest price sensitivity, while emergency department purchasing authorities prioritize turnaround time over per-test economics.
Supply Chain Analysis
Direct-to-hospital channels handle high-volume analyzer placements for integrated delivery networks, while distributor networks serve clinic and pharmacy procurement. Nitrocellulose membrane production concentrates in China, India, and Japan, with CMOS image sensor fabrication anchored in Taiwan and South Korea. Raw material dependencies include nitrocellulose substrates, printed electrode inks, and fluorescence detection reagents. Single-source vulnerability in CMOS sensor allocation from consumer electronics demand creates production cycle extensions. Distribution runs through regional diagnostic distributors with cold-chain capabilities for reagent logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rapid diagnostics has entered late-cycle quality phase where instrument reliability and assay accuracy specifications dominate procurement scoring. Demand is shifting toward multiplex respiratory panels with software-defined result interpretation as buyers prioritize platform extensibility over hardware acquisition cost.
For Market Incumbents: Deploy consumable lock-in through cloud-based assay management platforms to defend placement against emerging CRISPR-based biosensor entrants. Strengthen backward integration into nitrocellulose membrane production to insulate margin structures from Asian supplier concentration. Channel control through exclusive distributor agreements represents the critical defensive lever against unbundling pressures from group purchasing organizations. For New Entrants and Emerging Players: Pharmacy chain partnerships in Brazil and Southeast Asia offer lowest barrier-to-entry channels for smartphone-connected immunoassay readers. Sub-Saharan Africa's community health worker networks present the most penetrable white space for solar-powered molecular platforms lacking laboratory infrastructure. Go-to-market positioning should emphasize ambient-temperature stability and minimal operator training requirements to differentiate from incumbent cold-chain-dependent systems. For Investors and Strategic Acquirers: Valuations sit cheapest among contract manufacturers with WHO prequalification capabilities and membrane substrate production expertise. Long-term viability over the next decade hinges on regulatory harmonization accelerating market access for decentralized testing platforms. Acquisition targets should display proprietary isothermal amplification chemistry or printed biosensor electrode IP. The signal to watch is FDA categorization decisions for AI-assisted image interpretation systems as inflection indicator for software-enabled platform economics.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance accelerates market access for lateral flow manufacturers targeting European hospital procurement. |
| Hospital System Partnership | Integrated delivery network contracts unbundle instrument placement from consumable exclusivity, reshaping vendor economics. |
| Software Companion Development | AI-assisted image interpretation enables CLIA-waived certification for untrained operator use in retail clinic channels. |
| Reimbursement Strategy | CMS coverage determinations for decentralized testing models determine addressable market expansion in United States ambulatory settings. |
| Backward Integration | In-house nitrocellulose membrane production insulates margin structures from Asian supplier concentration and demand spike volatility. |
Research Approach
Multiple input streams — regulatory filing analysis, procurement database mining, and manufacturing capacity tracking — were reconciled to construct market estimates. Primary interviews with diagnostic instrument product managers, hospital purchasing committee members, biomedical engineers at point-of-care facilities, and group purchasing organization contract specialists informed demand-side assumptions. Secondary validation drew from FDA 510(k) and EUA submission databases, WHO prequalification listings, CMS reimbursement determinations, and import-export trade records. Bottom-up instrument placement estimates and top-down healthcare expenditure allocations were triangulated to resolve segmentation splits.
Data-stream reconciliation across chemistry platform adoption curves, end-user procurement patterns, and geographic regulatory timelines anchored the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, application, end-user facility class, technology platform, and regional regulatory cluster. CAGRs were derived from instrument replacement cycle analysis and consumable pull-through rates. Forecast inputs incorporated CLIA-waived assay expansion trajectories and decentralized testing infrastructure buildout under national health mission programs.
Revisions become necessary when FDA categorization decisions for novel chemistry formats, EU MDR notified body capacity constraints, or nitrocellulose membrane supply disruptions materialize. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and procurement decentralization rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Viral Molecular Diagnostics Market
Diagnostics
Inflammatory Markers Market
Diagnostics
Connected Diagnostics Market
Diagnostics
Global Immunoassay Market
Diagnostics
Population Screening Market
Diagnostics
Global Antinuclear Antibody Test Market
Diagnostics
Extraction Kits Market
Diagnostics
Chlamydia Diagnostics Market
Diagnostics
Global Companion Diagnostic Technologies Market
Diagnostics
Thyroid Cancer Diagnostics Market
Diagnostics
Fertility Test Market
Diagnostics
Global Hemoglobin A1c Testing Devices Market
Diagnostics
Adenovirus Diagnostic Testing Market
Diagnostics
Brain Cancer Diagnostics Market
Diagnostics
DNA and RNA Probes Market
Diagnostics
Global RSV Diagnostics Market