
 Global Rapid Diagnostic Kits Market | 2026-2036
Global Rapid Diagnostic Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rapid Diagnostic Kits Market Foresight
Market Context
India is reshaping manufacturing capacity for rapid diagnostic kits through government-backed pharmaceutical clusters and contract research expansion. Abbott Laboratories leverages integrated supply chains spanning reagent production to distribution networks across emerging markets. F. Hoffmann-La Roche AG sustains premium positioning through fluorescence-based immunoassay platforms that dominate hospital laboratory procurement. Siemens Healthineers anchors European demand with automated point-of-care systems that reduce technician training requirements.
Technical Definition and Segment Structure
Rapid diagnostic kits are self-contained analytical systems that detect target analytes in biological specimens within minutes through immunochemical, nucleic acid amplification, or biosensor-mediated reactions, typically requiring no specialized laboratory infrastructure. Lateral flow assays command the largest volume share due to minimal operator skill requirements and stability without cold chain storage. Immunoassay platforms capture disproportionate margin pools in cardiac marker and hormone monitoring applications where quantitative precision commands premium pricing. Microfluidic devices represent the fastest-expanding technology segment as manufacturers integrate multiplexing capabilities for simultaneous pathogen detection.
Regulatory Framework and Outlook
FDA 510(k) clearance pathways and EMA CE marking under the In Vitro Diagnostic Medical Devices Regulation govern market access timelines and clinical evidence requirements for rapid diagnostic kits. India's CDSCO and China's NMPA impose additional localization mandates that shape manufacturing location decisions and partnership strategies for multinational suppliers. Stakeholders must monitor evolving WHO prequalification standards and national essential diagnostics list expansions that determine reimbursement eligibility and procurement volume in public health programs.
Market Dynamics
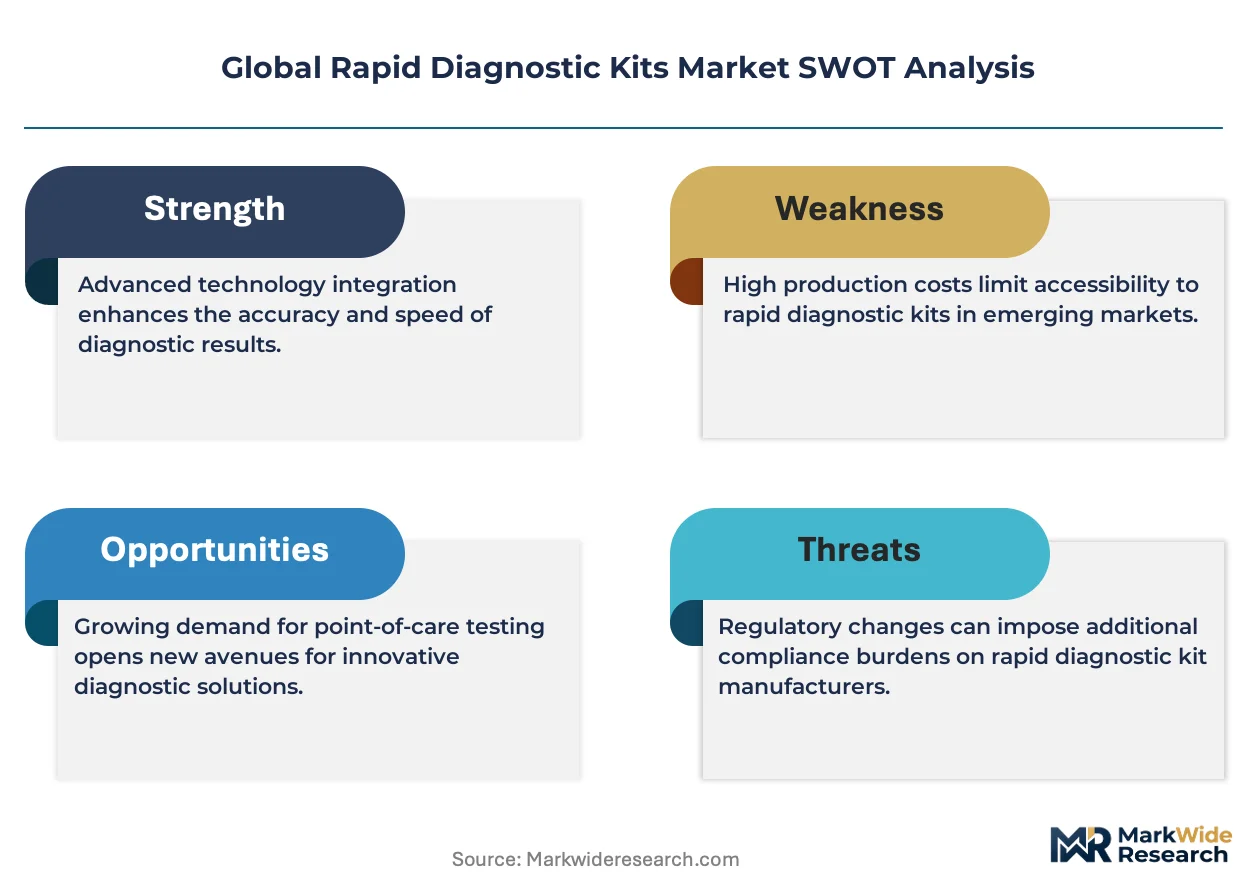
Decentralized healthcare infrastructure is compressing the traditional laboratory-to-patient testing pathway, forcing manufacturers to engineer devices that deliver clinical-grade accuracy without trained technicians or climate-controlled storage. This structural pull is redrawing competitive boundaries between point-of-care specialists and centralized diagnostics incumbents.
Growth Catalysts
- CLIA-waived FDA pathways:Simplified premarket clearance for waived-complexity devices accelerates commercialization timelines for infectious disease assays in US retail clinics and pharmacies.
- Point-of-care cardiac markers:Emergency departments and ambulance services demand quantitative troponin results within fifteen minutes, expanding the addressable base beyond traditional laboratory customers.
- India's pharmaceutical clusters:Government-backed manufacturing zones in Hyderabad and Ahmedabad reduce export logistics costs for reagent production serving Southeast Asian and African procurement programs.
Market Restraints
- Nitrocellulose membrane supply:Concentration of raw material production in Chinese chemical processing hubs exposes manufacturers to input volatility and trade policy friction.
- Cold chain-dependent molecular assays:Nucleic acid amplification platforms require refrigerated transport and storage, limiting deployment in tropical climates with unreliable electricity infrastructure.
- EMA MDR transition costs:Stricter clinical evidence requirements for CE marking under the In Vitro Diagnostic Medical Devices Regulation extend certification timelines and inflate documentation expenses for mid-tier suppliers.
Strategic Opportunities
- Sub-Saharan Africa essential diagnostics lists:WHO prequalification alignment with national procurement frameworks creates first-mover advantage for multiplex fever-panel manufacturers in Nigeria, Kenya, and Ethiopia.
- At-home fertility hormone monitoring:Consumer-directed quantitative LH and progesterone testing bypasses clinic-based workflows, opening direct-to-consumer channels previously inaccessible to clinical diagnostics vendors.
- Microfluidic-biosensor convergence:Integration of smartphone-readable electrochemical sensors with paper-based microfluidics enables connectivity for remote result transmission in telemedicine workflows.
Industry Challenges
- Multiplex assay validation:Cross-reactivity testing for simultaneous pathogen detection demands extended clinical studies and specialized biostatistical expertise that strains mid-sized R&D organizations.
- Legacy laboratory information system integration:Point-of-care devices must interface with hospital electronic health records through HL7 or FHIR protocols, requiring software engineering capabilities outside traditional hardware competencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rapid Diagnostic Kits Market |
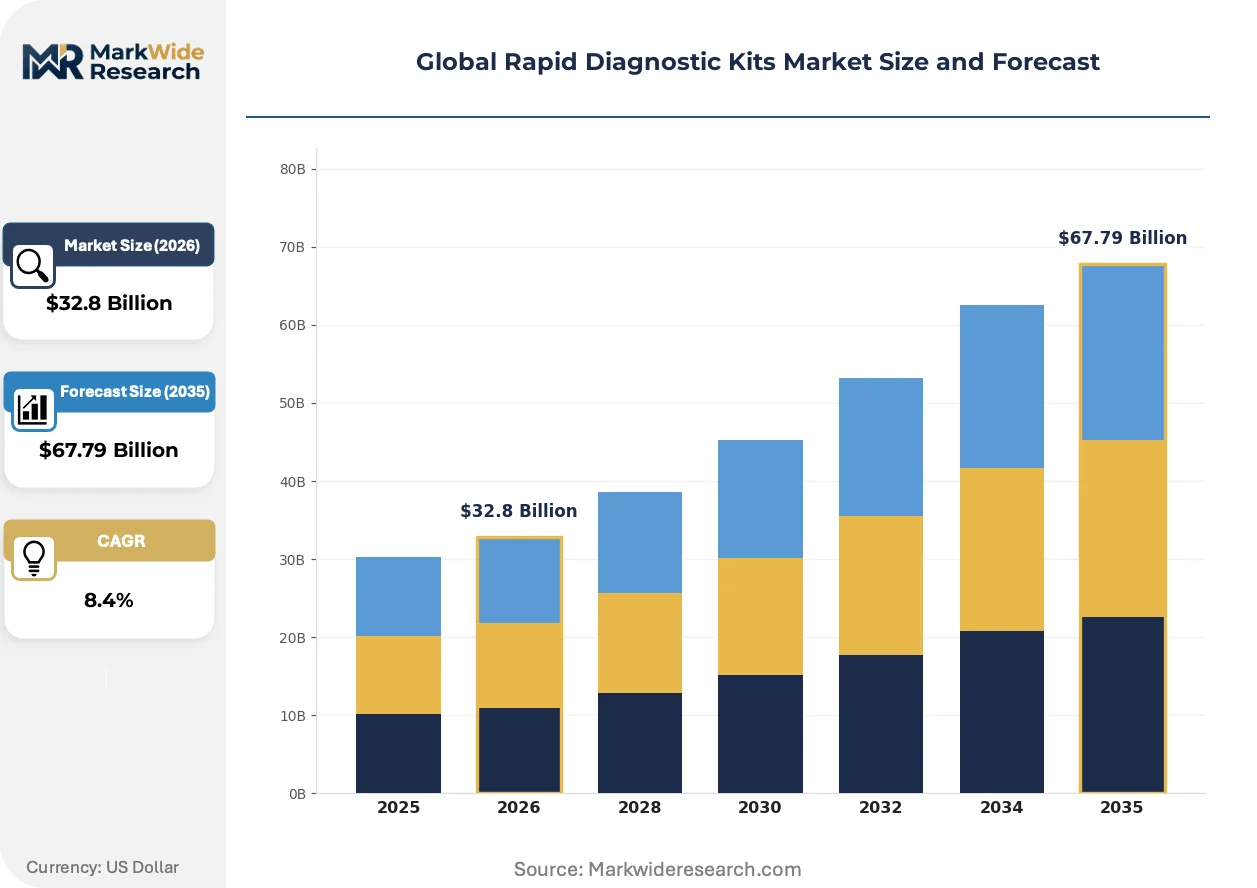
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $67.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lateral Flow Assays, Immunoassays, PCR Kits, Microfluidic Devices, Biosensors Application: Infectious Disease Detection, Cancer Screening, Cardiac Marker Analysis, Drug Abuse Testing, Hormone Monitoring End User: Clinical Laboratories, Point of Care Centers, Diagnostic Imaging Facilities, Research Institutes, Veterinary Clinics Technology: Fluorescence, Chemiluminescence, Electrochemical, Colorimetric, Magnetic Immunoassay |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche AG, Siemens Healthineers, Danaher Corporation, bioMérieux SA, Becton Dickinson, ACON Laboratories Inc., Meridian Bioscience Inc., Trinity Biotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rapid Diagnostic Kits Market Shifts & Advancements
Connectivity and quantitative readout capabilities are transforming rapid diagnostics from binary screening tools into data-generating nodes within integrated care pathways. This evolution is compressing the functional gap between decentralized testing and centralized laboratory precision.
Fluorescence-based lateral flow systems are migrating from hospital laboratory overflow settings into retail pharmacy clinics and employer health screening programs. These platforms deliver quantitative analyte concentrations previously requiring benchtop analyzers. Pharmacy chains in Germany and the United States deploy staff-operated devices for HbA1c and lipid panel screening. The technology is migrating from laboratory-centric business models toward subscription-based service contracts that bundle consumables, connectivity, and result interpretation.
EMA's In Vitro Diagnostic Medical Devices Regulation imposes post-market surveillance and clinical performance tracking obligations that exceed predecessor directive requirements. Manufacturers must maintain technical documentation and vigilance systems for device lifecycle duration. High-risk infectious disease assays face notified body scrutiny that delays market entry by twelve to eighteen months relative to pre-2022 timelines. European hospital procurement committees increasingly demand MDR compliance certification as a mandatory evaluation criterion.
Hospital pharmacy and materials management departments consolidate supplier relationships through single-source or dual-source frameworks that bundle rapid diagnostics with broader laboratory consumables contracts. Group purchasing organizations in the United States aggregate demand across health system networks, compressing vendor margins in exchange for volume commitments. This consolidation favors suppliers with diversified reagent portfolios spanning chemistry, immunoassay, and molecular platforms. Academic medical centers in Boston and the Research Triangle demonstrate earliest adoption of these consolidated procurement structures.
Global Rapid Diagnostic Kits Market Segmentation
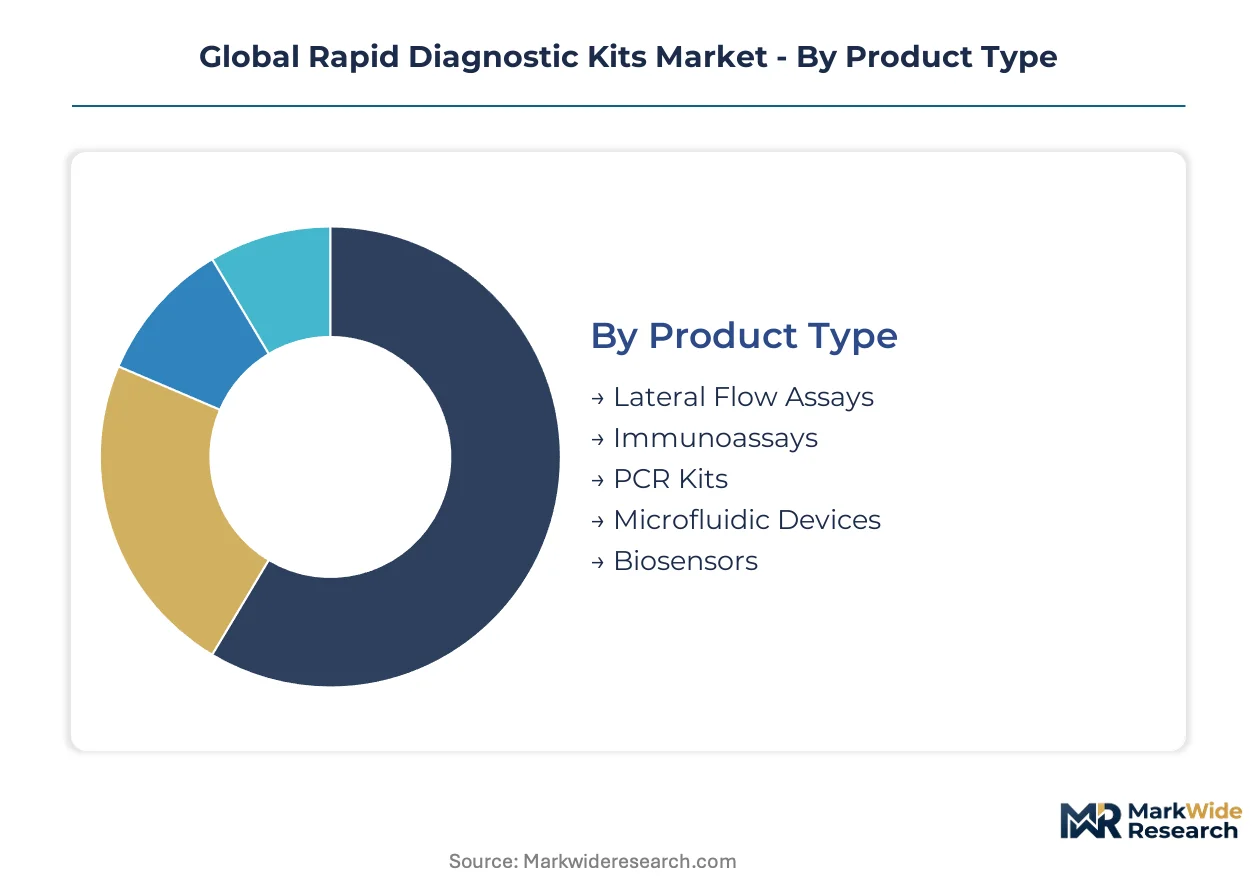
Rapid diagnostic kits fragment across technical platforms, clinical applications, and deployment settings that each impose distinct performance requirements and commercial timelines. Manufacturers must align R&D priorities with the cycle-time dynamics of specific segments—some turning over in months, others locked into multi-year procurement contracts.
Product Type:
Lateral flow assays turn inventory fastest through pharmacy and retail clinic channels, while microfluidic devices face extended validation cycles in hospital system evaluations. PCR kits and biosensors occupy intermediate positions shaped by regulatory pathway complexity.
- Lateral Flow Assays:Nitrocellulose membrane-based immunochromatographic strips deliver qualitative or semi-quantitative results within 15 minutes without cold chain requirements. Demand concentrates in Indian and Nigerian public health programs for malaria, HIV, and tuberculosis screening where field deployment dominates procurement specifications.
- Immunoassays:Enzyme-linked and fluorescence-based platforms achieve quantitative precision for cardiac troponin and hormone panels previously requiring central laboratory processing. German hospital emergency departments and US ambulance services drive replacement of legacy benchtop analyzers with cartridge-based systems.
- PCR Kits:Isothermal and traditional thermal-cycling nucleic acid amplification platforms enable pathogen identification at moderate complexity CLIA settings.
- Microfluidic Devices:Lab-on-chip architectures integrate sample preparation, reaction, and detection in disposable cartridges.
- Biosensors:Electrochemical and optical transducer systems enable continuous or frequent monitoring applications.
Lateral flow assays dominate installed base. Microfluidic devices are where expansion concentrates.
Application:
Margin profiles diverge sharply across clinical applications—infectious disease panels compete on volume and unit economics, while cardiac and cancer assays command pricing premia through clinical outcome differentiation.
- Infectious Disease Detection:Multiplex respiratory, fever, and sexually transmitted infection panels integrate sample-to-answer workflows for decentralized settings. Procurement through WHO prequalification and national essential diagnostics lists in Ethiopia, Kenya, and Bangladesh shapes supplier qualification requirements and volume forecasting.
- Cardiac Marker Analysis:Quantitative troponin, BNP, and D-dimer testing within 15 minutes enables emergency department triage and chest pain protocol compliance. US hospital accreditation standards and German ambulance service specifications drive performance benchmarking against central laboratory reference methods.
- Cancer Screening:Fecal occult blood, PSA, and emerging circulating tumor marker assays target asymptomatic population screening.
- Drug Abuse Testing:Workplace, forensic, and clinical toxicology panels detect amphetamines, opioids, and synthetic cannabinoids.
- Hormone Monitoring:Fertility, thyroid, and cortisol assays serve both clinical diagnostic and direct-to-consumer wellness segments.
Infectious disease detection anchors procurement volume. Cardiac marker analysis captures the steepest expansion trajectory.
End User:
Customer technical sophistication and purchasing authority create tiered access requirements—point-of-care sites demand simplicity and connectivity, while research institutes prioritize customization and data export flexibility.
- Point of Care Centers:Retail clinics, pharmacy health stations, and employer screening programs require waived-complexity devices with minimal training burden. CLIA-waived FDA clearances and German pharmacy operator licensing frameworks determine product eligibility for this fastest-expanding deployment channel.
- Clinical Laboratories:Hospital central labs and reference laboratories integrate rapid diagnostics as overflow capacity or stat testing alternatives. US health system consolidation through group purchasing organizations and German hospital federation procurement standardizes vendor qualification criteria.
- Diagnostic Imaging Facilities:Radiology and cardiology suites deploy companion diagnostics for procedural risk stratification.
- Research Institutes:Academic and contract research organizations utilize investigational devices and custom assay development services.
- Veterinary Clinics:Companion and livestock diagnostic applications adapt human-platform technologies with species-specific reagent formulations.
Clinical laboratories retain the largest installed base. Point of care centers are gaining share fastest.
Technology:
Detection modality selection trades off sensitivity, instrumentation cost, and result format—fluorescence and chemiluminescence penetrate premium quantitative segments, while colorimetric platforms sustain high-volume screening economics.
- Fluorescence:Time-resolved and fluorescence polarization methods achieve picomolar detection limits for cardiac troponin and infectious disease antigen quantification. EMA MDR technical documentation requirements and FDA 510(k) substantial equivalence benchmarks extend development timelines relative to qualitative alternatives.
- Chemiluminescence:Acridinium ester and alkaline phosphatase conjugate systems deliver wide dynamic range for hormone and tumor marker panels. Automated platform placement in US hospital laboratories and Indian corporate hospital chains generates recurring reagent revenue streams.
- Electrochemical:Amperometric and potentiometric biosensors enable smartphone-integrated readout for remote monitoring applications.
- Colorimetric:Enzyme substrate and gold nanoparticle visual detection sustains lowest-cost manufacturing for high-volume infectious disease screening.
- Magnetic Immunoassay:Superparamagnetic bead separation enhances assay kinetics and reduces matrix interference in complex specimens.
Colorimetric platforms dominate unit volume. Fluorescence technology is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European distribution for nitrocellulose membrane imports serving reagent manufacturing clusters. India's Pharmaceutical Export Promotion Council leverages Mundra Port container terminals for cold-chain shipments to Sub-Saharan African procurement programs.
United States
CVS MinuteClinic and Walgreens Health expansion drives CLIA-waived device placement in 15,000 retail health locations. FDA 510(k) clearance timelines compress to 90 days for waived infectious disease assays under pilot programs. Boston's Research Triangle medical device corridor concentrates connectivity-enabled biosensor development for telemedicine integration.
Germany
Pharmacy operator licensing frameworks mandate training certification for staff-operated HbA1c and lipid screening devices. EMA MDR notified body scrutiny extends infectious disease assay certification by 12-18 months. Baden-Württemberg's Stuttgart-Tübingen medtech cluster automates point-of-care system production for European hospital federation procurement.
India
Hyderabad and Ahmedabad pharmaceutical zones reduce export logistics costs for malaria and tuberculosis test kit production serving WHO prequalification programs. CDSCO manufacturing license mandates require local stability testing facilities for import substitution. Gujarat's Special Economic Zone infrastructure anchors contract research expansion for Southeast Asian diagnostic procurement.
China
NMPA Class III registration requirements for nucleic acid amplification platforms demand domestic clinical trial data. Yangtze River Delta chemical processing hubs concentrate nitrocellulose membrane supply for global lateral flow assay manufacturers. Shanghai's Zhangjiang Hi-Tech Park integrates microfluidic cartridge production with automated assembly lines.
Brazil
ANVISA import licensing delays for IVD reagents push manufacturers toward local assembly partnerships. SUS national procurement frameworks prioritize WHO prequalification alignment for HIV and syphilis screening programs. São Paulo's Campinas biotech corridor develops regional distribution hubs for Andean market access.
Global Rapid Diagnostic Kits Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in membrane chemistry and conjugate production. The vendor base stratifies across multinational conglomerates with diversified reagent portfolios, mid-tier regional suppliers, and single-technology niche players. Three archetypes dominate: fluorescence platform incumbents, lateral flow contract manufacturers, and microfluidic technology licensors. Competitive moves concentrate on M&A for multiplex assay capabilities and strategic partnerships for EMA MDR compliance outsourcing.
Among diversified diagnostics conglomerates, Abbott Laboratories, F. Hoffmann-La Roche AG, and Siemens Healthineers occupy positions exemplifying platform integration archetypes. These entities represent the system-tier configuration where automated analyzer placement generates recurring consumable revenue. Their geographic footprints span FDA-cleared US hospital networks, EMA MDR-compliant European installations, and CDSCO-registered Indian manufacturing. The competitive dynamic between these anchors and mid-tier specialists is reshaping procurement consolidation through group purchasing organization aggregation.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche AG |
| Siemens Healthineers |
| Danaher Corporation |
| bioMérieux SA |
| Becton Dickinson |
| ACON Laboratories Inc. |
| Meridian Bioscience Inc. |
| Trinity Biotech |
| Others |
Supply & Pricing Matrix
The Port of Hamburg's container throughput costs for nitrocellulose membrane imports from Chinese chemical processing hubs directly compress margin pools for lateral flow assay manufacturers while enabling fluorescence platform vendors to sustain premium positioning through captive reagent production and bundled service contracts.
Pricing Analysis
Volume-discount tiering separates CLIA-waived retail clinic placements from hospital laboratory analyzer contracts with premium-mid-economy pricing differentiation across infectious disease, cardiac marker, and hormone monitoring applications. Price differentiation hinges on FDA certification tier and geographic delivery infrastructure, with cold chain-dependent molecular assays facing downward pressure from ambient-stable lateral flow alternatives. Group purchasing organizations in the United States exhibit highest price sensitivity, while German hospital federations prioritize EMA MDR compliance over unit cost.
Supply Chain Analysis
Upstream feedstock concentration in Chinese nitrocellulose membrane production, Indian antibody conjugate manufacturing, and German precision optical component fabrication creates multi-node dependency for integrated platform vendors. Raw material flows draw from Yangtze River Delta chemical processing, Hyderabad pharmaceutical zones, and Stuttgart-Tübingen medtech clusters. Single-source vulnerability in nitrocellulose supply exposes manufacturers to tariff friction and logistics chokepoint risk. Distribution runs through Port of Hamburg for European hospital procurement and Mundra Port container terminals for WHO prequalification programs serving Sub-Saharan Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Point-of-care deployment expansion fragments procurement authority across retail pharmacy chains, employer health programs, and telemedicine platforms, creating specialized niches for connectivity-enabled biosensor specialists and multiplex assay developers.
For Market Incumbents: Entrench fluorescence platform positions through backward integration into nitrocellulose membrane chemistry and CDSCO-registered manufacturing in Hyderabad pharmaceutical zones. Acquire microfluidic technology licensors to neutralize emerging entrant threats in smartphone-integrated electrochemical sensing. Prioritize EMA MDR compliance outsourcing partnerships to compress certification timelines against mid-tier specialists. For New Entrants and Emerging Players: Establish a beachhead in at-home fertility hormone monitoring through direct-to-consumer channels bypassing clinic-based procurement workflows. Target Sub-Saharan Africa essential diagnostics list procurement in Nigeria, Kenya, and Ethiopia with WHO prequalification-aligned multiplex fever panels. Pursue microfluidic-biosensor convergence platforms with smartphone-readable electrochemical sensors as the primary go-to-market angle. For Investors and Strategic Acquirers: Multiplex assay validation specialists with extended clinical study capabilities and specialized biostatistical expertise represent the most defensible acquisition archetype across a five-to-ten year viability window. Monitor WHO prequalification standard expansions and national essential diagnostics list adoptions as inflection indicators for procurement volume shifts in public health programs.| Strategic Initiative | Industry Significance |
|---|---|
| EMA MDR Compliance Outsourcing | Reduces certification delays for infectious disease assays entering European hospital procurement frameworks. |
| Microfluidic Technology Licensing | Enables smartphone-integrated electrochemical sensing for remote telemedicine result transmission workflows. |
| WHO Prequalification Alignment | Unlocks national procurement volume in Ethiopia, Kenya, and Bangladesh essential diagnostics programs. |
| CLIA-Waived FDA Pathway Investment | Accelerates commercialization timelines for retail pharmacy and employer health screening placements. |
| Group Purchasing Organization Consolidation | Aggregates demand across US health system networks in exchange for volume commitment contracts. |
Research Methodology
The analysis maps lateral flow assay, immunoassay, PCR kit, microfluidic device, and biosensor sub-sectors, each validated through procurement managers at group purchasing organizations, regulatory affairs leads at multinational diagnostics conglomerates, biomedical engineers at hospital systems, and GPO contracts managers. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EMA MDR technical documentation, WHO prequalification databases, and hospital procurement contracts. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume and value estimates.
Assumption sets held regulatory pathway timelines and CLIA-waiver expansion rates fixed while varying infectious disease outbreak frequency, telemedicine adoption curves, and group purchasing organization consolidation pace across the projection horizon. Segmentation dimensions modeled include product platform, clinical application, end-user deployment setting, detection technology modality, and regional regulatory cluster. CAGRs derived from installed base turnover rates and replacement demand curves, with nucleic acid amplification platform cold chain infrastructure penetration and fluorescence-based lateral flow migration from laboratory to retail settings as key forecast inputs.
Sensitivities concentrate around nitrocellulose membrane supply disruptions, EMA MDR notified body capacity constraints, and WHO prequalification standard revisions for multiplex fever panels. Forecasts reflect these documented assumptions with acknowledged revision risk from trade policy friction, regulatory timeline extensions, and public health procurement budget reallocations. Cross-checking against CMS Medicare laboratory fee schedule benchmarks and European hospital federation procurement contract databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Fungal Antigens Market
Diagnostics
Global Immunoprotein Diagnostic Testing Market
Diagnostics
Immunodiagnostics Market
Diagnostics
Total Iron Binding Capacity Reagents Market
Diagnostics
Middle East and Africa HIV Diagnosis and Treatment Market
Diagnostics
Canada Latent Tuberculosis Infection Detection Market
Diagnostics
Global Neurodiagnostics Market
Diagnostics
Europe Blood Screening Market
Diagnostics
Global Autoimmune Disease Diagnostics Market
Diagnostics
Immunoassay Interference Blocker Market
Diagnostics
Global Tissue Diagnostics Market
Diagnostics
Middle East and Africa Liver Cancer Diagnostics Market
Diagnostics
Swine Disease Diagnostic Kit Market
Diagnostics
Digital Companion Diagnostics Market
Diagnostics
Mexico in-Vitro Diagnostics Market
Diagnostics
Global Paper Diagnostics Market