
 Asia-Pacific Flow Cytometry Market | 2026-2036
Asia-Pacific Flow Cytometry Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Flow Cytometry Market Insights
Market Context
End-use demand is shifting toward pharmaceutical firms as biologics pipelines across China and India multiply. Becton, Dickinson and Company leverages its instrument-reagent bundling to anchor hospital laboratories across Japan and Australia. Sysmex Corporation dominates hematology-adjacent flow cytometry through deep channel control in domestic Japanese diagnostics. Cytek Biosciences differentiates via spectral flow technology leadership that extends its footprint into Singaporean research institutes.
Technical Definition and Segment Structure
Flow cytometry is a laser- or impedance-based technique that quantifies physical and chemical characteristics of particles or cells suspended in fluid, typically analyzing 10,000 to 50,000 cells per second for parameters including size, granularity, and fluorescence intensity. Its primary purpose spans clinical diagnostics, drug discovery, and basic research where multiparametric single-cell analysis replaces bulk population assays. Instruments command the largest value share due to capital intensity and service attachment, while reagents generate recurring revenue streams that sustain margin pools across installed bases. Cancer Research applications are expanding fastest as Asia-Pacific immuno-oncology trials multiply, whereas academic institutes remain the volume anchor through government-funded life sciences programs.
Regulatory Framework
Japan's PMDA and China's NMPA enforce divergent instrument registration pathways that fragment product launch timelines across the region. India's CDSCO medical device rules and Australia's TGA conformity assessments add compliance layers for reagent kits and software modules. REACH-aligned chemical standards in South Korea and Taiwan restrict certain fluorophore formulations, pushing vendors toward reformulation investments. Stakeholders must monitor regulatory harmonization talks between ASEAN member states to anticipate whether unified device approval frameworks emerge or national divergence persists.
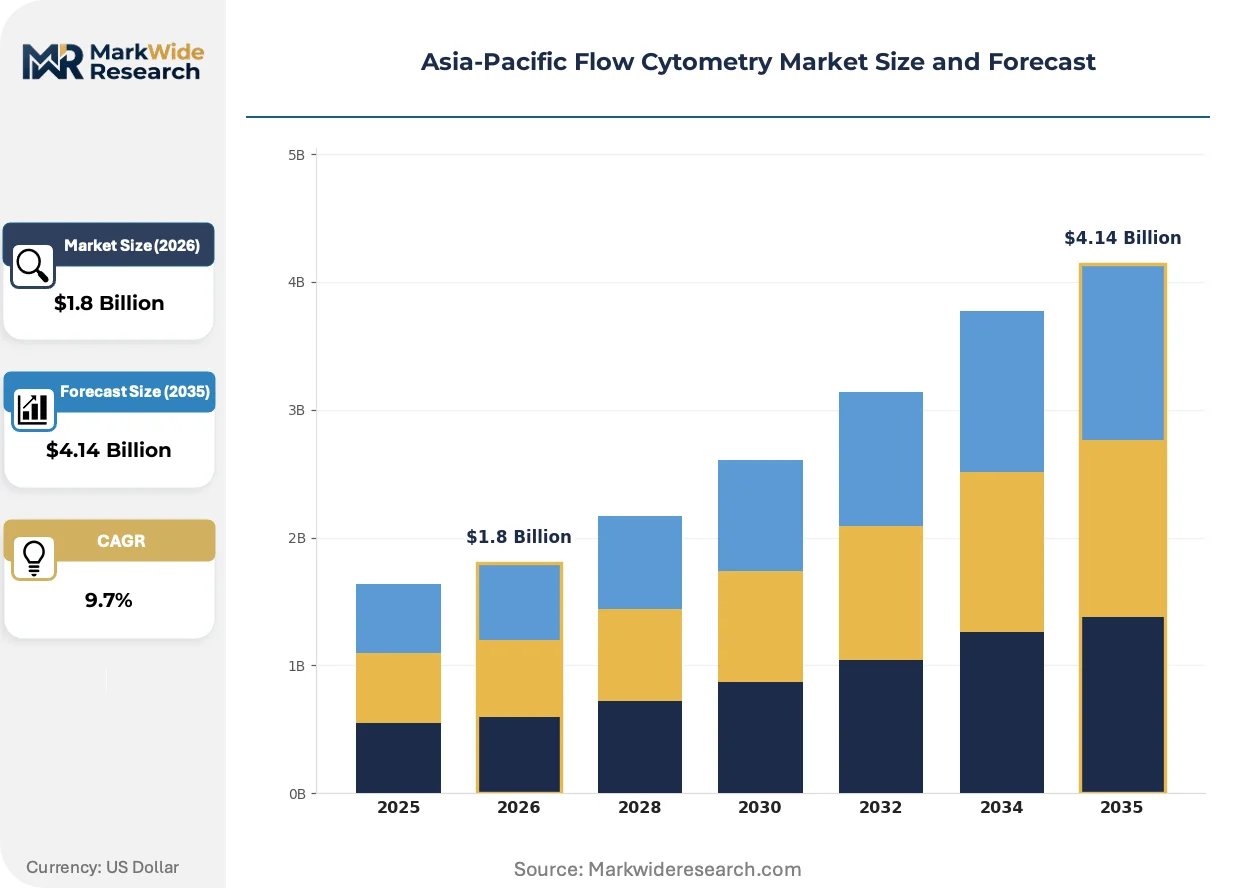
Market Dynamics
Spectral flow cytometry architectures are compressing traditional PMT-based instrument margins across Asia-Pacific research institutes, forcing vendors to accelerate service-revenue attachment or exit the hardware tier entirely.
Growth Catalysts
- Biologics pipeline expansion:Pharmaceutical firms in China and India are scaling analytical capabilities to support monoclonal antibody and cell therapy development, creating sustained instrument demand.
- CDSCO quality rule tightening:India's medical device import standards are elevating compliance barriers for low-tier instruments, advantaging certified vendors with established local service infrastructure.
- Fluorophore reformulation mandates:REACH-aligned chemical standards in South Korea and Taiwan are pushing reagent manufacturers toward next-generation dye platforms with superior photostability.
Market Restraints
- Laser source cost volatility:Solid-state laser components face supply concentration in Japanese and German specialty optics suppliers, exposing instrument margins to input price swings.
- NMPA-PMDA registration divergence:China's National Medical Products Administration and Japan's Pharmaceuticals and Medical Devices Agency maintain incompatible clinical data requirements, fragmenting product launch timelines and inflating regulatory overhead.
- Mass cytometry substitution threat:Metal-tag-based single-cell analysis is capturing high-parameter research applications above 30 colors, compressing addressable market for conventional fluorescence systems.
Strategic Opportunities
- Vietnamese research infrastructure:Government-funded life sciences campuses in Hanoi and Ho Chi Minh City remain underpenetrated by spectral flow vendors, offering first-mover positioning ahead of ASEAN harmonization.
- Cell therapy QC integration:Automated flow cytometry systems are converging with closed-cell processing platforms, enabling point-of-release potency testing for CAR-T manufacturing suites.
- ASEAN device approval convergence:Ongoing regulatory harmonization talks between member states could collapse multi-country registration into unified pathways, reducing compliance cost burdens for reagent kit suppliers.
Industry Challenges
- Spectral compensation expertise gap:Unmixing algorithm operation requires computational biology skill sets scarce in hospital laboratory workforces across tier-2 Chinese cities.
- Legacy LIS integration friction:Newer instruments face interoperability failures with established laboratory information systems in Australian public health networks, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Flow Cytometry Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Accessories Application: Cell Biology, Immunology, Hematology, Cancer Research End User: Academic Institutes, Biotechnology Companies, Pharmaceutical Firms, Hospitals Technology: Laser-based, Microfluidics, Imaging, Mass Cytometry |
| Companies Covered | Becton, Dickinson and Company, Beckman Coulter, Thermo Fisher Scientific, Agilent Technologies, Bio-Rad Laboratories, Sysmex Corporation, Miltenyi Biotec, Sony Biotechnology, Cytek Biosciences, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Flow Cytometry Market Trends and Innovations
Spectral detection architectures are actively compressing the traditional filter-based instrument tier across Asia-Pacific research markets, with downstream consequences for vendor service models and reattach rates.
Spectral flow cytometry replaces discrete optical filters with full-spectrum capture across continuous wavelength ranges, enabling simultaneous measurement of 40-plus fluorochromes without compensation matrix complexity. Cancer immunology research groups in Singaporean institutes and Shanghai biotech clusters are adopting these systems at replacement-cycle pace, bypassing incremental upgrades to conventional platforms. This capability expansion is overtaking the parameter ceiling that previously constrained high-dimensional immunophenotyping experiments.
China's NMPA implemented revised medical device classification rules in 2021 that reclassify certain flow cytometry instruments from Class II to Class III, mandating clinical trial submissions for registration renewals. The industrial consequence is extended approval timelines and elevated documentation burdens for multinational vendors seeking to refresh product lines. Hematology-adjacent diagnostic systems face the most acute compliance pressure, with several manufacturers accelerating local manufacturing partnerships to qualify for streamlined domestic-device pathways.
Academic procurement committees across Japan and Australia are unbundling instrument purchases from mandatory multi-year reagent supply agreements, reversing the historical attach-rate model that sustained vendor margins. Third-party reagent suppliers are capturing wallet share through certified compatibility claims and aggressive pricing on high-volume fluorochrome panels. This disintermediation is most visible in Australian research institutes, where national competitive grant funding pressures have intensified total-cost-of-ownership scrutiny.
Asia-Pacific Flow Cytometry Market Segmentation
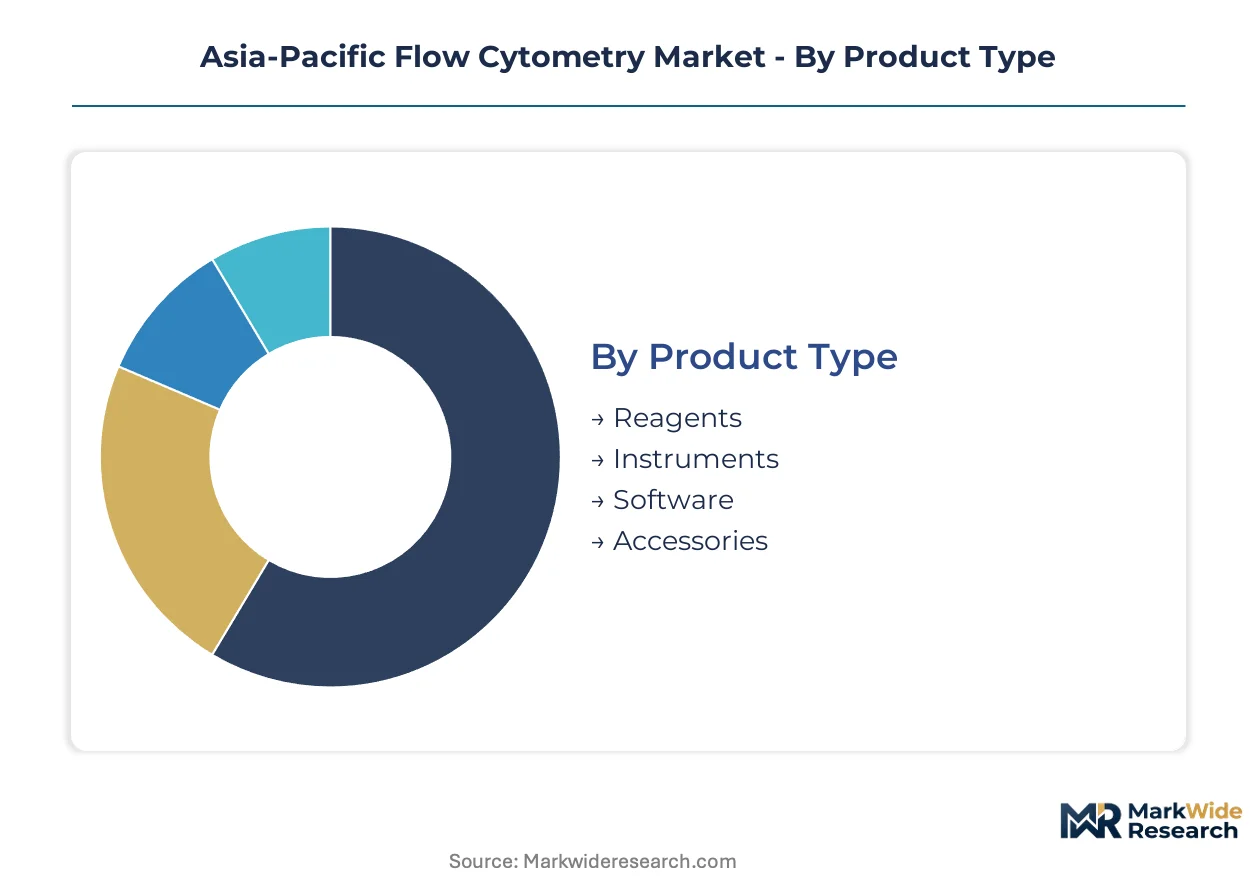
Flow cytometry procurement decisions in Asia-Pacific diverge sharply by product category, with capital-intensive instruments facing multi-year NMPA and PMDA approval cycles while reagents navigate REACH-aligned chemical restrictions. Segmentation clarity enables vendors to match compliance investment with margin recovery potential across divergent regulatory environments.
Product Type:
Certification burdens stratify sharply across this dimension: instruments trigger Class II or III medical device pathways under NMPA and PMDA, while reagents face chemical safety dossiers under REACH-aligned regimes in South Korea and Taiwan.
- Instruments:Capital equipment encompassing cell analyzers and sorters with solid-state laser architectures and PMT or spectral detection modules. Demand concentrates in Shanghai and Suzhou biotech clusters where pharmaceutical firms scale analytical capacity for biologics development, though NMPA's 2021 reclassification to Class III devices has extended renewal timelines.
- Reagents:Fluorochrome-conjugated antibodies, viability dyes, and calibration beads generating recurring revenue streams. Procurement committees across Australian research institutes are unbundling these from mandatory instrument supply agreements, intensifying third-party competition.
- Software:Acquisition and analysis platforms handling compensation matrices and spectral unmixing algorithms. CDSCO import quality rules now encompass software modules as medical device components.
- Accessories:Sheath fluid systems, waste containment units, and replacement optical filters. These components face fewer regulatory barriers but carry service-attach strategic importance for instrument vendors defending installed bases.
Leading the category by volume: Reagents. Growing fastest: Instruments, driven by biologics pipeline expansion in China and India.
Application:
End-use intensity varies by research funding concentration and therapeutic development priorities, with government-backed programs anchoring academic volume while commercial pipelines drive premium instrumentation.
- Cancer Research:Immuno-oncology trials and CAR-T potency testing demand high-parameter immunophenotyping capabilities. Singaporean institutes and Shanghai biotech clusters are adopting spectral flow systems at replacement-cycle pace, bypassing incremental upgrades to conventional platforms.
- Immunology:Autoimmune disease biomarker discovery and vaccine response profiling. Japanese diagnostic networks sustain hematology-adjacent demand through Sysmex's channel control in domestic hospital laboratories.
- Hematology:Blood cell differential analysis and leukemia/lymphoma diagnostics. PMDA compliance pressure is most acute here, with manufacturers accelerating local manufacturing partnerships to qualify for streamlined domestic-device pathways.
- Cell Biology:Apoptosis detection, cell cycle analysis, and proliferation assays. Academic institutes across Japan and Australia remain the volume anchor through government-funded life sciences programs.
Volume concentration: Cancer Research. Steepest expansion trajectory: Immunology, as Asia-Pacific vaccine development programs multiply.
End User:
Customer procurement authority shapes pricing leverage and attach-rate economics, with consolidated pharmaceutical buyers extracting unbundling concessions that fragment historical vendor margin pools.
- Pharmaceutical Firms:Biologics developers in China and India scaling analytical capabilities for monoclonal antibody and cell therapy programs. These buyers command volume discounts and demand service-revenue transparency.
- Academic Institutes:Government-funded research campuses across Japan, Australia, and emerging Vietnamese life sciences infrastructure. National competitive grant pressures have intensified total-cost-of-ownership scrutiny, particularly in Australian institutes.
- Biotechnology Companies:Venture-backed drug discovery operations concentrated in Singapore and Shanghai clusters. These entities prioritize spectral flow technology for high-dimensional immunophenotyping experiments.
- Hospitals:Clinical diagnostic laboratories in Japan and Australia where Becton, Dickinson and Company leverages instrument-reagent bundling. Legacy LIS integration friction extends deployment timelines in Australian public health networks.
Primary volume source: Academic Institutes. Fastest wallet-share gain: Pharmaceutical Firms.
Technology:
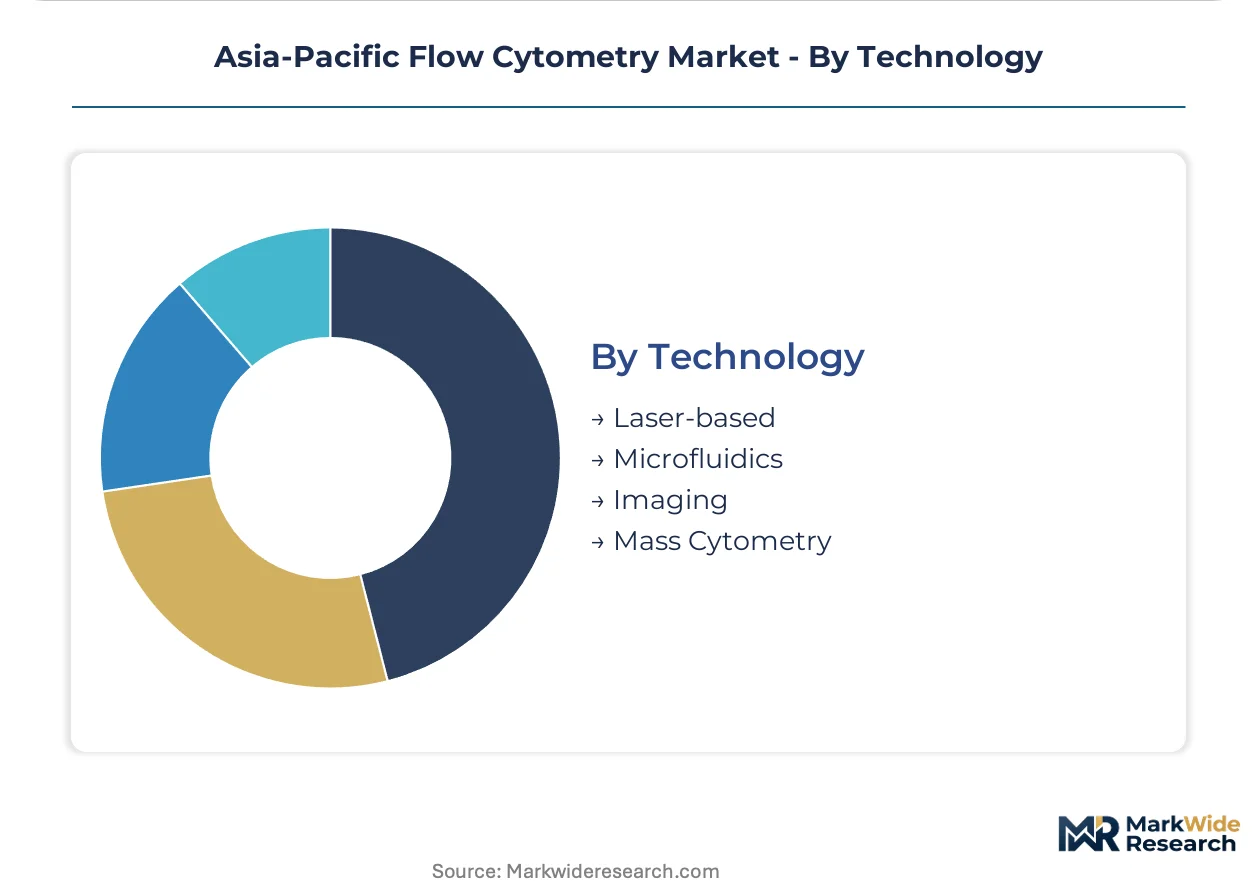
Architecture selection determines parameter ceiling, capital intensity, and operator skill requirements, with spectral and mass cytometry systems displacing conventional PMT-based platforms in high-dimensional applications.
- Laser-based:Conventional fluorescence systems using discrete optical filters and PMT detection. Margins are compressing across Asia-Pacific research institutes as spectral architectures capture replacement demand.
- Spectral:Full-spectrum capture across continuous wavelength ranges enabling 40-plus fluorochrome measurement without compensation matrix complexity. Cytek Biosciences extends footprint into Singaporean research institutes through this technology leadership.
- Mass Cytometry:Metal-tag-based single-cell analysis capturing high-parameter research applications above 30 colors. This modality threatens conventional fluorescence systems in deep immunophenotyping workflows.
- Imaging:Image-enabled flow cytometry combining morphometric data with fluorescence signatures. Adoption remains concentrated in specialized cancer research applications.
- Microfluidics:Chip-based fluid handling reducing sample volume requirements. Integration with automated cell therapy QC platforms is emerging as a point-of-release testing solution for CAR-T manufacturing suites.
Installed base dominance: Laser-based systems. Fastest capability expansion: Spectral detection architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates instrument manufacturing capacity while Japan and Australia absorb premium diagnostic systems. India and Vietnam represent consumption growth frontiers where biologics pipelines and government research campuses are multiplying procurement volumes.
China
Shanghai and Suzhou biotech clusters drive pharmaceutical firm demand for high-parameter analytical systems. NMPA's 2021 reclassification of certain flow cytometry instruments to Class III devices has extended clinical trial submission requirements for registration renewals. Domestic manufacturing partnerships are accelerating to qualify for streamlined approval pathways for hematology-adjacent diagnostic systems.
Japan
Hospital laboratories sustain hematology-adjacent instrument demand through established diagnostic networks. PMDA maintains stringent instrument registration pathways that fragment product launch timelines relative to other Asia-Pacific jurisdictions. Sysmex Corporation leverages deep channel control in domestic diagnostics to anchor reagent attach-rates across Kanto and Kansai regions.
India
Pharmaceutical firms in Hyderabad and Bengaluru are scaling analytical capabilities for monoclonal antibody development. CDSCO tightened medical device quality rules for imported instruments, elevating compliance barriers for low-tier vendors. Government-funded life sciences programs at IISc and AIIMS campuses anchor academic procurement volumes.
Australia
Research institutes in Melbourne and Sydney are unbundling instrument purchases from mandatory multi-year reagent supply agreements. TGA conformity assessments add compliance layers for reagent kits and software modules. National competitive grant funding pressures have intensified total-cost-of-ownership scrutiny across public health networks.
Vietnam
Government-funded life sciences campuses in Hanoi and Ho Chi Minh City remain underpenetrated by spectral flow vendors. The country's national pharmaceutical regulator is aligning chemical safety standards with REACH-aligned frameworks. First-mover positioning by instrument vendors is emerging ahead of potential ASEAN regulatory harmonization.
Asia-Pacific Flow Cytometry Market Competitive Landscape
Top-tier vendors anchor hospital and pharmaceutical laboratory segments, while mid-tier specialists capture research institute procurement through technology differentiation. The vendor base stratifies across three archetypes: diversified life sciences conglomerates with instrument-reagent bundling capabilities, spectral technology specialists with full-spectrum detection architectures, and hematology-focused diagnostics firms with deep domestic channel control. Competitive moves concentrate on service-revenue attachment acceleration and local manufacturing partnerships to navigate divergent NMPA and PMDA registration pathways.
Among diversified life sciences conglomerates, Becton, Dickinson and Company and Thermo Fisher Scientific exemplify the instrument-reagent bundling archetype across Japanese and Australian hospital networks. Cytek Biosciences occupies a position within the spectral technology specialist tier, with its geographic origin in California representing the cross-regional technology transfer pattern visible across Singaporean research institutes. Sysmex Corporation anchors the hematology-adjacent diagnostics archetype through its Tokyo-based corporate structure and established domestic Japanese market presence.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Beckman Coulter |
| Thermo Fisher Scientific |
| Agilent Technologies |
| Bio-Rad Laboratories |
| Sysmex Corporation |
| Miltenyi Biotec |
| Sony Biotechnology |
| Cytek Biosciences |
| Others |
Pricing and Supply Chain Analysis
Solid-state laser component price indices cascade through instrument manufacturing tiers, compressing margins on conventional PMT-based systems while spectral architectures command premium positioning through differentiated fluorochrome compatibility.
Pricing Analysis
Price erosion across entry-tier instruments traces to unbundling of reagent supply agreements by Australian and Japanese academic procurement committees. Three-tier pricing structure across premium spectral, standard laser-based, and economy filter systems stratifies by parameter ceiling and software sophistication. Cost compression accelerates in conventional platforms as third-party reagent suppliers erode historical attach-rates. Pharmaceutical firms in Shanghai biotech clusters exhibit lowest price sensitivity due to CAR-T potency testing requirements, while Vietnamese government campuses remain most cost-constrained.
Supply Chain Analysis
Freight cost volatility from German and Japanese specialty optics suppliers exposes instrument margins to input price swings. Manufacturing concentration centers on China for domestic NMPA pathway qualification, Japan for PMDA-compliant hematology systems, and Singapore for ASEAN research institute distribution. Solid-state laser diodes, PMT detection modules, and spectral gratings constitute critical component dependencies. Single-source vulnerability in Japanese laser optics creates supply continuity risk. Distribution runs through direct hospital laboratory contracts in Japan, GPO-aggregated research institute procurement in Australia, and pharmaceutical firm direct sales in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spectral detection architectures are actively displacing conventional fluorescence systems across Asia-Pacific research markets, compressing legacy vendor margins and opening white-space for technology specialists.
For Market Incumbents: Deploy service-revenue acceleration to defend installed bases against spectral substitution. Accelerate local manufacturing partnerships in China to qualify for NMPA Class III streamlined pathways. Deepen reagent attach-rates through closed-cell processing platform integration for CAR-T manufacturing suites. Counter third-party reagent disintermediation through certified compatibility lock-in. For New Entrants and Emerging Players: Begin with Vietnamese government-funded life sciences campuses in Hanoi and Ho Chi Minh City, where spectral flow penetration remains minimal. Target cell therapy QC integration opportunities as CAR-T manufacturing scales across Shanghai and Suzhou clusters. Pursue ASEAN regulatory harmonization positioning ahead of unified device approval frameworks. Lead with computational biology training partnerships to address spectral compensation expertise gaps in tier-2 Chinese hospital laboratories. For Investors and Strategic Acquirers: Distressed-cycle entries favor spectral technology specialists with established Singaporean research institute footprints and software algorithm differentiation. Long-term viability hinges on spectral unmixing IP portfolios and service infrastructure density across NMPA and PMDA jurisdictions. Monitor CDSCO import quality rule enforcement as inflection indicator for certified vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Class III Registration Pathway | Accelerates market access through domestic manufacturing partnerships in Shanghai biotech clusters. |
| Spectral Technology Licensing | Enables 40-plus fluorochrome measurement without compensation matrix complexity in Singaporean institutes. |
| Cell Therapy QC Integration | Converges automated flow cytometry with closed-cell processing for CAR-T potency testing. |
| CDSCO Certification Investment | Elevates compliance barriers against low-tier imports in Hyderabad and Bengaluru pharmaceutical corridors. |
| ASEAN Harmonization Positioning | Captures first-mover advantage ahead of unified device approval frameworks in Vietnamese campuses. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with biomedical engineers, hospital purchasing committee members, pharmaceutical analytical development heads, and GPO contracts managers combined with NMPA device registration databases, PMDA approval records, CDSCO import quality notifications, and customs trade statistics. Bottom-up instrument shipment modeling and top-down reagent revenue triangulation validated segment-level outputs.
Granularity-level modeling distinguished spectral from laser-based technology architectures, Class II versus Class III regulatory pathways, and pharmaceutical firm versus academic institute procurement patterns. CAGRs derived from replacement-cycle analysis of installed bases, biologics pipeline expansion rates, and fluorophore reformulation investment trajectories. Spectral detection adoption curves and mass cytometry substitution thresholds informed capability-transition assumptions across the projection horizon.
Underlying measurement precision varies by segment; instrument revenue and reagent attach-rate estimates carry tighter precision than emerging microfluidics integration forecasts. Projections reflect assumptions regarding NMPA-PMDA registration divergence persistence and ASEAN harmonization timeline uncertainty. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
North America Flow Cytometry Market
Medical Diagnostics
Global Hydrophobic Interaction Chromatography Market
Medical Diagnostics
US Molecular Diagnostics Market
Medical Diagnostics
Flow Cytometry Market
Medical Diagnostics
Global HLA Typing Market
Medical Diagnostics
MUC1 Antibody Market
Medical Diagnostics
Real-Time PCR, Digital PCR, and End-Point PCR Market
Medical Diagnostics
Fluid Biopsy Market
Medical Diagnostics
Dosimetry Market
Medical Diagnostics
Liver Biopsy Market
Medical Diagnostics
North America Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
Electroretinogram Market
Medical Diagnostics
Cellular Pathology Market
Medical Diagnostics
Stem Cell Characterization Kits Market
Medical Diagnostics
Medical Isotope Market
Medical Diagnostics
Circulating Tumor Cells (Ctcs) Prognostic Technologies Market