
 Carrier Screening Market | 2026-2036
Carrier Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Carrier Screening Market Intelligence
US-based reference laboratories is recalibrating service capacity to match rising physician-ordered test volumes. Illumina Inc. anchors the upstream sequencing instrument supply chain with dominant platform placements across clinical laboratories. Thermo Fisher Scientific Inc. leverages its integrated reagent and consumable ecosystem to sustain pricing power in high-throughput carrier screening workflows. Quest Diagnostics Incorporated competes through its national collection network and direct relationships with obstetrician-gynecologist practices.
Carrier screening comprises molecular diagnostic assays that detect pathogenic variants in genes associated with autosomal recessive and X-linked disorders, typically performed via next-generation sequencing or targeted SNP array analysis with detection thresholds often set at minor allele frequencies above 0.1% in relevant populations; its primary purpose is to inform reproductive decision-making by quantifying transmission risk prior to conception or during early pregnancy. Expanded carrier screening panels now lead test type demand as they replace single-gene testing in routine prenatal care, while next-generation sequencing technology captures the fastest growth trajectory due to superior multiplexing capacity and declining cost per base. Margin pools concentrate in physician-ordered service channels where reimbursement rates exceed direct-to-consumer alternatives and clinical interpretation bundling adds value.
FDA oversight of laboratory-developed tests and CLIA certification requirements shape analytical validity standards for carrier screening assays performed in US facilities, while HIPAA privacy rules govern genetic data handling and patient consent protocols. The EU In Vitro Diagnostic Regulation enforces stricter performance documentation and notified body involvement for sequencing-based screening products marketed in Europe. Stakeholders must monitor evolving payer coverage determinations and state-level genetic counseling mandates as these policies directly influence test access and commercial model sustainability.
Market Dynamics
Expanded carrier screening panels are compressing single-gene testing volumes as fertility clinics and OB-GYN practices standardize on broader genomic assays for preconception counseling.
Growth Catalysts
- HIPAA-aligned data infrastructure:US laboratories have built compliant genetic data pipelines that reduce patient consent friction and accelerate test turnaround times in physician-ordered channels.
- Next-generation sequencing multiplexing:The technology's parallel processing capability is collapsing per-sample costs while maintaining analytical validity for autosomal recessive variant detection.
- Fertility clinic consolidation:Large clinic networks in the United States are negotiating enterprise contracts for expanded panels, creating concentrated demand pools that justify assay menu expansion.
Market Restraints
- Reagent supply concentration:Sequencing consumables flow through a narrow supplier base concentrated in North American and European manufacturing clusters, exposing laboratories to allocation risk during demand surges.
- Genetic counselor workforce scarcity:The United States lacks sufficient board-certified counselors to interpret expanded panel results at the pace of test volume growth, creating interpretation bottlenecks.
- State-level mandate fragmentation:Inconsistent genetic counseling requirements across US states complicate national service models and force redundant compliance investments.
Strategic Opportunities
- Direct-to-consumer channel normalization:Regulatory clarity from the FDA on consumer-facing genetic health risk tests is opening compliant pathways for carrier screening outside traditional clinical settings.
- Polygenic risk score integration:Convergence of carrier screening with common variant risk quantification is enabling comprehensive reproductive health assessments that differentiate service offerings.
- South Asian population panels:Underpenetrated demand among South Asian communities in the United States and United Kingdom for beta-thalassemia and G6PD screening supports targeted assay development.
Industry Challenges
- Variant of uncertain significance interpretation:Expanded panels generate higher rates of inconclusive findings that strain laboratory geneticist capacity and extend reporting timelines.
- Laboratory information system integration:Electronic health record connectivity requirements differ across US health systems, forcing customized middleware development for each major hospital network deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carrier Screening Market |
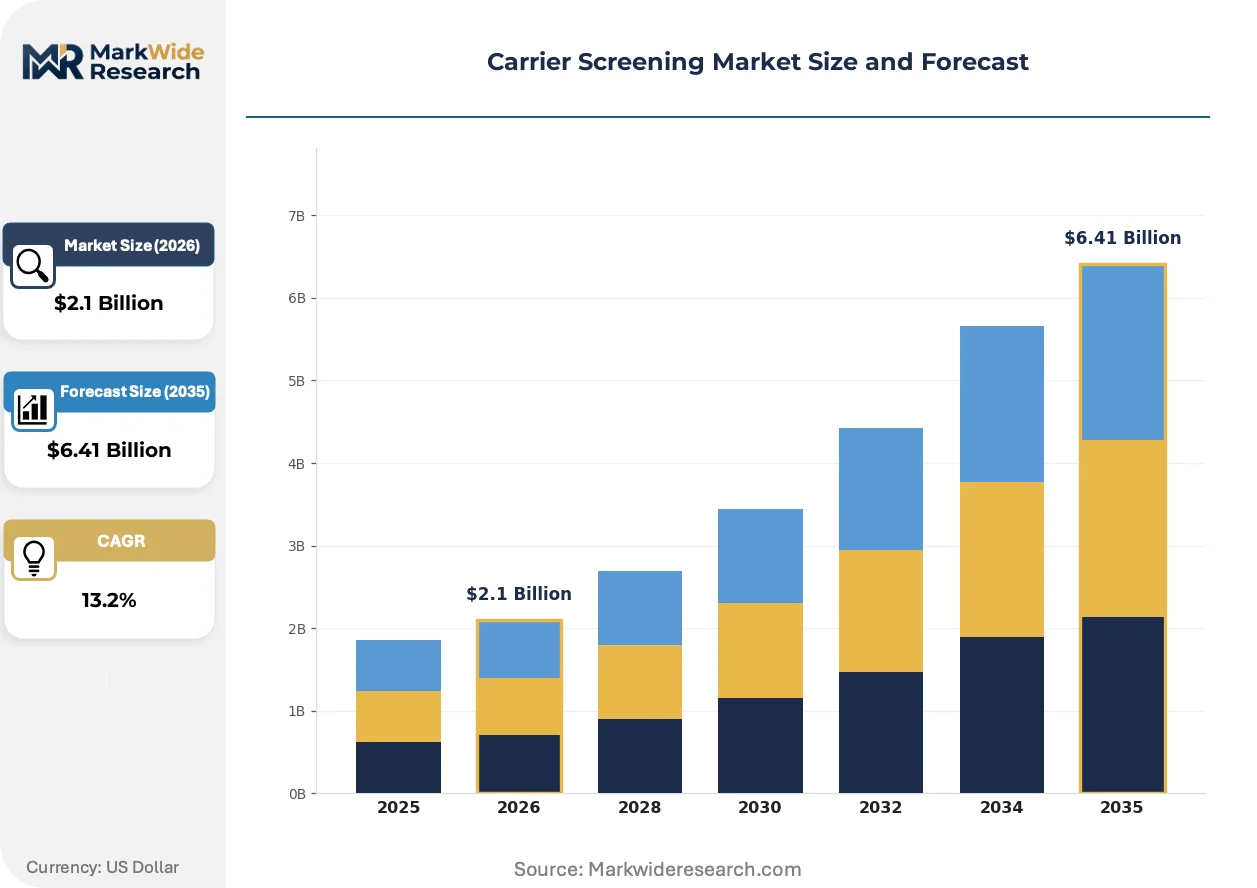
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $6.41 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Single Gene Testing, Expanded Carrier Screening, Preconception Testing, Non-Invasive Prenatal Testing Technology: SNP Array, Next-Generation Sequencing, PCR, Whole Genome Sequencing End User: Hospitals, Laboratories, Clinicians, Genetic Counselors Service Type: Direct-to-Consumer, Physician-Ordered, Research-Based, Newborn Screening |
| Companies Covered | Illumina Inc., Thermo Fisher Scientific Inc., Quest Diagnostics Incorporated, Myriad Genetics Inc., Fulgent Genetics Inc., Invitae Corporation, Natera Inc., Laboratory Corporation of America Holdings, Eurofins Scientific SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carrier Screening Market Strategic Shifts & Innovations
Carrier screening workflows are undergoing platform-level automation that compresses manual touchpoints while regulatory frameworks on both sides of the Atlantic tighten analytical validity documentation requirements.
Liquid biopsy sample preparation robotics is automating nucleic acid extraction and library construction steps that previously required skilled technologist intervention. Mid-sized reference laboratories in the United States are deploying these systems to maintain throughput without proportional headcount expansion. The technology is automating quality control checkpoints that historically delayed result release.
The EU In Vitro Diagnostic Regulation now mandates notified body review for sequencing-based screening products marketed in Europe, replacing the self-certification regime that governed prior generations of assays. Manufacturers must generate expanded clinical evidence packages and post-market surveillance systems. European laboratories are responding by consolidating purchasing relationships with suppliers who have secured MDR certification.
Employer-sponsored preconception benefits are displacing traditional insurance-based access models for carrier screening among US technology sector workers. Large self-insured employers in California and Washington state are contracting directly with laboratories for population health programs. This channel shift is most visible among dual-income professional households planning first pregnancies.
Carrier Screening Market Segmentation
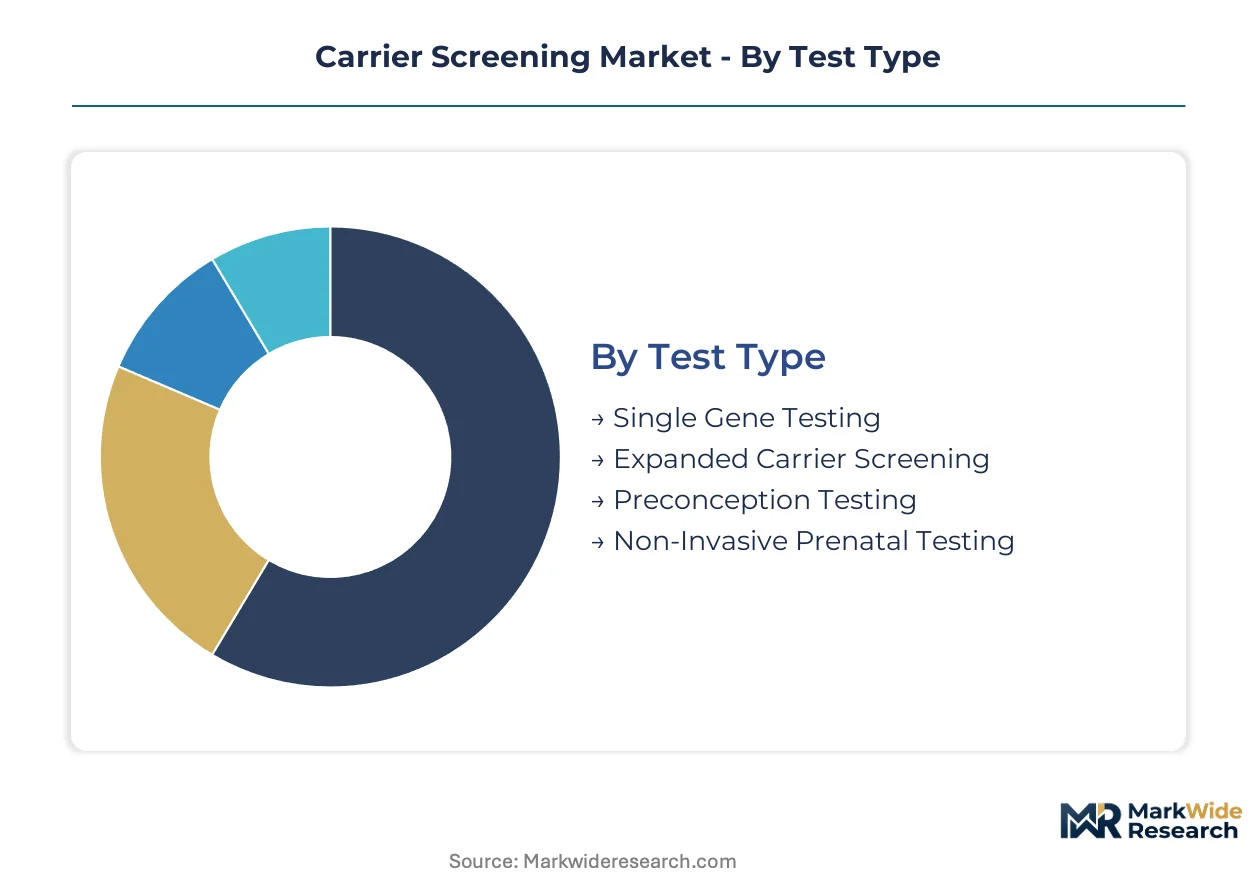
Carrier screening markets fragment across test design philosophies, technology platforms, and service delivery channels that determine reimbursement pathways and clinical utility. Understanding these segment boundaries clarifies where margin pools concentrate versus where commoditization pressures intensify.
Test Type:
Volume concentration favors broader panels while premium pricing persists in targeted applications.
- Single Gene Testing:Targeted assays for cystic fibrosis, sickle cell disease, and Tay-Sachs carrier status remain embedded in state-mandated newborn screening programs. Demand concentrates in Medicaid-funded health systems where narrow panels satisfy regulatory minimums at lowest cost per test.
- Expanded Carrier Screening:Multiplexed panels assessing 100+ recessive conditions now dominate fertility clinic procurement. OB-GYN practices in the United States are standardizing on these assays for preconception counseling, displacing sequential single-gene ordering.
- Preconception Testing:Couples-focused screening protocols assess concurrent carrier status across both partners. Deployment concentrates in employer-sponsored wellness programs at technology firms in California and Washington.
- Non-Invasive Prenatal Testing:Cell-free DNA analysis for fetal aneuploidy screening operates on adjacent clinical workflows. Laboratories bundle these services with expanded carrier panels to capture complete reproductive genetic testing spend per pregnancy.
Mature deployment sits with single gene testing in public health programs. Newer deployment is concentrated in expanded carrier screening across private fertility networks.
Technology:
Cost per base and analytical throughput differentiate platform economics across laboratory scales.
- SNP Array:Fixed-content genotyping platforms deliver rapid turnaround for common variant detection at predetermined loci. Mid-sized reference laboratories deploy these systems where sample volumes do not justify sequencing infrastructure investment.
- Next-Generation Sequencing:Massively parallel sequencing enables gene-agnostic variant discovery with expanding content flexibility. The technology's multiplexing capacity is collapsing per-sample costs while maintaining detection sensitivity for rare pathogenic variants.
- PCR:Targeted amplification remains cost-optimal for single-site mutation detection in resource-constrained settings.
- Whole Genome Sequencing:Comprehensive genomic analysis is penetrating research applications and ultra-high-net-worth direct-to-consumer channels.
SNP array deployment dominates high-volume, fixed-menu screening. Steepest expansion trajectory belongs to next-generation sequencing as reagent costs decline and bioinformatics pipelines mature.
End User:
Channel economics diverge sharply between institutional procurement and individual practitioner ordering.
- Hospitals:Integrated health systems negotiate enterprise contracts covering inpatient and outpatient genetic testing. Labor and delivery units in the United States are embedding expanded carrier screening into standard prenatal intake protocols.
- Laboratories:Reference laboratories process samples from multiple ordering sites, capturing economies of scale in sequencing operations. National networks compete on turnaround time and EHR integration depth.
- Clinicians:Individual OB-GYN and reproductive endocrinology practices maintain direct relationships with preferred testing vendors.
- Genetic Counselors:Board-certified practitioners interpret complex results and guide reproductive decision-making, though workforce scarcity limits channel expansion.
Laboratory consolidation is concentrating procurement power. Clinician-direct ordering is fragmenting across regional practice management preferences.
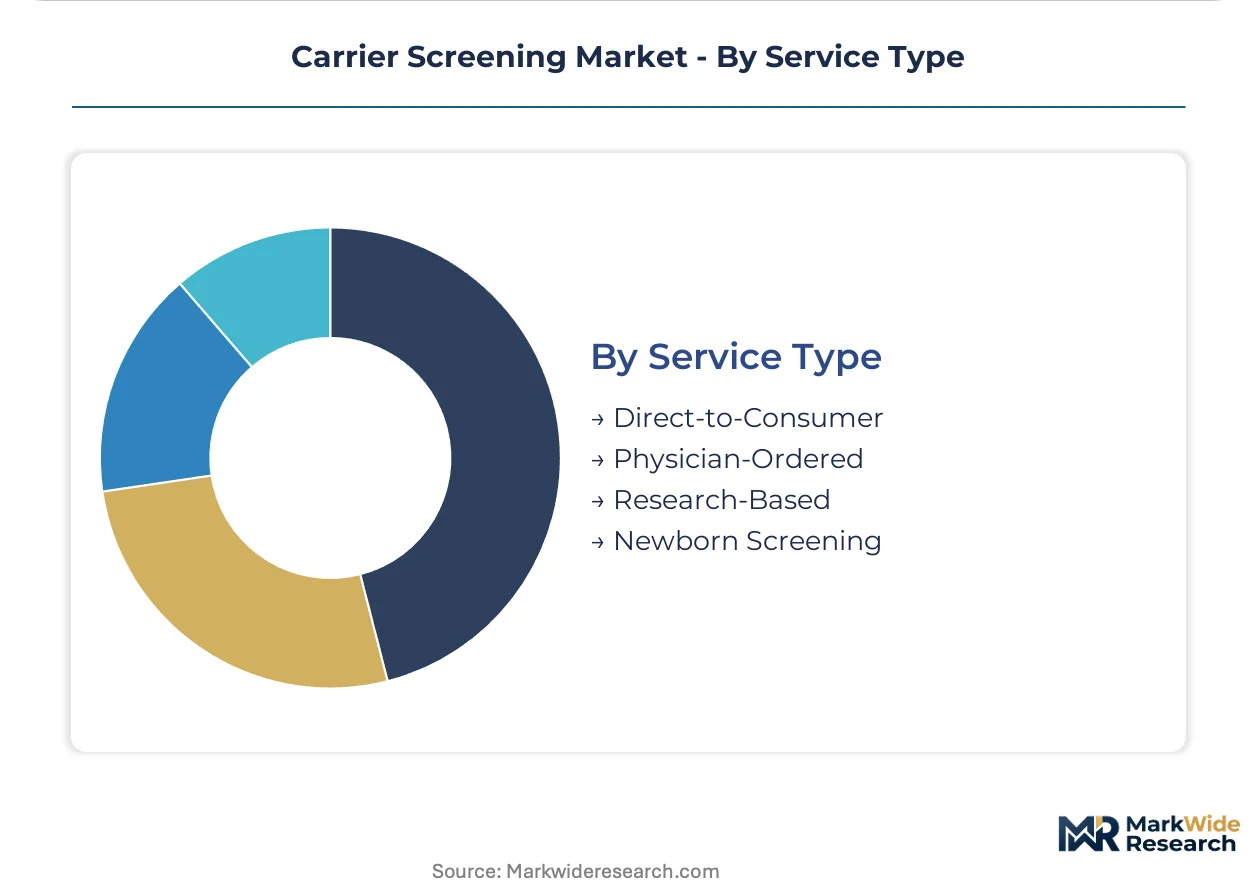
Service Type:
Regulatory classification and reimbursement methodology create distinct commercial model requirements.
- Direct-to-Consumer:Consumer-initiated testing bypasses traditional clinical channels, requiring FDA compliance for health risk communications. California and New York state laboratories dominate this segment due to permissive telemedicine counseling frameworks.
- Physician-Ordered:Clinician-mediated testing captures highest reimbursement rates through private payer coverage. The channel requires CLIA-certified laboratory processing and documented informed consent protocols.
- Research-Based:Investigational screening protocols operate outside standard clinical reimbursement, funded by academic grants or pharmaceutical partnerships.
- Newborn Screening:State-mandated testing programs operate as public health infrastructure with fixed fee schedules.
Physician-ordered services command premium pricing. Direct-to-consumer pathways are gaining regulatory clarity fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reproductive genetic testing infrastructure concentrates where fertility clinic networks and reference laboratory capacity overlap most densely.
United States
Private payer coverage expansion for expanded carrier screening panels drives test volume growth through OB-GYN practices and fertility networks. FDA oversight of laboratory-developed tests and CLIA certification requirements enforce analytical validity standards for sequencing-based assays. The San Francisco Bay Area and Boston corridor host dense clusters of reproductive health startups and reference laboratory operations.
Germany
Preimplantation genetic testing demand from fertility clinics in Bavaria and North Rhine-Westphalia supports carrier screening adoption as a preconception complement. The EU In Vitro Diagnostic Regulation mandates notified body review for sequencing-based screening products, replacing prior self-certification regimes. Berlin and Munich serve as hubs for clinical genetics service consolidation and reproductive medicine research coordination.
United Kingdom
NHS England's genomic medicine service integration creates procurement pathways for expanded carrier panels in preconception counseling. The UK Human Fertilisation and Embryology Authority regulates genetic testing in fertility treatment contexts with specific consent protocols. London's academic medical centers and Cambridge's biotechnology corridor anchor clinical implementation and assay development activity.
Canada
Provincial health system variation creates patchwork coverage for carrier screening outside newborn screening mandates. Health Canada regulates in vitro diagnostic devices with requirements for clinical evidence documentation that parallel FDA frameworks. Toronto and Vancouver concentrate fertility clinic networks and reference laboratory partnerships serving diverse metropolitan populations.
Australia
Specialist obstetrician adoption of expanded panels outpaces public reimbursement, creating private-pay market development. The Therapeutic Goods Administration oversees in vitro diagnostic regulation with post-market surveillance requirements for sequencing platforms. Sydney and Melbourne host the dominant fertility clinic networks and clinical genetics service providers.
Carrier Screening Market Key Industry Players
Global majors compete with regional champions across sequencing platform supply and laboratory service delivery. The market structure tiers between upstream instrument manufacturers, midstream reference laboratories, and downstream fertility clinic networks. Three archetypes dominate: integrated life science conglomerates with reagent-to-instrument ecosystems; national reference laboratories with collection network scale; and specialized genetic testing firms with reproductive health focus. Competitive moves center on enterprise contract consolidation with fertility clinic networks and regulatory certification acceleration for expanded panel content.
Within the integrated technology tier, Illumina Inc. and Thermo Fisher Scientific Inc. anchor sequencing instrument and consumable supply chains. Quest Diagnostics Incorporated occupies a position among national reference laboratory networks with physician relationship scale. These three entities exemplify the vertical specialization patterns that concentrate procurement power and service delivery capacity across distinct competitive vectors.
| Leading Market Players |
|---|
| Illumina Inc. |
| Thermo Fisher Scientific Inc. |
| Quest Diagnostics Incorporated |
| Myriad Genetics Inc. |
| Fulgent Genetics Inc. |
| Invitae Corporation |
| Natera Inc. |
| Laboratory Corporation of America Holdings |
| Eurofins Scientific SE |
| Others |
Cost & Logistics Intelligence
Captive integration into sequencing instrument and reagent ecosystems anchors supply security for US reference laboratories while simultaneously locking in pricing power for upstream platform vendors. This vertical control pattern concentrates procurement leverage among laboratories with enterprise-scale throughput, compressing margins for mid-tier competitors lacking comparable volume commitments.
Pricing Analysis
Service-bundling differentiation separates physician-ordered channels from direct-to-consumer alternatives, with clinical interpretation and genetic counseling support commanding premium positioning. Three-tier pricing structure across enterprise fertility networks, individual OB-GYN practices, and consumer-initiated testing reflects volume scale and reimbursement pathway disparities. Cost compression in direct-to-consumer tiers is intensifying because regulatory clarity is lowering compliance overhead for new entrants. Employer-sponsored wellness programs exhibit lowest price sensitivity due to population health budgeting, while Medicaid-funded health systems remain most constrained.
Supply Chain Analysis
Single-source vulnerability sits with Illumina's dominant sequencing instrument placements across North American clinical laboratories. Reagent manufacturing concentrates in the United States, Germany, and Singapore, with flow cells and library preparation kits drawing from specialized polymer and semiconductor-grade chemical suppliers. Tariff exposure on Chinese-sourced oligonucleotides and synthetic biology inputs threatens cost stability for mid-sized reference laboratories. Distribution runs through CLIA-certified laboratory networks with direct courier collection infrastructure, bypassing traditional medical device distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carrier screening markets are consolidating around sequencing platform scale and fertility clinic enterprise contracts, with regulatory compliance costs forcing sub-scale laboratories toward acquisition or exit. This consolidation pressure intensifies as EU MDR certification requirements and US FDA LDT oversight raise fixed compliance investments.
For Market Incumbents: Deepen captive control over bioinformatics pipelines and variant interpretation databases to differentiate from emerging sequencing-as-a-service competitors. Anchor capacity expansion in California and Massachusetts corridors where fertility clinic density supports throughput utilization. Defend against direct-to-consumer normalization by embedding EHR integration depth that consumer-facing alternatives cannot replicate. For New Entrants and Emerging Players: Polygenic risk score integration capabilities offer a technology-first wedge into employer-sponsored preconception benefits programs at technology sector firms. South Asian population-specific panels for beta-thalassemia and G6PD screening represent the most penetrable white-space target in the United States and United Kingdom. Pursue telemedicine-enabled genetic counseling partnerships to circumvent workforce scarcity constraints that bottleneck incumbent scaling. For Investors and Strategic Acquirers: Exit pathways concentrate in platform-level acquisitions by integrated life science conglomerates seeking reproductive health vertical penetration. Mid-sized reference laboratories with CLIA certification and established fertility clinic relationships represent the highest-probability acquisition archetype over the medium-term horizon. Watch FDA guidance on laboratory-developed tests as the critical inflection signal for direct-to-consumer channel viability and incumbent defensive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Acceleration | Notified body approval for sequencing-based panels unlocks European fertility clinic procurement pathways. |
| Polygenic Risk Score Integration | Convergence with common variant quantification differentiates service offerings in employer-sponsored channels. |
| Enterprise Fertility Network Contracts | Consolidated purchasing agreements with large clinic systems concentrate demand and justify assay menu expansion. |
| EHR Integration Middleware Development | Customized connectivity with major hospital networks creates switching costs that protect incumbent relationships. |
| Telemedicine Genetic Counseling Partnerships | Remote interpretation capacity addresses workforce scarcity without proportional headcount expansion. |
Research Approach
Independent corroboration across laboratory operations executives, fertility clinic medical directors, and genetic counseling program directors underwrites the qualitative findings in this study. Primary interviews with CLIA laboratory managers, reproductive endocrinologists, and payer policy specialists were cross-validated against FDA 510(k) filings, CMS coverage determinations, and state-level genetic counseling mandate databases. Bottom-up test volume modeling and top-down market sizing triangulate across the analysis window.
Comparable-period anchoring to historical carrier screening adoption curves in cystic fibrosis and spinal muscular atrophy informs the projection framework. Segmentation dimensions span test type, technology platform, end-user channel, and service delivery model, with CAGRs derived from slope-consistent trajectory analysis rather than endpoint targeting. Reimbursement pathway evolution and fertility clinic consolidation pace serve as primary forecast sensitivity inputs.
Several conditions sit outside the modeled scope, including disruptive regulatory reclassification of carrier screening as preventive versus diagnostic, and breakthrough non-invasive fetal genome sequencing technologies that could displace preconception testing paradigms. Deviation in FDA LDT enforcement posture or EU MDR implementation timeline would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Global ECG Stress Test Market
Medical Diagnostics
Cellular Pathology Market
Medical Diagnostics
X Ray Crystallography Market
Medical Diagnostics
In-Situ Hybridization (ISH) Market
Medical Diagnostics
Protein Sequencing Market
Medical Diagnostics
AI in Medical Diagnostics Market
Medical Diagnostics
Global HLA Typing for Transplant Market
Medical Diagnostics
US Molecular Diagnostics Market
Medical Diagnostics
Europe Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
Electroretinogram Market
Medical Diagnostics
Global Complete Blood Count Device Market
Medical Diagnostics
North America Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
Rapid Medical Diagnostic Kits Market
Medical Diagnostics
Stem Cell Characterization Kits Market
Medical Diagnostics
North America Flow Cytometry Market
Medical Diagnostics
MUC1 Antibody Market