
 Global ELISA Analyzer Market | 2026-2036
Global ELISA Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Global ELISA Analyzer Market Foresight
CE marking under the EU In Vitro Diagnostic Regulation is reorganizing competitive access for analyzer manufacturers seeking European commercialization. Thermo Fisher Scientific leverages its integrated reagent-instrument ecosystem to sustain installed-base loyalty across high-throughput clinical laboratories. Bio-Rad Laboratories anchors its position through specialized microplate detection architectures that dominate research and vaccine development settings. Danaher Corporation differentiates via Beckman Coulter automation platforms that compete on walkaway throughput for diagnostic workflows.
An ELISA analyzer is an automated or semi-automated photometric instrument that quantifies analyte concentration in liquid samples by measuring light absorbance, luminescence, or fluorescence following antigen-antibody binding reactions, typically operating across wavelength ranges of 340 to 750 nanometers with throughput from 96 to 1,536 wells per cycle. The device serves core purposes in clinical diagnostics, pharmaceutical quality control, and academic research where precise, reproducible quantification of proteins, hormones, or pathogens is required. Fully automated systems command the dominant share of value as diagnostic laboratories prioritize labor reduction and error-rate minimization in high-volume infectious disease testing. Chemiluminescent detection technology represents the fastest-expanding segment because its superior sensitivity and dynamic range displace colorimetric methods in hormone and tumor marker assays. Contract research organizations constitute a concentrated margin pool as their compound screening throughput demands premium-priced multi-mode reader configurations.
FDA 510(k) premarket notification and the EU In Vitro Diagnostic Regulation impose escalating clinical validation and quality management system requirements that extend development timelines and elevate capital barriers for new analyzer entrants. China's NMPA medical device registration pathway adds supplementary in-country testing mandates that shape market access sequencing for multinational manufacturers. ISO 13485 certification serves as a baseline procurement filter across institutional buyers, effectively segmenting compliant vendors from regional assemblers. Stakeholders must monitor how converging regulatory stringency in the United States, European Union, and China reshapes R&D allocation and geographic launch prioritization for next-generation detection platforms.
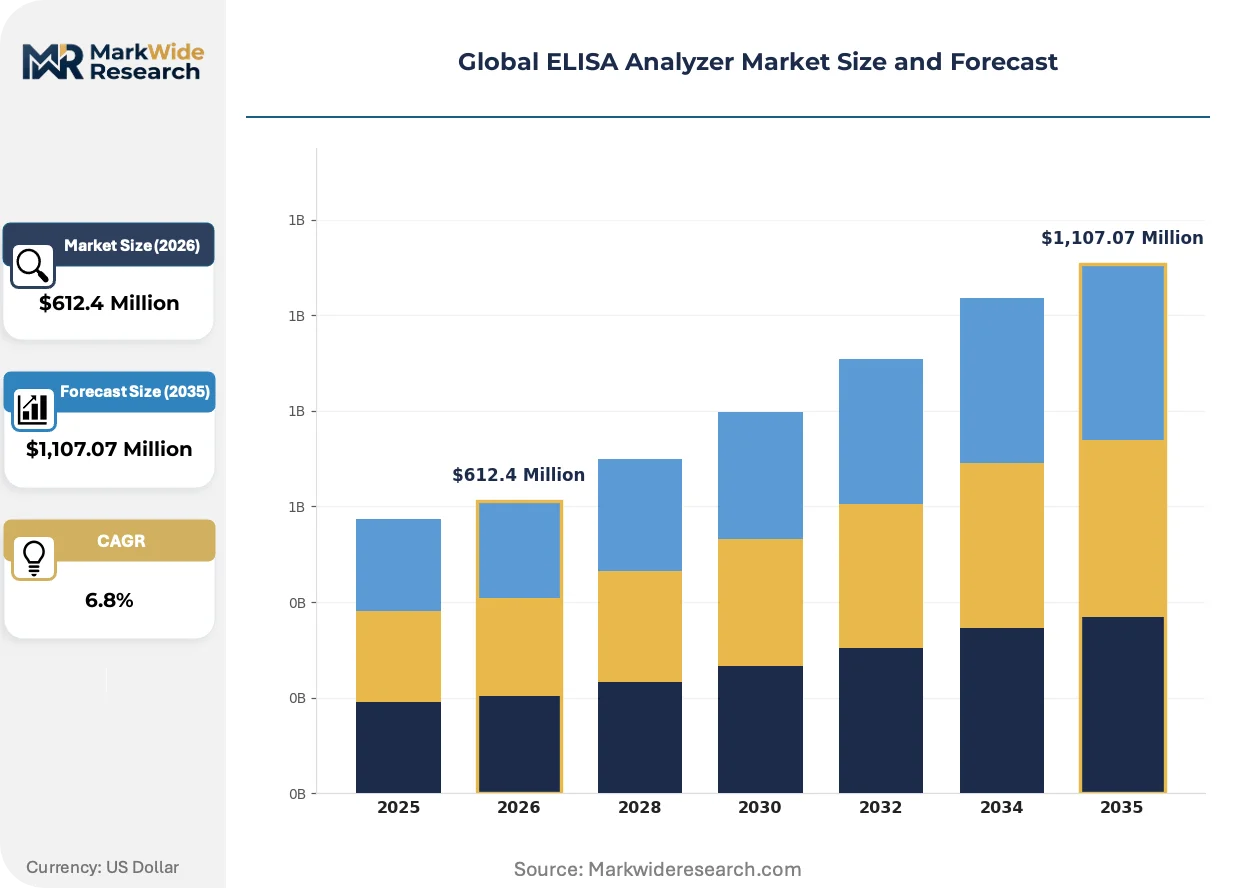
Market Dynamics
Automated workflow consolidation in centralized reference laboratories is compressing the addressable market for semi-automated ELISA analyzers while elevating capital requirements for full-system vendors serving high-throughput infectious disease screening networks.
Growth Catalysts
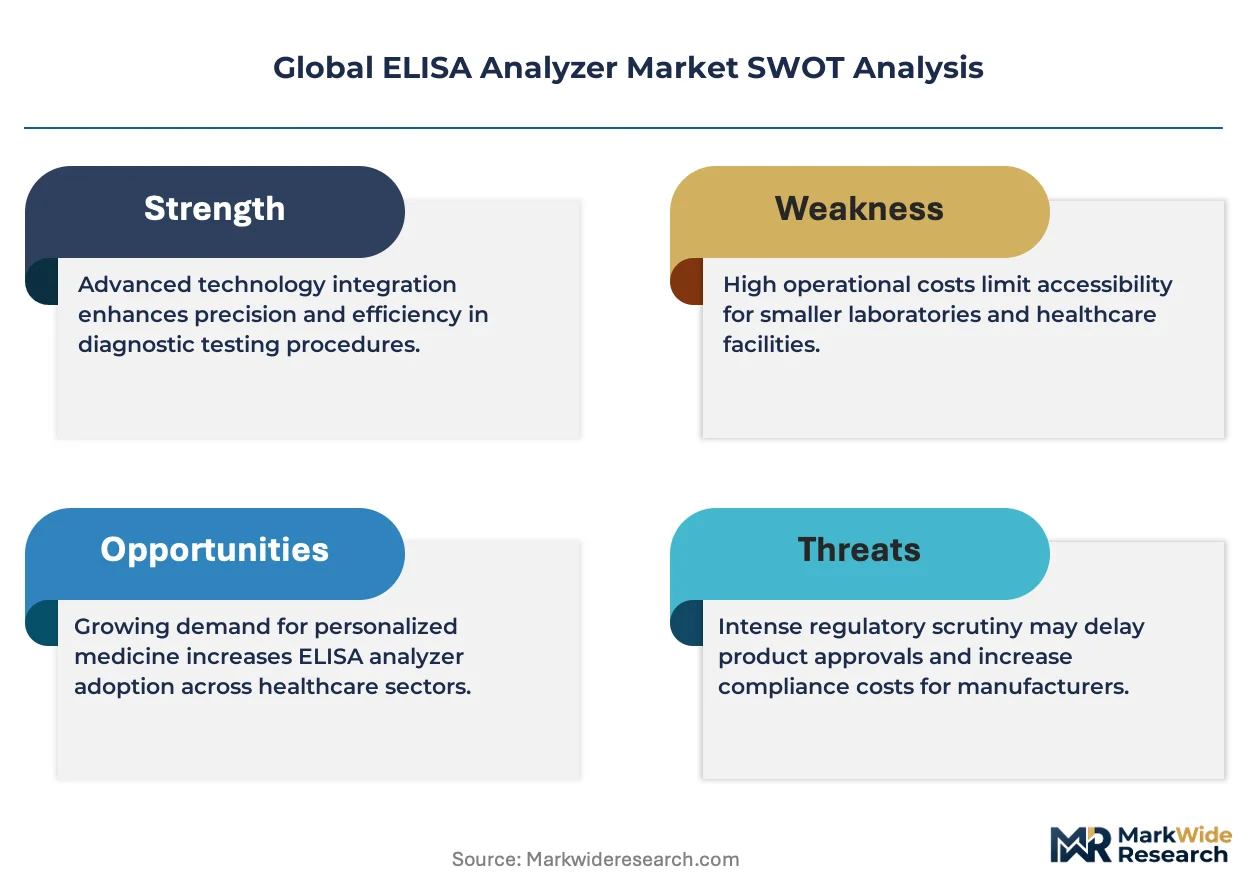
- EU IVDR Implementation:The European Union's In Vitro Diagnostic Regulation mandates enhanced performance validation for analyzer platforms, accelerating replacement cycles among laboratories seeking compliant instrumentation.
- Centralized Laboratory Expansion:China's scaling of reference laboratory networks under NMPA medical device registration pathways concentrates procurement authority and standardizes platform selection criteria.
- Chemiluminescence Detection Migration:Superior sensitivity and dynamic range in hormone and tumor marker assays is pulling diagnostic workflows away from colorimetric detection methods.
Market Restraints
- Optical Component Supply Concentration:Photomultiplier tubes and precision filters source predominantly from German and Japanese specialty manufacturers, creating single-source vulnerability for analyzer assembly.
- FDA 510(k) Timeline Extension:Escalating clinical validation requirements for new analyzer platforms stretch development-to-commercialization intervals and elevate regulatory capital barriers.
- Multiplex Bead Array Substitution:Luminex-based suspension array technologies capture mid-plex cytokine and biomarker quantification applications previously served by ELISA workflows.
Strategic Opportunities
- Point-of-Care Decentralization:Underpenetrated primary care clinics in India present installation potential for compact, cartridge-based ELISA systems bypassing reference laboratory bottlenecks.
- Veterinary Diagnostics Expansion:Companion animal healthcare networks in Germany and the United States are adopting human-clinical analyzer platforms for endocrine and infectious disease panels.
- Cloud-Connected Service Models:Remote instrument monitoring and predictive maintenance subscriptions create recurring revenue streams independent of reagent pull-through economics.
Industry Challenges
- ISO 13485 Talent Scarcity:Quality management system expertise required for medical device certification commands premium compensation and extends hiring timelines for emerging analyzer vendors.
- Legacy LIS Integration Complexity:Hospital information system interoperability with proprietary analyzer software requires customized middleware development, delaying installation acceptance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global ELISA Analyzer Market |
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fully Automated, Semi-Automated, Manual, Microplate Readers Technology: Colorimetric, Chemiluminescent, Fluorescent, Electrochemical Application: Infectious Diseases, Food Safety Testing, Vaccine Development, Drug Discovery End User: Diagnostic Laboratories, Pharmaceutical Companies, Academic Institutes, Contract Research Organizations |
| Companies Covered | Thermo Fisher Scientific, Bio-Rad Laboratories, Danaher Corporation, PerkinElmer Inc., Agilent Technologies, Tecan Group Ltd., Merck KGaA, Siemens Healthineers, DiaSorin S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global ELISA Analyzer Market Shifts & Advancements
Detection platform architecture is fragmenting as laboratories demand modular configurations that bridge clinical diagnostic throughput with research-grade flexibility, forcing vendors to reconcile incompatible design philosophies within unified product families.
Multi-mode reader technology is decomposing the traditional boundary between dedicated ELISA analyzers and general-purpose microplate detection systems. Contract research organizations in vaccine development settings are adopting these hybrid platforms at accelerated replacement cycles. The structural consequence is compressing the addressable market for single-function colorimetric analyzers while expanding premium configuration opportunities.
REACH regulation amendments restricting persistent organic pollutants in electronic components are compelling analyzer manufacturers to reformulate printed circuit board substrates and optical housing materials. Industrial consequence includes extended supplier qualification timelines and elevated bill-of-materials costs for European-market configurations. Diagnostic OEMs are responding by dual-sourcing compliant component streams and accelerating design-for-recyclability programs.
Reagent rental and instrument placement programs are displacing capital purchase models in United States hospital laboratory procurement. Third-party group purchasing organizations are consolidating negotiating leverage and unbundling service contracts from equipment financing. This behavioral shift is most visible in infectious disease screening networks where test volume commitments now determine platform selection criteria more than instrument specifications.
Global ELISA Analyzer Market Segmentation
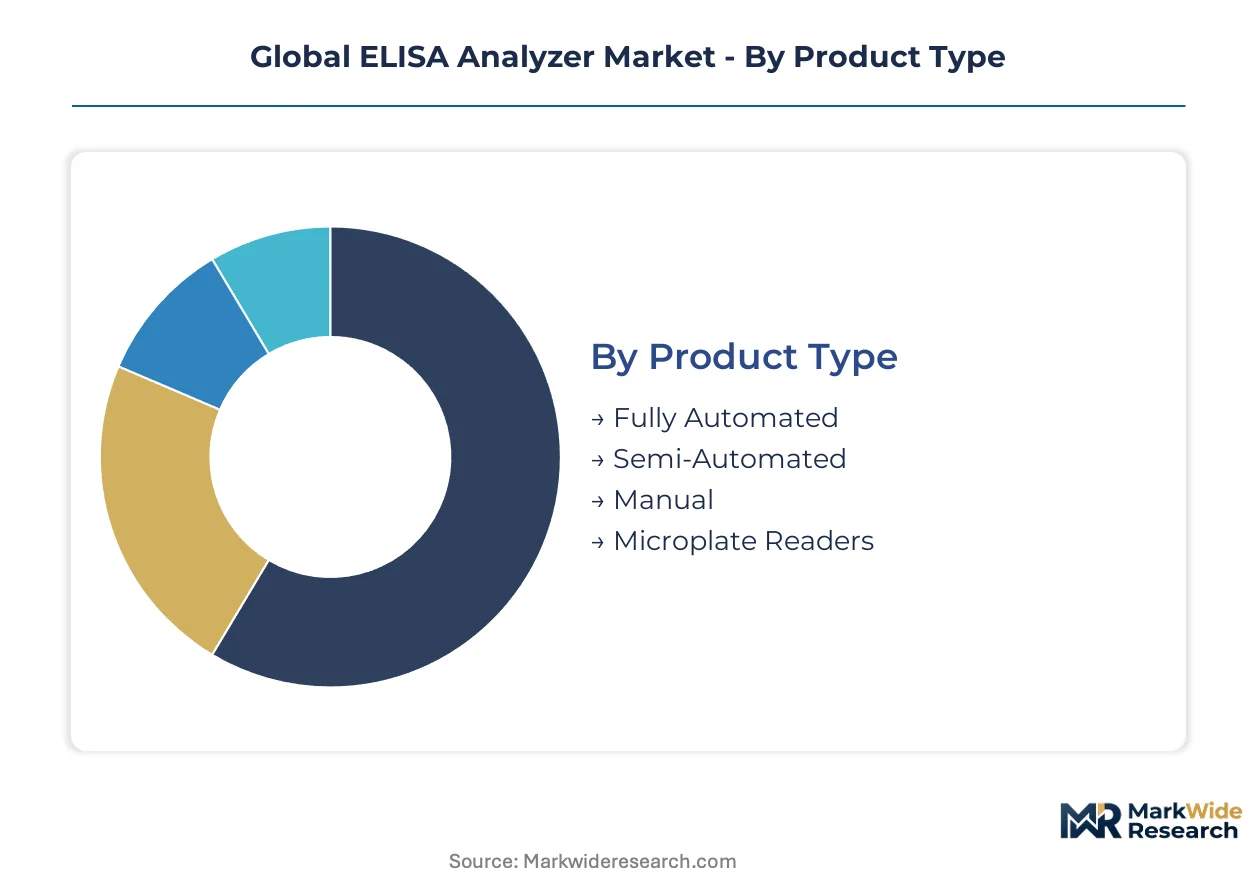
Analyzer configuration determines capital deployment patterns and service revenue potential across laboratory networks. Procurement decisions hinge on throughput requirements, detection sensitivity needs, and regulatory compliance burdens that vary sharply by end-use setting.
Product Type:
Margin pools concentrate in fully automated systems where reagent-locked consumables generate recurring revenue streams exceeding instrument hardware margins.
- Fully Automated:Integrated walkaway systems process 96 to 1,536 wells per cycle with robotic liquid handling and automated plate washing. United States reference laboratories prioritize these platforms for infectious disease screening networks under FDA 510(k) clearance requirements.
- Semi-Automated:Partial automation retains manual plate loading while automating detection and data capture. Mid-volume clinical laboratories in Germany select these configurations to balance throughput with capital constraints during EU IVDR transition periods.
- Manual:Benchtop photometric devices require operator intervention for all processing steps. Research laboratories with low sample volumes and academic budget limitations sustain residual demand.
- Microplate Readers:Modular detection engines accept multiple plate formats and detection modes. Contract research organizations deploy these for assay development flexibility across vaccine and drug discovery workflows.
Fully automated systems hold installed capacity in high-throughput networks. Semi-automated configurations are rotating up the share rankings as mid-tier laboratories defer full automation investments.
Technology:
Detection chemistry determines sensitivity thresholds and reagent cost structures that shape laboratory operating economics.
- Chemiluminescent:Enzyme-triggered light emission achieves picogram-level detection limits with extended dynamic range. Hormone and tumor marker assays in United States hospital laboratories are migrating to this modality for superior diagnostic precision.
- Colorimetric:Chromogenic substrate conversion produces absorbance signals proportional to analyte concentration. Routine infectious disease panels in resource-constrained settings retain this established methodology.
- Fluorescent:Excitation-emission wavelength pairs enable multiplexed detection and reduced background interference. Academic research institutes leverage this sensitivity for low-abundance protein quantification.
- Electrochemical:Current or impedance changes at functionalized electrodes transduce binding events without optical components. Point-of-care developers in India explore this miniaturization pathway for decentralized diagnostics.
Chemiluminescent detection is climbing the fastest as clinical laboratories upgrade sensitivity specifications. Colorimetric methods retain volume leadership in emerging market installations.
Application:
Assay volume and reimbursement rates create divergent profitability profiles across testing categories.
- Infectious Diseases:High-frequency screening for HIV, hepatitis, and respiratory pathogens dominates hospital laboratory throughput. China's NMPA-registered reference laboratories are scaling centralized testing networks for population-level surveillance.
- Vaccine Development:Immunogenicity and potency assays require standardized quantification across clinical trial phases. Contract research organizations in Germany command premium pricing for GLP-compliant analytical support.
- Drug Discovery:High-content screening and lead optimization generate massive microplate processing volumes. Pharmaceutical companies prioritize multi-mode reader flexibility over dedicated ELISA specificity.
- Food Safety Testing:Pathogen and allergen detection in production environments demands ruggedized instrumentation. Regulatory laboratories under EU food safety frameworks specify validated detection protocols.
Infectious disease applications anchor installed base utilization. Vaccine development workflows are gaining share fastest as pandemic preparedness funding sustains analytical capacity expansion.
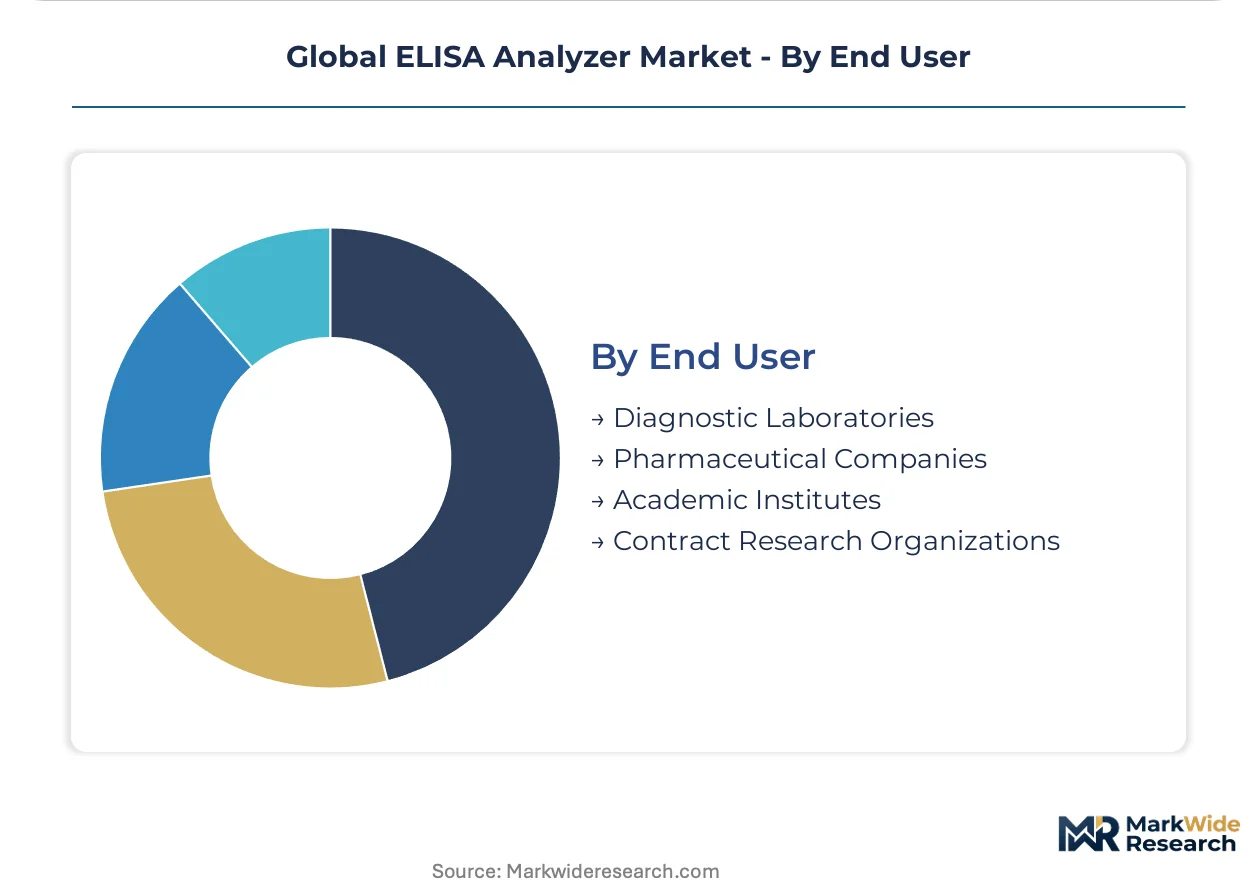
End User:
Capital access and procurement authority determine pricing power and contract structure across customer categories.
- Diagnostic Laboratories:Centralized testing facilities process thousands of samples daily with automated workflow integration. United States health system consolidation is concentrating purchasing authority among multi-site laboratory networks.
- Contract Research Organizations:Outsourced analytical services demand premium instrument configurations with rapid turnaround guarantees. Vaccine developers in Germany and the United States source GLP-validated platforms through service agreements.
- Pharmaceutical Companies:In-house quality control and clinical trial support require compliant documentation and audit trails. Multi-site standardization drives enterprise-wide platform selection.
- Academic Institutes:Research funding cycles and publication priorities shape capital equipment acquisition. Shared core facilities maximize instrument utilization across departmental boundaries.
Diagnostic laboratories command the deepest installed base. Contract research organizations are rotating up the share rankings as biopharmaceutical outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways and EU IVDR implementation are accelerating analyzer replacement cycles across major diagnostic markets. Laboratory consolidation in the United States, Germany, and China is concentrating procurement authority within centralized reference networks.
United States
Hospital system consolidation is funneling diagnostic spending into multi-site laboratory networks with standardized automation platforms. FDA 510(k) premarket notification requirements extend validation timelines for new analyzer entrants, elevating capital barriers. The Boston-Cambridge corridor anchors vaccine development analytical capacity with GLP-compliant contract research infrastructure.
Germany
EU IVDR mandates are compelling clinical laboratories to replace legacy instrumentation with CE-marked compliant platforms. Germany's national pharmaceutical regulator enforces enhanced performance validation protocols that reshape competitive access. The Rhine-Main cluster around Frankfurt concentrates diagnostic OEM headquarters and precision optical component supply chains.
China
NMPA medical device registration pathways require in-country testing that sequences market access for multinational manufacturers. Centralized reference laboratory expansion under population health surveillance programs concentrates procurement authority. Beijing and Shanghai host domestic analyzer assembly operations serving tier-one hospital networks.
Japan
PMDA quality management system requirements filter institutional procurement toward ISO 13485-certified vendors. METI industrial policy supports precision manufacturing capabilities for photomultiplier tube and optical filter production. The Kansai region around Osaka maintains specialty component fabrication for analytical instrument supply chains.
India
CDSCO medical device registration is formalizing import pathways for automated diagnostic platforms. Primary care clinic networks present installation potential for compact cartridge-based systems bypassing reference laboratory bottlenecks. Maharashtra's Mumbai-Pune corridor anchors domestic diagnostic distribution and service infrastructure.
Global ELISA Analyzer Market Competitive Landscape
Player mix skews toward diversified life science conglomerates with integrated reagent-instrument ecosystems. Market structure concentrates around three strategic archetypes: full-system automation vendors, specialized detection technology developers, and multi-modal platform diversifiers. Consolidation pressure intensifies as diagnostic laboratories prioritize single-source procurement relationships. Competitive moves center on reagent-locked consumable strategies and cloud-connected service model deployment.
Within the full-system automation tier, Thermo Fisher Scientific and Danaher Corporation exemplify the integrated ecosystem approach that sustains installed-base loyalty across high-throughput clinical networks. Bio-Rad Laboratories occupies a position among specialized detection architects whose microplate configurations dominate research and vaccine development settings. These three entities anchor competitive positioning through distinct value propositions: reagent pull-through economics, walkaway automation throughput, and research-grade analytical flexibility respectively.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Danaher Corporation |
| PerkinElmer Inc. |
| Agilent Technologies |
| Tecan Group Ltd. |
| Merck KGaA |
| Siemens Healthineers |
| DiaSorin S.p.A. |
| Others |
Supply & Pricing Matrix
Chemiluminescent detection module substitution for legacy colorimetric architectures simultaneously redraws component sourcing maps toward German and Japanese optical specialists and compresses margin structures for mid-tier analyzer assemblers unable to absorb precision photonics premiums.
Pricing Analysis
Certification level (ISO 13485/CE-IVDR/FDA-grade) creates the primary spread between analyzer tiers, with fully automated platforms commanding substantial premiums over semi-automated configurations due to validation documentation burdens. Three-tier pricing structure across premium, standard, and economy levels stratifies procurement pools, with United States hospital systems least price-sensitive given bundled reagent contracts and Indian primary care clinics most responsive to capital outlay constraints. Pricing pressure stems from group purchasing organization consolidation unbundling service contracts from hardware financing. Diagnostic laboratories in China exhibit intermediate sensitivity, balancing NMPA registration requirements against reference laboratory network standardization mandates.
Supply Chain Analysis
Photomultiplier tube fabrication chokepoints in Japan's Kansai industrial corridor and precision filter manufacturing concentration around Germany's Rhine-Main cluster tether analyzer assembly to dual-source vulnerability for core optical components. Photomultiplier tubes, interference filters, and robotic liquid handling modules draw from specialty suppliers in Japan, Germany, and Switzerland. Single-source vulnerability intensifies as REACH amendments restrict substrate materials, forcing extended supplier qualification timelines. Distribution runs through diagnostic OEM direct sales forces and third-party group purchasing organizations serving consolidated United States hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection arrives as cloud-connected service models decouple recurring revenue from reagent pull-through, creating interoperability standards battles between integrated ecosystem vendors and modular detection specialists.
For Market Incumbents: Secure reagent-locked installed base loyalty through predictive maintenance subscriptions that reduce customer switching costs for competing platforms. Consolidate middleware development capabilities to accelerate hospital information system integration timelines that currently delay installation acceptance. Vertical integration into precision optical component sourcing mitigates photomultiplier tube supply disruption risks from Japanese specialty manufacturers. For New Entrants and Emerging Players: Cloud-connected remote monitoring service gaps among legacy installed bases present white-space entry points for subscription-based predictive maintenance offerings. Target underpenetrated primary care clinic networks in India with compact cartridge-based systems bypassing centralized reference laboratory bottlenecks. Pursue veterinary diagnostics channel partnerships in Germany and the United States where companion animal healthcare networks adopt human-clinical platform architectures without equivalent service coverage. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract research organization service providers seeking analyzer fleet standardization to support GLP-compliant vaccine development workflows. Long-term viability hinges on reagent-consumable recurring revenue attachment rates rather than hardware shipment volumes. Monitor FDA 510(k) clearance backlog durations as inflection indicator for new platform commercialization velocity and competitive entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU IVDR compliance accelerates replacement cycles among European clinical laboratories seeking validated instrumentation. |
| Reagent Rental Program Expansion | Instrument placement models displace capital purchases in United States hospital procurement, locking in consumable commitments. |
| Cloud-Connected Service Deployment | Remote monitoring subscriptions create recurring revenue streams independent of assay volume fluctuations. |
| Precision Optics Backward Integration | Captive photomultiplier tube supply chains mitigate single-source vulnerability from Japanese specialty manufacturers. |
| Veterinary Diagnostics Platform Adaptation | Companion animal healthcare networks in Germany and the United States adopt human-clinical analyzer configurations. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with diagnostic laboratory directors, biomedical engineers, hospital purchasing committee members, and group purchasing organization contract managers; and secondary validation against FDA 510(k) filings, NMPA registration databases, EU IVDR notified body certificates, and ISO 13485 audit records. Bottom-up instrument shipment modeling triangulated against top-down reagent consumable revenue analysis.
Across the analysis window, projections incorporate product type segmentation (fully automated, semi-automated, manual, microplate readers), detection technology tiers (chemiluminescent, colorimetric, fluorescent, electrochemical), and end-user concentration patterns (diagnostic laboratories, contract research organizations, pharmaceutical companies, academic institutes). CAGRs derive from replacement cycle dynamics, regulatory transition timelines, and centralized laboratory network expansion trajectories. Forecast inputs include photomultiplier tube supply constraints and REACH amendment compliance costs.
Forecasts assume regulatory continuity in FDA 510(k), EU IVDR, and NMPA pathways; material policy shifts would require re-modeling commercialization timelines and geographic launch sequencing. Practitioners should keep alternative scenarios live as optical component supply concentration and group purchasing organization consolidation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Rapid Medical Diagnostic Kits Market
Medical Diagnostics
Global Circulating Tumor Cells Market
Medical Diagnostics
Protein Sequencing Market
Medical Diagnostics
AI in Medical Diagnostics Market
Medical Diagnostics
North America Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
X Ray Crystallography Market
Medical Diagnostics
Asia-Pacific Single Cell Analysis Market
Medical Diagnostics
Karyotype Analysis Service Market
Medical Diagnostics
MUC1 Antibody Market
Medical Diagnostics
Dosimetry Market
Medical Diagnostics
US Molecular Diagnostics Market
Medical Diagnostics
Magnetic Resonance Analyzer Market
Medical Diagnostics
Medical Isotope Market
Medical Diagnostics
Europe Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
Middle East and Africa Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
In-Situ Hybridization (ISH) Market