
 Cellular Pathology Market | 2026-2036
Cellular Pathology Market Size, Share, and Industry Trends Forecast 2026-2036
Cellular Pathology Market Outlook
Digital whole-slide imaging coupled with artificial intelligence-assisted analysis is reconfiguring how diagnostic workflows operate in cellular pathology laboratories. Danaher Corporation leverages its life sciences instrumentation portfolio to anchor automated staining and imaging platforms across major diagnostic networks. F. Hoffmann-La Roche AG sustains competitive positioning through specialized immunohistochemistry assay development. Thermo Fisher Scientific competes by extending its histology reagent and consumables reach into research and clinical segments.
Cellular pathology encompasses the microscopic examination of tissue samples to identify disease states, employing formalin-fixed paraffin-embedded processing, hematoxylin and eosin staining, and antibody-based detection methods to render cellular morphology visible for diagnostic interpretation. Its primary commercial purpose centers on enabling definitive cancer diagnosis, infectious agent identification, and inflammatory condition characterization that guides therapeutic selection. Immunohistochemistry technology leads current revenue generation due to established reimbursement and broad oncology application, while digital pathology represents the fastest-expanding segment as laboratories pursue remote consultation capabilities and algorithmic quality assurance. Biopsy devices constitute a mature hardware category where margin pools increasingly concentrate in disposable needle systems rather than capital equipment.
FDA oversight of laboratory-developed tests and CLIA quality standards shape validation requirements for new cellular pathology platforms entering the United States market, while the EU In Vitro Diagnostic Regulation enforces stricter performance documentation and notified body certification across European Economic Area countries. The FDA's premarket notification pathway for digital pathology devices creates specific evidence thresholds that influence R&D allocation and commercialization timelines for manufacturers. Stakeholders must monitor evolving reimbursement policies for digital pathology services and artificial intelligence-augmented diagnosis as these determinations will dictate adoption velocity and capital deployment priorities across health systems.
Market Dynamics
Digital pathology adoption is compressing diagnostic turnaround times while artificial intelligence-assisted analysis reshapes labor allocation in cellular pathology laboratories. This structural shift forces capital deployment toward integrated imaging platforms and algorithmic quality assurance systems.
Growth Catalysts
- EU In Vitro Diagnostic Regulation:Stricter performance documentation requirements accelerate platform upgrades across European Economic Area countries, driving replacement demand for compliant staining and imaging systems.
- Hospital network consolidation:Large health systems in Germany mandate standardized digital pathology infrastructure, creating volume commitments for automated slide processing equipment.
- Artificial intelligence-assisted diagnosis:Algorithmic quality assurance tools reduce pathologist review burden, expanding remote consultation capabilities and enabling centralized diagnostic hubs.
Market Restraints
- Capital equipment intensity:Whole-slide imaging scanners and automated staining platforms require substantial upfront investment, limiting adoption among independent pathology practices.
- Reagent supply concentration:Specialized immunohistochemistry antibodies and detection chemistries concentrate among limited specialty chemical suppliers, creating input cost volatility.
- FDA premarket notification pathway:Digital pathology device validation requirements extend commercialization timelines and elevate evidence-generation costs for manufacturers targeting the United States.
Strategic Opportunities
- Underpenetrated community pathology:Smaller laboratories in the United States remain reliant on manual slide review, presenting conversion potential for cloud-based digital pathology services.
- Technology convergence:Integration of multiplex immunofluorescence with computational pathology enables spatial biomarker profiling for precision oncology applications.
- India's healthcare digitization:National health stack initiatives and diagnostic network expansion create demand for affordable digital pathology infrastructure in tier-2 and tier-3 cities.
Industry Challenges
- Computational pathology expertise gap:Shortage of pathologists trained in algorithm validation and digital workflow management constrains effective technology deployment.
- Legacy system integration friction:Laboratory information system interoperability gaps complicate data exchange between digital pathology platforms and hospital electronic health records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellular Pathology Market |
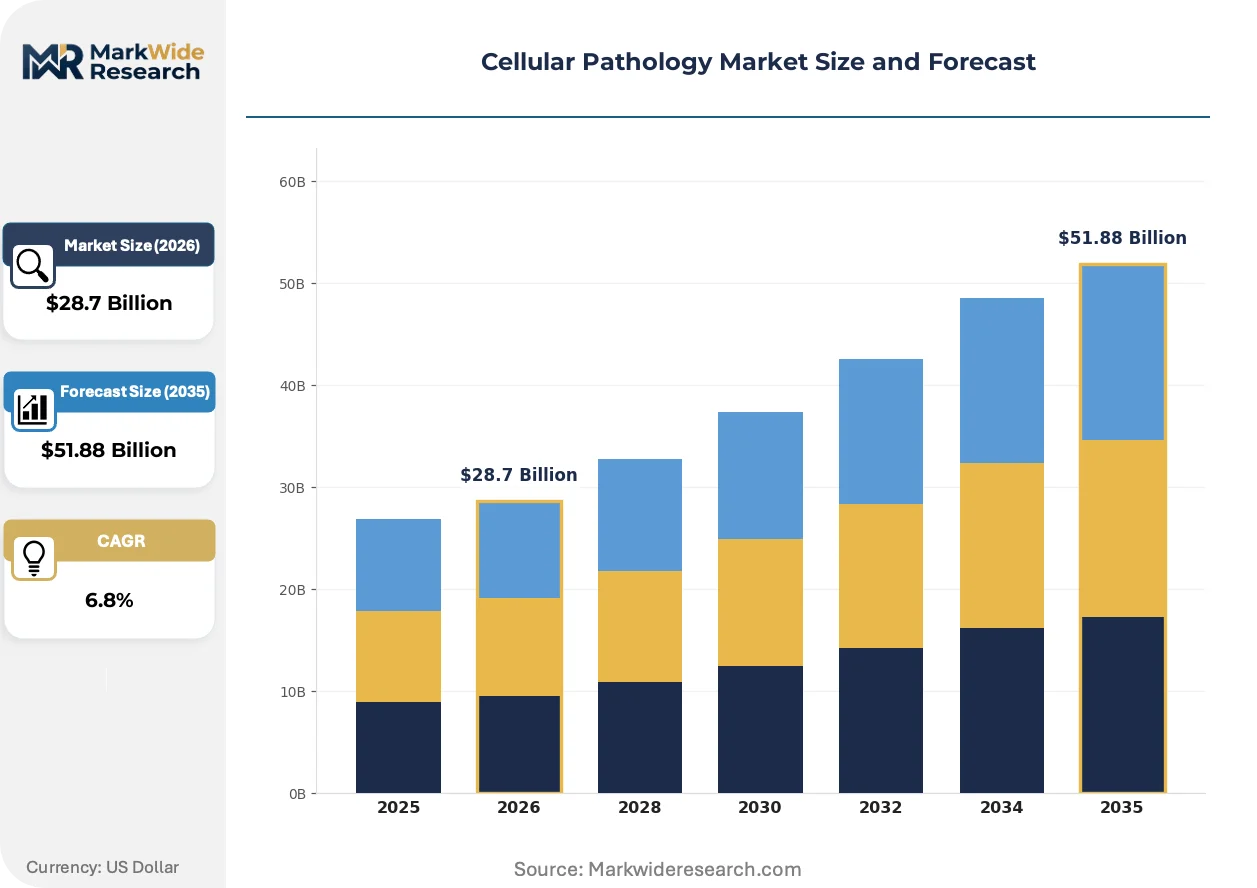
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biopsy Devices, Staining Products, Imaging Systems, Slide Preparation Equipment Technology: Digital Pathology, Immunohistochemistry, In Situ Hybridization, Histological Techniques End User: Hospitals, Diagnostic Laboratories, Research Institutes, Pharmaceutical Companies Application: Cancer Diagnosis, Infectious Disease, Inflammation Assessment, Genetic Testing |
| Companies Covered | Danaher Corporation, F. Hoffmann-La Roche AG, Thermo Fisher Scientific, Philips Healthcare, Agilent Technologies, Merck KGaA, PerkinElmer, Bio-Rad Laboratories, Sysmex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellular Pathology Market Strategic Shifts
Diagnostic workflows are fragmenting across physical and virtual environments as computational tools embed deeper into tissue analysis. This transformation compresses traditional skill hierarchies and reconfigures value capture toward software-enabled service models.
Multiplex immunohistochemistry is migrating from research-exclusive applications into clinical diagnostic protocols. Academic medical centers in the United States and Germany now deploy seven-color and nine-color panels for tumor microenvironment characterization. This migration from single-marker to spatial profiling compresses the number of tissue sections required per case, reducing specimen consumption while expanding reimbursable information content per biopsy.
REACH chemical restrictions and the EU Green Deal sustainability mandates are reshaping histology reagent formulations. Manufacturers reformulate xylene substitutes and paraffin alternatives to eliminate substances of very high concern from processing workflows. European pathology laboratories face the most immediate compliance deadlines, accelerating supplier qualification cycles for greener staining and embedding chemistries.
Pathology groups now unbundle diagnostic interpretation from technical slide preparation, creating distinct contracting relationships for each service component. Health systems in Germany and the Netherlands separately procure slide digitization, algorithmic pre-screening, and specialist sign-out through distinct vendor arrangements. This unbundling is most advanced where national tariff structures permit itemized reimbursement for digital workflow elements.
Cellular Pathology Market Segmentation
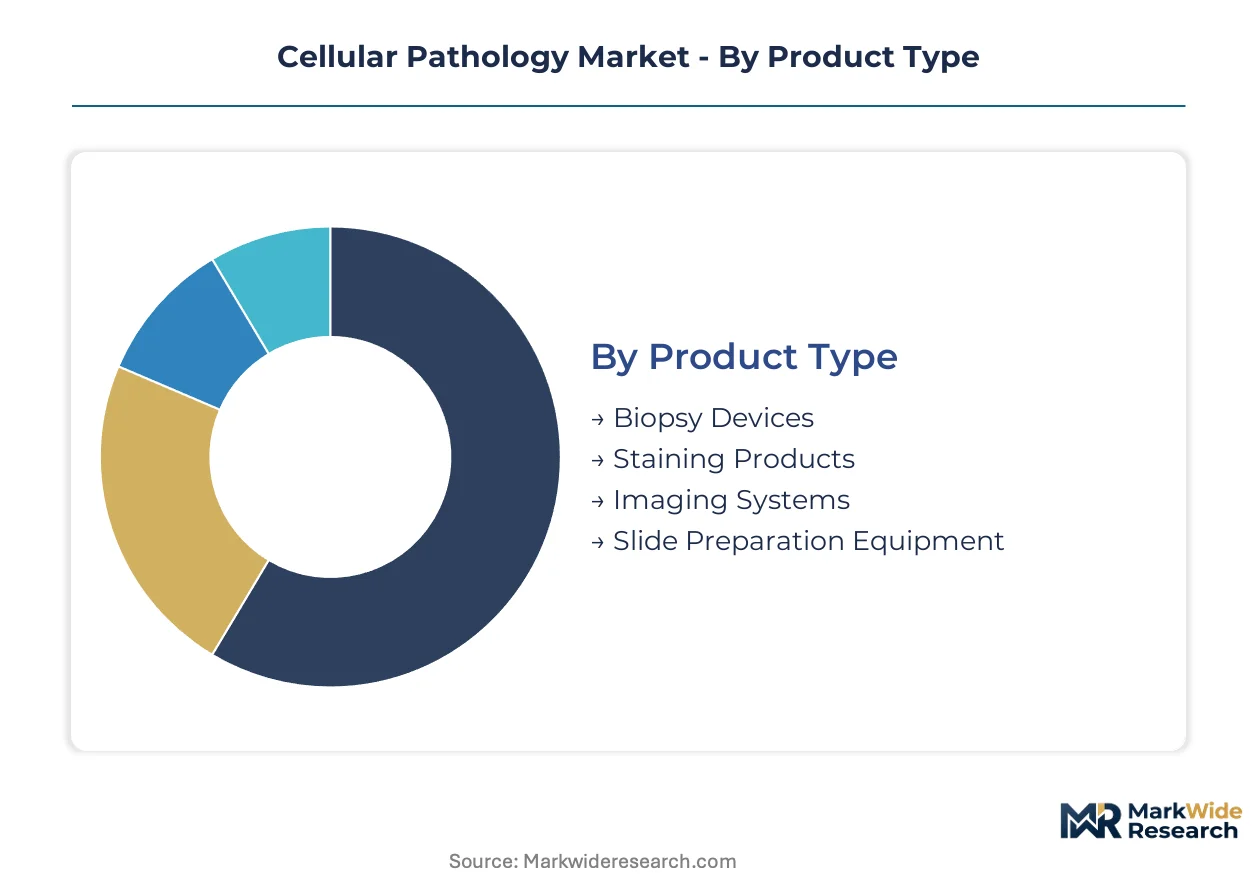
Segmentation in cellular pathology reveals distinct equipment lifecycles and technology refresh rates. Staining consumables turn over monthly while imaging platforms persist for seven to ten years, creating divergent competitive dynamics and vendor engagement models across product categories.
Product Type:
Replacement cycles vary dramatically across this category, from single-use biopsy needles to decade-long imaging system deployments.
- Biopsy Devices:Disposable needle systems and core biopsy instruments designed for tissue extraction. Demand concentrates in hospital outpatient departments across the United States and Germany, driven by screening program expansion and minimally invasive procedure preference.
- Staining Products:Hematoxylin and eosin reagents, specialized antibodies, and detection chemistries that render cellular structures visible. Diagnostic laboratories in Germany consume volume through national digitization mandates requiring standardized slide preparation quality.
- Imaging Systems:Whole-slide scanners and integrated microscopy platforms capturing high-resolution tissue images. Research institutes in the United States deploy these for algorithmic quality assurance and remote consultation infrastructure.
- Slide Preparation Equipment:Automated tissue processors, embedding stations, and microtomes preparing formalin-fixed paraffin-embedded specimens. Pharmaceutical companies utilize these for high-throughput toxicology studies requiring consistent section quality.
Staining Products dominate installed base. Imaging Systems is where expansion concentrates.
Technology:
Cost tiers separate established manual methods from capital-intensive digital platforms requiring substantial validation investment.
- Digital Pathology:Whole-slide imaging coupled with computational analysis and remote viewing capabilities. Academic medical centers in Germany and the United States deploy these systems to enable centralized diagnostic hubs and algorithmic pre-screening workflows.
- Immunohistochemistry:Antibody-based protein detection methods using chromogenic or fluorescent visualization. Hospital pathology departments across the United States maintain high utilization through established CPT reimbursement codes for oncology marker testing.
- In Situ Hybridization:Nucleic acid probe techniques identifying specific DNA or RNA sequences within tissue architecture. Research institutes apply these for genetic aberration detection in precision oncology biomarker development.
- Histological Techniques:Conventional hematoxylin and eosin staining and special stains for morphology assessment. Diagnostic laboratories in India leverage these affordable methods for high-volume cancer screening in tier-2 and tier-3 cities.
Histological Techniques anchor routine diagnostic volume. Digital Pathology is climbing the fastest as laboratories pursue workflow automation.
End User:
Customer type determines procurement sophistication and technology adoption willingness across institutional settings.
- Hospitals:Integrated health systems performing in-house pathology with direct patient care accountability. German hospital networks mandate standardized digital infrastructure under national healthcare digitization frameworks.
- Diagnostic Laboratories:Independent and reference laboratories processing specimens from multiple healthcare providers. United States community laboratories present conversion potential for cloud-based digital pathology services amid reimbursement uncertainty.
- Research Institutes:Academic and government facilities advancing tissue analysis methodology. These institutions in the United States and Germany pioneer multiplex immunofluorescence panels for tumor microenvironment characterization.
- Pharmaceutical Companies:Drug developers requiring toxicology and biomarker support for clinical trials. These organizations demand high-throughput automated staining and imaging for companion diagnostic development.
Hospitals command capital equipment decisions. Diagnostic Laboratories represent the steepest expansion trajectory for outsourced digital services.
Application:
Maturity gradients separate well-established oncology protocols from emerging infectious disease and genetic testing applications.
- Cancer Diagnosis:Definitive malignancy identification through morphological assessment and biomarker profiling. This application consumes the majority of immunohistochemistry reagent volume in hospital pathology departments across Germany and the United States.
- Infectious Disease:Tissue-based pathogen detection for fungal, bacterial, and viral agents. Diagnostic laboratories deploy specialized stains and molecular methods where blood-based testing proves insufficient for localized infection characterization.
- Inflammation Assessment:Characterization of immune cell infiltrates and tissue damage patterns. Research institutes utilize these applications for autoimmune disease mechanism studies and therapeutic target validation.
- Genetic Testing:Tissue-based hereditary and somatic mutation analysis. Academic medical centers integrate these methods with next-generation sequencing workflows for comprehensive precision oncology profiling.
Cancer Diagnosis anchors current revenue. Genetic Testing is gaining share fastest through convergence with molecular pathology platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments and reference laboratory networks concentrate purchasing power across four major national markets. Germany's pathology digitization mandates, United States reimbursement evolution, India's diagnostic network expansion, and Japan's precision oncology infrastructure each shape distinct demand patterns.
United States
Academic medical centers in Boston and the San Francisco Bay Area deploy whole-slide imaging for algorithmic quality assurance workflows. FDA premarket notification requirements for digital pathology devices extend validation timelines for manufacturers entering this market. The Mayo Clinic and MD Anderson Cancer Center anchor centralized diagnostic hub development in Rochester and Houston respectively.
Germany
Hospital network consolidation under national healthcare digitization frameworks creates volume commitments for automated staining platforms. EU In Vitro Diagnostic Regulation enforces stricter performance documentation for platforms entering the European Economic Area. Pathology networks in Bavaria and North Rhine-Westphalia standardize digital infrastructure under federal interoperability mandates.
India
Tier-2 and tier-3 cities generate demand for affordable digital pathology infrastructure as national health stack initiatives expand diagnostic access. CDSCO regulates in vitro diagnostic imports while state governments procure equipment for public hospital networks. Maharashtra and Karnataka host the most concentrated private diagnostic laboratory expansion in Mumbai and Bangalore clusters.
Japan
Precision oncology programs at university hospitals drive multiplex immunofluorescence panel adoption for tumor microenvironment characterization. PMDA oversight shapes validation requirements for companion diagnostic platforms entering the market. The Kanto region around Tokyo and the Kansai region around Osaka concentrate the majority of academic pathology research infrastructure.
Cellular Pathology Market Competitive Environment
Channel-controlling players compete with product-specialist players for positioning in procurement decisions at consolidated hospital networks and reference laboratories. The vendor base organizes into three tiers: diversified life sciences conglomerates with full workflow portfolios, specialized diagnostics companies with assay depth, and regional equipment suppliers with service proximity advantages. Dominant competitive moves include strategic partnerships for algorithm development and geographic expansion through distribution agreements in underpenetrated community pathology segments.
Among diversified life sciences conglomerates, Danaher Corporation and Thermo Fisher Scientific exemplify the channel-control archetype through integrated instrumentation and consumables portfolios. F. Hoffmann-La Roche AG occupies a specialized position within the assay-development tier, anchoring immunohistochemistry reagent supply relationships with major diagnostic networks. These three companies represent distinct strategic postures: conglomerate breadth versus specialized depth versus integrated workflow control.
| Leading Market Players |
|---|
| Danaher Corporation |
| F. Hoffmann-La Roche AG |
| Thermo Fisher Scientific |
| Philips Healthcare |
| Agilent Technologies |
| Merck KGaA |
| PerkinElmer |
| Bio-Rad Laboratories |
| Sysmex Corporation |
| Others |
Value Chain & Pricing Dynamics
Basel's specialty chemical cluster anchors immunohistochemistry reagent production, concentrating antibody manufacturing capacity that shapes downstream pricing power for diagnostic laboratories negotiating multi-year supply agreements. Cost-plus contracts with raw material indexation dominate procurement relationships, creating pass-through volatility for hematoxylin and eosin dyes while automated staining platform vendors extract premiums through bundled service arrangements.
Pricing Analysis
Cost-plus contracts with reagent price indexation govern long-term supply agreements between antibody manufacturers and diagnostic networks. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated assay kits from research-grade reagents and bulk unlabeled antibodies. Pricing pressure stems from REACH chemical compliance costs elevating formulation expenses for European suppliers. Community pathology laboratories in the United States exhibit highest price sensitivity, while academic medical centers prioritize assay performance over unit economics.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for histology consumables manufacturers sourcing paraffin alternatives and xylene substitutes. Manufacturing concentrates in Germany, Switzerland, and the United States for high-purity reagents, while China supplies bulk chemical intermediates. Specialized immunohistochemistry antibodies draw from hybridoma cell lines and recombinant protein expression systems concentrated among limited biotechnology suppliers. Distribution runs through diagnostic distributors and direct hospital contracts, with group purchasing organizations consolidating procurement leverage for integrated health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cellular pathology is crossing into platform economics as digital workflow unbundling creates distinct monetization layers for imaging hardware, algorithmic software, and specialist interpretation services. Laboratory information system interoperability mandates in Germany and the United States are forcing vendor ecosystems toward open architecture standards that reshape competitive moats.
For Market Incumbents: Insulate installed base relationships by embedding algorithmic quality assurance tools into existing staining platform contracts, creating switching costs against cloud-native entrants. Backward integration into antibody production secures supply continuity amid CDSCO and FDA import scrutiny on Chinese-sourced reagents. Prioritize CE-IVDR certification investment to capture European replacement demand under stricter performance documentation requirements.
For New Entrants and Emerging Players: Establish a beachhead in cloud-based digital pathology services for United States community laboratories lacking capital for whole-slide imaging scanner acquisition. India's tier-2 and tier-3 diagnostic networks present conversion potential for affordable imaging infrastructure under national health stack digitization initiatives. Pursue algorithm development partnerships with academic medical centers in Boston and Houston to validate proprietary pre-screening workflows.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because diagnostic digitization mandates create sustained replacement demand for compliant platforms across Germany and the United States. Target acquisition profiles emphasize computational pathology software specialists with FDA premarket notification clearance and established hospital system integration. The signal to watch is reimbursement policy determination for artificial intelligence-augmented diagnosis codes, which will dictate capital deployment velocity across health systems.
| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVDR Certification Pathway | European Economic Area market access hinges on notified body approval for staining and imaging platforms. |
| Hospital System Partnership | German network consolidation creates volume commitments for automated slide processing equipment vendors. |
| Algorithm Development Alliance | Academic medical centers in the United States provide validation data for FDA premarket notification submissions. |
| Software Companion Development | Companion diagnostic platforms require integrated image analysis for precision oncology biomarker quantification. |
| Reimbursement Strategy | CPT code establishment for digital pathology services determines adoption velocity among United States laboratories. |
Study Parameters
Cross-validation between primary interviews with hospital pathology directors and secondary analysis of FDA premarket notification filings anchors the qualitative findings on digital pathology adoption barriers. Conversations with diagnostic laboratory procurement managers, biomedical engineers, GPO contracts specialists, and immunohistochemistry assay developers informed workflow integration challenges. Secondary sources include CMS Medicare reimbursement databases, EU In Vitro Diagnostic Regulation guidance documents, CDSCO import registration records, and hospital capital expenditure disclosures. Bottom-up segmentation modeling triangulates against top-down market sizing from instrumentation shipment data and reagent consumption patterns.
Calibration against historical adoption curves for whole-slide imaging platforms and automated staining systems shapes the projection framework across the analysis window. Segmentation dimensions include product type, technology platform, end-user institution, and application area, with geographic regulatory clusters capturing FDA, CE-IVDR, PMDA, and CDSCO pathway differences. CAGRs derive from equipment replacement cycle analysis and consumables throughput modeling per laboratory throughput tier. Industry-specific inputs incorporate EU Green Deal chemical reformulation timelines and national healthcare digitization mandate implementation schedules.
Sensitivities concentrate around reimbursement policy evolution for artificial intelligence-augmented diagnosis and laboratory-developed test regulatory classification shifts. Forecasts reflect assumptions on hospital network consolidation velocity and pathology workforce training pipeline expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
North America Flow Cytometry Market
Medical Diagnostics
Flow Cytometry Market
Medical Diagnostics
Blood Platelet Market
Medical Diagnostics
AI in Medical Diagnostics Market
Medical Diagnostics
Medical Marker Bands Market
Medical Diagnostics
North America Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
Asia Pacific Immunohistochemistry Market
Medical Diagnostics
Asia-Pacific Single Cell Analysis Market
Medical Diagnostics
Circulating Tumor Cells (Ctcs) Prognostic Technologies Market
Medical Diagnostics
Artificial Intelligence (AI) in Medical Diagnostics Market
Medical Diagnostics
Karyotype Analysis Service Market
Medical Diagnostics
Real-Time PCR, Digital PCR, and End-Point PCR Market
Medical Diagnostics
Asia-Pacific Flow Cytometry Market
Medical Diagnostics
Europe Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
Liver Biopsy Market
Medical Diagnostics
Global Complete Blood Count Device Market