
 MUC1 Antibody Market | 2026-2036
MUC1 Antibody Market Size, Share, and Industry Trends Forecast 2026-2036
MUC1 Antibody Market Insights
The FDA's Biomarker Qualification Program is broadening the cost-of-entry calculus for MUC1 antibody developers seeking diagnostic approval. Thermo Fisher Scientific leverages its global distribution network to sustain reagent supply chains across academic and clinical segments. Abcam PLC anchors its competitive stance through rigorous validation protocols and open-source citation data. Bio-Rad Laboratories differentiates via integrated instrument-antibody workflows that reduce customer protocol development time.
MUC1 antibodies are glycoprotein-targeting immunoreagents that bind the mucin-1 extracellular tandem repeat domain, typically produced through hybridoma or recombinant mammalian expression systems with protein A/G purification achieving 95% plus monomeric purity. These reagents enable cancer cell detection, circulating tumor cell isolation, and therapeutic target engagement in solid tumor indications. Monoclonal antibodies command the largest value share due to batch-to-batch consistency requirements in regulated diagnostic settings, while companion diagnostics represents the fastest-expanding product type as pharmaceutical companies co-develop therapeutics with predictive biomarker assays. Flow cytometry and immunohistochemistry dominate technology adoption, though ELISA formats retain strong positions in preclinical pharmacokinetic studies where throughput and cost efficiency matter.
FDA, EMA, and ISO 13485 standards collectively govern MUC1 antibody quality, lot release criteria, and in vitro diagnostic device registration across major markets. These frameworks elevate manufacturing documentation burdens but simultaneously filter out low-validity suppliers, concentrating procurement decisions toward vendors with established quality management systems. Stakeholders must monitor evolving companion diagnostic co-labeling requirements as oncology drug developers increasingly demand antibody reagents with demonstrated clinical analytical validity rather than research-grade performance alone.
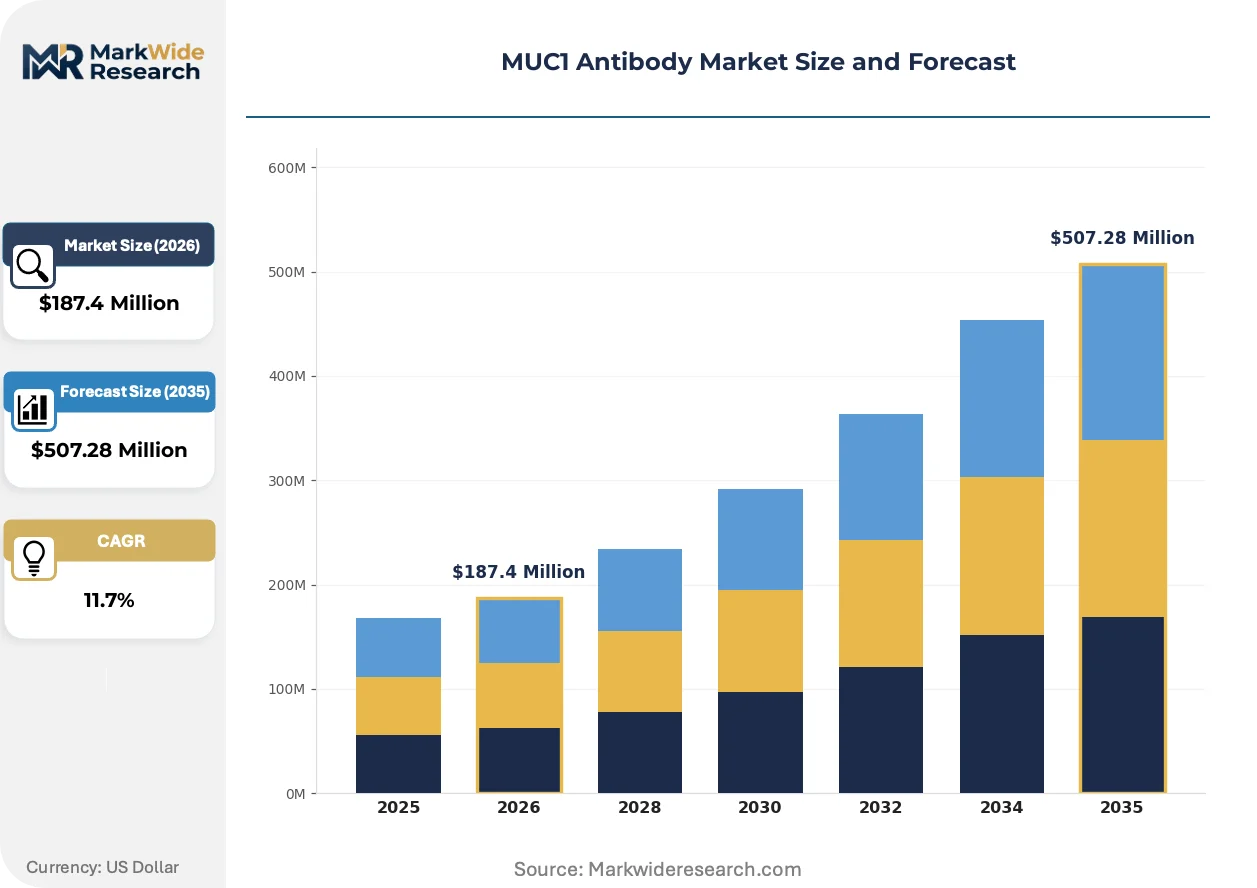
Market Dynamics
Companion diagnostic co-labeling mandates are compressing antibody validation timelines, forcing developers to front-load clinical analytical studies before therapeutic partnerships finalize.
Growth Catalysts
- FDA Biomarker Qualification Program:Streamlined qualification pathways accelerate companion diagnostic approval timelines, reducing regulatory uncertainty for MUC1 assay developers.
- Hybridoma-to-recombinant manufacturing transition:Cell line engineering advances yield higher-affinity monoclonal formats with reduced lot-to-lot variability for regulated diagnostic settings.
- Germany and Japan biomarker discovery concentration:Academic medical centers in these markets drive demand for high-specificity reagents in circulating tumor cell isolation workflows.
Market Restraints
- Protein A/G resin cost volatility:Chromatography purification media supply concentrates among three dominant chemical suppliers, exposing margin structures to input price shocks.
- ISO 13485 documentation burden:Small research-grade antibody vendors lack quality management system infrastructure to bridge into IVD-device registration pathways.
- Research-grade serum substitute availability:Fetal bovine serum supply constraints from Australia and New Zealand disrupt hybridoma culture media formulations.
Strategic Opportunities
- India CDSCO diagnostic pathway expansion:Central Drugs Standard Control Organization streamlines import licensing for reference-grade antibodies, opening access to price-sensitive clinical laboratories.
- Multiplex immunohistochemistry convergence:Spatial biology platforms integrating MUC1 with PD-L1 and HER2 markers create premium reagent bundling potential.
- Direct-to-academic distribution channels:E-procurement platforms bypass traditional distributor markups for NIH and NSF-funded research institutions.
Industry Challenges
- Cell line authentication expertise gap:Shortage of molecular biologists trained in STR profiling and mycoplasma testing delays master cell bank establishment.
- Companion diagnostic analytical validation timelines:Bridging studies demonstrating clinical concordance across antibody lots extend development cycles by months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MUC1 Antibody Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Polyclonal Antibodies, Biosimilars, Companion Diagnostics End User: Research Institutes, Hospitals, Diagnostic Laboratories, Pharmaceutical Companies Application: Cancer Immunotherapy, Biomarker Research, Diagnostic Testing, Preclinical Studies Technology: Flow Cytometry, ELISA, Western Blotting, Immunohistochemistry |
| Companies Covered | Abcam PLC, Bio-Rad Laboratories, Enzo Life Sciences, Thermo Fisher Scientific, Santa Cruz Biotechnology, Cell Signaling Technology, R&D Systems, Novus Biologicals, Proteintech Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MUC1 Antibody Market Trends and Innovations
Antibody engineering and spatial multiplexing platforms are compressing the gap between research-grade reagent discovery and clinical diagnostic deployment.
Recombinant rabbit monoclonal technology is electrifying affinity maturation workflows, yielding sub-nanomolar binding constants against MUC1 tandem repeat epitopes. Contract research organizations in Boston and Basel are adopting these formats for patient stratification studies. The technology is electrifying competitive positioning by enabling diagnostic developers to claim superior analytical sensitivity in FDA pre-submission packages.
EMA's In Vitro Diagnostic Regulation transition deadlines are forcing European distributors to reclassify antibody catalog offerings by risk class. Manufacturers must now compile technical documentation and performance data previously reserved for device-level submissions. Germany's notified body capacity constraints are creating bottlenecks for smaller reagent vendors seeking CE-IVDR certification.
Consolidated procurement through group purchasing organizations is displacing individual laboratory reagent selection autonomy. Academic medical centers in the US Northeast and California are centralizing antibody sourcing through integrated supply agreements with preferred distributors. This concentration is most visible in National Cancer Institute-designated comprehensive cancer centers where standardization protocols override principal investigator preferences.
MUC1 Antibody Market Segmentation
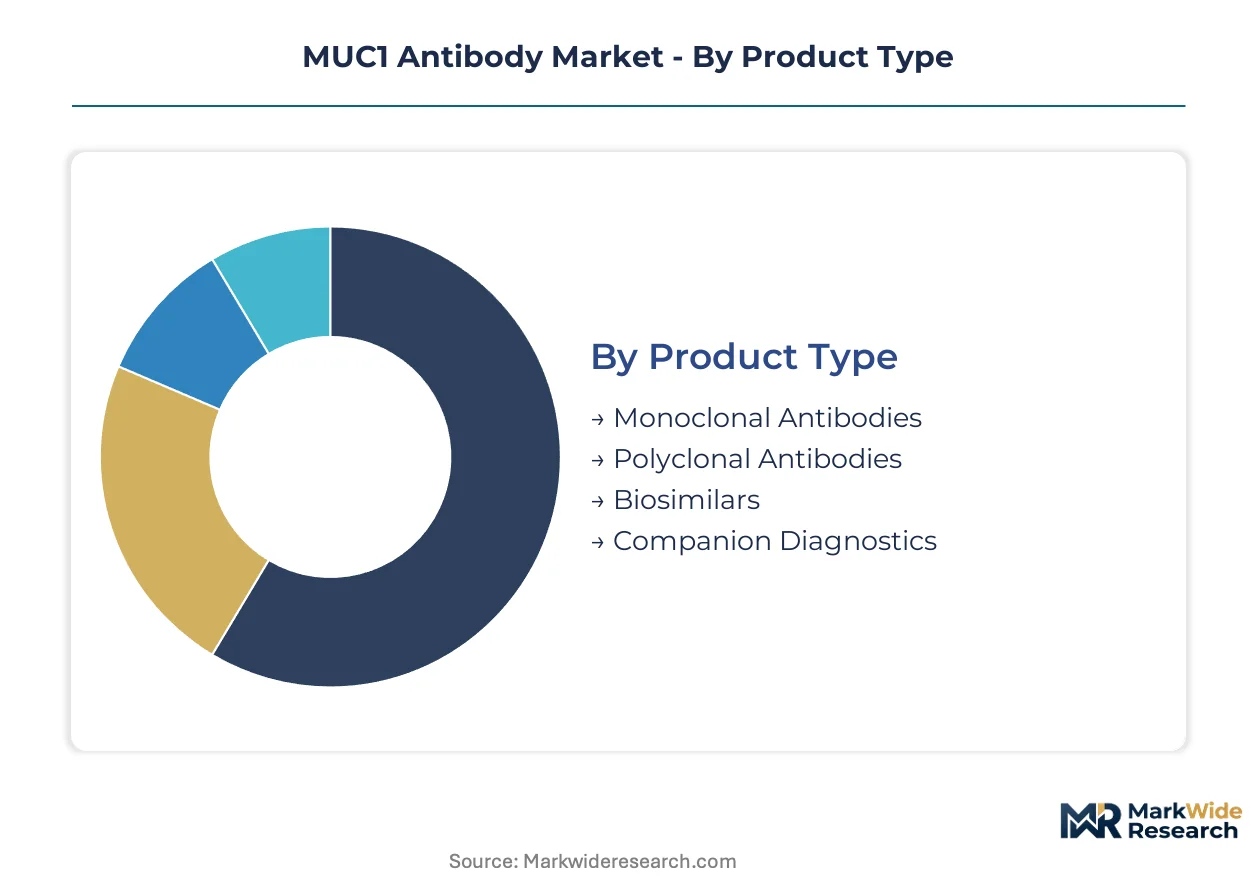
MUC1 antibody segmentation reveals distinct regulatory pathways and margin structures across product formats. Certification requirements from FDA, EMA, and ISO 13485 create tiered entry barriers that reshape competitive dynamics within each category.
Product Type:
FDA Biomarker Qualification Program and EMA IVDR implementation impose divergent documentation burdens across antibody formats, with companion diagnostics requiring device-level validation that research-grade reagents escape.
- Monoclonal Antibodies:Hybridoma-derived or recombinant mammalian formats with protein A/G purification achieve 95% plus monomeric purity. Batch-to-batch consistency commands premium positioning in regulated diagnostic settings at oncology research institutes across Germany and Japan.
- Companion Diagnostics:Predictive biomarker assays co-developed with therapeutics demand demonstrated clinical analytical validity per FDA pre-submission protocols. Pharmaceutical partnerships front-load validation timelines, compressing development cycles.
- Polyclonal Antibodies:Multi-epitope recognition profiles from immunized animal sera serve preclinical pharmacokinetic studies where cost efficiency outweighs lot consistency requirements.
- Biosimilars:Reference product equivalence demonstrations follow abbreviated approval pathways with reduced clinical trial burdens compared to novel biologics.
Leading the category by volume: Monoclonal Antibodies. Growing fastest: Companion Diagnostics.
End User:
Procurement autonomy varies sharply across customer types, with consolidated purchasing through group purchasing organizations displacing individual laboratory selection at hospital systems while academic medical centers retain principal investigator discretion.
- Research Institutes:NIH and NSF-funded institutions drive demand for open-source citation data and rigorous validation protocols. Direct-to-academic e-procurement platforms bypass traditional distributor markups.
- Diagnostic Laboratories:Clinical analytical validity requirements filter procurement toward vendors with established ISO 13485 quality management systems. National Cancer Institute-designated comprehensive cancer centers centralize sourcing through integrated supply agreements.
- Pharmaceutical Companies:Co-development partnerships for therapeutic companion diagnostics create premium reagent demand with extended validation support services.
- Hospitals:Standardization protocols override individual preferences as academic medical centers in the US Northeast and California consolidate antibody procurement.
Research Institutes capture the largest procurement volume. Diagnostic Laboratories are climbing the fastest amid tightening regulatory frameworks.
Application:
Spatial biology platform integration and multiplex immunohistochemistry convergence are redrawing application boundaries, with biomarker research and diagnostic testing increasingly overlapping in clinical deployment.
- Biomarker Research:Circulating tumor cell isolation workflows at academic medical centers in Germany and Japan concentrate demand for high-affinity monoclonal formats. PMDA and EMA qualification pathways accelerate regulatory approval.
- Cancer Immunotherapy:Patient stratification studies in Boston and Basel contract research organizations adopt recombinant rabbit monoclonal technology for sub-nanomolar binding constants against MUC1 tandem repeat epitopes.
- Diagnostic Testing:Flow cytometry and immunohistochemistry dominate technology adoption with ELISA formats retaining strong positions where throughput and cost efficiency matter.
- Preclinical Studies:ELISA formats serve pharmacokinetic assessment with reduced regulatory documentation burdens compared to clinical diagnostic deployment.
Biomarker Research holds the dominant volume position. Cancer Immunotherapy is gaining share fastest through therapeutic co-development partnerships.
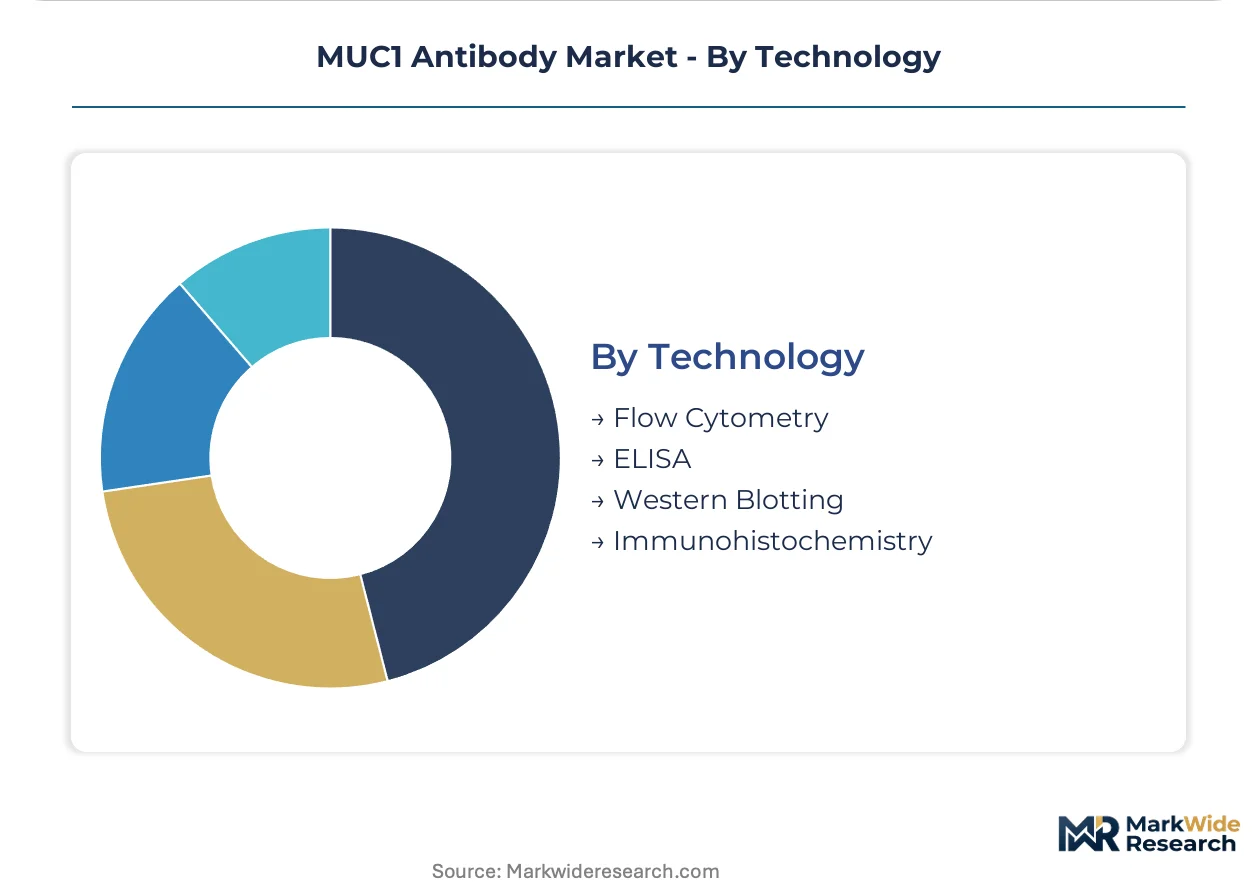
Technology:
Instrument-antibody workflow integration determines technology selection, with vendors bundling reagent supply and protocol development support to reduce customer implementation timelines.
- Immunohistochemistry:Spatial biology platforms integrating MUC1 with PD-L1 and HER2 markers create premium reagent bundling potential. Multiplex convergence compresses gap between research discovery and clinical deployment.
- Flow Cytometry:Cancer cell detection and circulating tumor cell isolation workflows demand high-specificity reagents with validated fluorophore conjugation protocols.
- ELISA:Preclinical pharmacokinetic studies favor this format for throughput and cost efficiency in regulated diagnostic settings.
- Western Blotting:Protein expression confirmation in research settings with lower regulatory validation requirements than clinical diagnostic applications.
Immunohistochemistry leads technology deployment by installed base. Flow Cytometry shows the steepest expansion trajectory through diagnostic laboratory adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oncology research institutes in the United States and Germany concentrate MUC1 antibody procurement, while Japan's academic medical centers drive demand for high-affinity monoclonal formats in circulating tumor cell isolation workflows.
United States
National Cancer Institute-designated comprehensive cancer centers anchor diagnostic laboratory procurement through consolidated supply agreements. FDA Biomarker Qualification Program streamlines companion diagnostic approval pathways, reducing regulatory uncertainty for assay developers. Boston-area contract research organizations adopt recombinant rabbit monoclonal technology for patient stratification studies.
Germany
Academic medical centers concentrate biomarker discovery workflows requiring high-specificity reagents. EMA In Vitro Diagnostic Regulation transition deadlines force reclassification of antibody catalog offerings by risk class. Notified body capacity constraints in Berlin and Munich create certification bottlenecks for smaller reagent vendors.
Japan
PMDA qualification pathways accelerate regulatory approval for circulating tumor cell isolation applications. METI funding programs support domestic antibody engineering capabilities. Tokyo and Osaka research clusters drive demand for sub-nanomolar binding formats in cancer immunotherapy patient stratification.
India
CDSCO diagnostic pathway expansion streamlines import licensing for reference-grade antibodies. Price-sensitive clinical laboratories in Delhi-NCR and Maharashtra open access for premium reagent bundling. Central Drugs Standard Control Organization reforms reduce distributor markups for academic institutions.
United Kingdom
NIH-funded research institutes leverage direct-to-academic e-procurement platforms bypassing traditional distribution channels. MHRA alignment with EMA IVDR standards elevates documentation requirements for IVD-device registration. London and Cambridge oncology clusters sustain demand for rigorous validation protocols.
MUC1 Antibody Market Competitive Landscape
United States producers anchor one tier; European specialists hold differentiated positions through regulatory compliance depth. The vendor base spans consolidated life science conglomerates with global distribution networks alongside focused antibody developers with hybridoma-to-recombinant manufacturing capabilities. Three archetypes dominate: diversified reagent conglomerates, validation-focused specialists, and integrated instrument-antibody workflow providers. Competitive moves concentrate on companion diagnostic co-development partnerships and multiplex immunohistochemistry platform integration.
Among diversified reagent conglomerates, Thermo Fisher Scientific and Bio-Rad Laboratories exemplify scale-driven positioning through global supply chain infrastructure. Abcam PLC occupies a position within the validation-focused specialist tier, representing rigorous protocol documentation and open-source citation data approaches. These three companies anchor the competitive structure, with each exemplifying distinct strategic postures toward regulatory compliance depth and customer segment specialization.
| Leading Market Players |
|---|
| Abcam PLC |
| Bio-Rad Laboratories |
| Enzo Life Sciences |
| Thermo Fisher Scientific |
| Santa Cruz Biotechnology |
| Cell Signaling Technology |
| R&D Systems |
| Novus Biologicals |
| Proteintech Group |
| Others |
Pricing and Supply Chain Analysis
ISO 13485 quality management system certification gates qualified supply access and premium-tier pricing positioning for MUC1 antibody vendors seeking diagnostic laboratory contracts. Pharmaceutical companies and National Cancer Institute-designated comprehensive cancer centers restrict procurement to certified manufacturers, concentrating pricing power among established players while research-grade suppliers compete on cost in academic segments.
Pricing Analysis
Short lead time availability commands substantial premiums in the MUC1 antibody market, with diagnostic laboratories paying elevated rates for validated lots with documented chain-of-custody records while spot inventory trades at discounts. Three-tier pricing structure across premium companion diagnostic, standard research-grade, and economy preclinical levels separates certified IVD-device reagents from hybridoma-derived batches. Pricing pressure stems from protein A/G resin cost volatility as chromatography media supply concentrates among dominant chemical suppliers. Academic medical centers exhibit highest price sensitivity due to NIH budget constraints, whereas pharmaceutical co-development partnerships demonstrate lowest sensitivity given front-loaded validation timeline requirements.
Supply Chain Analysis
Dual-sourcing requirements from FDA-regulated diagnostic laboratories mandate multi-supplier qualification for master cell banks and protein A/G resin inventories. Manufacturing concentrates in the United States, Germany, and Japan where hybridoma-to-recombinant engineering capabilities anchor production. Critical inputs encompass fetal bovine serum from Australia and New Zealand, recombinant expression vectors, and fluorophore conjugation chemistries. Single-source vulnerability in protein A/G resin supply exposes margin structures to input price shocks. Distribution runs through Thermo Fisher Scientific's global network alongside specialized life science distributors serving academic and clinical segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Notified body capacity constraints in Germany and Japan prop pricing premiums by limiting CE-IVDR certification throughput for smaller reagent vendors. Master cell bank establishment bottlenecks concentrate qualified supply among incumbents with established quality infrastructure.
For Market Incumbents: Deepen companion diagnostic co-development partnerships with oncology drug developers to secure long-term offtake commitments before EMA IVDR transition deadlines compress vendor pools. Expand recombinant rabbit monoclonal production capacity in Boston and Basel contract research organization clusters to capture patient stratification study demand. Vertical integration into protein A/G resin inventory buffers margin exposure to chromatography media price volatility from the three dominant chemical suppliers. For New Entrants and Emerging Players: Enter via CDSCO-streamlined import licensing pathways for reference-grade antibodies serving price-sensitive clinical laboratories in Delhi-NCR and Maharashtra. Target spatial biology platform integration opportunities where multiplex immunohistochemistry convergence creates premium reagent bundling potential for MUC1 with PD-L1 and HER2 markers. Leverage direct-to-academic e-procurement channels bypassing traditional distributor markups at NIH-funded research institutes. For Investors and Strategic Acquirers: FDA Biomarker Qualification Program expansion is the leading indicator that companion diagnostic validation services will command sustained premium multiples. The MUC1 antibody market presents long-term viability through therapeutic co-development partnership structures extending across the analysis window. Acquisition targets include hybridoma-to-recombinant manufacturing specialists with established ISO 13485 infrastructure and open-source citation data repositories. Monitor EMA notified body capacity utilization rates as the inflection signal for European market access tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development Partnership | Pharmaceutical companies front-load validation timelines with MUC1 assay developers for predictive biomarker assays. |
| Recombinant Rabbit Monoclonal Technology Adoption | Sub-nanomolar binding constants against tandem repeat epitopes electrify competitive positioning in FDA pre-submission packages. |
| CE-IVDR Certification Investment | EMA transition deadlines force reclassification of antibody catalog offerings by risk class in Germany. |
| Direct-to-Academic Distribution Channel | E-procurement platforms bypass traditional distributor markups for NIH and NSF-funded research institutions. |
| Multiplex Immunohistochemistry Platform Integration | Spatial biology convergence compresses the gap between research-grade reagent discovery and clinical diagnostic deployment. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this MUC1 antibody market analysis. Primary interviews with hybridoma facility directors, diagnostic laboratory procurement managers, pharmaceutical regulatory affairs leads, and academic principal investigators combined with FDA 510(k) submissions, EMA IVDR technical documentation, and ISO 13485 audit records. Bottom-up segment sizing across monoclonal, polyclonal, companion diagnostic, and biosimilar product types triangulated against top-down oncology research institute spending estimates.
Data-stream reconciliation across shipment volumes, import licensing records, and reagent catalog pricing established the analytical framework. Segmentation dimensions encompassed product format, end user archetype, application workflow, and technology platform across the projection horizon. CAGRs derived from validated lot growth rates in regulated diagnostic settings and research-grade volume expansion in academic medical centers. Forecast inputs incorporated protein A/G resin price indices and fetal bovine serum supply constraints from Australia and New Zealand.
Revisions become necessary when FDA Biomarker Qualification Program pathway modifications, EMA notified body capacity expansions, or protein A/G resin supply disruptions materialize. Deviation in companion diagnostic co-labeling mandate timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Fluorescence Cell Market
Medical Diagnostics
Asia-Pacific Single Cell Analysis Market
Medical Diagnostics
Medical Marker Bands Market
Medical Diagnostics
Medical Isotope Market
Medical Diagnostics
X Ray Crystallography Market
Medical Diagnostics
Flow Cytometry Market
Medical Diagnostics
Dosimetry Market
Medical Diagnostics
Circulating Tumor Cells (Ctcs) Prognostic Technologies Market
Medical Diagnostics
Telepathology Market
Medical Diagnostics
Global HLA Typing for Transplant Market
Medical Diagnostics
Carrier Screening Market
Medical Diagnostics
AI in Medical Diagnostics Market
Medical Diagnostics
Asia-Pacific Flow Cytometry Market
Medical Diagnostics
Global HLA Typing Market
Medical Diagnostics
Global Hydrophobic Interaction Chromatography Market
Medical Diagnostics
Liver Biopsy Market