
 Immunochromatography Kits Market | 2026-2036
Immunochromatography Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Immunochromatography Kits Market Foresight
Nitrocellulose membrane is consolidating its position as the preferred capture substrate over cellulose acetate in immunochromatography kits, cutting manufacturing costs while improving protein binding efficiency. Abbott Laboratories leverages backward integration into membrane production to secure supply continuity. Siemens Healthineers anchors its portfolio in high-sensitivity colloidal gold platforms for infectious disease panels. bioMérieux SA specializes in multiplex lateral flow architectures that differentiate its offering in European diagnostic channels.
Immunochromatography kits are diagnostic devices that employ antigen-antibody binding reactions on a porous membrane strip, typically requiring 5-15 minutes for qualitative or semi-quantitative results at the point of care. The format eliminates laboratory infrastructure demands, making it indispensable for field screening, emergency medicine, and resource-limited settings. Lateral flow assays command the largest product-type position due to their scalability in infectious disease and pregnancy testing, while rapid tests represent the fastest-expanding category as home-based diagnostics gain protocol acceptance. Among end users, diagnostic labs absorb the highest kit volumes, though hospitals are shifting procurement toward integrated point-of-care platforms that bundle immunochromatography with digital readout systems.
FDA quality-system regulation and the In Vitro Diagnostics Regulation in Europe impose stringent analytical sensitivity and clinical validation thresholds that filter market access for newer entrants. ISO 13485 certification has become a baseline procurement requirement across hospital systems and blood bank networks, compressing margins for manufacturers lacking established quality management infrastructure. Stakeholders must monitor how evolving WHO prequalification criteria for malaria and HIV rapid tests reshape competitive eligibility in low-income country tenders.
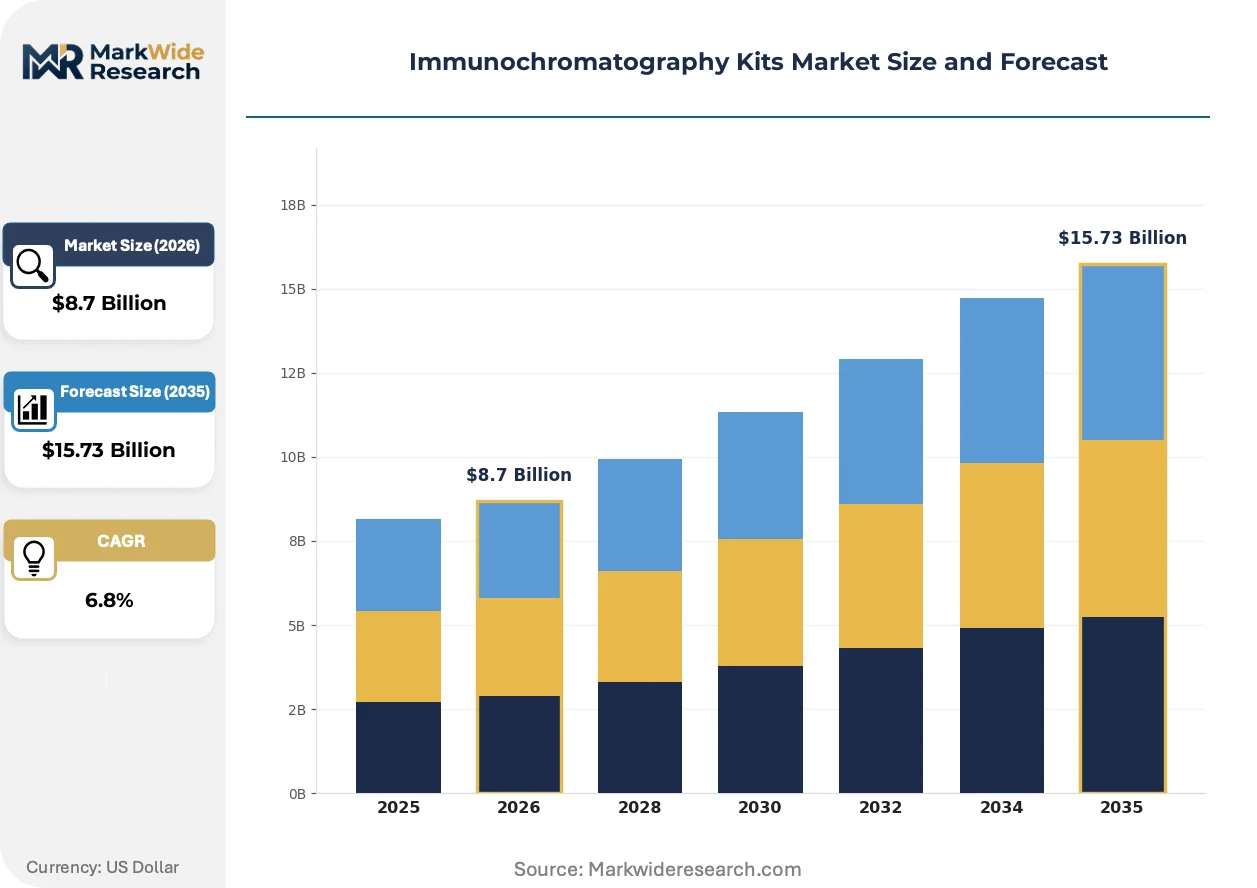
Market Dynamics
Point-of-care testing decentralization is compressing kit procurement cycles and forcing manufacturers to reconfigure distribution networks around hospital-at-home protocols and pharmacy-based diagnostics.
Growth Catalysts
- MDR compliance deadlines:European diagnostic labs are accelerating kit validation timelines ahead of IVDR transition requirements, pulling forward replacement demand for certified products.
- Colloidal gold nanoparticle enhancement:Improved sensitivity thresholds in infectious disease panels are expanding addressable test categories beyond legacy visual-read formats.
- Diagnostic lab procurement centralization:Consolidated purchasing across US health systems is standardizing kit specifications and favoring suppliers with captive membrane production.
Market Restraints
- Nitrocellulose supply concentration:Three specialized chemical manufacturers control upstream membrane substrate supply, creating input cost volatility during demand surges.
- FDA quality-system validation timelines:Extended 510(k) review periods for novel multiplex architectures delay commercialization by 12-18 months versus legacy lateral flow formats.
- Molecular PCR substitution:Polymerase chain reaction platforms are capturing share in high-accuracy infectious disease screening where laboratory infrastructure exists.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives are attracting kit assembly investments to serve WHO prequalification tenders for malaria and HIV rapid tests.
- Digital readout convergence:Smartphone camera-based quantitative analysis is creating premium pricing tiers for home-use fertility and cardiac marker panels.
- Pharmacy channel expansion:US retail clinic networks are adopting integrated point-of-care platforms that bundle immunochromatography with telehealth referral systems.
Industry Challenges
- ISO 13485 certification timelines:Emerging manufacturers face 14-18 month quality management system implementation cycles before tender eligibility in blood bank networks.
- Multiplex assay development complexity:Cross-reactivity control in lateral flow architectures demands specialized antibody engineering capabilities that concentrate among established players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immunochromatography Kits Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid Tests, Lateral Flow Assays, Dipstick Tests, Membrane Tests End User: Diagnostic Labs, Research Institutions, Hospitals, Blood Banks Application: Infectious Diseases, Allergy Testing, Drug Testing, Veterinary Diagnostics Technology: Colloidal Gold, Silver Nanoparticles, Latex Agglutination, Enzyme Immunoassays |
| Companies Covered | Abbott Laboratories, PerkinElmer Inc., Danaher Corporation, Bio-Rad Laboratories, F. Hoffmann-La Roche AG, bioMérieux SA, Becton, Dickinson and Company, Siemens Healthineers AG, Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immunochromatography Kits Market Shifts & Advancements
Fluorescent nanoparticle quantification is displacing colloidal gold in high-sensitivity applications, while regulatory convergence between FDA and IVDR frameworks is harmonizing validation standards across major markets.
Quantum dot nanocrystals are enabling single-molecule detection limits in cardiac troponin and D-dimer assays. Emergency departments in German and Japanese tertiary hospitals are piloting these platforms for 90-second turnaround protocols. This sensitivity tier is converging with machine-learning readout algorithms that standardize interpretation across operator skill levels.
IVDR's Common Specifications for Class D devices are mandating extended clinical performance studies for self-test infectious disease kits. Manufacturers must now submit analytical sensitivity data against WHO international standards rather than internal reference panels. European notified bodies are prioritizing review resources toward COVID-19 and influenza combination assays, delaying clearance timelines for tropical disease panels.
Hospital procurement committees are unbundling kit supply from analyzer maintenance contracts, forcing price transparency in previously bundled point-of-care ecosystems. US integrated delivery networks are consolidating vendor panels to three approved suppliers per test category. This concentration is most visible in Texas and Florida health systems where Medicare Advantage penetration drives capitated cost management.
Immunochromatography Kits Market Segmentation
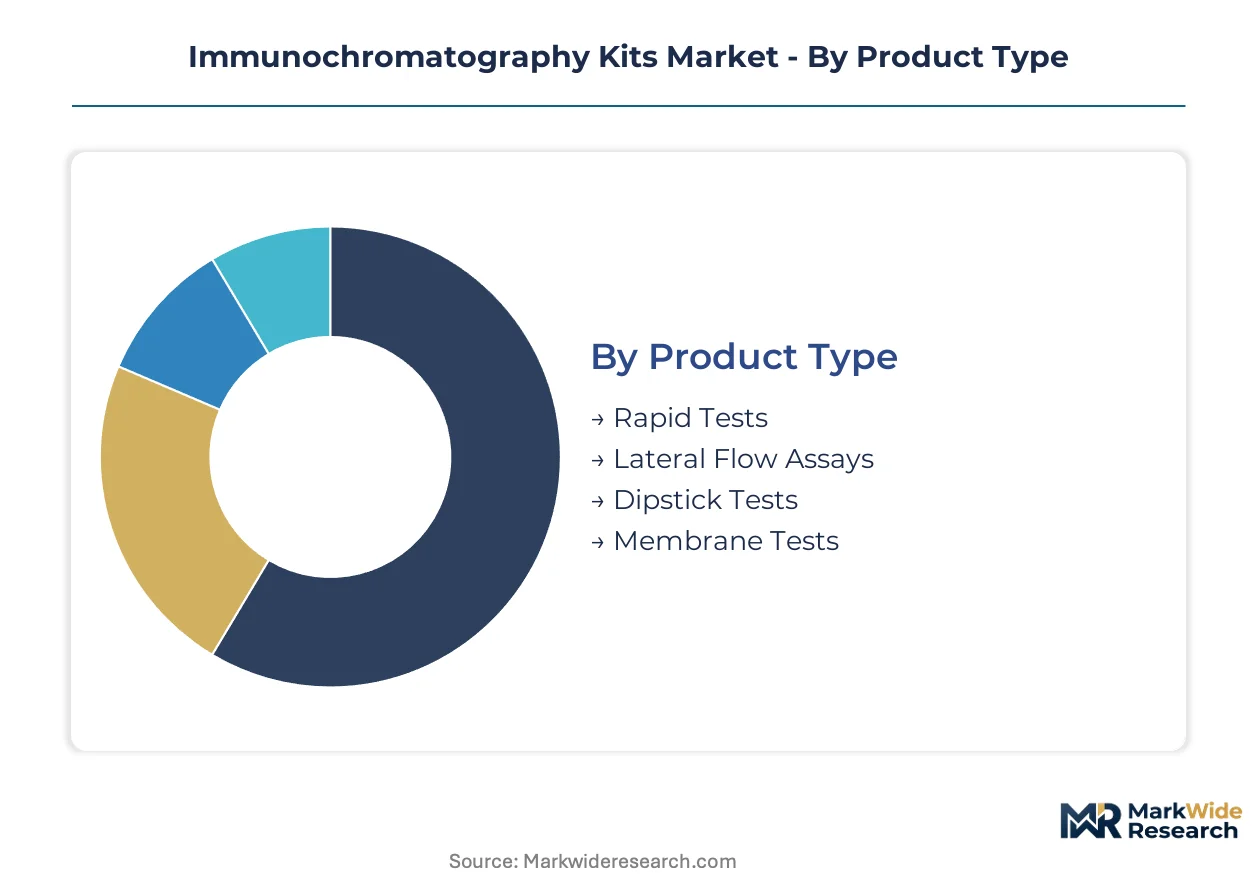
Immunochromatography kit manufacturers configure product architectures around distinct use environments, from resource-limited field settings to integrated hospital systems. Each segment demands specific sensitivity thresholds, readout formats, and regulatory documentation that reshape manufacturing priorities and margin structures.
Product Type:
Standalone single-use formats dominate decentralized testing, while embedded cartridge systems serve analyzer-integrated workflows in consolidated laboratory networks.
- Lateral Flow Assays:Nitrocellulose membrane strips with visual or instrument-read endpoints support infectious disease and pregnancy screening at scale. Diagnostic labs in the United States absorb the highest procurement volumes as hospital-at-home protocols expand point-of-care infrastructure.
- Rapid Tests:Simplified single-step formats eliminate operator training requirements for emergency medicine and pharmacy-based diagnostics. Home-use fertility and cardiac marker panels are driving premium pricing tiers through smartphone camera-based quantitative readout integration.
- Dipstick Tests:Direct immersion formats serve veterinary diagnostics and agricultural screening where laboratory infrastructure is absent.
- Membrane Tests:Customizable capture geometries enable multiplexed antibody detection in blood bank screening protocols.
Lateral Flow Assays lead volumes today; Rapid Tests are gaining share fastest through home diagnostic channel expansion.
End User:
Procurement authority concentrates in institutional buyers with centralized purchasing committees, compressing vendor panels and standardizing kit specifications.
- Diagnostic Labs:High-throughput facilities demand batch-validated kits with electronic health record connectivity and automated result logging. The United States health system consolidation is narrowing approved suppliers to three per test category in Texas and Florida integrated delivery networks.
- Hospitals:Emergency departments and outpatient clinics prioritize 5-15 minute turnaround formats that eliminate send-out delays. German and Japanese tertiary hospitals are piloting quantum dot platforms for 90-second cardiac troponin protocols.
- Blood Banks:Transfusion safety screening mandates ISO 13485 certification and extended analytical validation against WHO international standards.
- Research Institutions:Custom assay development contracts support biomarker discovery with flexible membrane chemistries and non-standard capture reagents.
Diagnostic Labs anchor current procurement volume; Hospitals are expanding fastest through point-of-care platform integration.
Application:
Disease prevalence patterns and regulatory prequalification criteria determine geographic market access and tender eligibility for each test category.
- Infectious Diseases:HIV, malaria, and respiratory panels constitute the largest addressable category with WHO prequalification requirements shaping competitive eligibility. India's PLI scheme for medical devices is attracting assembly investments to serve low-income country tenders.
- Drug Testing:Workplace and forensic screening panels require chain-of-custody documentation and adulteration detection features.
- Allergy Testing:Multiplexed allergen panels differentiate offerings in European diagnostic channels through specialized antibody engineering capabilities.
- Veterinary Diagnostics:Farm animal and companion animal screening operates outside clinical regulatory frameworks with faster validation cycles.
Infectious Diseases commands the largest revenue base; Veterinary Diagnostics is climbing the fastest as livestock health monitoring expands.
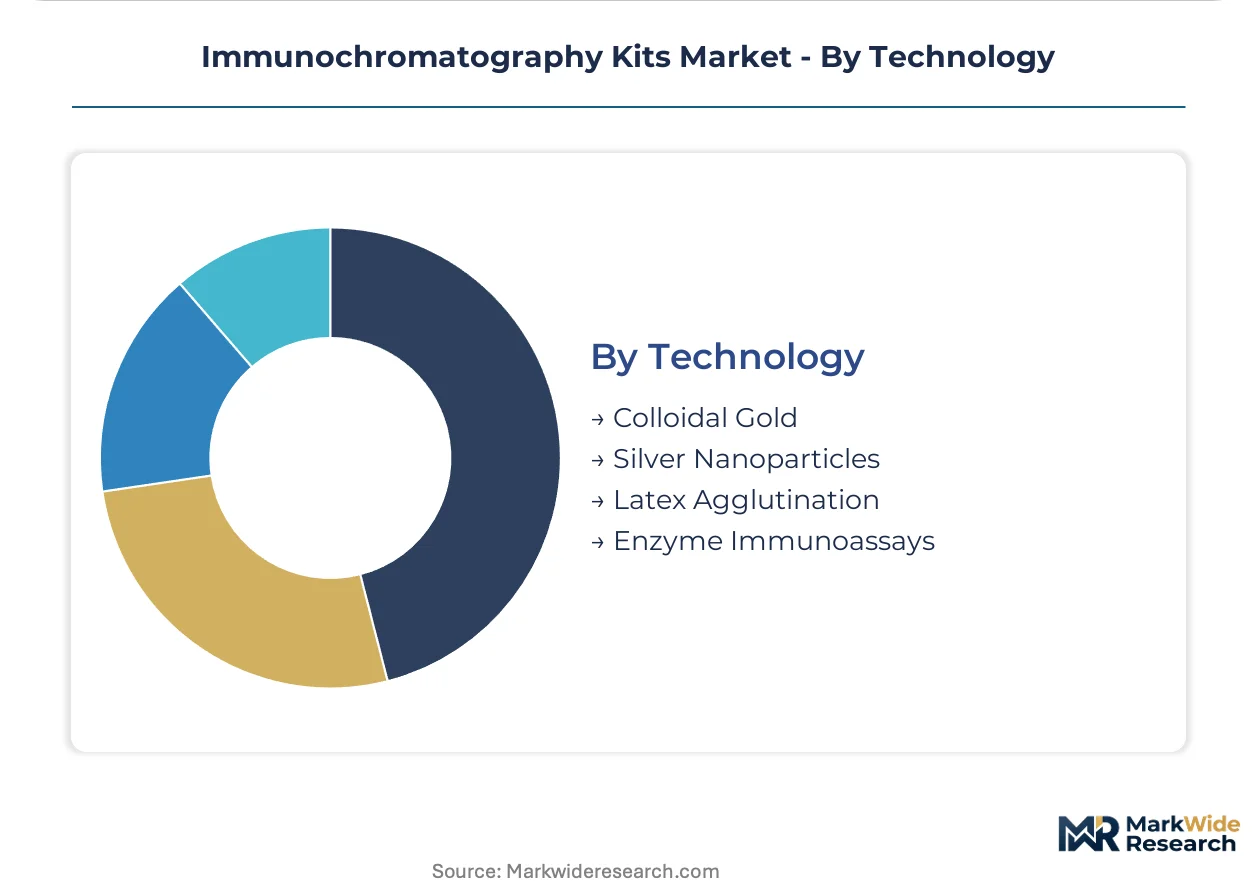
Technology:
Signal generation chemistry directly determines sensitivity thresholds, manufacturing cost structures, and compatibility with quantitative readout systems.
- Colloidal Gold:Visual-read nanoparticle formats remain the cost-optimized standard for pregnancy and infectious disease screening. Abbott Laboratories leverages backward integration into membrane production to secure supply continuity for high-volume colloidal gold platforms.
- Fluorescent Nanoparticles:Europium chelate and quantum dot formats enable single-molecule detection limits in cardiac marker and D-dimer assays. Machine-learning readout algorithms standardize interpretation across operator skill levels in emergency department deployments.
- Silver Nanoparticles:Enhanced optical density provides intermediate sensitivity for tropical disease panels in resource-limited settings.
- Latex Agglutination:Microparticle-based formats serve veterinary and agricultural applications with simplified manufacturing requirements.
- Enzyme Immunoassays:Chromogenic substrate systems support laboratory-based quantitative analysis with instrument-read endpoints.
Colloidal Gold dominates manufacturing output; Fluorescent Nanoparticles are expanding most quickly through high-sensitivity cardiac and emergency medicine applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotech corridor anchors North American immunochromatography kit development, with FDA quality-system regulation shaping validation protocols that diffuse to manufacturing sites across multiple continents.
United States
Hospital-at-home initiatives and Medicare Advantage capitation in Texas and Florida health systems are consolidating vendor panels to three approved suppliers per test category. FDA's evolving 510(k) review framework extends validation timelines for multiplex architectures by 12-18 months versus legacy formats. Abbott Laboratories maintains backward integration into membrane production from its Illinois manufacturing base to secure supply continuity.
Germany
IVDR Common Specifications for Class D devices mandate extended clinical performance studies for self-test infectious disease kits, pulling forward replacement demand ahead of compliance deadlines. German tertiary hospitals in Bavaria and Baden-Württemberg pilot quantum dot platforms for 90-second cardiac troponin turnaround protocols. Siemens Healthineers anchors its European operations from Erlangen with high-sensitivity colloidal gold platforms.
India
The PLI scheme for medical devices attracts kit assembly investments targeting WHO prequalification tenders for malaria and HIV rapid tests. CDSCO alignment with international standards accelerates domestic manufacturer access to low-income country procurement channels. Manufacturing clusters in Maharashtra and Gujarat specialize in cost-optimized lateral flow production for tropical disease panels.
Japan
PMDA harmonization with FDA validation standards reduces redundant testing for kits seeking dual-market approval, compressing commercialization cycles. METI funding for point-of-care infrastructure expansion drives adoption in rural prefectures lacking laboratory access. Tokyo and Osaka metropolitan hospitals integrate smartphone-based quantitative readout systems for home-use fertility monitoring.
United Kingdom
NHS procurement centralization standardizes kit specifications across integrated care systems, favoring suppliers with ISO 13485 certification and electronic health record connectivity. MHRA post-Brexit regulatory autonomy maintains alignment with IVDR technical standards while streamlining urgent public health authorizations. The Cambridge-Oxford-London biotech triangle hosts specialized antibody engineering capabilities for multiplex assay development.
Immunochromatography Kits Market Competitive Landscape
Global majors compete with regional champions across membrane substrate supply and point-of-care platform integration. The vendor base concentrates among diversified diagnostics conglomerates with captive manufacturing infrastructure and specialized mid-tier players with antibody engineering depth. Three archetypes dominate: integrated life science conglomerates with backward membrane production, European specialists in multiplex lateral flow architectures, and emerging Asian assemblers serving WHO prequalification tenders. Competitive dynamics center on M&A for membrane supply security and strategic partnerships for digital readout convergence.
Among diversified diagnostics conglomerates, Abbott Laboratories, Danaher Corporation, and Siemens Healthineers occupy positions defined by manufacturing scale and regulatory infrastructure breadth. Abbott exemplifies the integrated archetype through upstream membrane production control. Danaher represents the acquisition-driven consolidation pattern across life science tools. Siemens Healthineers anchors the European hospital-system integration vector with analyzer-compatible cartridge formats. These three entities sit within a tier where ISO 13485 certification and FDA master file documentation serve as baseline tender eligibility requirements rather than differentiators.
| Leading Market Players |
|---|
| Abbott Laboratories |
| PerkinElmer Inc. |
| Danaher Corporation |
| Bio-Rad Laboratories |
| F. Hoffmann-La Roche AG |
| bioMérieux SA |
| Becton, Dickinson and Company |
| Siemens Healthineers AG |
| Thermo Fisher Scientific Inc. |
| Others |
Supply & Pricing Matrix
Nitrocellulose membrane substrate costs cascade through three distinct pricing tiers as the raw material moves from German and Chinese chemical manufacturers through kit assemblers to hospital procurement committees. This input concentration amplifies cost pass-through volatility during demand surges, compressing margins for manufacturers lacking backward integration into membrane production while rewarding integrated players with pricing power in contract negotiations.
Pricing Analysis
Input-cost pass-through from nitrocellulose substrate suppliers dominates pricing formation across the value chain. Three-tier pricing structure across premium, standard, and economy levels separates quantum dot fluorescent platforms from colloidal gold visual-read formats from unbranded rapid tests for resource-limited settings. Price differentiation hinges on ISO 13485 certification grade and after-sales service bundling with digital readout systems. Pricing pressure stems from Medicare Advantage capitation in Texas and Florida health systems forcing vendor panel consolidation to three approved suppliers per category. Diagnostic labs exhibit highest price sensitivity due to centralized purchasing authority, while emergency departments prioritize turnaround speed over unit cost.
Supply Chain Analysis
ISO 13485 certification and FDA master file documentation gate entry for membrane substrate suppliers and kit assemblers alike. Manufacturing concentrates in the United States, Germany, and India, with specialized chemical production anchored in German industrial clusters and cost-optimized assembly scaling in Indian PLI-supported facilities. Raw material dependencies center on nitrocellulose membranes, colloidal gold nanoparticles, and antibody reagents sourced from a limited qualified supplier base. Single-source vulnerability in upstream membrane substrate creates supply risk during demand spikes for infectious disease panels. Distribution runs through consolidated hospital procurement committees and group purchasing organizations that standardize specifications across integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in immunochromatography kits rests on fluorescent nanoparticle premium-tier adoption and captive membrane production cost discipline. Manufacturers capturing backward integration into substrate supply and quantum dot signal chemistry simultaneously will outearn competitors trapped in commodity colloidal gold positioning.
For Market Incumbents: Anticipate molecular PCR substitution in high-accuracy infectious disease screening by accelerating quantum dot platform FDA submissions and securing exclusive membrane supply contracts before IVDR compliance deadlines tighten. Prioritize backward integration into nitrocellulose production or binding long-term offtake agreements with German chemical manufacturers to defend against input cost volatility. Channel control through integrated point-of-care platform bundling with digital readout systems protects pricing power as hospital procurement committees unbundle kit supply from analyzer maintenance contracts. For New Entrants and Emerging Players: The price-point gap between premium fluorescent cardiac marker panels and economy colloidal gold infectious disease tests creates white-space opportunity for mid-sensitivity silver nanoparticle formats in tropical disease applications. Target India's PLI scheme for medical devices to establish cost-optimized manufacturing serving WHO prequalification tenders for malaria and HIV rapid tests in low-income countries. Pursue veterinary diagnostics as the fastest-climbing application segment with faster validation cycles outside clinical regulatory frameworks and direct distribution through agricultural supply channels rather than hospital procurement committees. For Investors and Strategic Acquirers: Consolidation pressure builds where membrane substrate supply concentrates among three specialized chemical manufacturers and ISO 13485 certification timelines stretch 14-18 months for emerging players. Long-term viability favors vertically integrated manufacturers with captive nitrocellulose production and multiplex antibody engineering capabilities over pure-play assemblers dependent on qualified supplier networks. Acquisition target archetype: mid-tier European specialists in multiplex lateral flow architectures with established IVDR technical documentation and blood bank network relationships. Signal to watch: FDA 510(k) review period extension for novel multiplex architectures beyond 12-18 months versus legacy formats, indicating regulatory barrier elevation that favors incumbents with established master files.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Production | Abbott Laboratories secures supply continuity and cost discipline through captive nitrocellulose manufacturing in Illinois. |
| Quantum Dot Platform FDA Submission | Single-molecule detection limits in cardiac troponin assays command premium pricing in German and Japanese emergency departments. |
| IVDR Compliance Investment | Extended clinical performance studies against WHO international standards filter market access for self-test infectious disease kits. |
| Digital Readout Convergence Partnership | Smartphone camera-based quantitative analysis creates premium tiers for home-use fertility and cardiac marker panels. |
| India PLI Scheme Manufacturing Entry | Domestic assembly investments target WHO prequalification tenders for malaria and HIV rapid tests in low-income countries. |
Research Methodology
Direct dialogue with hospital procurement managers, GPO contracts specialists, biomedical engineers, and regulatory affairs leads at kit manufacturers grounded the qualitative foundation of this study. Secondary validation drew from FDA 510(k) filings, IVDR Common Specifications documentation, WHO prequalification assessment reports, and hospital procurement database records. Bottom-up segment sizing across product type, end user, application, and technology dimensions was triangulated against top-down macroeconomic indicators and healthcare expenditure trends.
Projected market values and growth trajectories across the modeling period reflect segment-level demand modeling incorporating point-of-care testing decentralization rates, regulatory compliance timeline shifts, and technology substitution patterns. Segmentation dimensions included lateral flow versus rapid test versus dipstick formats, diagnostic lab versus hospital versus blood bank end users, infectious disease versus cardiac marker versus veterinary applications, and colloidal gold versus fluorescent nanoparticle versus enzyme immunoassay signal chemistries. CAGRs were derived from regression analysis of historical procurement volume trends and forward projection of hospital-at-home protocol expansion and pharmacy channel adoption curves.
The model assumes a particular technology adoption path; alternative pathways for quantum dot nanocrystal platforms displacing colloidal gold in high-sensitivity applications would alter the outlook for manufacturer margin structures and competitive positioning. Forecasts reflect assumptions regarding IVDR transition timelines, FDA review period stability, and nitrocellulose substrate supply continuity that material regulatory restructuring or supply chain disruption could revise. A model refresh is warranted upon material change in WHO prequalification criteria for malaria and HIV rapid tests or Medicare Advantage capitation penetration in US integrated delivery networks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Ophthalmic Diagnostic Equipment Market
Diagnostic Devices
North America Saliva Test Devices Market
Diagnostic Devices
Contactless Vital Sign Monitoring Device Validation Test Platforms Market
Diagnostic Devices
GCC Breath Analyzer Market
Diagnostic Devices
Dual Energy X-Ray Absorptiometry Market
Diagnostic Devices
Skin Moisture Detectors Market
Diagnostic Devices
Thrombus Precursor Protein Market
Diagnostic Devices
Non-Invasive Biosensors Market
Diagnostic Devices
Ocular Allergy Diagnostic System Market
Diagnostic Devices
Breath Samplers Market
Diagnostic Devices
Portable Cancer Screen Devices Market
Diagnostic Devices
Europe Companion Diagnostics Market
Diagnostic Devices
Europe Point of Care Diagnostics Market
Diagnostic Devices
Amniotic Fluid Detection Market
Diagnostic Devices
Global Real Time Polymerase Chain Reaction Systems Market
Diagnostic Devices
Diagnostic Ophthalmic Devices Market