
 Fluid Biopsy Market | 2026-2036
Fluid Biopsy Market Size, Share, and Industry Trends Forecast 2026-2036
Fluid Biopsy Market Foresight
Digital PCR chemistries is restructuring cost profiles across sample preparation workflows. Guardant Health leverages comprehensive genomic profiling to anchor its position in treatment selection. Thermo Fisher Scientific dominates reagent supply chains through backward integration into nucleic acid extraction. QIAGEN specializes in companion diagnostic partnerships that extend regulatory co-approval pathways.
Fluid biopsy denotes isolation and molecular characterization of circulating biomarkers from peripheral blood, operating through centrifugation, immunomagnetic enrichment, or membrane filtration to achieve analytical sensitivity down to single-molecule detection. Its primary purpose enables real-time tumor genotyping without tissue invasion, supporting serial monitoring during therapy. Circulating tumor DNA commands the largest revenue share due to established clinical utility in EGFR and KRAS mutation tracking. Next-generation sequencing represents the fastest-expanding technology segment as panel breadth expands from 50 to 500+ genes. Microfluidics occupies a niche but growing position where point-of-care deployment demands miniaturized sample-in-answer-out architectures.
The FDA oversees premarket approval for liquid biopsy companion diagnostics under its in vitro diagnostic framework, while the EMA's IVDR transition in Europe imposes stricter performance documentation for CE-marked kits. ISO 13485 quality management systems and CAP laboratory accreditation shape operational compliance for diagnostic laboratories processing clinical samples. Stakeholders must monitor evolving payer coverage policies as Medicare's MolDX program evaluates evidence thresholds for multi-cancer screening reimbursement.
Market Dynamics
Medicare's MolDX program is recalibrating reimbursement thresholds for multi-cancer early detection tests, compressing commercialization timelines and forcing assay developers to front-load clinical evidence generation.
Growth Catalysts
- Companion Diagnostic Pathway:The FDA's liquid biopsy companion diagnostic framework accelerates co-approval timelines for oncology therapeutics, enabling parallel market entry of targeted drugs and matching diagnostics.
- Digital PCR Workflows:Droplet-based digital PCR chemistries are restructuring cost profiles across sample preparation, reducing per-sample reagent consumption while preserving single-molecule sensitivity.
- Oncology Clinic Concentration:United States-based oncology clinics are expanding adoption of circulating tumor DNA monitoring for serial therapy tracking, creating pull-through demand for extraction-to-analysis platforms.
Market Restraints
- Reagent Supply Concentration:Backward integration into nucleic acid extraction chemistry concentrates upstream supply among three dominant reagent manufacturers, exposing assay developers to sole-source risk.
- Analytical Specificity Limitations:Clonal hematopoiesis introduces false-positive mutation signals in liquid biopsy panels, complicating clinical interpretation and requiring orthogonal validation workflows.
- IVDR Documentation Burden:The EMA's IVDR transition imposes stricter performance documentation requirements for CE-marked kits, extending European commercialization timelines by 12-18 months.
Strategic Opportunities
- Point-of-Care Deployment:Microfluidic sample-in-answer-out architectures enable decentralized testing in community oncology settings, bypassing centralized laboratory bottlenecks.
- Minimal Residual Disease Monitoring:Post-surgical circulating tumor DNA surveillance represents an underpenetrated application with limited competing modalities.
- Multi-Cancer Screening Reimbursement:Medicare coverage determinations for pan-cancer early detection tests are creating a regulatory tailwind for evidence-generation investments.
Industry Challenges
- Bioinformatics Talent Scarcity:Variant calling algorithm development requires specialized computational biology expertise that outpaces current training pipeline output.
- CAP Accreditation Timelines:Laboratory accreditation processes for clinical sample processing create 6-9 month operational delays for new market entrants.
- Legacy LIMS Integration:Enterprise laboratory information management systems require custom middleware development to interface with cloud-based variant interpretation platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluid Biopsy Market |
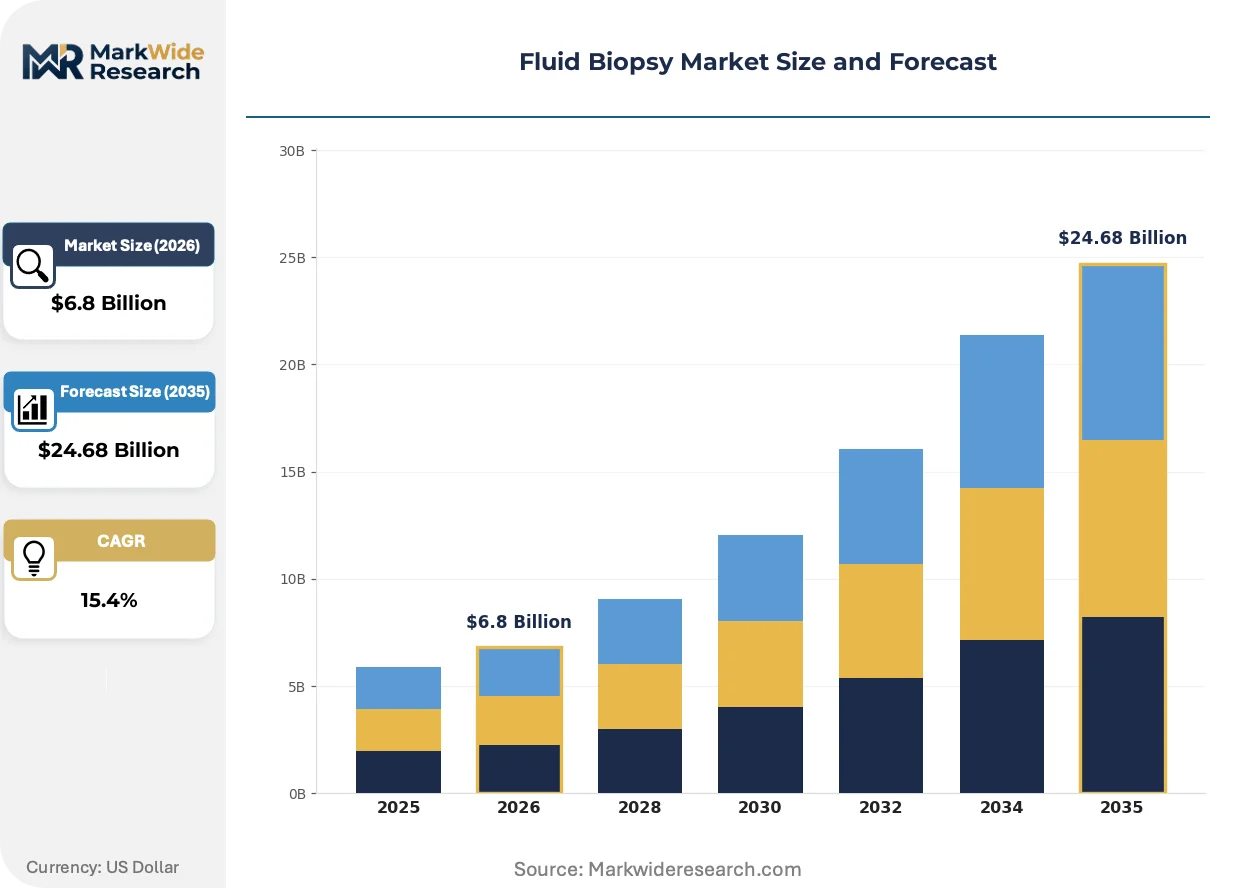
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $24.68 Billion |
| CAGR (2026 – 2036) | 15.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Circulating Tumor Cells, Circulating Tumor DNA, Exosomes, MicroRNA Application: Cancer Detection, Disease Monitoring, Treatment Selection, Recurrence Assessment End User: Diagnostic Laboratories, Research Institutes, Pharmaceuticals, Biotechnology Firms Technology: Next-Generation Sequencing, Polymerase Chain Reaction, Microfluidics, Digital PCR |
| Companies Covered | Guardant Health, F. Hoffmann-La Roche Ltd, Illumina Inc., Thermo Fisher Scientific Inc., QIAGEN, Natera Inc., Exact Sciences Corporation, Myriad Genetics Inc., Bio-Rad Laboratories Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluid Biopsy Market Shifts & Advancements
Next-generation sequencing panel architectures are expanding gene coverage breadth while digital PCR workflows compress cost structures at the point of care, creating divergent technology trajectories across clinical use cases.
Bead-based enrichment chemistries for circulating tumor DNA isolation are modularizing assay development pipelines, allowing oncology diagnostic developers to swap capture probe sets without revalidating entire workflows. Academic medical centers in the United States are adopting these interchangeable modules at accelerated pace. The modularizing architecture is compressing time-to-market for tumor-agnostic companion diagnostics.
The EMA's IVDR performance documentation requirements are forcing reagent manufacturers to generate expanded clinical evidence packages for legacy CE-marked products. European diagnostic laboratories face 18-month transition windows to recertify existing workflows. High-complexity molecular pathology laboratories in Germany and France are consolidating supplier relationships to reduce recertification burden.
Oncology clinics are unbundling genomic profiling from centralized academic pathology departments, contracting directly with specialized liquid biopsy reference laboratories. Community oncology practices in Texas and Florida are leading this disintermediation, seeking faster turnaround times for treatment selection decisions. The bypassing of traditional hospital-based laboratory channels is reshaping distribution economics for assay consumables.
Fluid Biopsy Market Segmentation
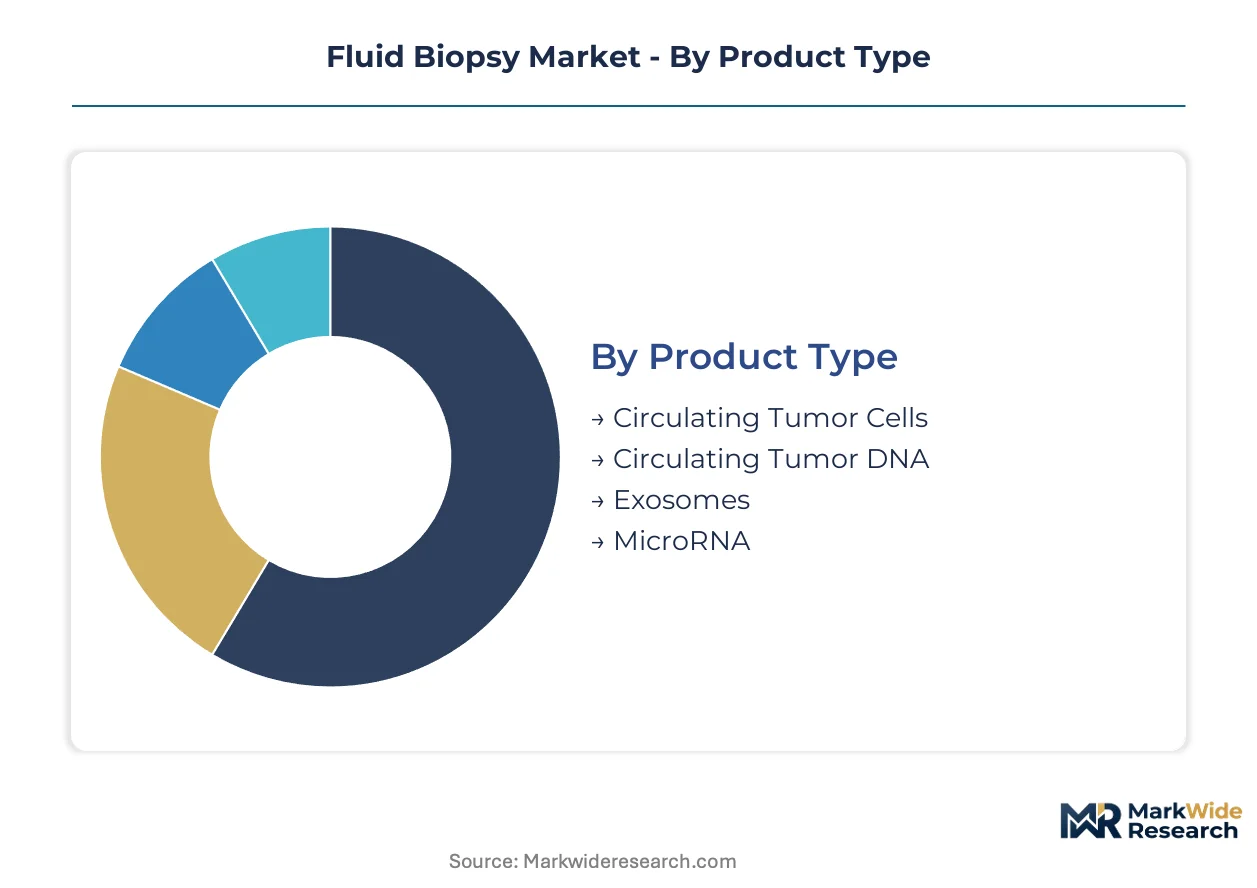
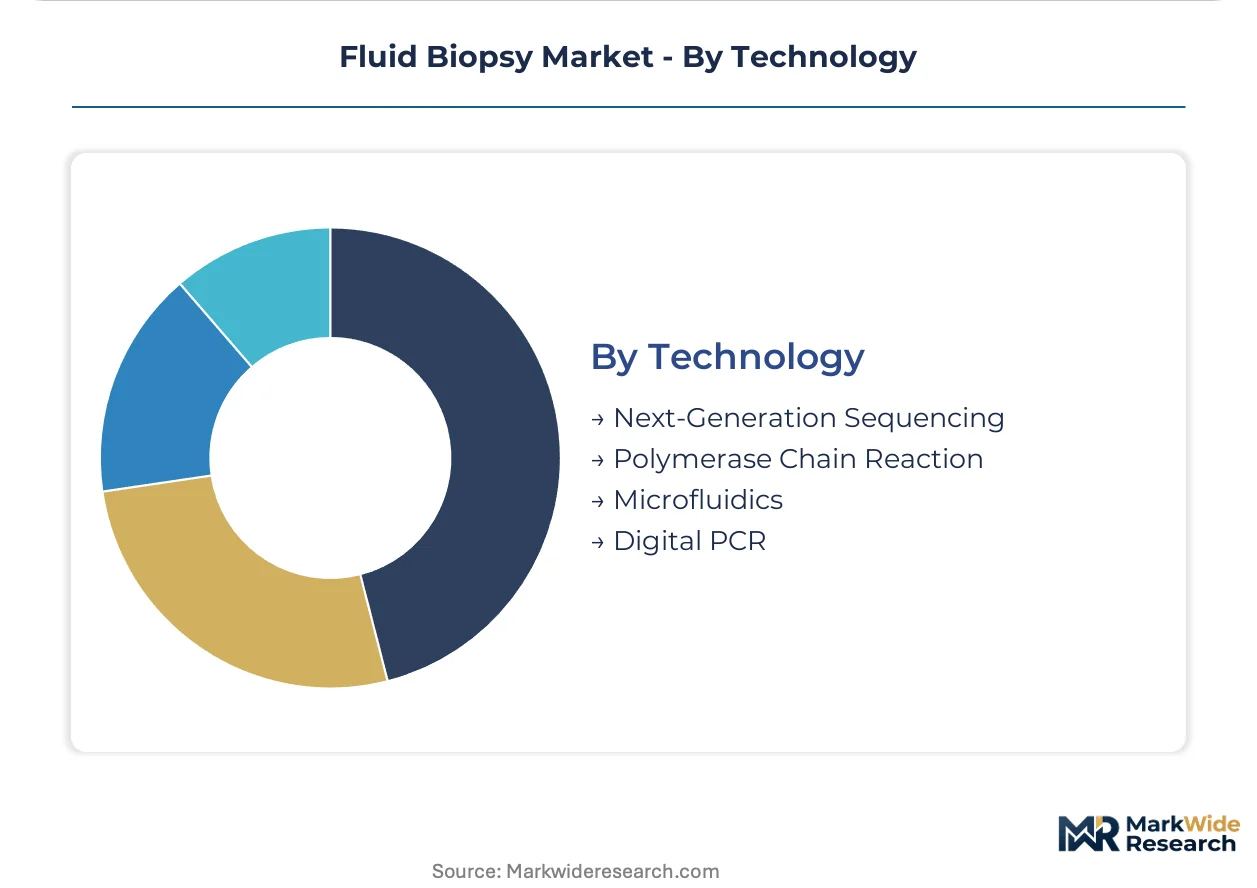
Fluid biopsy market segmentation reflects divergent technical architectures and clinical deployment models. Technology choices determine sensitivity thresholds, turnaround economics, and regulatory pathways for each product category.
Product Type:
Circulating biomarker isolation methods differ in analytical sensitivity and clinical validation depth, shaping reimbursement eligibility and laboratory adoption curves.
- Circulating Tumor DNA:Fragmented DNA shed by tumor cells into bloodstream enables non-invasive genotyping with detection limits approaching single-molecule levels. United States oncology clinics deploy ctDNA panels for serial monitoring during targeted therapy, driven by Medicare coverage for companion diagnostic applications.
- Circulating Tumor Cells:Intact viable tumor cells isolated from peripheral blood permit functional assays beyond genomic profiling. Research institutes in Germany and France concentrate demand for CTC-based drug sensitivity testing, constrained by complex enrichment workflows requiring specialized operator training.
- Exosomes:Extracellular vesicles carry protein and nucleic acid cargo reflecting tumor microenvironment status.
- MicroRNA:Small non-coding RNA molecules serve as stable biomarkers for tissue-of-origin identification.
Circulating tumor DNA leads on scale; exosomes lead on momentum.
Application:
Clinical use cases span the care continuum from screening through end-of-life monitoring, with reimbursement density varying sharply by indication.
- Treatment Selection:Real-time tumor genotyping matches patients to approved targeted therapies, requiring rapid turnaround to guide first-line decisions. United States community oncology practices in Texas and Florida prioritize liquid biopsy for EGFR and KRAS mutation assessment, compressing time-to-treatment initiation.
- Disease Monitoring:Serial ctDNA quantification tracks treatment response and detects emerging resistance mutations. Academic medical centers deploy longitudinal monitoring protocols for immunotherapy patients, facing analytical specificity challenges from clonal hematopoiesis interference.
- Cancer Detection:Asymptomatic screening applications pursue multi-cancer early detection signatures.
- Recurrence Assessment:Post-surgical surveillance identifies minimal residual disease prior to radiographic progression.
Treatment selection leads on scale; cancer detection leads on momentum.
End User:
Customer types differ in sample volume, technical sophistication, and procurement authority, fragmenting go-to-market requirements.
- Diagnostic Laboratories:High-complexity molecular pathology facilities process clinical samples under CAP accreditation, requiring ISO 13485-compliant reagent supply chains. Centralized laboratories in the United States dominate commercial testing volumes, consolidating purchasing power for extraction-to-analysis platforms.
- Pharmaceuticals:Drug developers deploy liquid biopsy for patient stratification in registrational trials and companion diagnostic co-development. FDA's liquid biopsy companion diagnostic pathway accelerates parallel approval timelines, concentrating investment in prospective-retrospective clinical evidence generation.
- Research Institutes:Academic centers pursue biomarker discovery and technology validation studies.
- Biotechnology Firms:Assay developers and platform innovators commercialize novel detection chemistries.
Diagnostic laboratories lead on scale; pharmaceuticals lead on momentum.
Technology:
Detection platforms trade off gene coverage breadth against cost per sample and point-of-care deployability.
- Next-Generation Sequencing:Massively parallel sequencing enables comprehensive genomic profiling across 500+ gene panels. United States reference laboratories adopt NGS for tumor-agnostic companion diagnostics, though bioinformatics infrastructure requirements limit penetration in community settings.
- Digital PCR:Droplet-based partitioning achieves absolute quantification without standard curves, compressing per-sample reagent costs while preserving single-molecule sensitivity. Oncology clinics deploy digital PCR for hotspot mutation monitoring where rapid turnaround outweighs breadth requirements.
- Polymerase Chain Reaction:Established qPCR workflows dominate legacy installed bases for well-characterized mutation targets.
- Microfluidics:Lab-on-chip architectures miniimize sample volume requirements and operator steps.
Next-generation sequencing leads on scale; digital PCR leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Boston anchors fluid biopsy commercialization through dense concentrations of oncology-focused molecular diagnostics firms and proximity to FDA regulatory infrastructure.
United States
Medicare's MolDX program drives reimbursement policy for multi-cancer early detection tests, compressing evidence-generation timelines for assay developers. The FDA's liquid biopsy companion diagnostic framework accelerates co-approval pathways for oncology therapeutics. Texas and Florida community oncology practices are disintermediating hospital-based laboratories, contracting directly with specialized reference laboratories for faster turnaround.
Germany
High-complexity molecular pathology laboratories concentrate demand for ISO 13485-compliant reagent supply chains under EMA IVDR transition requirements. The country's national pharmaceutical regulator imposes stricter performance documentation for CE-marked kits, extending recertification timelines. Academic medical centers in Heidelberg and Munich are consolidating supplier relationships to reduce regulatory burden.
China
Domestic oncology diagnostic developers are scaling NMPA regulatory submissions for circulating tumor DNA panels targeting EGFR mutation monitoring. The national medical products administration maintains parallel pathways for innovative diagnostics and imported reference standards. Shanghai and Beijing biotech clusters are attracting venture investment for point-of-care microfluidic platform development.
United Kingdom
NHS England's commissioning frameworks shape adoption curves for genomic profiling services in cancer care pathways. The national health service evaluates cost-effectiveness evidence for liquid biopsy integration into standard-of-care protocols. London-based reference laboratories are expanding CAP-accredited processing capacity to serve European clinical trial sponsors.
Japan
PMDA regulatory consultations guide companion diagnostic co-development strategies for domestic pharmaceutical firms. The national pharmaceutical regulator emphasizes analytical validation standards for circulating biomarker quantification. Tokyo and Osaka medical centers are piloting digital PCR workflows for minimal residual disease monitoring in post-surgical surveillance protocols.
Fluid Biopsy Market Competitive Landscape
Strategic partnerships dominate the current landscape as reagent manufacturers anchor companion diagnostic co-development agreements with pharmaceutical sponsors. The vendor base concentrates around three archetypes: comprehensive genomic profiling platforms, nucleic acid extraction chemistry suppliers, and specialized reference laboratories. Consolidation pressures intensify as Medicare reimbursement determinations favor scaled evidence-generation capabilities. Technology licensing and backward integration into sample preparation workflows represent the two dominant competitive vectors reshaping supply relationships.
Among United States-based molecular diagnostics specialists, Guardant Health exemplifies the comprehensive profiling platform archetype, while Thermo Fisher Scientific Inc. occupies a position representing reagent supply chain concentration. QIAGEN sits within the companion diagnostic partnership tier, anchoring regulatory co-approval pathways for oncology therapeutic developers. These three entities collectively illustrate how FDA pathway access and Medicare reimbursement policy are concentrating competitive advantage around integrated evidence-generation capabilities.
| Leading Market Players |
|---|
| Guardant Health |
| F. Hoffmann-La Roche Ltd |
| Illumina Inc. |
| Thermo Fisher Scientific Inc. |
| QIAGEN |
| Natera Inc. |
| Exact Sciences Corporation |
| Myriad Genetics Inc. |
| Bio-Rad Laboratories Inc. |
| Others |
Supply & Pricing Matrix
United States-based oncology clinics concentrate purchasing authority for circulating tumor DNA panels, anchoring a contract-based pricing model where multi-year service agreements lock in per-sample rates and bundle extraction-to-analysis workflows. This buyer concentration compresses margins for assay developers while rewarding scaled reference laboratories with volume-driven cost efficiencies.
Pricing Analysis
Reagent cost pass-through from nucleic acid extraction chemistry suppliers shapes assay pricing trajectories, with three-tier pricing structure across premium, standard, and economy levels reflecting CAP accreditation status and turnaround guarantees. Price differentiation hinges on ISO 13485 certification tier and panel gene coverage breadth, with comprehensive genomic profiling commanding premiums over hotspot monitoring. Pricing pressure stems from Medicare's MolDX program recalibrating reimbursement thresholds, forcing developers to absorb cost compression rather than pass through to clinics. Community oncology practices in Texas and Florida exhibit highest price sensitivity due to direct contracting economics, while academic medical centers prioritize analytical sensitivity over per-sample economics.
Supply Chain Analysis
Magnetic bead chemistry for circulating tumor DNA isolation rests on concentrated specialty reagent production in the United States, Germany, and China, with backward integration by dominant manufacturers capturing upstream value. Key inputs span oligonucleotide probe synthesis, high-fidelity polymerase enzymes, and microfluidic cartridge substrates. Single-source vulnerability concentrates in nucleic acid extraction chemistry, where sole-qualified suppliers expose assay developers to allocation risk during demand surges. Distribution runs through ISO 13485-compliant cold chain logistics to CAP-accredited reference laboratories, with direct-to-clinic disintermediation emerging in community oncology settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fluid biopsy market functions as a regulatory compounder where FDA's liquid biopsy companion diagnostic pathway accelerates commercialization timelines and concentrates competitive advantage around evidence-generation capabilities.
For Market Incumbents: Cement market position through captive supply of nucleic acid extraction chemistry and exclusive reference laboratory partnerships that lock in community oncology channel access. Threat from digital PCR point-of-care disruptors demands defensive investment in microfluidic sample-in-answer-out architectures. Priority lever centers on consolidating CAP-accredited processing capacity in high-volume geographies. For New Entrants and Emerging Players: Enter via minimal residual disease monitoring for post-surgical surveillance, an application with limited competing modalities and lower regulatory evidence thresholds than multi-cancer screening. Most penetrable segment spans community oncology practices in Florida and Texas seeking faster turnaround than academic pathology departments. Go-to-market angle emphasizes direct contracting bypassing hospital-based laboratory channels. For Investors and Strategic Acquirers: Pharmaceutical sponsors developing oncology therapeutics represent the most active acquirer in this space, seeking companion diagnostic co-development capabilities to accelerate parallel approval pathways. Long-term viability over the next decade hinges on Medicare reimbursement density for pan-cancer early detection. Target acquisition archetype: specialized reference laboratories with CAP accreditation and established FDA pre-submission track records. Signal to watch: MolDX program coverage determinations for multi-cancer screening tests.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Parallel FDA approval timelines for Guardant Health and Roche accelerate therapeutic market entry. |
| Backward Integration into Extraction Chemistry | Thermo Fisher Scientific's captive reagent supply secures margin control and sole-source relationships. |
| Point-of-Care Microfluidic Deployment | QIAGEN's sample-in-answer-out architecture bypasses centralized laboratory bottlenecks in community settings. |
| CAP Accreditation Expansion | Natera's laboratory network consolidation captures Medicare reimbursement for serial monitoring protocols. |
| Multi-Cancer Screening Reimbursement Strategy | Exact Sciences' MolDX program engagement shapes evidence requirements for pan-cancer test coverage. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with laboratory directors at CAP-accredited molecular pathology facilities, regulatory affairs leads at IVD manufacturers, oncology clinic procurement officers, and Medicare coverage policy specialists with secondary validation against FDA 510(k) and PMA filings, EMA IVDR technical documentation, ClinicalTrials.gov protocol registries, and CMS Medicare reimbursement databases. Bottom-up assay volume modeling and top-down market sizing triangulated across technology segments and clinical applications.
Segment-weighting approaches distributed revenue across circulating biomarker types, detection platforms, and end-user categories, with analytical frameworks tracking technology substitution dynamics between next-generation sequencing and digital PCR across the analysis window. CAGRs derived from fitted growth curves incorporating Medicare coverage expansion scenarios, IVDR transition timeline impacts, and pharmaceutical companion diagnostic pipeline maturation. Industry-specific inputs spanned laboratory test volume data from hospital procurement systems and reagent consumption metrics from ISO 13485-certified manufacturers.
Inputs from FDA pre-submission meeting minutes and EMA IVDR notified body guidance were available through the study window; gaps in real-world clinical utility evidence for minimal residual disease monitoring introduce uncertainty bands around adoption trajectory assumptions. Forecasts reflect documented regulatory milestones and reimbursement policy shifts, with clonal hematopoiesis analytical specificity limitations and IVDR recertification delays representing material revision triggers. Material deviation in Medicare MolDX coverage determinations or FDA companion diagnostic pathway restructuring warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Real-Time PCR, Digital PCR, and End-Point PCR Market
Medical Diagnostics
North America Flow Cytometry Market
Medical Diagnostics
Asia-Pacific Flow Cytometry Market
Medical Diagnostics
Stem Cell Characterization Kits Market
Medical Diagnostics
Flow Cytometry Market
Medical Diagnostics
Medical Marker Bands Market
Medical Diagnostics
US Molecular Diagnostics Market
Medical Diagnostics
MUC1 Antibody Market
Medical Diagnostics
Global Circulating Tumor Cells Market
Medical Diagnostics
Telepathology Market
Medical Diagnostics
Protein Sequencing Market
Medical Diagnostics
Liver Biopsy Market
Medical Diagnostics
Global Complete Blood Count Device Market
Medical Diagnostics
Artificial Intelligence (AI) in Medical Diagnostics Market
Medical Diagnostics
Global Hydrophobic Interaction Chromatography Market
Medical Diagnostics
Dosimetry Market