
 Global Complete Blood Count Device Market | 2026-2036
Global Complete Blood Count Device Market Size, Share, and Industry Trends Forecast 2026-2036
Global Complete Blood Count Device Market Foresight
CE marking under the EU Medical Device Regulation is redrawing competitive boundaries for hematology equipment manufacturers. Sysmex leverages its installed base of automated CBC analyzers across Japanese and European hospital networks. Danaher Corporation anchors its position through Beckman Coulter's vertical integration in reagent and consumable supply chains.
A complete blood count device quantifies erythrocytes, leukocytes, platelets, hemoglobin concentration, and hematocrit percentage using electrical impedance or laser-based detection methods. These instruments serve as foundational diagnostic tools for anemia detection, infection monitoring, and chemotherapy management in clinical settings. Automated CBC analyzers dominate hospital procurement budgets due to throughput requirements, while point-of-care devices capture the fastest expansion as emergency departments prioritize turnaround time over laboratory centralization. Microfluidics technology segments attract venture funding for miniaturization, though electrical impedance platforms sustain the largest installed base revenue streams from consumable contracts.
The FDA's 510(k) clearance framework and the EU MDR's post-market surveillance requirements shape validation timelines and clinical evidence burdens for manufacturers entering Western markets. China's NMPA accelerates review pathways for domestically manufactured hematology instruments under innovation device designations. Stakeholders must monitor how reimbursement coding for CBC testing evolves under value-based care contracts versus fee-for-service schedules.
Market Dynamics
Point-of-care testing adoption in hospital emergency departments is compressing traditional laboratory centralization models, forcing hematology manufacturers to bifurcate product portfolios between high-throughput analyzers and portable diagnostic platforms.
Growth Catalysts
- Health system modernization programs:Government-funded hospital automation initiatives in the United States, Germany, and China are accelerating procurement of automated CBC analyzers with integrated slide preparation systems.
- FDA's stricter Class II device clearance pathways:Elevated validation requirements for hematology instruments are filtering out marginal competitors and consolidating procurement decisions around established platform vendors.
- Microfluidics miniaturization:Venture-backed startups are advancing cartridge-based CBC devices that reduce sample volume requirements and enable near-patient testing in oncology infusion centers.
Market Restraints
- Consumable contract lock-in:Electrical impedance platform users face switching costs from proprietary reagent supply agreements that extend seven to ten years.
- Laser-based detection component concentration:Optical subsystem manufacturing concentrates among Japanese and German precision optics suppliers, creating single-source vulnerability.
- EU MDR clinical evidence burdens:Expanded post-market surveillance requirements for Class IIa hematology devices are extending CE marking timelines by eighteen to twenty-four months.
Strategic Opportunities
- Rural clinic penetration in India:Underdeveloped district hospital laboratory infrastructure creates demand for battery-operated, low-throughput CBC devices with minimal maintenance requirements.
- China's NMPA innovation device designation:Accelerated review pathways for domestically manufactured hematology instruments enable faster market entry against imported platforms.
- Integration of artificial intelligence with digital morphology:Automated white blood cell differential classification is converging with cloud-based pathologist consultation networks.
Industry Challenges
- ISO 15189 laboratory accreditation timelines:Hospital laboratories face eighteen-month certification cycles that delay analyzer commissioning and revenue recognition.
- Field service engineer scarcity:Maintenance of laser-based optical systems requires specialized photonics training that outpaces vocational program output in emerging markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Complete Blood Count Device Market |
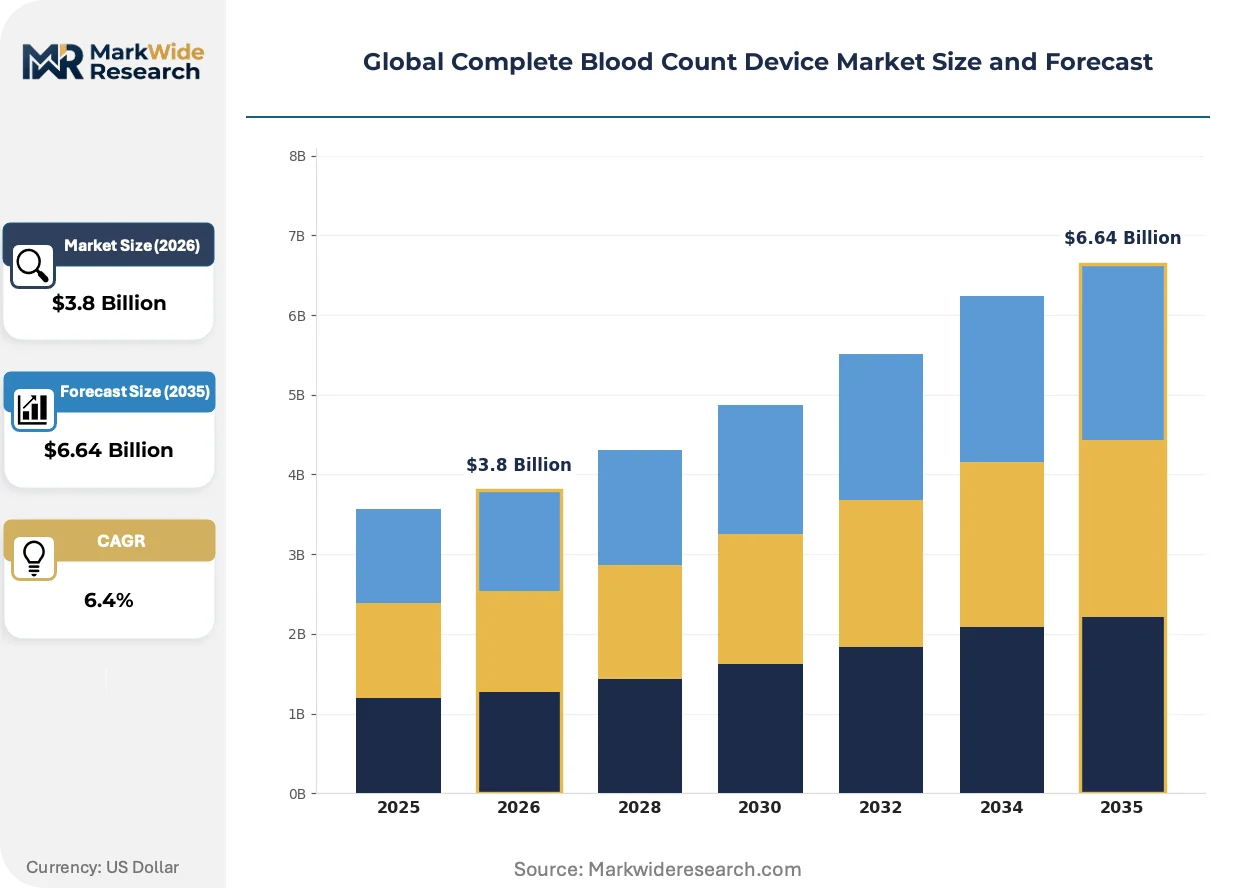
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated CBC Analyzers, Manual Hemocytometers, Hematology Analyzers, Point-of-Care Devices, Flow Cytometers Technology: Electrical Impedance, Laser Flow Cytometry, Fluorescence, Digital Imaging, Microfluidics Application: Clinical Diagnostics, Blood Banking, Veterinary Testing, Research Laboratories, Biopharmaceutical Quality Control End User: Hospitals, Diagnostic Laboratories, Academic Institutions, Blood Donation Centers, Pharmaceutical Companies |
| Companies Covered | Sysmex, Danaher Corporation, Abbott Laboratories, Siemens Healthineers, Horiba, BD, Thermo Fisher, Mindray, Roche Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Complete Blood Count Device Market Shifts & Advancements
Three intersecting developments are reshaping hematology instrumentation: detection technology diversification, regulatory framework fragmentation across major markets, and procurement model evolution favoring operational expenditure over capital outlay.
Microfluidics-based sample processing is fragmenting the traditional dichotomy between centralized laboratory analyzers and manual microscopy methods. Emergency departments in tertiary care hospitals are piloting cartridge-based CBC devices that deliver results in eight minutes versus forty-five minutes for core laboratory transport. This speed advantage is compressing the addressable market for mid-throughput benchtop analyzers in facilities with annual test volumes below fifty thousand.
The EU Medical Device Regulation's post-market clinical follow-up requirements are mandating systematic collection of real-world performance data from hematology analyzers. Manufacturers must now maintain clinical evidence registries spanning the device lifecycle, adding fifteen to twenty percent to regulatory affairs staffing. Japanese and European hospital networks are prioritizing vendors with established MDR technical documentation, disadvantaging newer market entrants.
Hospital procurement departments are unbundling analyzer acquisition from reagent supply contracts, separating capital equipment purchasing from operational consumable expenditure. Group purchasing organizations in the United States are negotiating multi-hospital analyzer placements with reagent pricing indexed to test volume commitments. This shift is visible most acutely in integrated delivery networks consolidating laboratory services across fifteen to twenty affiliated hospitals.
Global Complete Blood Count Device Market Segmentation
CBC device segmentation reveals divergent margin structures across detection technologies and care settings. Procurement patterns in hospital emergency departments favor speed-optimized platforms over throughput-focused laboratory systems, fragmenting traditional vendor dominance.
Product Type:
Margin pools concentrate in consumable-linked installed bases rather than capital equipment sales.
- Automated CBC Analyzers:High-throughput platforms integrate slide preparation and digital morphology for hospital core laboratories. Demand clusters in the United States, Germany, and China where health system modernization programs prioritize hematology automation with seven-to-ten-year reagent contracts.
- Point-of-Care Devices:Cartridge-based systems deliver results in eight minutes for emergency department triage. Hospital networks in tertiary care settings are piloting these platforms to compress turnaround time versus core laboratory transport.
- Manual Hemocytometers:Glass counting chambers persist in resource-constrained settings with intermittent power supply.
- Hematology Analyzers:Mid-throughput benchtop systems serve diagnostic laboratories with annual test volumes below fifty thousand.
- Flow Cytometers:Research-grade instruments enable leukocyte subset analysis in academic medical centers.
The dominant share belongs to Automated CBC Analyzers, while Point-of-Care Devices are closing the gap fastest.
Technology:
Cost tiers separate mature electrical impedance platforms from emerging optical and microfluidic alternatives.
- Electrical Impedance:Coulter principle-based counting sustains the largest installed base through proven erythrocyte and platelet enumeration. Proprietary reagent supply agreements lock users into extended consumable contracts that filter switching.
- Laser Flow Cytometry:Optical detection enables five-part white blood cell differential without lysing reagents. Japanese and German precision optics suppliers concentrate laser subsystem manufacturing, creating single-source vulnerability for instrument makers.
- Fluorescence:Dye-based nucleated cell detection improves reticulocyte quantification accuracy.
- Digital Imaging:CCD camera systems capture cellular morphology for AI-assisted classification.
- Microfluidics:Silicon and polymer chip fabrication reduces sample volume to microliter scale for oncology infusion center applications.
Electrical Impedance retains the dominant installed base, though Microfluidics is expanding most quickly among venture-backed development programs.
Application:
Volume concentration varies sharply between regulated clinical environments and research settings with different procurement cycles.
- Clinical Diagnostics:Anemia detection, infection monitoring, and chemotherapy management drive routine testing in hospital and outpatient settings. China's NMPA accelerates review pathways for domestically manufactured instruments under innovation device designations.
- Biopharmaceutical Quality Control:Cell therapy manufacturing requires precise leukocyte enumeration for release testing. FDA's stricter Class II device clearance pathways elevate validation requirements for instruments entering GMP environments.
- Blood Banking:Donor screening and component processing rely on high-throughput platforms with continuous operation.
- Veterinary Testing:Companion animal practices adopt adapted human hematology platforms with species-specific software.
- Research Laboratories:Preclinical studies utilize open-platform analyzers with customizable gating protocols.
Clinical Diagnostics commands the dominant share, while Biopharmaceutical Quality Control is climbing the fastest on cell therapy manufacturing expansion.
End User:
Customer type determines procurement authority, with integrated delivery networks consolidating decisions across fifteen-to-twenty affiliated hospitals.
- Hospitals:Emergency departments and core laboratories bifurcate between point-of-care speed and central laboratory throughput. Group purchasing organizations negotiate multi-hospital placements with reagent pricing indexed to volume commitments.
- Diagnostic Laboratories:Independent reference labs and hospital outreach programs prioritize mid-throughput analyzers with extended maintenance contracts.
- Academic Institutions:Teaching hospitals combine clinical service with research applications requiring flexible software.
- Blood Donation Centers:High-volume continuous operation demands ruggedized instruments with minimal downtime.
- Pharmaceutical Companies:GMP-compliant quality control laboratories require validated instruments with complete documentation packages.
Hospitals hold the dominant share, though Diagnostic Laboratories are gaining share fastest as laboratory service outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical logistics infrastructure underwrites Europe's distribution role for hematology instruments, while Shanghai Pudong International Airport's cold-chain cargo terminals anchor Asia-Pacific supply movements.
United States
Hospital automation initiatives and integrated delivery network consolidation drive analyzer procurement. FDA's stricter Class II device clearance pathways filter marginal competitors from the 510(k) pathway. Boston's medical device cluster concentrates hematology R&D alongside venture-backed microfluidics startups.
Germany
Health system modernization programs prioritize laboratory automation in university hospitals. EU MDR post-market surveillance requirements extend CE marking timelines for Class IIa hematology devices. The Baden-Württemberg precision optics corridor supplies laser subsystem components to instrument manufacturers.
China
NMPA innovation device designations accelerate review pathways for domestically manufactured hematology platforms. Government-funded hospital tier-upgrading programs automate county-level laboratory infrastructure. Suzhou's biomedical industrial park hosts domestic analyzer assembly operations competing against imported platforms.
Japan
PMDA regulatory harmonization with IMDRF standards streamlines multi-market submissions for hematology instruments. METI funding for diagnostic device miniaturization supports point-of-care development. The Kobe biomedical innovation cluster concentrates automated analyzer engineering expertise.
India
District hospital laboratory infrastructure gaps create demand for battery-operated low-throughput devices. CDSCO medical device rules impose quality management system requirements on hematology instrument imports. Hyderabad's medical technology corridor attracts contract manufacturing for portable diagnostic platforms.
Global Complete Blood Count Device Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and regulatory compliance capabilities. The market structure concentrates around diversified life science conglomerates with captive reagent supply chains and established service networks. Two archetypes dominate: integrated platform vendors bundling analyzers with consumable contracts, and point-of-care specialists advancing cartridge-based miniaturization. Competitive moves center on backward integration into precision optics manufacturing and strategic partnerships with group purchasing organizations for multi-hospital placements.
Among Japanese precision instrument specialists, Sysmex and Horiba occupy positions within the integrated platform tier, exemplifying archetypes that leverage installed base expansion for recurring consumable revenue. Danaher Corporation anchors the conglomerate structure through Beckman Coulter's position in reagent supply chain control.
| Leading Market Players |
|---|
| Sysmex |
| Danaher Corporation |
| Abbott Laboratories |
| Siemens Healthineers |
| Horiba |
| BD |
| Thermo Fisher |
| Mindray |
| Roche Diagnostics |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day laser optics lead times from Baden-Württemberg and Kobe suppliers concentrate pricing power among integrated platform vendors with captive reagent contracts, while cartridge-based point-of-care entrants face margin compression from precision component sourcing.
Pricing Analysis
Volume-discount tiering structures separate high-throughput analyzer placements with seven-to-ten-year consumable commitments from spot purchases of point-of-care cartridges. Pricing stratifies across premium laser-flow-cytometry systems, standard electrical-impedance platforms, and economy manual devices based on throughput certification and after-sales service bundling. Cost compression in the mid-throughput benchtop segment is intensifying because emergency departments are bypassing core laboratories for near-patient testing. Group purchasing organizations exhibit the highest price sensitivity, while academic medical centers prioritize performance specifications over unit economics.
Supply Chain Analysis
Just-in-time inventory strategies dominate among electrical-impedance platform manufacturers with established reagent supply chains, whereas point-of-care developers maintain strategic stockpiles of microfluidic chips due to silicon foundry allocation constraints. Manufacturing concentrates in Germany, Japan, and China for precision optics, automated analyzer assembly, and domestic hematology platform production respectively. Component dependencies include laser diodes, proprietary lysing reagents, and polymer microfluidic substrates. Single-source vulnerability in Japanese and German optical subsystems creates supply risk. Distribution runs through hospital group purchasing organizations and diagnostic laboratory service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated integrated delivery networks negotiating multi-hospital analyzer placements, fragmenting vendor pricing authority across fifteen-to-twenty-facility procurement coalitions.
For Market Incumbents: Consolidate backward integration into precision optics manufacturing to reduce single-source dependency on Baden-Württemberg and Kobe suppliers. Deepen reagent contract lock-in through extended consumable supply agreements that raise switching costs for electrical-impedance platform users. Defend against microfluidics entrants by embedding digital morphology and AI-assisted classification into high-throughput analyzer roadmaps.
For New Entrants and Emerging Players: Lead with battery-operated low-throughput devices targeting India's district hospital laboratory infrastructure gaps, where intermittent power supply and maintenance scarcity create white-space demand. Penetrate oncology infusion centers with microliter-scale microfluidic cartridges that reduce sample volume requirements for chemotherapy monitoring. Pursue China's NMPA innovation device designation as the fastest regulatory pathway against established imported platforms.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue installed-base play because consumable-linked contracts generate seven-to-ten-year revenue streams that outpace capital equipment cyclicality. Target point-of-care specialists with FDA 510(k) clearance progress and cartridge manufacturing scale. Watch emergency department point-of-care adoption rates as the inflection signal for mid-throughput benchtop displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation requirements filter competitors and extend CE marking timelines eighteen to twenty-four months. |
| Hospital System Partnership | Group purchasing organization negotiations consolidate procurement across integrated delivery networks with volume-indexed reagent pricing. |
| Backward Integration | Captive precision optics manufacturing reduces single-source vulnerability to Japanese and German laser subsystem suppliers. |
| Software Companion Development | AI-assisted digital morphology integration converges with cloud-based pathologist consultation networks for white blood cell classification. |
| Reimbursement Strategy | Value-based care contracts versus fee-for-service schedules determine CBC testing coding evolution and analyzer placement economics. |
Research Methodology
A spread of perspectives from hospital laboratory directors, hematology instrument service engineers, group purchasing organization contract managers, and regulatory affairs specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, EU MDR technical documentation filings, NMPA innovation device designations, and hospital procurement contract records. Bottom-up test volume modeling and top-down healthcare expenditure triangulation anchored market sizing.
Segmentation dimensions modeled include detection technology, product type, application setting, and end-user procurement authority across the projection horizon. CAGRs were derived from instrument placement trajectories, consumable contract renewal rates, and point-of-care penetration curves. Forecast inputs incorporated health system modernization program budgets, emergency department throughput requirements, and biopharmaceutical cell therapy manufacturing expansion.
Forecasts assume regulatory continuity in FDA Class II device pathways, EU MDR post-market surveillance, and NMPA innovation designations; material policy shifts would require re-modeling. Revision becomes warranted when point-of-care adoption in emergency departments crosses thresholds that compress mid-throughput benchtop addressable markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Stem Cell Characterization Kits Market
Medical Diagnostics
Protein Sequencing Market
Medical Diagnostics
North America Flow Cytometry Market
Medical Diagnostics
Fluid Biopsy Market
Medical Diagnostics
Asia-Pacific Flow Cytometry Market
Medical Diagnostics
Magnetic Resonance Analyzer Market
Medical Diagnostics
Circulating Tumor Cells (Ctcs) Prognostic Technologies Market
Medical Diagnostics
Europe Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
Global Circulating Tumor Cells Market
Medical Diagnostics
MUC1 Antibody Market
Medical Diagnostics
Global Histology and Cytology Market
Medical Diagnostics
Medical Marker Bands Market
Medical Diagnostics
Real-Time PCR, Digital PCR, and End-Point PCR Market
Medical Diagnostics
Asia-Pacific Single Cell Analysis Market
Medical Diagnostics
Global Hydrophobic Interaction Chromatography Market
Medical Diagnostics
Middle East and Africa Circulating Tumor Cells (CTC) Liquid Biopsy Market