
 Rapid Hepatitis Testing Market | 2026-2036
Rapid Hepatitis Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Rapid Hepatitis Testing Market Analytics
The capital-intensity divergence between molecular diagnostics platforms and lateral-flow strip manufacturers is redrawing competitive boundaries in rapid hepatitis testing. Abbott Laboratories leverages integrated immunoassay architectures to sustain hospital laboratory contracts across North American and European markets. Siemens Healthineers anchors its position through automated point-of-care systems that reduce technician training burdens in high-throughput clinics.
Rapid hepatitis testing encompasses diagnostic assays designed to detect hepatitis A, B, C, D, and E viral markers within minutes through immunochromatographic or nucleic acid amplification methods, typically requiring capillary blood or serum samples of 10–100 microliters without cold-chain infrastructure. These tests serve primary screening, outbreak response, and perioperative safety verification in settings lacking centralized laboratory capacity. Nucleic acid tests command premium positioning due to their analytical sensitivity for early viremia detection, while rapid antibody tests dominate volume procurement in public health programs where cost-per-test governs tender outcomes. Point-of-care devices represent the fastest-expanding structural category as microfluidics integration enables multiplexed hepatitis panel results on single cartridges.
FDA premarket notification pathways and WHO prequalification standards govern product commercialization timelines, with the former emphasizing analytical specificity claims and the latter prioritizing operational stability at ambient temperatures. EU MDR technical documentation requirements are elevating clinical evidence burdens for manufacturers seeking CE-marked access to European clinical settings. Stakeholders must monitor evolving regulatory harmonization between stringent and emerging market frameworks to anticipate where manufacturing investments and dossier preparation should concentrate.
Market Dynamics
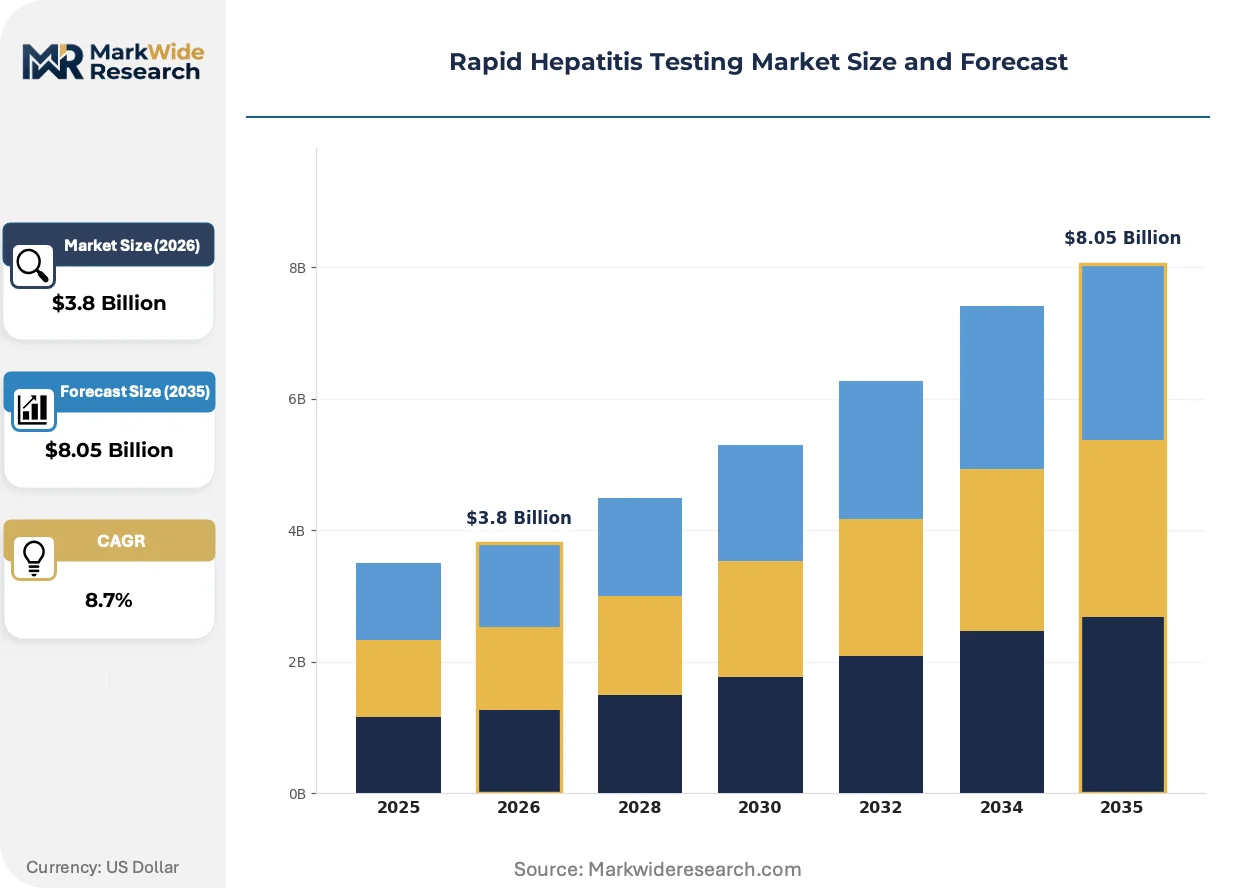
The divergence between nucleic acid amplification platforms and lateral-flow immunoassays is fragmenting procurement hierarchies in hepatitis diagnostics, as blood banks and decentralized clinics pursue incompatible performance-cost tradeoffs.
Growth Catalysts
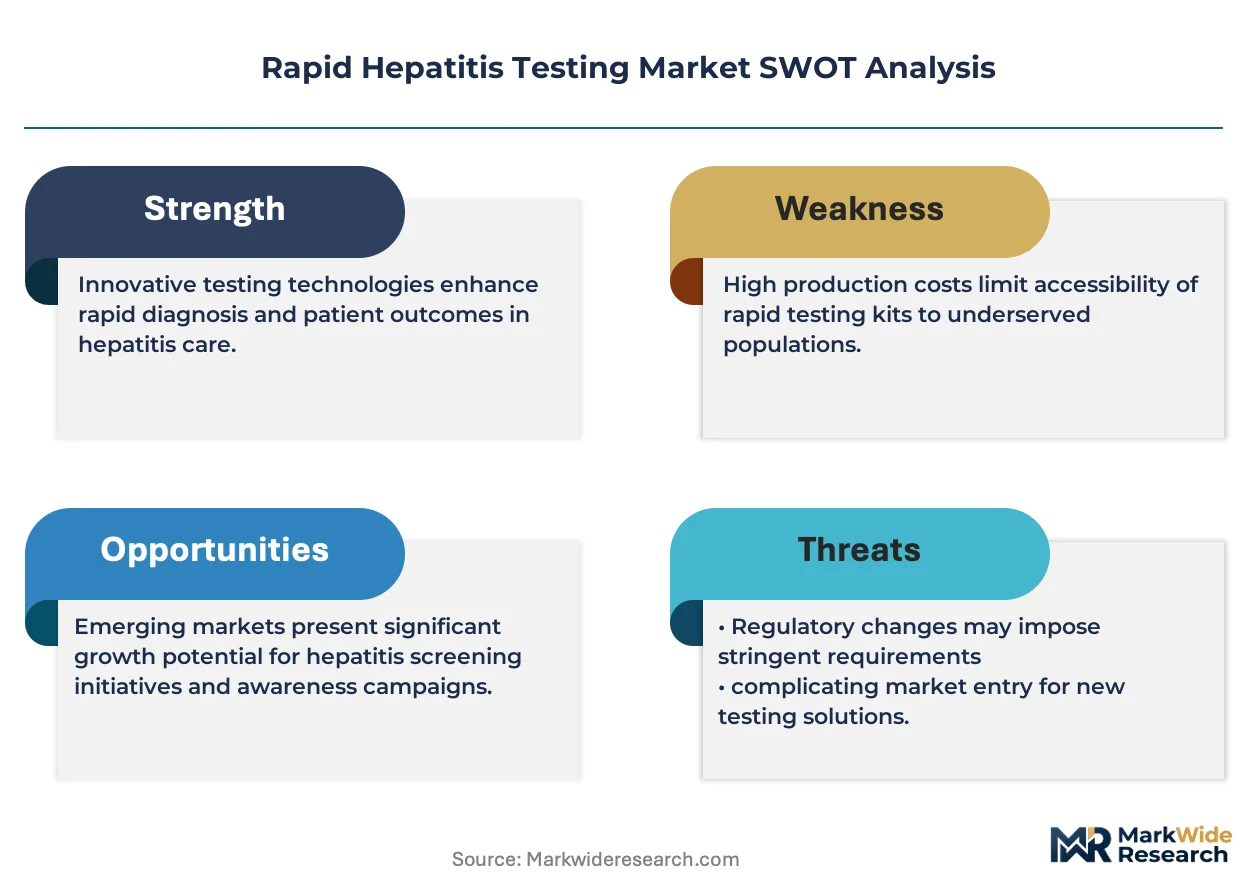
- WHO Prequalification Program:Ambient-temperature stability requirements under this framework accelerate product registration in tropical climates lacking cold-chain infrastructure, opening tender access across sub-Saharan African ministries of health.
- Microfluidics Integration:Cartridge-based multiplexing enables simultaneous hepatitis B surface antigen and core antibody detection on single devices, reducing technician workload in India's National Viral Hepatitis Control Program screening sites.
- Blood Bank Safety Mandates:Perioperative screening protocols in tertiary hospitals across Brazil and Thailand now require rapid serological confirmation prior to transfusion, institutionalizing point-of-care deployment.
Market Restraints
- Reagent Supply Concentration:Polymerase and reverse transcriptase enzyme production clusters in South Korean contract manufacturing organizations, exposing nucleic acid test makers to single-source dependency risks.
- EU MDR Clinical Evidence Burden:Technical documentation requirements for CE-marked hepatitis assays now demand prospective performance studies exceeding 18 months, compressing smaller manufacturers' commercialization timelines.
- Lateral-Flow Sensitivity Ceiling:Immunochromatographic strip detection limits for early viremia lag nucleic acid methods by 2-3 logs, restricting their utility in high-risk donor screening where analytical sensitivity governs protocol acceptance.
Strategic Opportunities
- India's District-Level Expansion:The National Viral Hepatitis Control Program's procurement decentralization to 700+ district hospitals creates volume demand for battery-operated readers compatible with rural electrical intermittency.
- Telemedicine Integration:Cloud-connected point-of-care devices transmitting encrypted results to centralized dashboards enable remote quality assurance for community health worker screening in Indonesia's archipelago provinces.
- Sustainability-Driven Tenders:European hospital procurement consortia now weight biodegradable cartridge materials in scoring algorithms, rewarding manufacturers with redesigned lateral-flow housings eliminating polypropylene.
Industry Challenges
- Multiplex Assay Validation Complexity:Cross-reactivity matrices for hepatitis D antibody in the presence of hepatitis B surface antigen extend regulatory submission preparation by 8-14 months.
- Technician Certification Bottlenecks:Nucleic acid platform operation requires molecular biology competencies scarce in West African laboratory workforces, constraining installed base utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rapid Hepatitis Testing Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid Antigen Tests, Rapid Antibody Tests, Nucleic Acid Tests, Point-of-Care Devices End User: Hospitals, Clinics, Diagnostic Laboratories, Home Care Settings Technology: Immunoassays, Microfluidics, Molecular Diagnostics, Enzyme-Linked Immunosorbent Assay Distribution Channel: Direct Sales, Online Retailers, Medical Supply Distributors, Pharmacies |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche AG, Siemens Healthineers, Cepheid Inc., Bio-Rad Laboratories, DiaSorin S.p.A, bioMérieux, LumiraDx, MedMira, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rapid Hepatitis Testing Market Evolving Landscape
Convergence of smartphone-based image analysis with disposable test strips is collapsing the cost-performance frontier in community-based hepatitis screening, while regulatory harmonization efforts accelerate product registration velocity.
Isothermal amplification chemistries are fragmenting the nucleic acid testing landscape by eliminating thermal cycler dependency. Recombinase polymerase amplification enables hepatitis C RNA detection at 37°C using handheld incubators. Community health programs in Kenya and Vietnam are piloting these platforms for same-day treatment initiation. The technology is fragmenting procurement categories previously dominated by laboratory-bound quantitative systems.
EU MDR Article 10 technical documentation requirements are elevating post-market surveillance obligations for hepatitis assay manufacturers. Clinical performance data must now span intended-use populations across member states. High-volume IVD producers are consolidating notified body relationships to streamline conformity assessment timelines. Smaller manufacturers face dossier preparation costs exceeding their annual R&D budgets.
Consolidated procurement by national health programs is compressing distributor margins and accelerating direct manufacturer-to-ministry contracting. UNICEF's supply division and the Global Fund now negotiate framework agreements spanning 40+ countries. Local distributors in Nigeria and Pakistan are repositioning as logistics and training service providers rather than inventory-holding intermediaries. This channel restructuring concentrates pricing power with volume-committed manufacturers.
Rapid Hepatitis Testing Market Segmentation
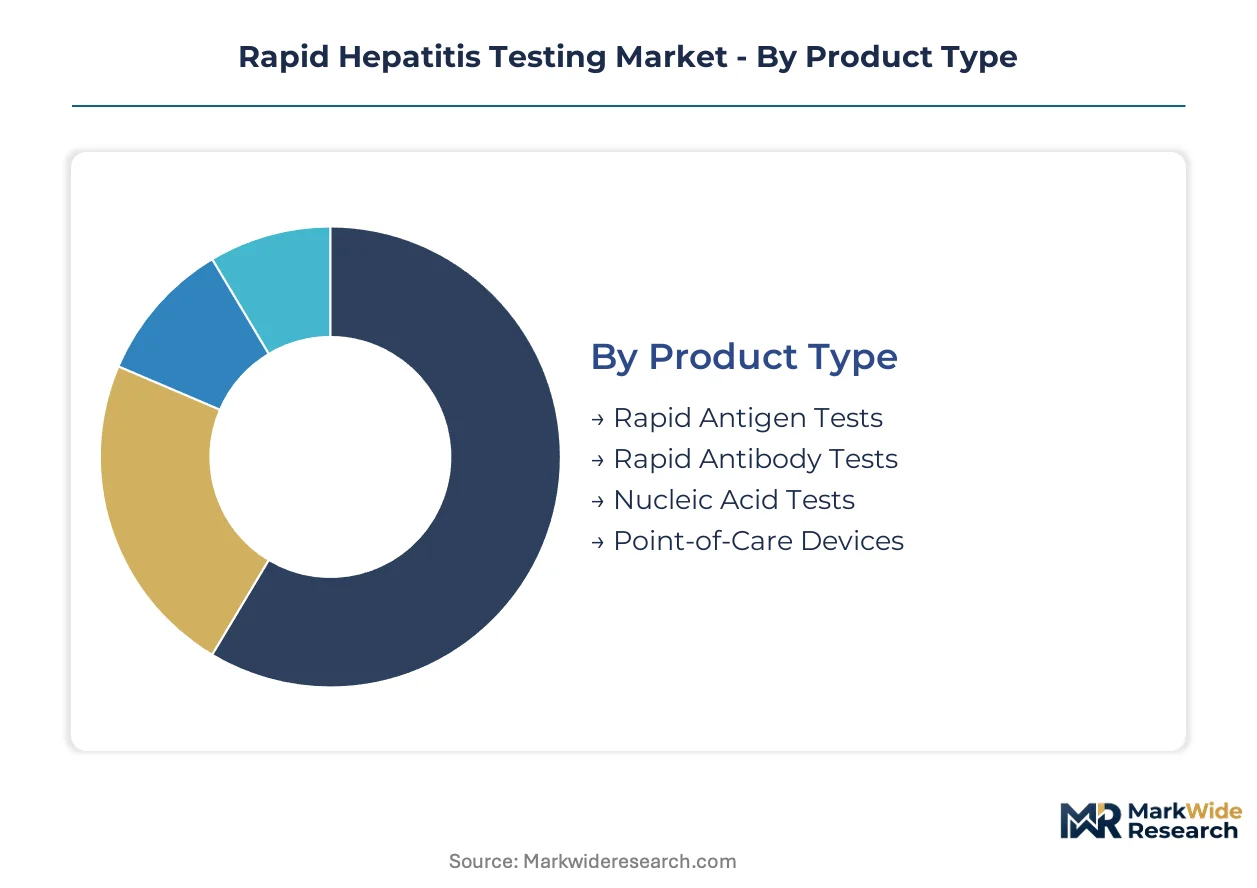
Segmentation in rapid hepatitis testing reveals where procurement power and margin pools diverge across testing modalities. Product architecture choices determine reimbursement pathways, while end-user concentration shapes channel economics and regulatory evidence requirements.
Product Type:
Margin pools concentrate in nucleic acid platforms and integrated point-of-care devices, where analytical sensitivity commands premium positioning against commodity lateral-flow strips.
- Nucleic Acid Tests:Polymerase chain reaction and isothermal amplification methods detect viral RNA at 10-100 copies per milliliter, enabling early viremia identification in blood bank screening protocols. Demand clusters in tertiary hospital transfusion services across Brazil and Thailand where perioperative safety mandates require serological confirmation prior to transfusion.
- Point-of-Care Devices:Cartridge-based microfluidic systems integrate sample preparation, amplification, and result interpretation on single disposable units. India's National Viral Hepatitis Control Program drives volume procurement for battery-operated readers compatible with rural electrical intermittency at 700-plus district hospitals.
- Rapid Antigen Tests:Immunochromatographic strips detect hepatitis B surface antigen in 15-20 minutes using capillary blood without cold-chain infrastructure.
- Rapid Antibody Tests:Lateral-flow assays identify IgM and IgG serological markers for hepatitis A, C, D, and E exposure screening in community health settings.
The dominant share belongs to rapid antibody tests, while point-of-care devices are closing the gap fastest.
End User:
Procurement authority and test volume scale differently across institutional settings, with blood banks and national screening programs wielding tender power that compresses per-unit margins.
- Diagnostic Laboratories:Centralized reference laboratories process high-throughput hepatitis panels using automated immunoassay analyzers with barcoded sample tracking and laboratory information system integration. Siemens Healthineers anchors contracts through systems that reduce technician training burdens in high-volume clinics across Germany and France.
- Hospitals:Tertiary care institutions deploy rapid testing for emergency department triage, preoperative screening, and occupational exposure protocols. Abbott Laboratories leverages integrated immunoassay architectures to sustain hospital laboratory contracts across the United States and United Kingdom.
- Clinics:Outpatient facilities prioritize rapid turnaround for same-day clinical decision-making in urban and semi-urban locations.
- Home Care Settings:Self-testing kits target high-risk populations seeking privacy for hepatitis C screening without clinical visits.
Diagnostic laboratories capture the largest procurement volumes, though hospitals are expanding their installed base most aggressively.
Technology:
Technical sophistication determines regulatory pathway complexity and manufacturing capital intensity, fragmenting competitive boundaries between chemistry platforms.
- Molecular Diagnostics:Nucleic acid amplification technologies including real-time PCR, transcription-mediated amplification, and recombinase polymerase amplification enable quantitative viral load monitoring. WHO prequalification ambient-temperature stability requirements accelerate product registration in tropical climates across sub-Saharan African ministries of health lacking cold-chain infrastructure.
- Microfluidics:Lab-on-chip architectures manipulate 10-100 microliter sample volumes through etched channels for multiplexed hepatitis B surface antigen and core antibody detection. EU MDR technical documentation requirements elevate clinical evidence burdens for manufacturers seeking CE-marked access to European clinical settings.
- Immunoassays:Antigen-antibody binding reactions on porous membranes produce visual or instrument-read results within minutes.
- Enzyme-Linked Immunosorbent Assay:Microplate-based colorimetric detection offers intermediate sensitivity between rapid strips and molecular methods for batch processing.
Immunoassays retain the broadest installed base, while microfluidics is gaining share fastest among new procurement cycles.
Distribution Channel:
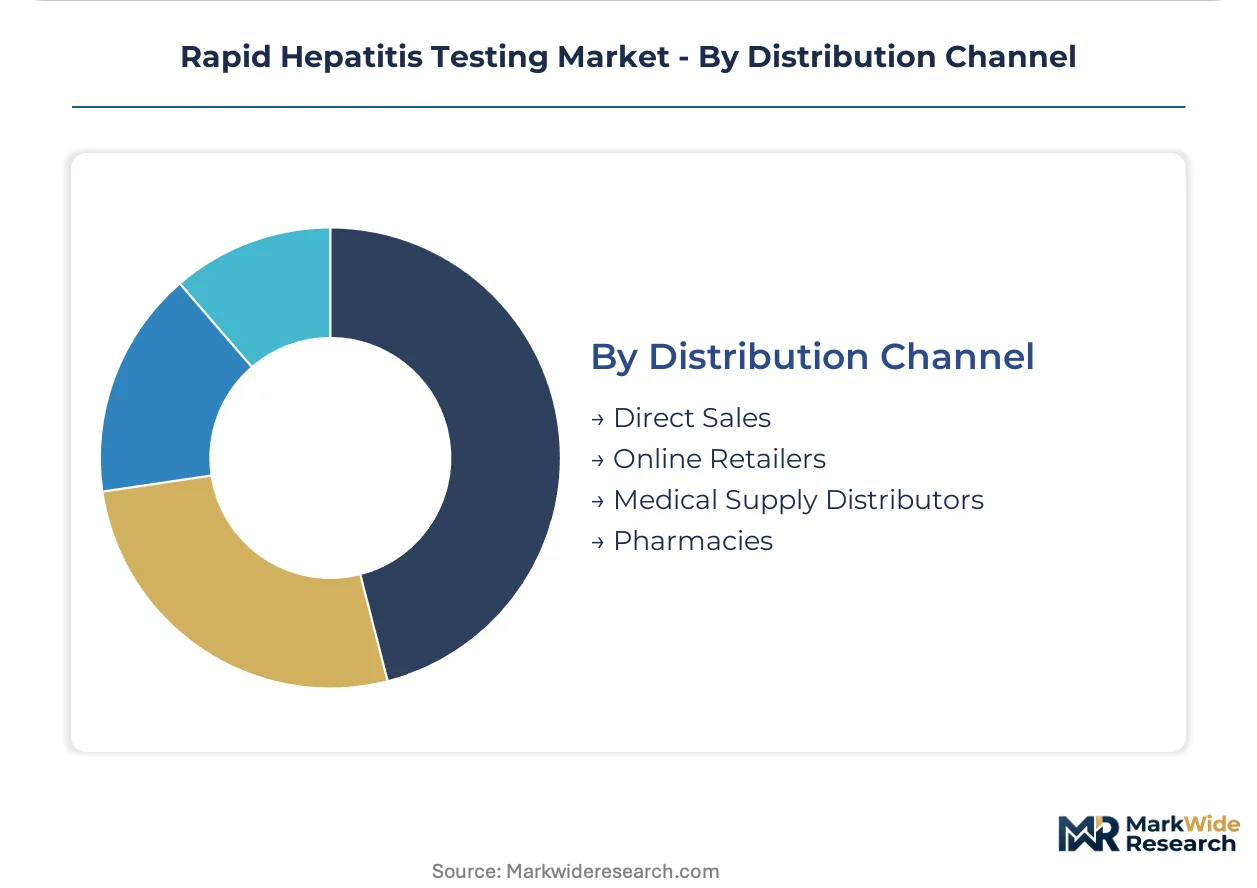
Channel restructuring concentrates pricing power with volume-committed manufacturers as consolidated procurement compresses traditional distributor margins.
- Direct Sales:Manufacturers negotiate framework agreements directly with UNICEF's supply division, the Global Fund, and national health programs spanning 40-plus countries. Local distributors in Nigeria and Pakistan reposition as logistics and training service providers rather than inventory-holding intermediaries.
- Medical Supply Distributors:Regional wholesalers maintain cold-chain logistics for temperature-sensitive reagents and provide technical training for complex instrument platforms.
- Online Retailers:E-commerce platforms serve home care and small clinic segments with direct-to-consumer shipping for self-testing kits.
- Pharmacies:Community pharmacy chains stock rapid antibody tests for over-the-counter purchase in jurisdictions with liberalized diagnostic regulations.
Direct sales commands the dominant procurement value, though medical supply distributors are expanding their service scope most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and Switzerland where CE-marked nucleic acid platforms command premium positioning, while procurement volume aggregates in India where the National Viral Hepatitis Control Program drives tender scale at compressed per-unit margins.
United States
FDA premarket notification pathways govern hepatitis assay commercialization timelines with emphasis on analytical specificity claims. Hospital laboratory consolidation across Texas and Florida accelerates integrated immunoassay procurement for perioperative screening protocols. Abbott Laboratories anchors contracts through automated platforms serving high-throughput tertiary care networks.
Germany
EU MDR technical documentation requirements elevate clinical evidence burdens for manufacturers seeking CE-marked access to European clinical settings. Siemens Healthineers leverages automated point-of-care systems that reduce technician training burdens in high-volume clinics across Bavaria and North Rhine-Westphalia. The notified body consolidation streamlines conformity assessment for high-volume IVD producers.
India
The National Viral Hepatitis Control Program drives procurement volumes for decentralized screening across 700-plus district hospitals. CDSCO registration pathways prioritize ambient-temperature stability for tropical deployment without cold-chain infrastructure. Karnataka and Maharashtra host manufacturing clusters producing battery-operated readers compatible with rural electrical intermittency.
Brazil
ANVISA regulatory frameworks govern IVD registration for hepatitis screening assays entering the Mercosur market. Blood bank safety mandates in São Paulo and Rio de Janeiro tertiary hospitals require rapid serological confirmation prior to transfusion. Local distributors reposition as logistics and training service providers under consolidated national health program procurement.
China
NMPA approval pathways for hepatitis diagnostic kits emphasize clinical performance validation across intended-use populations. Isothermal amplification chemistries pilot in Guangdong and Jiangsu provinces for same-day treatment initiation in community health programs. Domestic manufacturers scale cartridge-based microfluidic production for district-level hospital networks.
Rapid Hepatitis Testing Market Competitive Landscape
Concentration sits with diversified diagnostics conglomerates and point-of-care specialists who command tender access through WHO prequalification and CE marking. The vendor base stratifies across three tiers: integrated platform manufacturers sustaining hospital laboratory contracts, cartridge-based microfluidics developers capturing National Viral Hepatitis Control Program volumes, and lateral-flow strip producers serving commodity screening programs. Dominant competitive moves include strategic partnerships for ambient-temperature stability validation and geographic expansion into district-level procurement channels.
Among diversified diagnostics conglomerates, Abbott Laboratories and F. Hoffmann-La Roche AG exemplify the integrated platform archetype with sustained presence across North American and European hospital networks. Siemens Healthineers occupies a position within the automated point-of-care tier, while Cepheid Inc. represents the molecular diagnostics specialist segment focused on nucleic acid amplification platforms.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche AG |
| Siemens Healthineers |
| Cepheid Inc. |
| Bio-Rad Laboratories |
| DiaSorin S.p.A |
| bioMérieux |
| LumiraDx |
| MedMira, Inc. |
| Others |
Value Network & Pricing Analysis
WHO prequalification ambient-temperature stability requirements gate both supplier qualification and price differentiation simultaneously, as manufacturers must validate tropical deployment capabilities before accessing ministry of health tenders across sub-Saharan Africa and South Asia. This certification tier separates nucleic acid platform providers commanding premium positioning from commodity lateral-flow strip producers competing on per-test cost in volume procurement programs.
Pricing Analysis
The customization-premium spread runs wide between configured-to-order cartridge-based microfluidic systems and standard lateral-flow antibody strips. Three-tier pricing structure across premium, standard, and economy levels reflects analytical sensitivity gradations, with nucleic acid amplification platforms anchored by ISO 13485 certification tiers commanding highest positioning. Cost compression in the economy tier intensifies because India's National Viral Hepatitis Control Program consolidates district-level procurement at scale. Blood banks and transfusion services exhibit lowest price sensitivity due to perioperative safety mandates, while community health programs in Indonesia's archipelago provinces prioritize per-test economics above performance margins.
Supply Chain Analysis
Inventory lead times for polymerase and reverse transcriptase enzymes extend procurement cycles for nucleic acid test manufacturers, creating working capital intensity distinct from lateral-flow strip production. South Korea, China, and the United States concentrate supply for molecular diagnostic reagents, while India and Germany host cartridge assembly and automated reader manufacturing respectively. Single-source dependency risks center on South Korean contract manufacturing organizations for enzymatic components. Distribution runs through direct manufacturer-to-ministry framework agreements spanning UNICEF supply division and Global Fund negotiations, compressing traditional distributor margins into logistics and training service fees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated national health programs and hospital procurement consortia, fragmenting traditional distributor intermediaries as direct contracting concentrates volume with manufacturers committed to tender scale.
For Market Incumbents: Secure WHO prequalification renewals and EU MDR technical documentation completeness to defend hospital laboratory contracts against isothermal amplification entrants. Abbott Laboratories and Siemens Healthineers anchor positions through integrated immunoassay architectures, but recombinase polymerase amplification pilots in Kenya and Vietnam threaten platform substitution. Backward integration into cartridge manufacturing in Karnataka and Maharashtra insulates against supply intermittency risks. For New Entrants and Emerging Players: Lead with battery-operated reader compatibility for India's 700-plus district hospital expansion under the National Viral Hepatitis Control Program, where electrical intermittency creates white-space demand underserved by laboratory-bound systems. Telemedicine-integrated cloud connectivity for Indonesia's archipelago provinces offers second penetration vector. Partner with local logistics providers repositioning as training service operators to bypass established distributor relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified diagnostics conglomerates seeking hepatitis assay portfolio rationalization under EU MDR clinical evidence burden pressures. Long-term viability hinges on ambient-temperature stability validation capabilities and district-level procurement channel access. Watch for isothermal amplification chemistry adoption inflection in community health programs as signal of nucleic acid platform commoditization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Renewal | UNICEF supply division tenders require ambient-temperature stability validation for tropical deployment access. |
| CE Marking Pathway | EU MDR technical documentation demands prospective performance studies exceeding eighteen months for European clinical entry. |
| Hospital System Partnership | Abbott Laboratories sustains perioperative screening contracts through automated immunoassay platform integration. |
| Cartridge Manufacturing Scale-Up | Battery-operated reader production in Karnataka addresses India's district-level electrical intermittency constraints. |
| Reimbursement Strategy | National Viral Hepatitis Control Program procurement decentralization creates volume commitment pathways for point-of-care devices. |
Research Methodology
A spread of perspectives from regulatory affairs leads at notified bodies, procurement managers at national health programs, biomedical engineers at tertiary hospital transfusion services, and GPO contracts managers converged on the working assumptions. Secondary validation drew from WHO prequalification listings, FDA 510(k) filings, EU MDR technical documentation databases, and hospital procurement records across Brazil and Thailand. Bottom-up test volume modeling triangulated against top-down market sizing from ministry of health tender disclosures.
Segmentation dimensions modeled span product architecture, end-user concentration, technology platform, and distribution channel structure across the projection horizon. CAGRs were derived from installed base expansion rates and replacement cycle analysis, with nucleic acid amplification platform adoption curves and lateral-flow strip procurement volumes as hepatitis-specific forecast inputs.
Underlying assumptions cover regulatory harmonization trajectories between stringent and emerging market frameworks, with deviation risk concentrated in EU MDR notified body capacity constraints and polymerase enzyme supply concentration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
In-Vitro Diagnostic Services Market
Testing Services
Europe Point-Of-Care-Testing (POCT) Market
Testing Services
Global HPV Testing and Pap Test Market
Testing Services
Nicotine Testing Market
Testing Services
Global Enzyme Linked Immunosorbent Assay (ELISA) Testing Market
Testing Services
Arthropod-Borne Viral Infections Testing Market
Testing Services
Global CA 125 Test Market
Testing Services
Blood Pressure Test Market
Testing Services
Asia-Pacific Antimicrobial Susceptibility Testing Market
Testing Services
Global Efficacy Testing Market
Testing Services
Global Helicobacter Pylori (H. Pylori) Non-Invasive Testing Market
Testing Services
Europe Mass Spectrometry Market
Testing Services
Service Laboratory Market
Testing Services
Global Terminal Sterilization Services Market
Testing Services
Global Extractables and Leachables Testing Services Market
Testing Services
Pharmaceutical Dosage Form Testing Systems Market