
 Rail Composites Market | 2026-2036
Rail Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Rail Composites Market Intelligence
High-speed rail procurement is hardening as the dominant demand vertical, while freight wagon refurbishment is softening across mature networks. Gurit Holdings AG leverages its prepreg expertise to anchor supply relationships with European train builders. Hexcel Corporation sustains aerospace-grade carbon fiber qualification protocols that transfer directly to rail structural applications. Toray Industries, Inc. dominates Asian supply chains through integrated PAN precursor-to-fabric verticality.
Rail composites encompass fiber-reinforced polymer materials engineered for specific strength-to-weight ratios, typically incorporating glass, carbon, or natural fibers within epoxy, polyester, or phenolic resin matrices cured through autoclave, resin transfer molding, or pultrusion processes. These materials serve primarily to reduce mass, extend service intervals, and meet stringent fire-smoke-toxicity requirements in rolling stock construction. Glass fiber composites occupy the largest volume share across interior panels and non-structural cladding where cost sensitivity outweighs performance premiums. Carbon fiber composites represent the fastest-expanding category in structural bogie frames and body shells for high-speed platforms where every kilogram removed translates to energy savings and track wear reduction. Hybrid composites capture emerging interest among infrastructure developers seeking optimized property blends for platform edge doors and tunnel lining segments.
The European Union's EN 45545 standard governs fire behavior of materials in rail vehicles, compelling resin system reformulation toward halogen-free intumescent chemistries. The Federal Railroad Administration in the United States enforces crashworthiness criteria that shape laminate architecture and energy-absorbing composite geometries for domestic passenger equipment. China's GB/T standardization framework and Ministry of Environmental Protection directives simultaneously address structural performance metrics and volatile organic compound emissions from manufacturing processes. Stakeholders must monitor evolving national rail procurement frameworks that increasingly embed lifecycle carbon accounting alongside upfront material specifications.
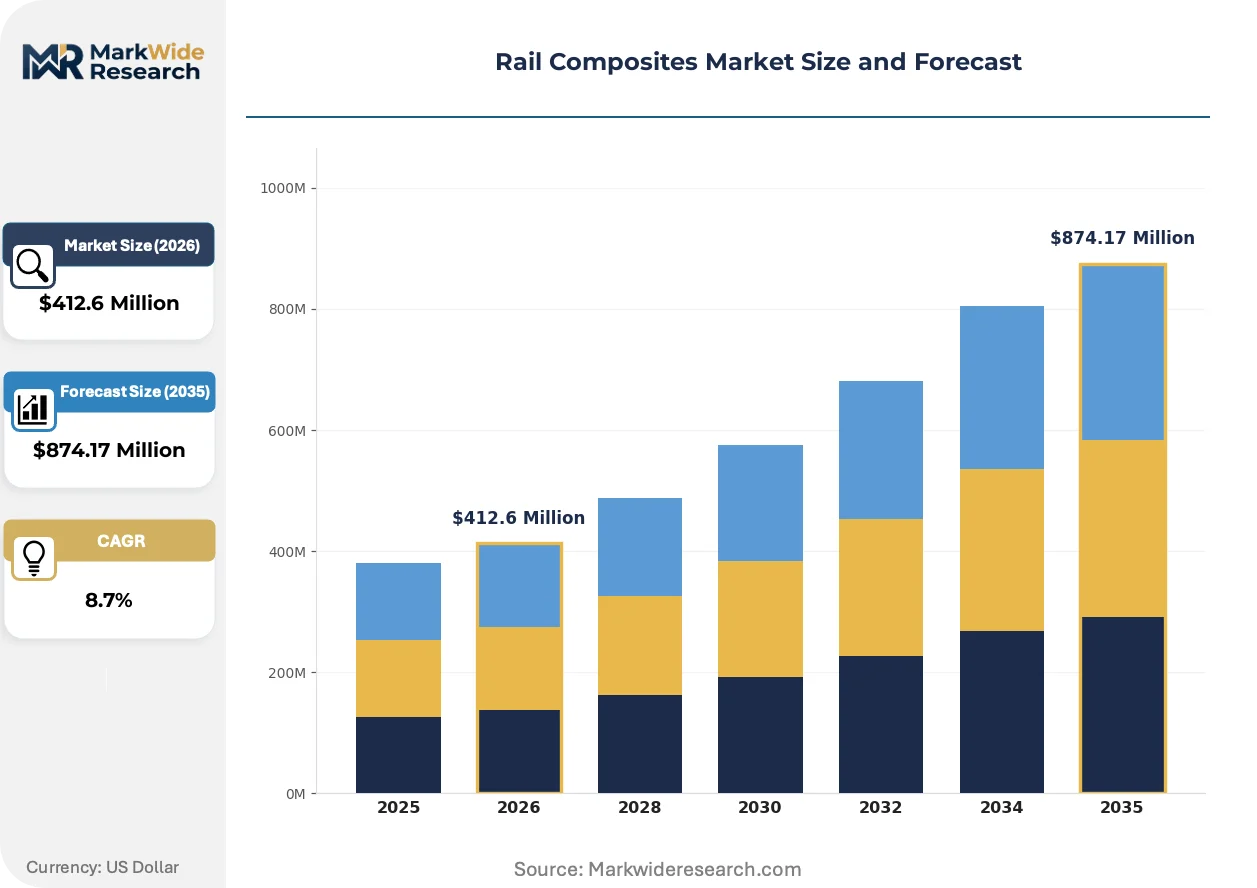
Market Dynamics
European EN 45545 fire safety mandates are forcing resin system reformulation across the entire supply base, while Asian high-speed rail procurement compresses qualification timelines for structural carbon fiber laminates.
Growth Catalysts
- High-speed rail expansion:China's intercity network and India's metro corridors are hardening demand for lightweight body shells and bogie frames that reduce track wear and energy consumption.
- EN 45545 compliance mandates:European fire-smoke-toxicity standards are compelling manufacturers to certify halogen-free intumescent thermoset formulations for interior applications.
- Freight wagon refurbishment cycles:Mature European and North American networks are replacing steel superstructures with corrosion-resistant glass fiber composites to extend service intervals.
Market Restraints
- Acrylonitrile price volatility:Carbon fiber precursor costs fluctuate with oil-derived feedstock markets, compressing margin visibility for structural composite suppliers.
- Asian supply concentration:Integrated PAN precursor-to-fabric production clusters in Japan and China create geographic dependency risk for European and North American laminators.
- Autoclave curing bottlenecks:Large-dimension rail components require energy-intensive thermal processing that limits throughput and capital efficiency.
Strategic Opportunities
- Natural fiber hybridization:Flax and jute reinforcement blends are penetrating non-structural interior panels where fire regulations permit bio-based alternatives.
- India's metro buildout:The country's urban rail expansion corridors present uncaptured demand for certified interior composite systems and platform edge door assemblies.
- Lifecycle carbon accounting:EU Green Deal procurement frameworks are embedding embodied carbon metrics that favor lightweight composite substitution over aluminum.
Industry Challenges
- Multi-standard certification complexity:Suppliers must simultaneously qualify products under EN 45545, China's GB/T framework, and Federal Railroad Administration crashworthiness criteria.
- Resin transfer molding scale-up:Transitioning from aerospace batch processes to rail-appropriate continuous production requires capital-intensive tooling and process engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rail Composites Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Fiber Composites, Glass Fiber Composites, Carbon Fiber Composites, Hybrid Composites End User: Rail Vehicle Manufacturers, Maintenance Providers, Infrastructure Developers, Rail Operators Application: Interior Components, Exterior Components, Structural Parts, Insulation Materials Installation Method: Adhesive Bonding, Mechanical Fastening, Coating, Integrated Molding |
| Companies Covered | Gurit Holdings AG, Hexcel Corporation, 3A Composites, Toray Industries, Inc., Solvay, Teijin Limited, Avient Corporation, BASF SE, Exel Composites, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rail Composites Market Strategic Shifts & Innovations
Digital twin integration and automated fiber placement are compressing development cycles for structural rail components, while regulatory carbon accounting is rewriting material selection criteria across procurement frameworks.
Automated fiber placement with in-situ consolidation is rewriting the economics of large rail body shell production. European train builders are adopting these systems to reduce touch labor and improve laminate consistency. The technology is compressing the cost gap between composite and aluminum structures for high-speed platforms.
REACH restrictions on halogenated flame retardants are forcing resin formulators toward phosphorus-nitrogen intumescent chemistries. This regulatory pressure is fragmenting the supplier base between compliant European specialists and reformulating Asian producers. Interior panel applications face the steepest compliance timeline pressures.
Lifecycle service contracting is displacing traditional component sales in European rolling stock procurement. Train operators are bundling composite structural maintenance into multi-decade fleet management agreements. This shift concentrates buyer power with large fleet operators in Germany and France.
Rail Composites Market Segmentation
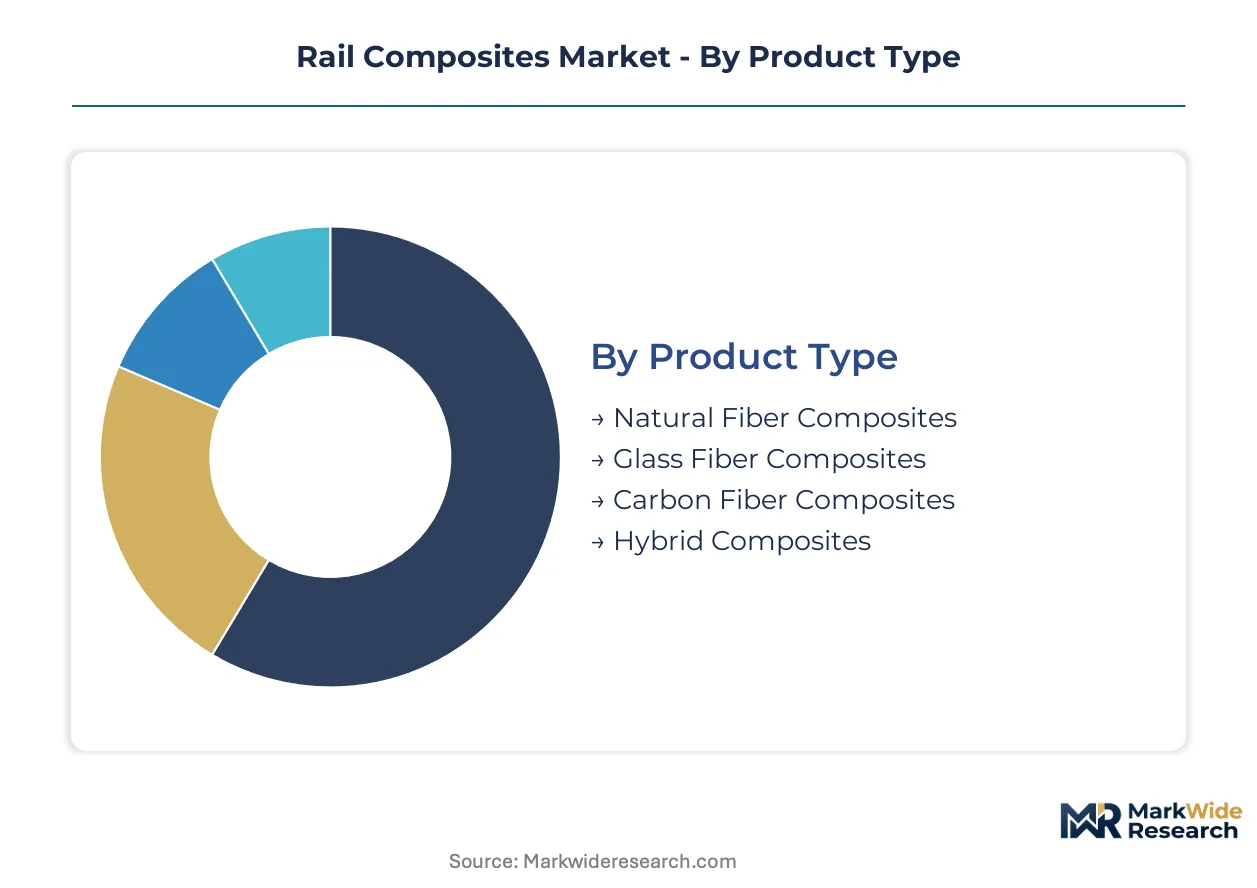
Rail composites demand fragments across four distinct category axes. Product type determines performance tier and regulatory compliance burden. End user concentration shapes procurement scale and lifecycle contracting models.
Product Type:
Standardization dominates commodity glass fiber grades, while carbon fiber specifications fragment across high-speed rail platforms demanding tailored mechanical properties.
- Glass Fiber Composites:E-glass and S-glass reinforcements within epoxy or polyester matrices serve interior panels and non-structural cladding. Demand concentrates in India's metro expansion corridors where cost sensitivity outweighs performance premiums for station fixtures and passenger compartment linings.
- Carbon Fiber Composites:PAN-based carbon fiber prepregs with toughened epoxy formulations deliver specific strength-to-weight ratios exceeding 300 kN·m/kg. Procurement hardens for China's intercity high-speed fleet where bogie frame mass reduction directly reduces track wear and energy consumption per passenger-kilometer.
- Natural Fiber Composites:Flax and jute reinforcements within bio-based resins penetrate non-structural interior applications where fire regulations permit renewable alternatives.
- Hybrid Composites:Glass-carbon or natural-synthetic fiber blends optimize property-cost tradeoffs for platform edge doors and tunnel lining segments.
Leading the category by volume: Glass Fiber Composites. Expanding most quickly: Carbon Fiber Composites.
End User:
OEM procurement scales concentrate with large fleet operators, while maintenance providers fragment across decentralized refurbishment networks.
- Rail Vehicle Manufacturers:Alstom, Siemens, and CRRC anchor composite demand through original equipment specifications for new rolling stock. Their procurement frameworks embed EN 45545 fire certification and lifecycle carbon accounting requirements that filter supplier qualification.
- Rail Operators:Deutsche Bahn and SNCF are displacing component sales with multi-decade service contracts bundling structural maintenance. This shift concentrates buyer power and demands predictive analytics integration from composite suppliers.
- Maintenance Providers:Regional refurbishment specialists replace corroded steel superstructures with glass fiber composites across European and North American freight wagon fleets.
- Infrastructure Developers:Platform and tunnel construction consortia specify hybrid composites for edge doors and lining segments requiring combined structural and environmental performance.
Dominating procurement scale: Rail Vehicle Manufacturers. Gaining contract sophistication fastest: Rail Operators.
Application:
Interior applications face the steepest regulatory compliance timelines, while structural parts command the highest qualification barriers.
- Interior Components:Wall panels, ceiling systems, and seating shells require halogen-free intumescent formulations meeting EN 45545 HL3 fire-smoke-toxicity criteria. REACH restrictions on brominated flame retardants are forcing resin system reformulation across European supply chains.
- Structural Parts:Bogie frames, body shells, and load-bearing underframes demand aerospace-grade carbon fiber qualification protocols transferred to rail specifications. Federal Railroad Administration crashworthiness criteria shape laminate architecture and energy-absorbing geometries for US passenger equipment.
- Exterior Components:Roof fairings, nose cones, and aerodynamic skirts balance weathering resistance with mass reduction targets.
- Insulation Materials:Thermal and acoustic barrier layers integrate multi-layer composite architectures for passenger comfort and energy efficiency.
Steepest regulatory pressure: Interior Components. Highest technical barriers: Structural Parts.
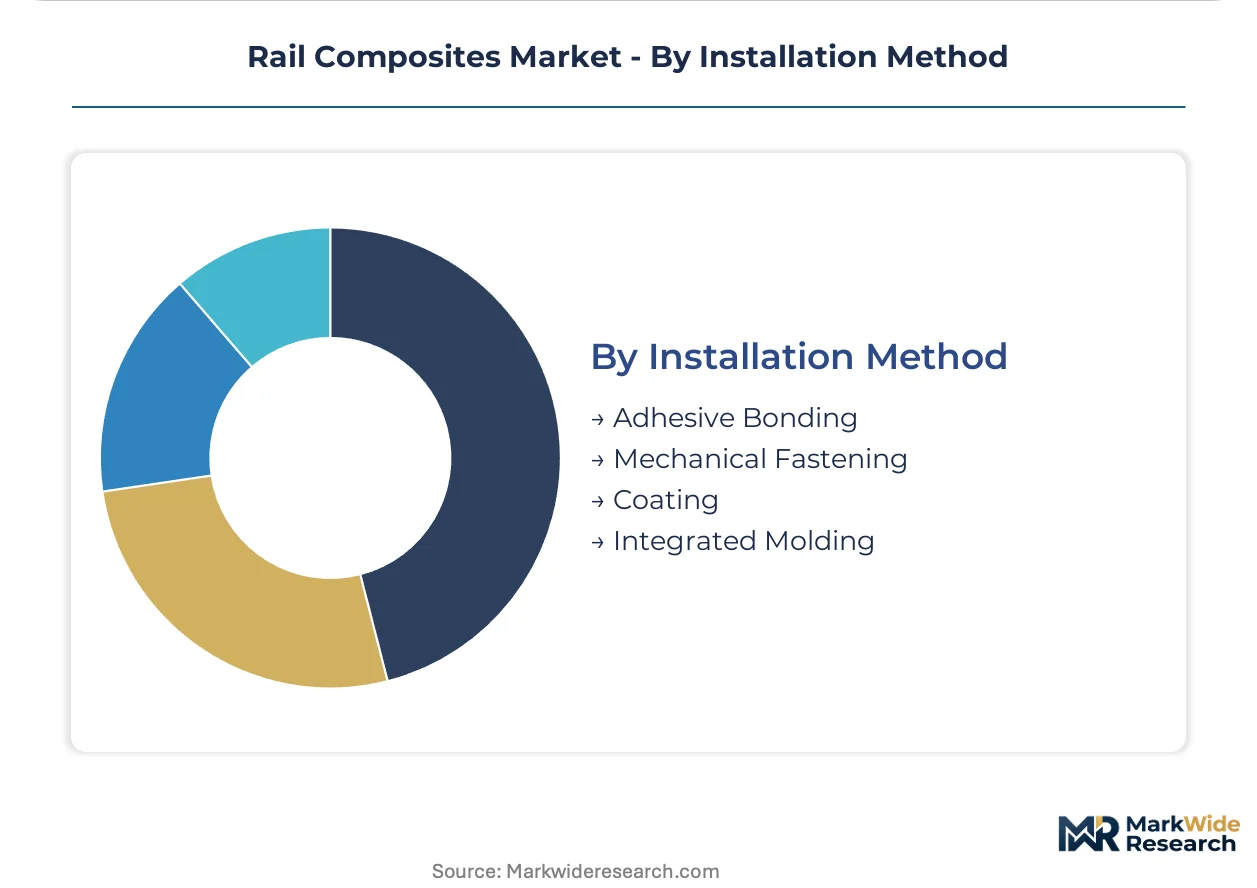
Installation Method:
Adhesive bonding scales with OEM production lines, while mechanical fastening persists in field refurbishment contexts.
- Adhesive Bonding:Structural acrylic and epoxy adhesives enable continuous stress distribution across large body shell assemblies. Automated dispensing systems integrate with fiber placement robotics at European train builder facilities.
- Integrated Molding:Resin transfer molding and compression molding consolidate multi-component assemblies into single cure cycles, reducing touch labor and interface variability.
- Mechanical Fastening:Bolted and riveted joints dominate maintenance provider workflows for wagon refurbishment where disassembly access remains critical.
- Coating:Protective and decorative surface treatments extend service intervals for exterior components exposed to UV, moisture, and particulate abrasion.
Scaling with production automation: Adhesive Bonding. Dominating refurbishment workflows: Mechanical Fastening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asian manufacturing clusters dominate rail composites supply, while European and North American markets concentrate consumption within high-specification rolling stock procurement. China and Japan anchor precursor-to-fabric production, creating geographic asymmetry between material origin and end-use demand.
China
CRRC's high-speed fleet expansion drives structural carbon fiber demand for bogie frames and body shells. The Ministry of Environmental Protection enforces volatile organic compound emission limits on manufacturing processes. The Yangtze River Delta hosts integrated PAN precursor-to-prepreg facilities serving domestic train builders.
Germany
Deutsche Bahn's lifecycle service contracts concentrate buyer power for composite structural maintenance. The Federal Railway Authority enforces crashworthiness criteria that shape laminate architecture for domestic passenger equipment. Bavaria's rail manufacturing corridor around Munich and Nuremberg anchors Alstom and Siemens procurement specifications.
United States
Freight wagon refurbishment cycles sustain glass fiber demand for corrosion-resistant superstructures. The Federal Railroad Administration mandates energy-absorbing composite geometries for passenger equipment crashworthiness. Midwestern rail maintenance clusters in Illinois and Ohio execute steel-to-composite conversions for Class I railroads.
India
Metro expansion corridors in Delhi, Mumbai, and Bangalore harden demand for certified interior composite systems. The Bureau of Indian Standards implements fire safety protocols aligned with EN 45545 frameworks. Gujarat's industrial belt hosts emerging fabrication capacity for platform edge door assemblies and station fixtures.
Japan
Shinkansen fleet renewal sustains aerospace-grade carbon fiber qualification for rail structural applications. METI oversees standardization frameworks for composite performance metrics in rolling stock. The Chubu region around Nagoya maintains integrated precursor-to-fabric verticality serving domestic and export markets.
Rail Composites Market Key Industry Players
Top-tier vendors anchor supply relationships with European and Asian train builders, while mid-tier specialists occupy regional refurbishment niches. The market structure reflects tiered qualification barriers: aerospace-grade carbon fiber producers leverage existing certification protocols, while glass fiber fabricators compete on cost for interior applications. Strategic archetypes include integrated chemical conglomerates with captive resin formulation, specialized prepreg manufacturers with rail-specific fire certification, and pultrusion-focused regional suppliers. Competitive moves concentrate on backward integration into PAN precursor production and multi-standard certification bundling for cross-border procurement.
Among Swiss-headquartered specialists, Gurit Holdings AG occupies a position exemplifying prepreg-centric supply relationships with European rolling stock manufacturers. Hexcel Corporation represents the aerospace-to-rail certification transfer archetype, leveraging existing qualification protocols for structural carbon fiber applications. Toray Industries, Inc. anchors the integrated production model, with its name signaling Japanese origin and vertical control from precursor through fabric stages.
| Leading Market Players |
|---|
| Gurit Holdings AG |
| Hexcel Corporation |
| 3A Composites |
| Toray Industries, Inc. |
| Solvay |
| Teijin Limited |
| Avient Corporation |
| BASF SE |
| Exel Composites |
| Others |
Cost & Logistics Intelligence
Backward integration into PAN precursor production anchors both supply security and pricing power for structural carbon fiber suppliers serving Asian high-speed rail OEMs. European glass fiber fabricators without captive resin formulation face margin compression as acrylonitrile volatility feeds through to laminate costs.
Pricing Analysis
Short lead-time premiums separate urgent procurement for India's metro buildout from contract-indexed pricing for CRRC's scheduled fleet renewals. Three-tier pricing structure across aerospace-qualified, rail-certified, and commodity glass fiber grades reflects EN 45545 compliance investment and volume scale. Cost compression in standard E-glass interior panels is intensifying because Indian cost-sensitive procurement is displacing European specification premiums. Freight wagon refurbishment specialists exhibit highest price sensitivity; high-speed rail OEMs absorb performance premiums for bogie frame mass reduction.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and Chinese PAN precursor-to-fabric clusters that feed structural carbon fiber demand. Raw material dependencies draw from petroleum-derived acrylonitrile, epoxy resin formulations, and halogen-free intumescent additives. Geographic concentration in the Yangtze River Delta and Chubu region creates tariff exposure risk for European laminators sourcing Asian prepregs. Distribution runs through qualified supplier programs at Alstom, Siemens, and CRRC that filter tier-2 fabricators from direct OEM access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around multi-standard certification capability as EN 45545, GB/T, and FRA crashworthiness criteria eliminate single-regional players. Smaller fabricators without fire-chemistry expertise or aerospace-grade qualification protocols are exiting.
For Market Incumbents: Hedge resin cost exposure through captive formulation or long-term acrylonitrile offtake agreements. Deepen EN 45545 HL3 certification portfolios ahead of REACH flame retardant restrictions. Anchor supply position with Deutsche Bahn and SNCF lifecycle service contracts that bundle predictive maintenance analytics. For New Entrants and Emerging Players: Digital-channel qualification platforms offer low-friction entry for India's metro component procurement, where BIS fire safety alignment with EN 45545 creates certification arbitrage. Target platform edge door assemblies and station fixtures in Gujarat's industrial belt. Pursue natural fiber hybridization for non-structural interior panels where fire regulations permit bio-based alternatives. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated chemical conglomerates seeking rail-specific fire certification. Five-to-ten-year viability hinges on backward integration into precursor production or multi-standard qualification bundling. Monitor acrylonitrile price volatility as inflection indicator for structural composite margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PAN Precursor | Toray's captive supply chain insulates margin from oil-derived feedstock volatility. |
| Multi-Standard Certification Bundling | Gurit's simultaneous EN 45545 and FRA qualification opens cross-border procurement. |
| Automated Fiber Placement Scale-Up | European train builders reduce touch labor for large body shell assemblies. |
| Natural Fiber Hybridization R&D | Flax-epoxy formulations penetrate interior panels under REACH-aligned fire protocols. |
| Lifecycle Service Contracting | Deutsche Bahn bundles composite maintenance into multi-decade fleet management agreements. |
Research Approach
Document review covered customs trade data for carbon fiber and glass fiber imports, SEC filings from composite manufacturers, EN 45545 certification registries, and railway procurement disclosures, complemented by interviews with plant managers at European prepreg facilities, procurement leads at CRRC and Alstom, technical R&D directors at resin formulators, and maintenance directors at Deutsche Bahn refurbishment depots. Secondary validation drew from railway industry association reports, academic composites research, and Ministry of Environmental Protection emission disclosures. Bottom-up segment sizing triangulated against top-down OEM production forecasts.
Cross-referencing historical laminate adoption rates with panel input from train builder engineering teams shaped the analytical framework across the analysis window. Segmentation dimensions modeled include fiber type, application tier, end-user procurement scale, installation method, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating high-speed rail fleet expansion schedules and freight wagon replacement cycles. Forecast inputs incorporated EN 45545 compliance timeline acceleration and India's metro corridor commissioning pace.
The model holds under stable acrylonitrile pricing and continued EN 45545 harmonization across EU member states; deviation in oil feedstock volatility or regulatory fragmentation would shift composite substitution economics versus aluminum. Forecasts reflect assumptions about certification timeline compression and OEM qualification backlog clearance. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Locomotive Maintenance Market
Railway
Automatic Train Control Market
Railway
Railway Axle Market
Railway
Global Smart Locomotive Market
Railway
Solar Powered Train Market
Railway
Railroad Brake Shoe Market
Railway
Railway Window Market
Railway
Railroad Tie Market
Railway
Latin America Connected Rail Market
Railway
Global Train Lighting Market
Railway
Global High-Speed Train Seat Market
Railway
Rail Seat Market
Railway
Railway Buffer Stops Market
Railway
Sanitary Systems for Rail Transit Market
Railway
Train Bogie Market
Railway
Locomotive Radiator Fan Market