
 Latin America Connected Rail Market | 2026-2036
Latin America Connected Rail Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Connected Rail Market Analytics
Market Context
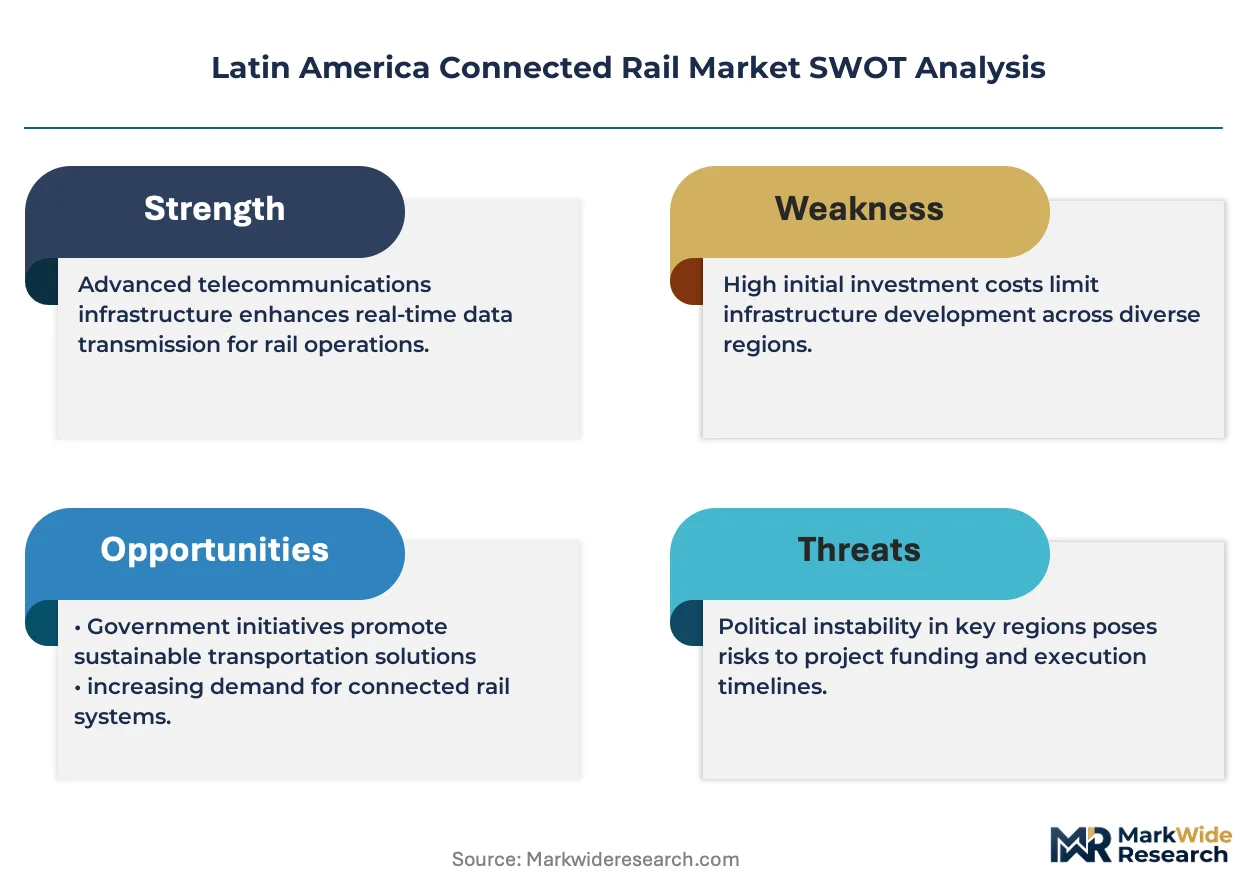
A shortage of rail systems engineers with IoT and cybersecurity credentials is redrawing competitive dynamics across Latin America. Siemens Mobility leverages its digital signaling heritage to anchor projects in Brazil and Argentina. Alstom SA competes through integrated smart train platforms designed for tropical climate resilience. Hitachi Rail sustains market presence via predictive maintenance systems tailored to Latin American freight corridors.
Technical Definition and Segments
Latin America Connected Rail encompasses rail infrastructure and rolling stock integrated with real-time data exchange, GPS positioning, onboard sensors, and centralized control systems to optimize safety, scheduling, and asset utilization across passenger and freight networks. Signal Systems within the Product Type category command concentrated investment as legacy interlocking upgrades drive near-term spending, while IoT Solutions across the Technology dimension represent the fastest expansion vector through sensor-based condition monitoring. Public Transport Authorities among End Users dominate procurement volume for urban metro digitization, whereas Freight Operators concentrate margin pools through long-term predictive analytics contracts spanning multi-year concession agreements.
Regulatory and Forward Outlook
Brazil's ANTT, Mexico's SCT, and Argentina's CNRT collectively shape market access through mandatory communications-based train control timelines and local content requirements for rail technology procurement. ANTT's freight concession renewal rules now embed digital performance benchmarks, forcing technology refresh cycles across operator fleets. Stakeholders must weigh regulatory divergence against platform standardization as each national regulator advances distinct connectivity protocols and certification pathways.
Market Dynamics
Brazil's ANTT freight concession renewal rules now embed digital performance benchmarks, forcing technology refresh cycles across operator fleets and redrawing vendor procurement patterns.
Growth Catalysts
- ANTT Digital Mandates:Brazil's freight rail regulator requires IoT-enabled fleet monitoring in renewed concessions, compelling operators to upgrade legacy signaling.
- Freight Corridor Concentration:Heavy traffic on São Paulo–Santos and Mexico City–Querétaro axes generates concentrated demand for predictive maintenance systems.
- Edge Computing:Real-time sensor processing at trackside nodes is reducing latency for safety-critical applications across tropical networks.
Market Restraints
- Specialized Talent Scarcity:Rail systems engineers with combined IoT and cybersecurity credentials command premium wages, inflating project delivery costs.
- Import Dependency:Critical signaling components concentrate supply among European and Asian manufacturers, exposing operators to currency volatility and extended lead times.
- Legacy Interlocking Lock-in:Existing electromechanical systems in Argentina and Chile resist seamless digital overlay without complete infrastructure replacement.
Strategic Opportunities
- Colombia Atlantic Corridor:Underdeveloped rail connectivity between Barranquilla and Bogotá offers first-mover advantage for integrated smart train platforms.
- 5G-Rail Convergence:Combining dedicated railway communications with public 5G networks promises cost reduction for regional operators outside major freight axes.
- Peru Mining Rail:Mineral export corridors from Andean pits to Pacific ports lack digitization, creating demand for autonomous haulage and remote monitoring systems.
Industry Challenges
- Cybersecurity Certification:Fragmented national standards across Brazil, Mexico, and Argentina delay product homologation and inflate compliance costs for multi-country deployments.
- Interoperability Complexity:Proprietary protocols from incumbent vendors obstruct data exchange between rolling stock and trackside infrastructure, forcing costly integration middleware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Connected Rail Market |
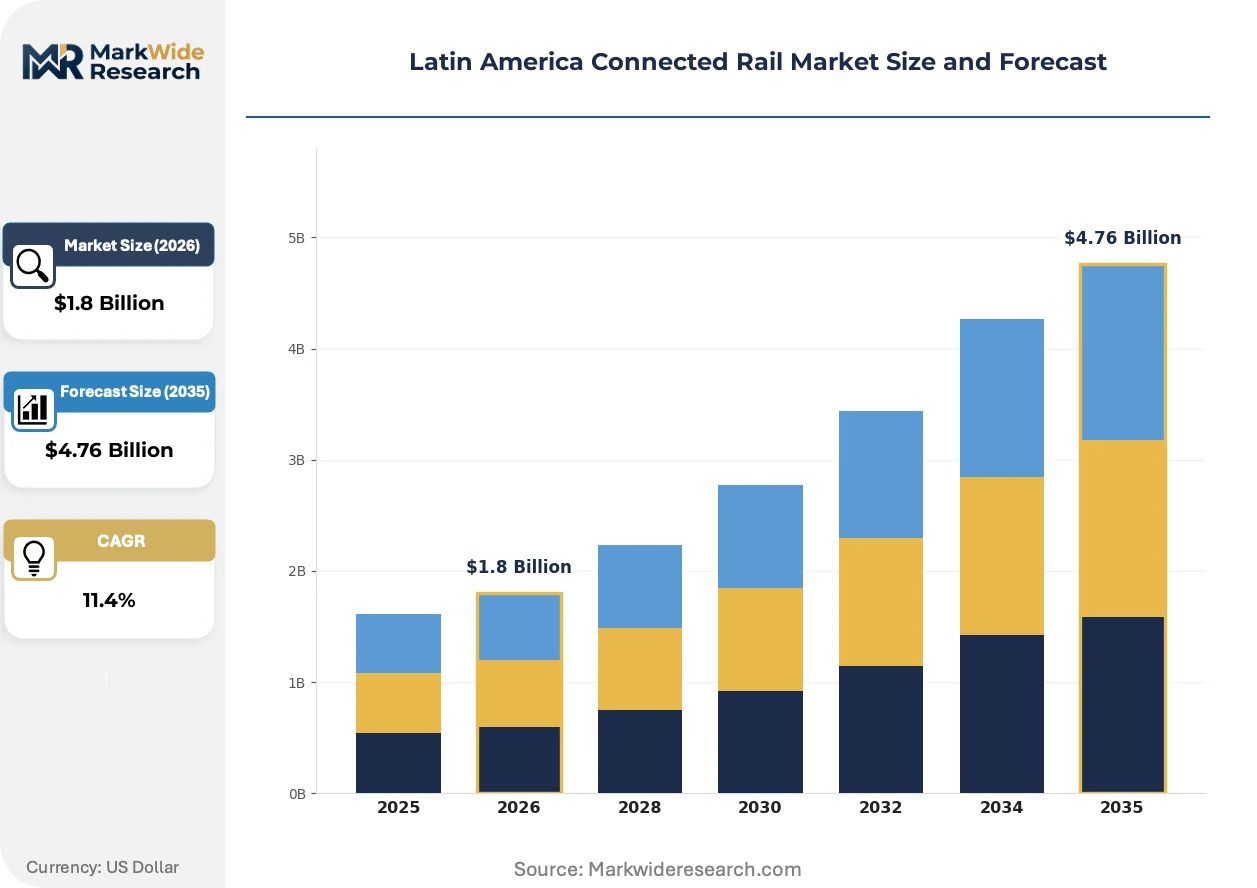
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Locomotives, Passenger Coaches, Freight Cars, Signal Systems Technology: IoT Solutions, Big Data Analytics, Cloud Computing, Artificial Intelligence End User: Public Transport Authorities, Freight Operators, Rail Operators, Government Agencies Service Type: Maintenance, Consulting, Integration, Support |
| Companies Covered | Huawei Technologies Co., Ltd., International Business Machines Corporation, Siemens Mobility, Alstom SA, Wabtec, Hitachi Rail, Cisco Systems, Inc., Rail Vision Ltd., Robert Bosch GmbH, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Connected Rail Market Evolving Landscape
Digital twin architectures are compressing design-to-deployment cycles for rail infrastructure, while regulatory pressure on safety systems accelerates communications-based train control adoption.
Onboard sensor arrays for bearing temperature, wheel wear, and brake performance are miniaturizing from rack-mounted units to chip-scale packages. Freight operators in Brazil and Mexico are retrofitting these compact modules across existing locomotive fleets within 18-month rollout windows. This compression is miniaturizing the hardware footprint required for predictive maintenance, enabling deployment on older rolling stock without structural modification.
Brazil's ANTT now mandates digital performance reporting in all freight concession renewals, with compliance deadlines tied to contract anniversary dates. Operators must demonstrate real-time fleet visibility and automated incident logging to maintain operating licenses. The São Paulo–Santos corridor faces the most aggressive timeline, with concessionaires accelerating IoT platform procurement to meet 2026 certification requirements.
Long-term service contracts are displacing capital-heavy equipment purchases among Latin American freight operators. Concession holders now prefer 10-year availability agreements bundling hardware, software, and maintenance into per-kilometer fees. This model concentrates procurement authority with financial engineering teams rather than engineering departments, most visibly among Mexican mining-rail joint ventures seeking to preserve balance sheet capacity for mineral price cycles.
Latin America Connected Rail Market Segmentation
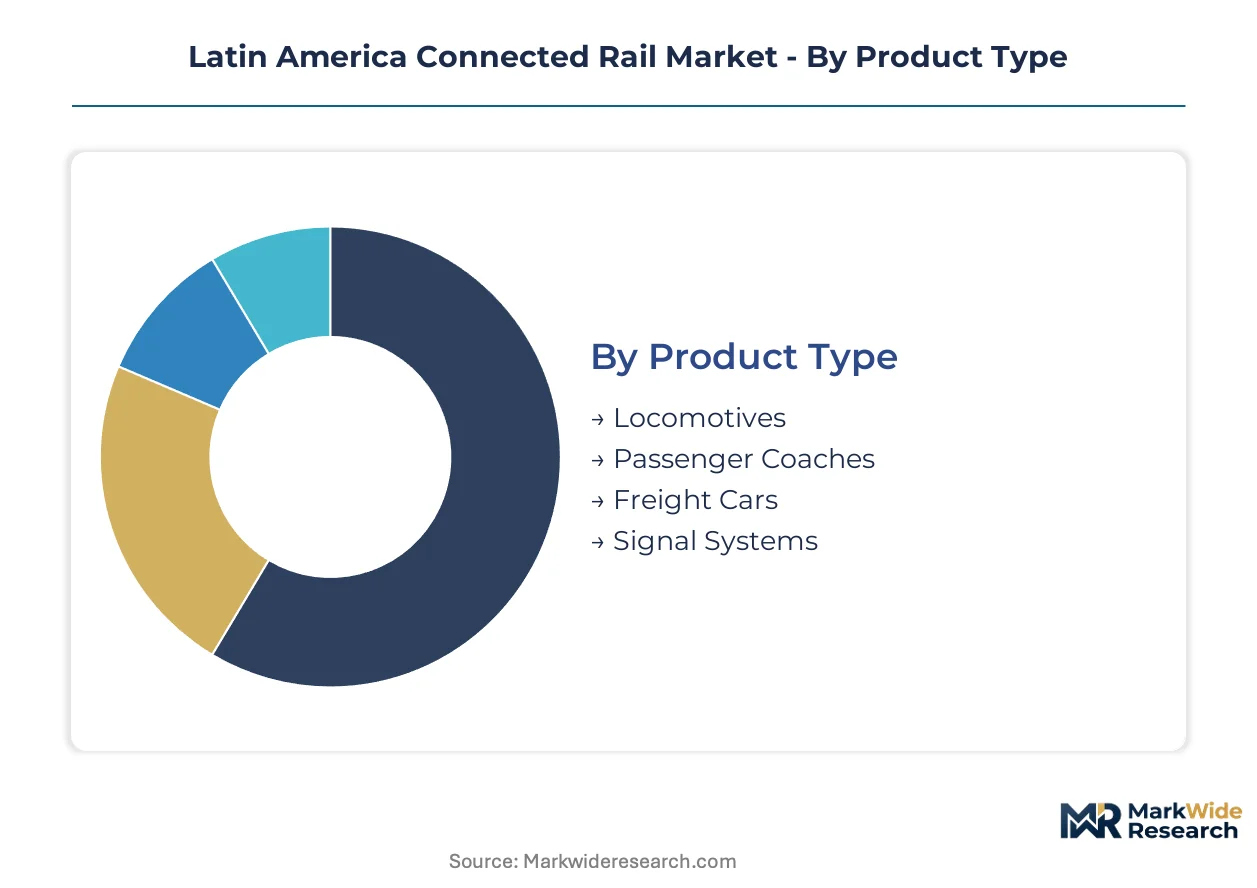
Latin American regulators embed distinct technical mandates across each segment category, forcing vendors to customize platforms for ANTT, SCT, and CNRT compliance rather than deploy standardized regional offerings. Segmentation clarity determines whether procurement teams prioritize hardware refresh cycles or long-term service bundling under concession financing structures.
Product Type:
Brazil's ANTT mandates differential equipment specifications for freight versus passenger corridors, while Mexico's SCT imposes separate certification tracks for urban metro and intercity rolling stock.
- Signal Systems:Communications-based train control hardware and legacy interlocking replacements absorb concentrated capital deployment. Brazil's São Paulo–Santos corridor drives procurement volume as concessionaires face ANTT-mandated digital performance deadlines for concession renewals.
- Locomotives:Diesel-electric and electric traction units equipped with onboard sensor arrays and GPS positioning modules. Freight operators across Brazil and Mexico retrofit compact predictive maintenance hardware to avoid balance sheet strain from full fleet replacement.
- Passenger Coaches:Urban metro and intercity rolling stock requiring climate-hardened connectivity for tropical humidity and temperature cycling.
- Freight Cars:Wagon-mounted telemetry for cargo monitoring, brake performance, and location tracking across mineral and agricultural corridors.
Established volume favors Signal Systems; emerging adoption favors Locomotives.
Technology:
Cost tier differentiation separates capital-intensive edge deployments from subscription-based cloud analytics, with freight operators gravitating toward operational expenditure models.
- IoT Solutions:Sensor networks for bearing temperature, wheel wear, and brake performance monitoring miniaturize to chip-scale packages. Brazil's freight concessionaires deploy these modules across existing fleets within compressed 18-month windows to meet ANTT reporting mandates.
- Big Data Analytics:Predictive maintenance algorithms processing historical failure patterns and real-time sensor streams. Mexico City–Querétaro freight operators contract multi-year analytics services tied to availability guarantees rather than capital purchases.
- Cloud Computing:Centralized data lakes for fleet-wide visibility and automated incident logging.
- Artificial Intelligence:Autonomous train operation and dynamic scheduling optimization for high-density corridors.
Freight procurement concentrates in Big Data Analytics; passenger networks are climbing the fastest with AI-driven traffic management.
End User:
Customer type determines contract structure, with public authorities favoring capital grants and private concessionaires preferring availability-based service agreements.
- Freight Operators:Private concessionaires under ANTT, SCT, and CNRT oversight deploying predictive maintenance to preserve operating licenses. Long-term per-kilometer service contracts displace equipment ownership across Brazilian and Mexican mining-rail joint ventures.
- Public Transport Authorities:State and municipal agencies procuring urban metro digitization through infrastructure bonds. São Paulo's metro authority anchors regional demand for integrated smart train platforms with tropical climate resilience specifications.
- Rail Operators:Integrated passenger and freight service providers managing mixed-use corridors.
- Government Agencies:National regulators and ministry departments funding rural connectivity and safety system standardization.
Procurement volume concentrates with Public Transport Authorities; margin expansion favors Freight Operators.
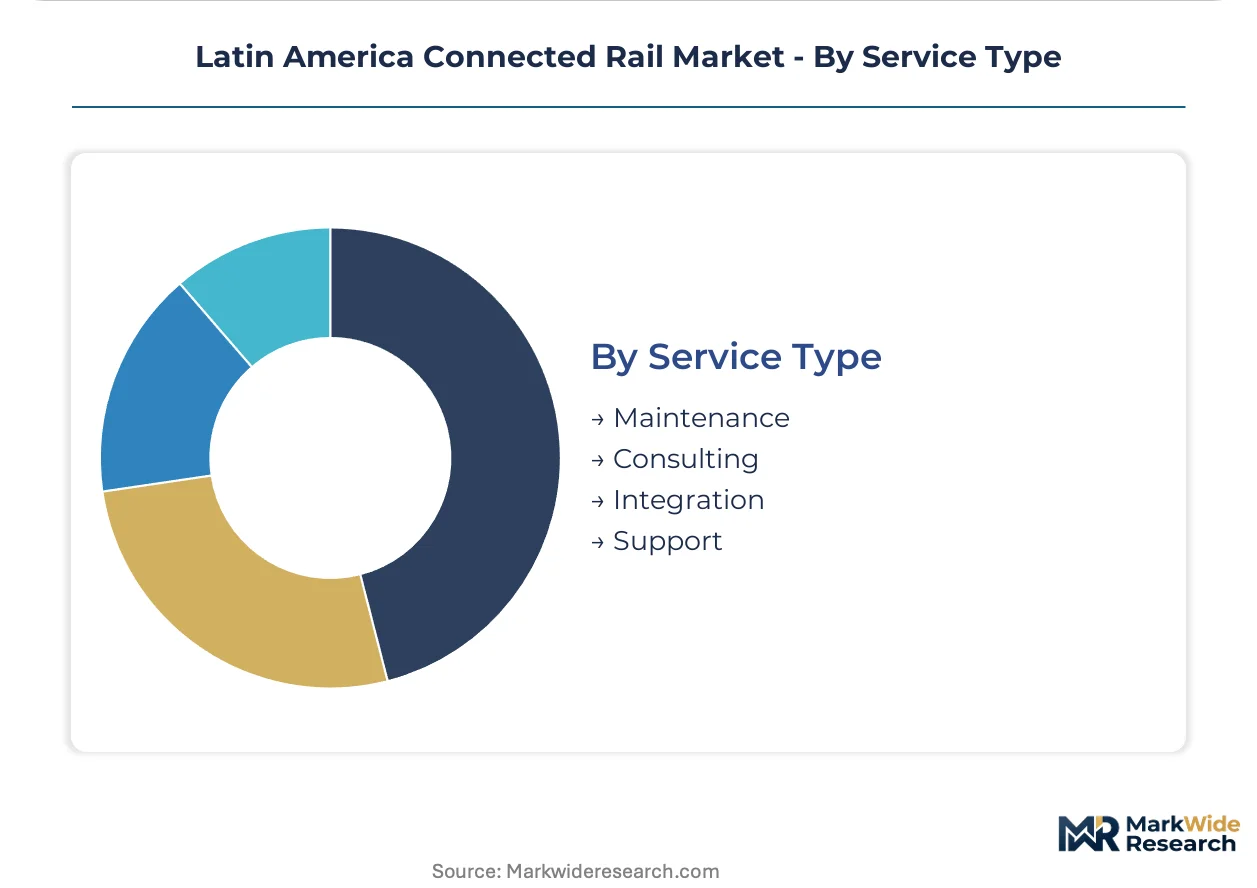
Service Type:
Supply concentration in European and Asian component manufacturers shapes whether operators source locally or import integrated service packages.
- Maintenance:Predictive and corrective services bundled into 10-year availability agreements. Mexican mining-rail ventures favor these structures to preserve balance sheet flexibility for mineral price volatility.
- Integration:Middleware development bridging proprietary vendor protocols with open-architecture control systems. Argentina's legacy electromechanical interlocking requires complete infrastructure replacement rather than seamless digital overlay.
- Consulting:Regulatory compliance and concession bid preparation for ANTT digital performance benchmarks.
- Support:Training and certification programs addressing scarcity of rail systems engineers with combined IoT and cybersecurity credentials.
Revenue stability favors Maintenance; capability building drives Support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANTT's freight concession renewal rules embed digital performance benchmarks that force technology refresh cycles across Brazilian operator fleets. Brazil anchors regional demand concentration, with Mexico and Argentina following distinct regulatory pathways for connected rail deployment.
Brazil
São Paulo–Santos corridor concessionaires face compressed 18-month procurement windows for IoT-enabled fleet monitoring. ANTT mandates real-time visibility and automated incident logging as license conditions. Rio de Janeiro and Minas Gerais freight operators accelerate predictive maintenance contracts to meet 2026 certification deadlines.
Mexico
Mexico City–Querétaro freight axis generates concentrated demand for sensor-based condition monitoring systems. SCT imposes separate certification tracks for urban metro versus intercity rolling stock, complicating vendor platform standardization. Nuevo León mining-rail joint ventures favor 10-year availability agreements bundling hardware and analytics into per-kilometer fees.
Argentina
Buenos Aires metro digitization drives procurement for climate-hardened connectivity platforms. CNRT advances distinct communications-based train control protocols that diverge from Brazilian and Mexican standards. Legacy electromechanical interlocking in Rosario and Córdoba resists seamless digital overlay without complete infrastructure replacement.
Chile
Antofagasta mineral export corridors create demand for autonomous haulage and remote monitoring systems. The country's national transport regulator mandates safety system upgrades on Andean pit-to-port routes. Santiago urban rail authorities pilot 5G-rail convergence combining dedicated railway communications with public networks.
Colombia
Underdeveloped Atlantic corridor connectivity between Barranquilla and Bogotá offers first-mover positioning for integrated smart train platforms. The national infrastructure agency evaluates concession structures for freight digitization. Medellín metro operators explore edge computing deployments for real-time sensor processing at trackside nodes.
Latin America Connected Rail Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding multi-country deployment authority through bundled hardware-software-service offerings. Mid-tier specialists compete on tropical climate adaptation and legacy system integration. Two strategic archetypes dominate: European rolling stock incumbents leveraging digital signaling heritage, and Asian telecom-equipment providers supplying communications infrastructure. Competitive moves concentrate on long-term service contract capture and regulatory certification pre-positioning.
Within the integrated systems tier, Siemens Mobility and Alstom SA occupy positions anchored by digital signaling platforms designed for concession-financed deployments. Hitachi Rail sits within the predictive maintenance specialist category, with its market presence tied to sensor-based condition monitoring contracts. Among communications infrastructure providers, Huawei Technologies Co., Ltd. exemplifies the Asian equipment archetype supplying trackside connectivity hardware.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| International Business Machines Corporation |
| Siemens Mobility |
| Alstom SA |
| Wabtec |
| Hitachi Rail |
| Cisco Systems, Inc. |
| Rail Vision Ltd. |
| Robert Bosch GmbH |
| Others |
Value Network & Pricing Analysis
Twenty-four-week lead times for communications-based train control hardware concentrate procurement authority among European rolling stock incumbents, compressing margin pools for Latin American freight operators facing ANTT-mandated digital refresh cycles. This supply bottleneck amplifies pricing power for vendors bundling hardware-software-service packages across Brazil's São Paulo–Santos corridor and Mexico's Mexico City–Querétaro freight axis.
Pricing Analysis
Price spreads between São Paulo and Buenos Aires deployments reach 35-40 percent for equivalent signaling hardware, reflecting import duty differentials and currency volatility exposure. Subscription-based availability agreements now dominate freight operator procurement, with per-kilometer fees bundling predictive maintenance analytics and hardware refresh cycles. Price differentiation hinges on tropical climate certification tiers and multi-country regulatory homologation breadth. Cost compression in standard-grade IoT sensor modules is intensifying because Brazilian concessionaires demand chip-scale packages for 18-month fleet retrofit windows. Public Transport Authorities exhibit highest price sensitivity due to municipal budget constraints, while mining-rail joint ventures prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Strategic stockpiling of critical signaling components has displaced just-in-time preferences among Latin American operators confronting 20-week order backlogs from German and Japanese manufacturers. Geographic supply concentration centers on Germany, France, and Japan for interlocking hardware, with China anchoring trackside communications infrastructure. Raw material dependencies span gallium nitride semiconductors, fiber-optic cable sheathing rated for tropical humidity, and rare-earth magnets for traction motor sensors. Single-source vulnerability in European safety-critical chip fabrication exposes operators to allocation rationing during automotive sector demand spikes. Distribution runs through concession-holder engineering departments rather than centralized procurement functions, fragmenting volume leverage across ANTT, SCT, and CNRT jurisdictional boundaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America Connected Rail functions as a regulatory-moat market where ANTT, SCT, and CNRT certification entrenchment creates switching costs that lock concession holders into incumbent vendor ecosystems. Network effects from interoperable fleet data standards compound this defensive positioning.
For Market Incumbents: Secure multi-country regulatory pre-certification for communications-based train control platforms before concession renewal waves peak, insulating against Asian telecom-equipment providers expanding from trackside connectivity into integrated systems. Deepen backward integration into tropical-hardened sensor manufacturing to compress 24-week hardware lead times threatening contract penalties. Prioritize São Paulo–Santos corridor reference installations as competitive ammunition for Colombia Atlantic Corridor bids.
For New Entrants and Emerging Players: Anchor in Peru's Andean mining-rail corridors where autonomous haulage demand outpaces established vendor coverage, exploiting 15-year mineral export concession windows for technology embedding. Target Medellín metro edge computing pilots as demonstration platforms for regional scalability. Pursue joint venture structures with Mexican mining-rail operators seeking balance sheet-friendly availability agreements rather than capital-intensive equipment purchases.
For Investors and Strategic Acquirers: Long-term, this sits as a concession-annuity play because 10-15 year operating licenses with embedded digital performance mandates generate recurring service revenue visibility. Acquisition candidates include predictive maintenance specialists with CNRT regulatory track records and tropical climate adaptation IP. Monitor ANTT freight concession renewal velocity as inflection indicator—accelerated 2026 certification deadlines signal procurement cycle compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Certification Investment | ANTT, SCT, and CNRT homologation ahead of concession renewals locks out unqualified competitors. |
| Peru Mining-Rail Joint Venture | Andean pit-to-port autonomous haulage partnerships capture 15-year mineral export infrastructure cycles. |
| Colombia Atlantic Corridor First-Mover Positioning | Barranquilla–Bogotá connectivity gaps offer integrated smart train platform deployment without legacy displacement costs. |
| 5G-Rail Convergence Pilot | Santiago urban rail trials of public network integration reduce dedicated communications infrastructure capital intensity. |
| Backward Integration into Tropical Sensor Manufacturing | In-house production of humidity-hardened chip-scale packages compresses 24-week procurement lead times. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with rail systems engineers, concession procurement directors, ANTT regulatory officials, and predictive maintenance software architects; and secondary validation against customs import records, ANTT concession renewal filings, SCT certification databases, and rolling stock manufacturer technical documentation. Bottom-up fleet deployment counts triangulated against top-down infrastructure investment flows from national development banks.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, technology tier, end-user contract structure, and service bundling intensity. CAGRs emerged from logistic diffusion curves fitted to regulatory mandate compliance deadlines and concession renewal schedules. Forecast inputs incorporated freight corridor traffic density projections and tropical climate hardware failure rate differentials.
Decision-makers should treat outputs as directional under assumptions of sustained ANTT digital mandate enforcement and stable mineral export demand from Andean mining operations; material deviation would warrant model refresh. Revision becomes warranted when Brazil's real effective exchange rate volatility exceeds 20 percent annual bands or when 5G spectrum allocation delays push rail communications convergence timelines beyond concession compliance windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Solar Train Market
Railway
Sanitary Systems for Rail Transit Market
Railway
South Korea Connected Rail Market
Railway
Automatic Train Control Market
Railway
Check Rails Market
Railway
Railway Axle Market
Railway
Railway System Market
Railway
Rail Brace Market
Railway
Railway Draft Gears Market
Railway
Bullet Train Market
Railway
Rail and Intermodal Decarbonization Strategy Consulting Market
Railway
Locomotive Radiator Fan Market
Railway
Tugger Trains Market
Railway
Gearbox for Rail Vehicles Market
Railway
Rail Brake Frame Market
Railway
Railroad Tie Market