
 Railway Axle Market | 2026-2036
Railway Axle Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Axle Market Analysis
Freight operators is collapsing as the dominant buyer archetype as passenger transport agencies and urban transit authorities accelerate fleet renewal programs. CRRC Corporation Limited leverages its integrated foundry-to-assembly footprint to dominate domestic procurement cycles across Chinese high-speed corridors. Siemens Mobility GmbH competes through technology leadership in hollow-bore and lightweight axle designs optimized for European interoperability standards. Lucchini RS S.p.A. anchors its position via deep specialization in forged solid axles for heavy-haul freight applications.
A railway axle is a machined steel shaft that transmits locomotive torque to wheelsets while bearing static and dynamic loads exceeding 20 tonnes per wheel; manufacturers typically employ vacuum-degassed alloy steel billets forged at temperatures above 1,100°C to achieve the fatigue resistance required for million-kilometre service intervals. Solid axles remain the volume backbone across freight and conventional passenger fleets due to proven durability and lower unit economics, while composite axles are gaining traction in high-speed train applications where unsprung mass reduction directly improves track adhesion and energy efficiency. The alloy steel material segment commands the premium margin pool as EN 13261 and AAR specifications mandate tighter grain structure control and non-destructive testing protocols.
The European Union Agency for Railways enforces EN 13261 compliance for all axles operating on trans-European networks, while the Association of American Railroads maintains M-101 standards that govern North American freight axle metallurgy and inspection intervals. India's Bureau of Indian Standards and Ministry of Railways have introduced localized axle specifications under the Make in India framework, compelling OEMs to establish domestic forging capacity or partner with local licensees. Stakeholders must monitor how divergent certification timelines between European harmonized standards and emerging Asian national codes reshape supplier qualification costs and regional competitive access.
Market Dynamics
Freight tonnage expansion across Asia-Pacific corridors is compressing axle replacement cycles, while EN 13261 and AAR M-101 certification tightening is raising supplier qualification barriers and reshaping competitive access.
Growth Catalysts
- Dedicated Freight Corridor buildout:India's Ministry of Railways is accelerating domestic axle procurement through Make in India localization mandates, forcing OEMs to establish captive forging capacity.
- EN 13261 harmonization:The European Union Agency for Railways is tightening grain structure control and non-destructive testing protocols, elevating alloy steel specifications across trans-European networks.
- Hollow-bore axle adoption:High-speed operators are specifying lightweight designs to reduce unsprung mass and improve track adhesion on million-kilometre service intervals.
Market Restraints
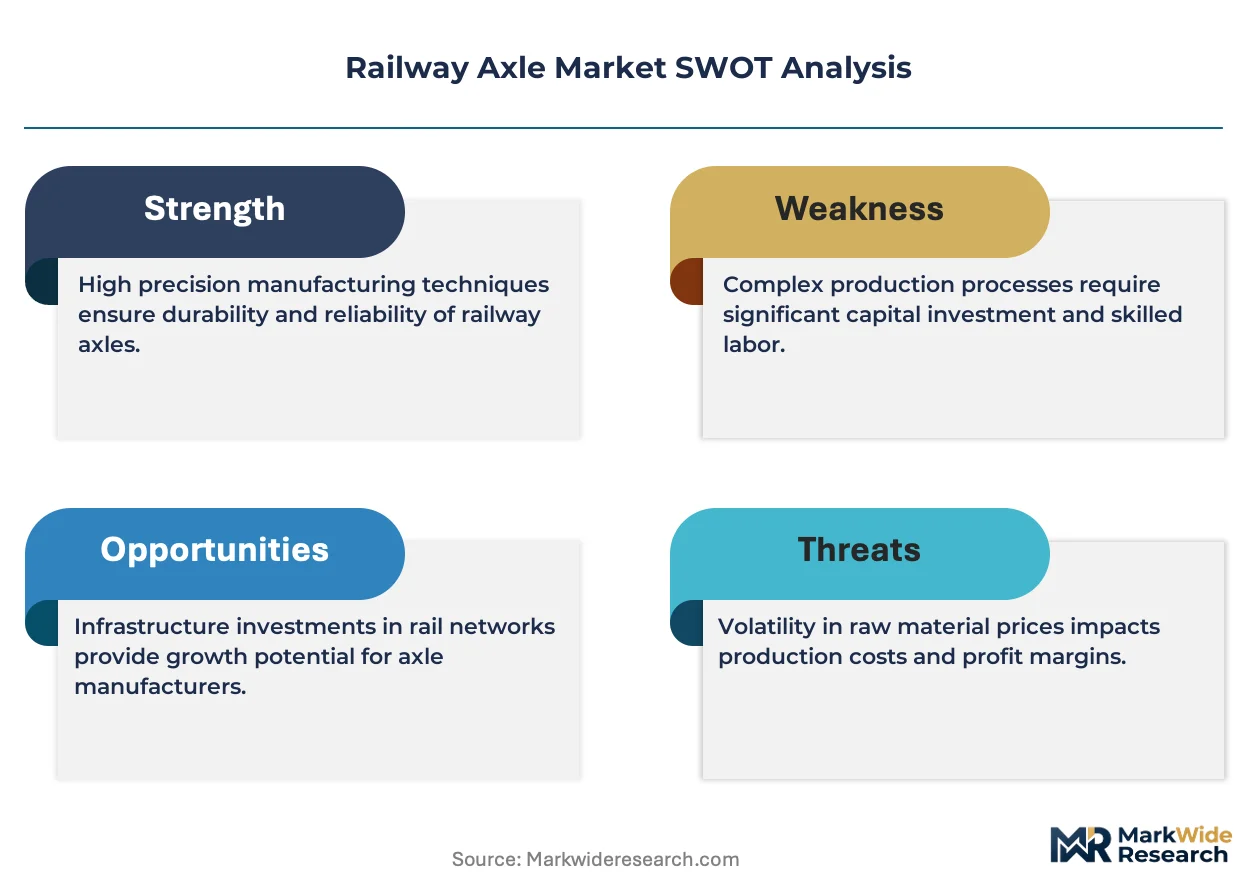
- Scrap steel volatility:Vacuum-degassed alloy steel billet costs fluctuate with ferrous scrap indexes, squeezing margin predictability for forged axle producers.
- Supplier concentration:Integrated foundry-to-assembly footprints in China dominate high-speed corridor procurement, limiting access for non-domestic competitors.
- Composite substitution ceiling:Carbon fiber axle designs face fatigue validation gaps under AAR M-101 inspection intervals, capping penetration in heavy-haul freight.
Strategic Opportunities
- Urban transit authorities:Metro rail expansions in India and Southeast Asia are creating dedicated procurement streams separate from national railway tenders.
- PLI scheme alignment:India's production-linked incentive framework for railway components offers cost offsets for domestic forging investments.
- Digital twin convergence:Predictive maintenance platforms paired with axle-mounted sensors are opening recurring revenue streams beyond unit sales.
Industry Challenges
- NDT technician scarcity:Ultrasonic and magnetic particle inspection certification programs are failing to match forging capacity expansion timelines.
- Dual standard compliance:Suppliers serving both EN 13261 and AAR M-101 markets face divergent documentation and audit cycle burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Axle Market |
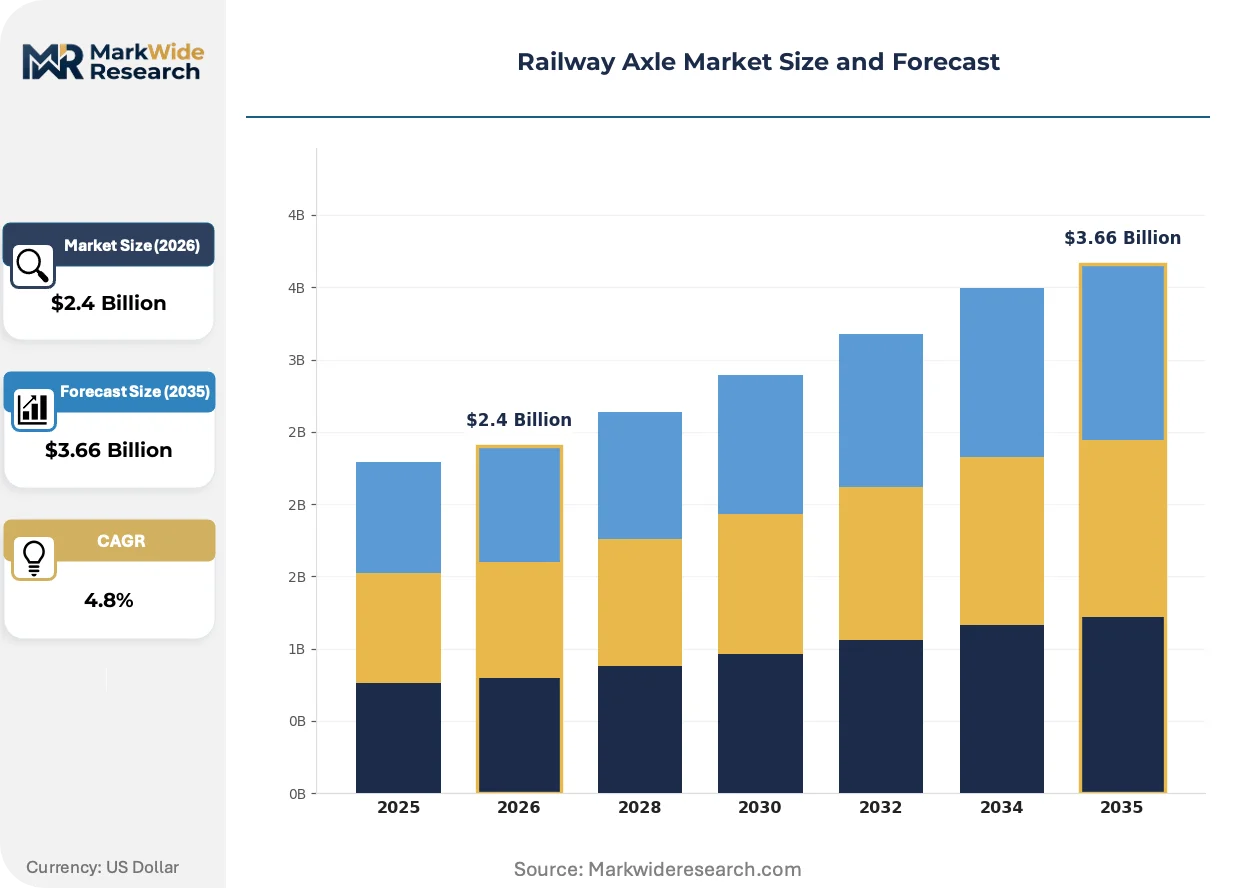
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.66 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Axles, Boxed Axles, Composite Axles, Forged Axles End User: Freight Operators, Passenger Transport, Maintenance Providers, OEMs Material: Carbon Steel, Alloy Steel, Cast Iron, Composite Materials Application: High-Speed Trains, Freight Trains, Urban Transit, Locomotives |
| Companies Covered | Lucchini RS S.p.A., Bombardier Transportation, CRRC Corporation Limited, SKF Group, Siemens Mobility GmbH, Amsted Rail Company, Inc., voestalpine AG, Interpipe, Alstom SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Axle Market Emerging Trajectories
Axle manufacturing is bifurcating between legacy solid designs and advanced lightweight architectures, with regulatory pressure and operational efficiency demands pulling development in parallel directions.
Additive manufacturing for axle bearing seats and brake disc interfaces is decomposing traditional machining workflows. European tier suppliers are piloting laser-deposited inconel coatings on hollow-bore designs to extend service intervals. This capability compression is enabling smaller forges to compete on complex geometries without full captive machining lines.
REACH substance restrictions are forcing reformulation of axle lubrication and corrosion protection chemistries. The European Chemicals Agency's candidate list expansion is compelling suppliers to substitute chromium-based coatings with phosphate alternatives. High-speed operators in Germany and France are front-loading qualification testing to avoid service disruptions from compliance deadlines.
Lifecycle service contracts are unbundling axle supply from wheelset maintenance. Freight operators in North America are negotiating availability-based agreements that transfer inspection liability to manufacturers. This model is compressing most visibly among Class I railroads seeking to outsource non-core maintenance functions.
Railway Axle Market Segmentation
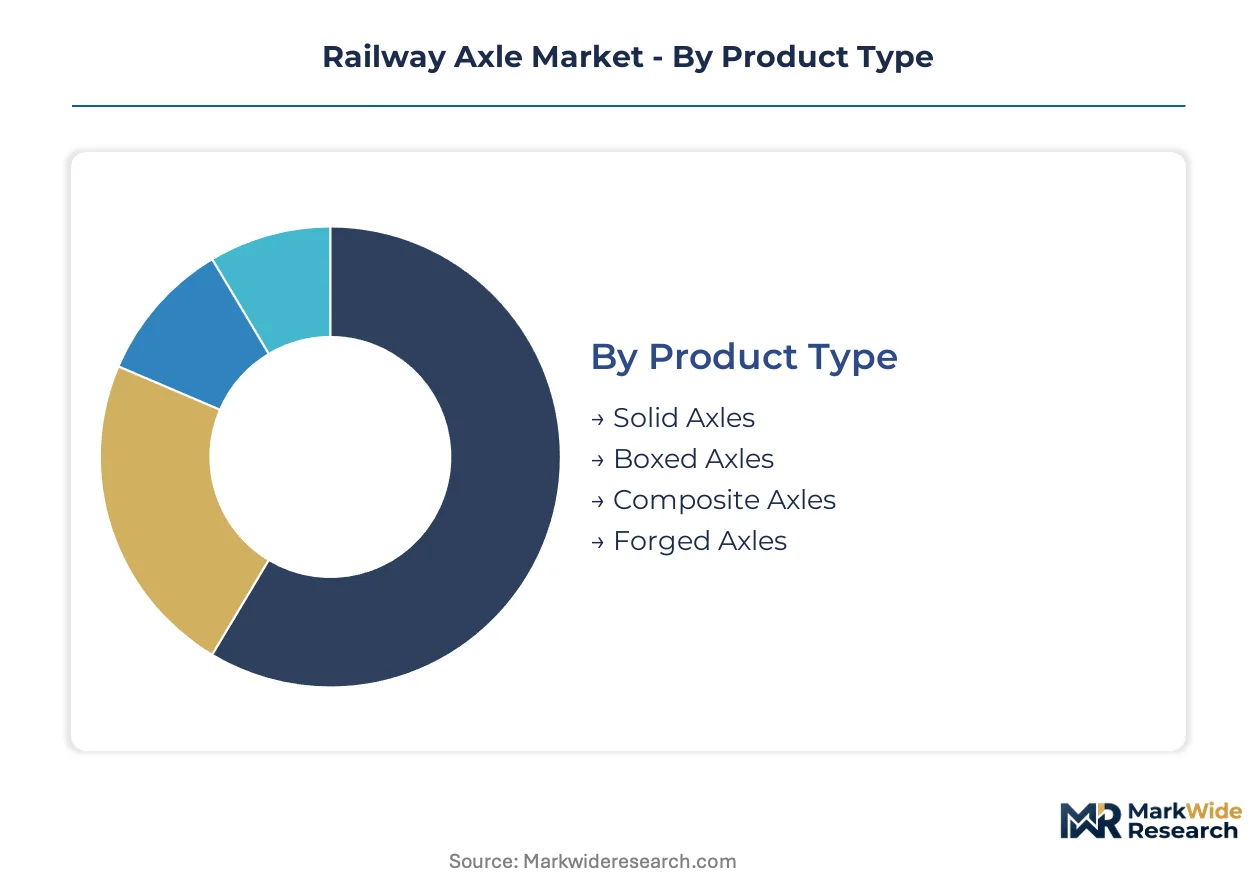
Axle procurement patterns diverge sharply across product architectures and operational regimes. Material certification tiers and service duty cycles create distinct margin architectures that suppliers must navigate.
Product Type:
Premium margin pools concentrate in hollow-bore and composite architectures where unsprung mass reduction commands pricing power, while solid forged axles anchor volume throughput.
- Solid Axles:Monolithic steel shafts machined from vacuum-degassed billets dominate heavy-haul freight installations. Indian Dedicated Freight Corridor operators specify these for 25-tonne axle load corridors where fatigue resistance outweighs weight savings.
- Forged Axles:Closed-die forging above 1,100°C yields grain structures meeting EN 13261 and AAR M-101 specifications. European interoperability mandates are compressing supplier qualification timelines for integrated forge-to-finish operations.
- Boxed Axles:Hollow tubular designs with internal reinforcement ribs serve regional passenger fleets.
- Composite Axles:Carbon fiber reinforced polymer cores with steel end fittings target high-speed applications.
Solid axles hold installed capacity across legacy freight fleets. Forged axles are rotating up the share rankings as certification harmonization elevates metallurgical specifications.
End User:
Procurement authority is fragmenting across asset ownership models, with availability-based contracts transferring inspection liability from operators to manufacturers.
- Freight Operators:Class I railroads and Asia-Pacific corridor managers drive replacement cycles through tonnage-mileage thresholds. North American operators are outsourcing wheelset maintenance via lifecycle service agreements.
- Passenger Transport:High-speed rail authorities specify hollow-bore designs for million-kilometre service intervals. German and French operators front-load qualification testing to avoid REACH compliance disruptions.
- Maintenance Providers:Independent service companies capture axle reconditioning volumes.
- OEMs:Rolling stock manufacturers integrate axle-wheelset assemblies for new build programs.
Freight operators retain volume dominance. Passenger transport is climbing the fastest as fleet renewal accelerates.
Material:
Alloy specifications are bifurcating between legacy carbon grades and premium vacuum-degassed formulations that satisfy tightened non-destructive testing protocols.
- Alloy Steel:Chromium-molybdenum formulations with controlled grain size deliver fatigue resistance for high-speed and heavy-haul duty cycles. EN 13261 harmonization is elevating alloy content requirements across trans-European networks.
- Carbon Steel:Standard grades serve conventional passenger and regional freight applications where inspection intervals remain less stringent.
- Cast Iron:Ductile iron variants appear in brake disc integration points.
- Composite Materials:Carbon fiber cores with metallic interface layers enable 30% unsprung mass reduction.
Alloy steel commands specification premiums. Composite materials are gaining share fastest where energy efficiency targets override first-cost constraints.
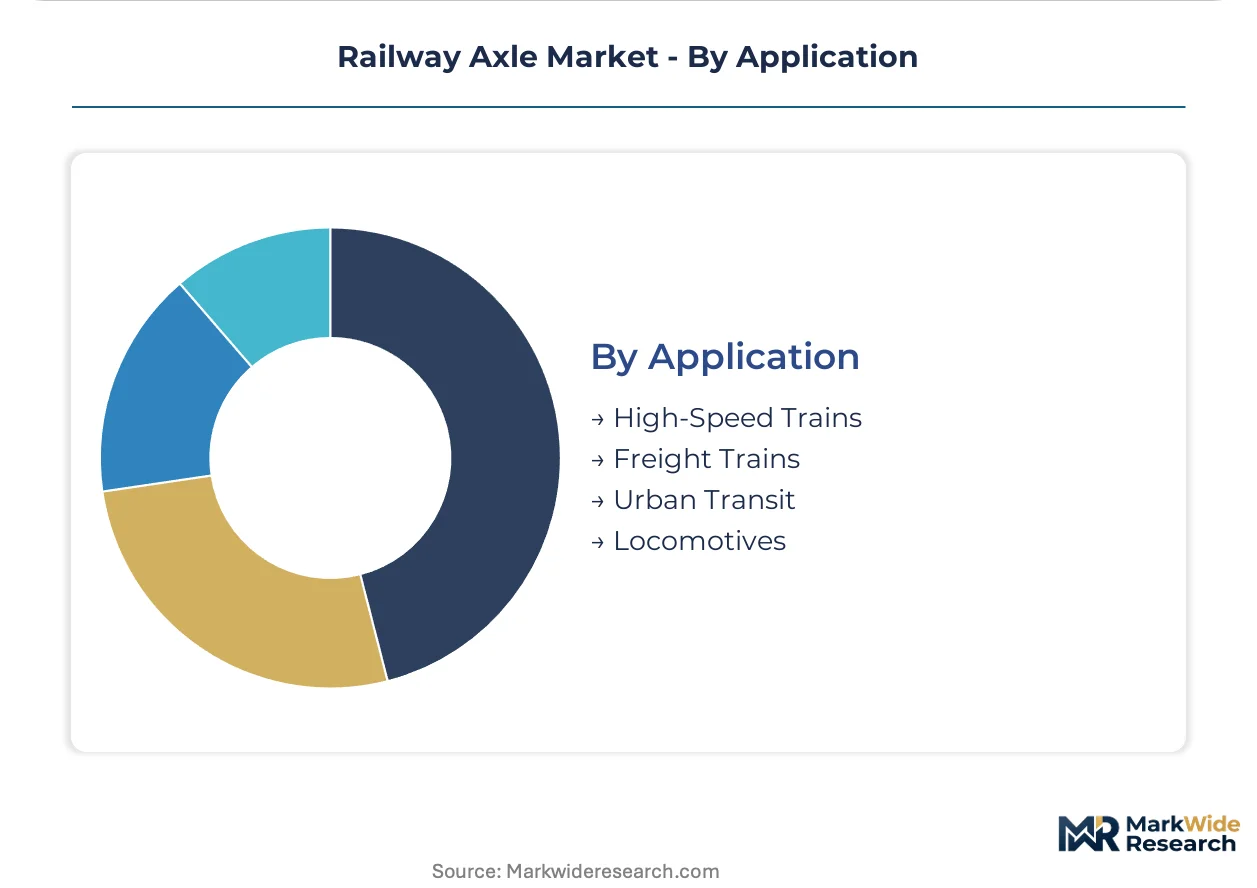
Application:
Service speed and axle load combinations dictate material selection and design architecture across operational categories.
- High-Speed Trains:Hollow-bore and composite axle designs reduce unsprung mass below 3,000 kg per wheelset. Track adhesion improvements translate directly to energy consumption reductions on 300+ km/h corridors.
- Freight Trains:Solid forged axles with 30-tonne static load ratings dominate heavy-haul routes. Indian Ministry of Railways procurement mandates are accelerating domestic forging capacity expansion.
- Urban Transit:Metro rail operators in India and Southeast Asia specify lighter axle loads with enhanced corrosion protection.
- Locomotives:Traction motor torque transmission demands torsional fatigue resistance.
Freight trains anchor replacement demand volumes. High-speed trains are expanding most quickly as corridor construction accelerates across Asia-Pacific.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Freight operators dominate procurement volumes across concentrated manufacturing clusters. Passenger transport agencies and urban transit authorities are accelerating fleet renewal programs in parallel corridors.
China
High-speed rail authorities specify hollow-bore designs for million-kilometre service intervals on 300+ km/h corridors. MIIT enforces GB standards for axle metallurgy and non-destructive testing protocols. CRRC Corporation leverages integrated foundry-to-assembly footprints across Changzhou and Qingdao manufacturing bases to capture domestic procurement cycles.
India
Dedicated Freight Corridor projects and metro rail expansions are compressing axle replacement timelines. The Ministry of Railways mandates Make in India localization, compelling OEMs to establish domestic forging capacity. Ramakrishna Forgings and Titagarh Rail Systems anchor production clusters in West Bengal and Jharkhand to serve eastern corridor demand.
Germany
High-speed operators front-load qualification testing to avoid REACH compliance disruptions from chromium-based coating substitutions. ECHA candidate list expansion drives reformulation of axle lubrication chemistries. Siemens Mobility GmbH and voestalpine AG concentrate R&D and precision finishing operations across Bavaria and Upper Austria cross-border industrial zones.
United States
Class I railroads negotiate availability-based agreements that transfer inspection liability to manufacturers. AAR M-101 standards govern freight axle metallurgy and inspection intervals. Amsted Rail Company anchors heavy-haul solid axle production across Missouri and Illinois forging corridors serving Union Pacific and BNSF procurement.
Italy
Specialized forged solid axle producers serve European interoperability mandates and heavy-haul export markets. EN 13261 harmonization elevates grain structure control requirements. Lucchini RS S.p.A. concentrates precision forging and finishing operations across Lombardy industrial districts to meet trans-European network certification.
Railway Axle Market Vendor Landscape
Player mix skews toward integrated forge-to-finish conglomerates and specialized axle manufacturers. Tiered competition separates premium hollow-bore specialists from volume solid axle producers. Strategic archetypes include captive railway equipment divisions, independent forging specialists, and diversified industrial conglomerates. Capacity expansion and backward integration into vacuum-degassed alloy steel billet supply represent dominant competitive moves.
Among integrated rolling stock manufacturers, CRRC Corporation Limited and Siemens Mobility GmbH exemplify the captive division archetype with control over design-to-assembly workflows. Specialized forging specialists include Lucchini RS S.p.A., which occupies a position exemplifying deep metallurgical expertise in heavy-haul applications. Amsted Rail Company, Inc. anchors the North American independent supplier tier. These three represent distinct strategic postures: Chinese integrated conglomerate, European precision forging specialist, and North American heavy-haul independent.
| Leading Market Players |
|---|
| Lucchini RS S.p.A. |
| Bombardier Transportation |
| CRRC Corporation Limited |
| SKF Group |
| Siemens Mobility GmbH |
| Amsted Rail Company, Inc. |
| voestalpine AG |
| Interpipe |
| Alstom SA |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Indian forging clusters shapes both supply concentration and price floors for vacuum-degassed alloy steel axles. Freight operators in Asia-Pacific corridors face compressed replacement cycles as tonnage-mileage thresholds accelerate, while EN 13261 certification tightening elevates metallurgical specifications that filter through to contract structures.
Pricing Analysis
Cost-plus contracts with ferrous scrap indexation dominate procurement between Class I railroads and forged axle producers. Price differentiation separates EN 13261-certified hollow-bore designs from AAR M-101 solid axle tiers, with certification grade and volume scale as primary levers. Pricing pressure stems from scrap steel volatility squeezing margin predictability at integrated forge-to-finish operations. Urban transit authorities exhibit highest price sensitivity due to municipal budget constraints, while high-speed rail authorities prioritize performance specifications over unit economics.
Supply Chain Analysis
China and India anchor vacuum-degassed alloy steel billet production and precision forging capacity for railway axles. Raw material dependencies center on ferrous scrap indexes, chromium-molybdenum alloy additives, and vacuum degassing equipment. Single-source vulnerability concentrates in Chinese integrated foundry-to-assembly footprints that dominate high-speed corridor procurement. Distribution runs through rolling stock OEM direct contracts and national railway tender platforms, with lifecycle service agreements emerging as an alternative channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The railway axle market sits in cyclical recovery as Dedicated Freight Corridor buildouts across India compress replacement timelines and reactivate dormant forging capacity.
For Market Incumbents: Fortify backward integration into vacuum-degassed alloy steel billet supply to offset scrap volatility exposure. Expand captive forging capacity in Jharkhand and West Bengal industrial clusters to satisfy Make in India localization mandates. Deepen EN 13261 and AAR M-101 dual-certification investments to defend against emerging Chinese competitors with integrated foundry-to-assembly footprints. For New Entrants and Emerging Players: Lead with urban transit axle reconditioning services as the most penetrable white-space segment, where metro rail expansions in India and Southeast Asia create procurement streams separate from national railway tenders. Target independent maintenance providers with predictive maintenance platform bundles that pair axle-mounted sensors with availability-based contracts. Pursue PLI scheme alignment for domestic forging investments to capture cost offsets. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among axle manufacturers with lifecycle service contracts that transfer inspection liability to suppliers. Long-term viability over a five-to-ten-year window favors specialized forging specialists with deep metallurgical expertise over diversified industrial conglomerates. Monitor EN 13261 harmonization timelines as the inflection signal for supplier qualification cost escalation and competitive access reshaping.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Forging Capacity Expansion | Captures Make in India procurement mandates and PLI scheme cost offsets for Dedicated Freight Corridor supply. |
| Dual-Standard Certification Investment | Enables access to both EN 13261 European interoperability and AAR M-101 North American freight markets. |
| Lifecycle Service Contract Conversion | Transforms unit-sales economics into recurring revenue streams with transferred inspection liability. |
| Predictive Maintenance Platform Development | Pairs axle-mounted sensor hardware with digital twin software for availability-based agreements. |
| Alloy Steel Billet Backward Integration | Reduces scrap steel volatility exposure and secures grain structure control for fatigue resistance. |
Methodological Framework
A standing panel of railway procurement officers, forging plant managers, non-destructive testing certification leads, and rolling stock maintenance directors provided ongoing calibration across primary fieldwork. Secondary validation drew from Bureau of Indian Standards axle specifications, Association of American Railroads M-101 technical bulletins, European Union Agency for Railways EN 13261 harmonization documents, and Ministry of Railways tender disclosures. Bottom-up axle unit shipment estimates triangulated against top-down freight tonnage expansion projections.
Consistency checks validated volume and value outputs against external benchmarks including customs trade data for alloy steel billet flows and national railway capital expenditure disclosures. The analytical framework modeled product type, end user archetype, material certification tier, and application duty cycle across the projection horizon. CAGRs derived from axle replacement cycle compression rates and corridor construction timelines, with sensitivity testing around scrap steel price volatility and certification timeline divergence.
The analysis sits within stated boundaries; outcomes outside sustained freight tonnage expansion or accelerated EN 13261 harmonization would require recalibration. Forecasts reflect documented assumptions regarding Make in India localization enforcement and REACH substance restriction implementation timelines. Recalibration cycles align with material shifts in Dedicated Freight Corridor completion schedules and ECHA candidate list expansion decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Railway Draft Gears Market
Railway
France Rail Freight Transport Market
Railway
Electro-Pneumatic Train Brakes Market
Railway
Freight Wagon Market
Railway
Railway Window Market
Railway
Train HVAC Market
Railway
Train Suspension System Market
Railway
Railroad Tie Market
Railway
Global Hyperloop Train Market
Railway
Railroad Brake Shoe Market
Railway
Global Train Brake Market
Railway
Locomotive Parking Brake Market
Railway
Tugger Trains Market
Railway
Locomotive Radiator Fan Market
Railway
Train Exterior Lighting Market
Railway
Rolling Stock Management Market