
 Railroad Tank Car Market | 2026-2036
Railroad Tank Car Market Size, Share, and Industry Trends Forecast 2026-2036
Railroad Tank Car Market Analytics
Modular tank car leasing bundles are expanding as fleet operators seek flexible capacity without outright ownership. Trinity Industries leverages captive manufacturing to control delivery timelines for pressure car retrofits. GATX Corporation sustains one of the largest leased fleets in North America through long-term chemical shipper contracts. Union Tank Car Company anchors its position with in-house steel foundry operations that supply railcar components directly.
A railroad tank car is a cylindrical pressure vessel mounted on a rail chassis, typically constructed from normalized steel plate with thermal protection systems and bottom outlet valves, engineered to transport liquids, gases, and pressurized chemicals across continental rail networks. Steel construction dominates the material segment due to its fatigue resistance under cyclic loading, though aluminum variants are gaining traction for non-corrosive food-grade service. The chemicals application commands the deepest margin pools because specialized linings and pressure ratings command premium lease rates. Tank cars themselves represent the core product category, while hopper cars serve dry bulk commodities with fundamentally different containment economics.
The US Federal Railroad Administration enforces tank car integrity standards through 49 CFR regulations, while Transport Canada mandates equivalently stringent containment protocols under the Transportation of Dangerous Goods Act. These frameworks directly shape replacement cycles, as legacy DOT-111 cars face accelerated phase-out deadlines for crude oil and ethanol service. Stakeholders must monitor pending rulemakings on vapor pressure limits and thermal protection upgrades that could trigger another wave of fleet modernization investment.
Market Dynamics
EPA and Transport Canada are accelerating phase-out schedules for legacy DOT-111 tank cars in crude and ethanol service, forcing fleet operators into replacement cycles faster than normal depreciation timelines would dictate.
Growth Catalysts
- US Gulf Coast petrochemical buildouts:Export terminal expansions along the Houston Ship Channel and Corpus Christi are locking in multi-year fleet commitments from chemical shippers.
- 49 CFR thermal protection mandates:The Federal Railroad Administration's upgraded containment rules are compelling retrofits and new-build orders for pressure-rated units.
- Specialized lining technologies:Advanced epoxy and rubber linings for corrosive chemical transport are extending service intervals and commanding premium lease structures.
Market Restraints
- Normalized steel plate volatility:Input costs for tank car hulls fluctuate with scrap metal and alloy pricing, compressing manufacturing margins during procurement spikes.
- Foundry concentration in the US Midwest:Railcar component supply depends on a narrow geographic band of steel casting operations, creating single-source vulnerability.
- DOT-111 grandfathering limits:Regulatory friction prevents indefinite extension of legacy car service, forcing premature retirement of mechanically sound assets.
Strategic Opportunities
- Modular lease bundling:Fleet operators are assembling flexible capacity pools without balance-sheet ownership, opening recurring revenue streams for lessors.
- Food-grade aluminum variants:Non-corrosive edible oil and sweetener transport is shifting toward lighter-weight aluminum construction for fuel efficiency gains.
- Transport Canada harmonization:Cross-border regulatory alignment between the US and Canada is simplifying fleet certification for continental chemical shippers.
Industry Challenges
- Pressure vessel welder scarcity:Certified welders qualified for normalized steel railcar construction remain concentrated at legacy manufacturing sites, constraining production scaling.
- Retrofit queue compression:Simultaneous demand for tank car upgrades and new builds is stretching shop capacity and extending delivery timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railroad Tank Car Market |
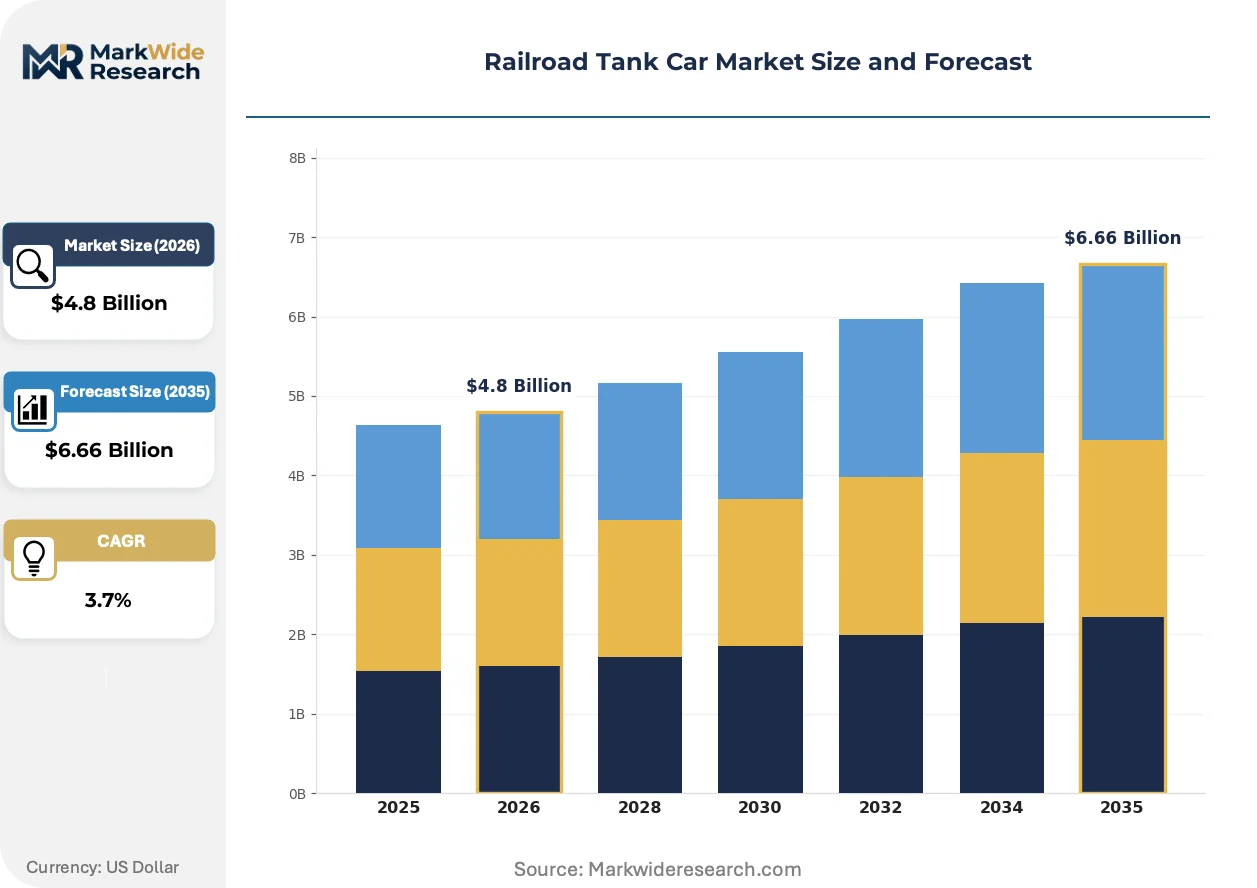
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tank Cars, Hopper Cars, Flat Cars, Boxcars Material: Steel, Aluminum, Composite, Plastic Application: Chemicals, Liquefied Gases, Food Products, Oil End User: Logistics Companies, Oil Producers, Chemical Manufacturers, Importers |
| Companies Covered | Trinity Industries, GATX Corporation, Union Tank Car Company, The Greenbrier Companies, American Railcar Industries, National Steel Car, VTG, Procor Limited, Japan Oil Transportation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railroad Tank Car Market Evolving Landscape
Digital freight matching platforms and sensor-enabled fleet monitoring are compressing asset utilization cycles and reshaping how tank car capacity is priced and deployed across chemical supply chains.
Telematics-enabled pressure monitoring is converging with predictive maintenance algorithms to transform how lessors manage tank car health. Chemical shippers with high-frequency rotation demands are adopting these systems fastest. The technology is converging with lease pricing models to enable usage-based rate structures that displace flat daily rates.
Transport Canada's Transportation of Dangerous Goods Act amendments are tightening vapor pressure containment thresholds for crude oil transport. The rules are forcing accelerated retirement of unjacketed legacy cars. Pressure car specifications are displacing general service units in the Alberta crude corridor as shippers pre-empt enforcement timelines.
Shippers are unbundling maintenance obligations from long-term lease contracts, opting instead for third-party shop networks with certified pressure vessel capabilities. This channel shift is fragmenting service relationships that historically tied fleets to original lessors. The pattern is most visible in the US Midwest ethanol belt, where independent repair shops are capturing volume from captive maintenance programs.
Railroad Tank Car Market Segmentation
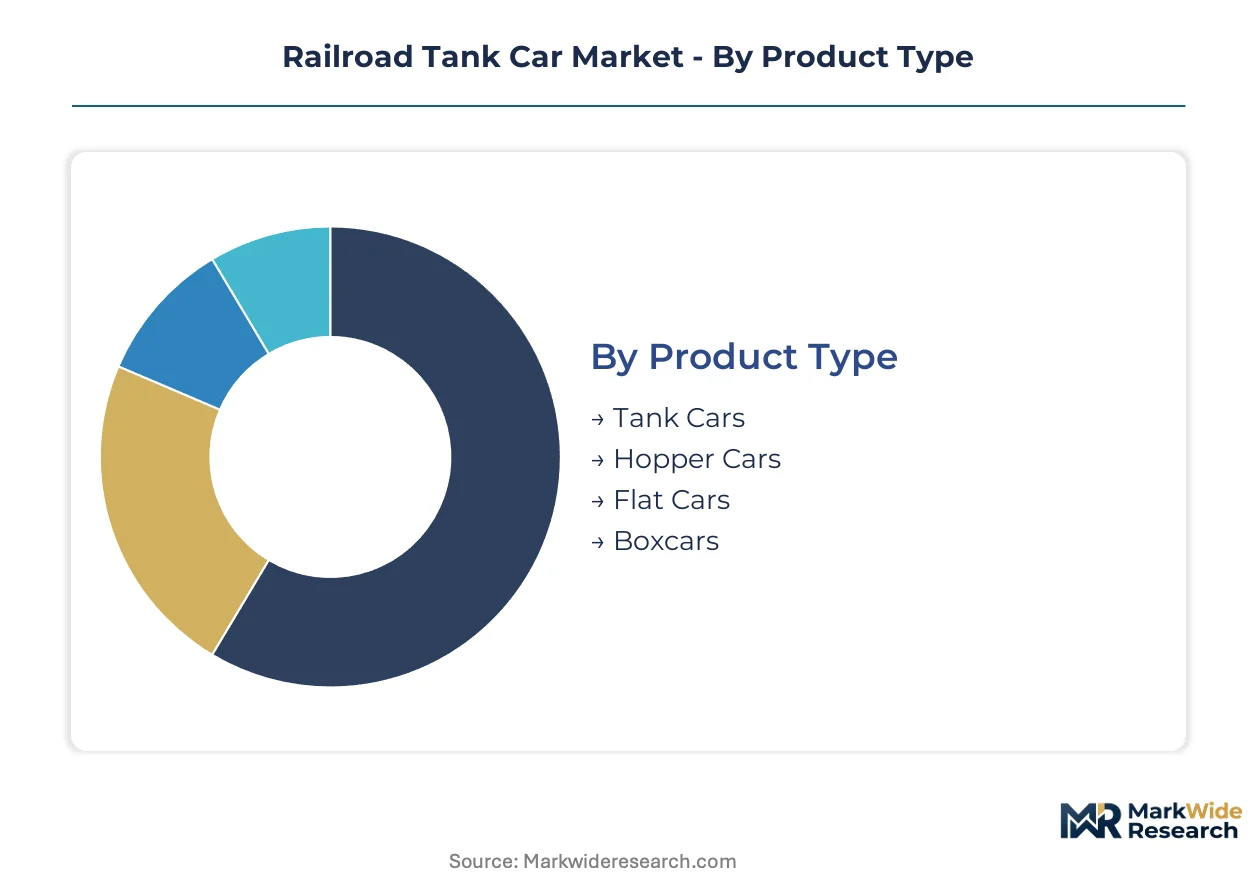
Railroad tank car segmentation reveals how specialized containment requirements fragment manufacturing capacity and lease pricing structures. Each dimension—product type, material, application, and end user—creates distinct margin pools and regulatory exposure profiles that shape fleet investment decisions.
Product Type:
Supply concentration in tank car manufacturing dominates this category, with pressure-rated and general service units commanding fundamentally different production footprints.
- Tank Cars:Cylindrical pressure vessels engineered for liquid, gas, and pressurized chemical transport, constructed from normalized steel plate with thermal protection systems and bottom outlet valves. Demand concentrates along the US Gulf Coast petrochemical corridor, where export terminal buildouts require specialized pressure-rated units under tightening EPA containment rules.
- Hopper Cars:Enclosed or open-top designs with bottom discharge gates for dry bulk commodities such as grain, coal, and minerals. Procurement concentrates in the US Midwest agricultural belt, where grain elevator networks and fertilizer distributors drive seasonal capacity surges.
- Flat Cars:Open-deck platforms for oversized or intermodal container loads.
- Boxcars:Enclosed rectangular structures for weather-sensitive general freight.
Today's leader: Tank Cars. Tomorrow's challenger: Hopper Cars.
Material:
Cost tier differentiation separates commodity-grade inputs from performance-optimized alloys and lightweight alternatives.
- Steel:Normalized carbon and alloy steel plate dominates hull construction due to fatigue resistance under cyclic loading and compatibility with pressure vessel certification. Foundry concentration in the US Midwest creates single-source vulnerability for railcar component supply.
- Aluminum:Lighter-weight alloys gaining traction for non-corrosive food-grade service, particularly edible oil and sweetener transport where fuel efficiency gains offset material cost premiums. Demand clusters around California and Florida food processing hubs.
- Composite:Fiber-reinforced polymer constructions for specialized chemical resistance applications.
- Plastic:Limited-use thermoplastic linings and internal coatings for extreme corrosion environments.
Steel retains volume dominance. Aluminum climbs the fastest on regulatory pressure for transport efficiency.
Application:
Margin structure varies dramatically across cargo hazard classes and containment complexity tiers.
- Chemicals:Specialized linings and pressure ratings command premium lease rates, with advanced epoxy and rubber systems extending service intervals. Fleet commitments concentrate among North American chemical manufacturers scaling orders under EPA and Transport Canada hazmat rule tightening.
- Liquefied Gases:Cryogenic and pressurized containment for propane, butane, and industrial gases. Specifications are displacing general service units in the Alberta crude corridor as shippers pre-empt Transport Canada vapor pressure enforcement timelines.
- Food Products:Sanitary-grade construction for edible oils, sweeteners, and liquid food ingredients.
- Oil:Crude and refined petroleum transport facing accelerated DOT-111 phase-out schedules.
Chemicals capture the deepest margin pools. Liquefied gases show the steepest expansion trajectory on regulatory-driven fleet replacement.
End User:
Customer type determines contract duration, maintenance obligation allocation, and sensitivity to lease-versus-own economics.
- Logistics Companies:Third-party rail operators and multimodal freight brokers assembling flexible capacity pools through modular lease bundling without balance-sheet ownership. Procurement concentrates among firms serving the Houston Ship Channel chemical export complex.
- Oil Producers:Upstream crude marketers and integrated petroleum companies facing compressed replacement cycles for legacy DOT-111 fleets. Investment timing hinges on FERC pipeline competition and export terminal access economics.
- Chemical Manufacturers:Petrochemical producers and specialty chemical firms with high-frequency rotation demands adopting telematics-enabled fleet monitoring fastest.
- Importers:Port-facing distributors and bulk liquid handlers with seasonal volume volatility.
Logistics companies lead lease innovation. Chemical manufacturers drive technology adoption fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The railroad tank car industry traces its modern scale to the United States, where standardized railcar manufacturing consolidated during the post-war expansion of continental chemical transport networks.
United States
Petrochemical export terminal buildouts along the Houston Ship Channel and Corpus Christi are locking in multi-year fleet commitments from specialty chemical shippers. The Federal Railroad Administration enforces 49 CFR thermal protection mandates that compel retrofits and new-build orders for pressure-rated units. Manufacturing gravity concentrates in the US Midwest foundry belt, where steel casting operations supply railcar components to assembly facilities.
Canada
Crude oil shippers in the Alberta corridor are preempting Transport Canada vapor pressure enforcement timelines by displacing general service units with pressure car specifications. The Transportation of Dangerous Goods Act amendments tighten containment thresholds for rail hazmat transport. Edmonton and Calgary anchor the replacement cycle demand as fleet operators accelerate DOT-111 phase-outs ahead of regulatory deadlines.
Germany
Chemical manufacturers along the Rhine industrial corridor are scaling specialized tank car orders under ECHA REACH compliance pressures for hazardous material containment. The EU's CSRD reporting requirements are extending traceability obligations through chemical supply chains. BASF and Bayer supplier networks around Ludwigshafen and Leverkusen are driving demand for epoxy-lined pressure vessels.
Japan
Industrial gas distributors and refined petroleum marketers are modernizing aging fleets under METI pressure vessel safety directives. JIS standards for railcar construction create certification barriers that favor domestic fabricators with established foundry relationships. The Chubu region around Nagoya hosts concentrated maintenance and retrofit capacity for the domestic chemical rail network.
India
Fertilizer and petrochemical shippers are expanding leased fleet commitments as the Dedicated Freight Corridor unlocks bulk liquid transport economics. BIS pressure vessel standards are tightening certification requirements for imported railcar components. Gujarat's Jamnagar refining complex and Maharashtra's Mumbai-Pune industrial belt are emerging as demand centers for corrosion-resistant chemical tank cars.
Railroad Tank Car Market Competitive Landscape
The competitive structure tilts toward integrated lessor-manufacturers with captive production capacity. Market concentration is moderate, with a handful of North American firms controlling substantial leased fleet positions alongside specialized fabricators serving regional chemical corridors. Three archetypes dominate: vertically integrated lessors with in-house manufacturing, independent fleet operators relying on third-party shop networks, and regional specialists concentrating on food-grade or cryogenic niche specifications. Capacity expansion and modular lease bundling represent the dominant competitive vectors as operators seek flexible deployment without balance-sheet ownership.
Among North American integrated players, Trinity Industries and GATX Corporation exemplify the lessor-manufacturer archetype with substantial fleet positions, while Union Tank Car Company anchors the specialty fabricator tier with captive steel foundry operations. These firms occupy positions that reflect divergent strategic bets on ownership versus leasing economics across the chemical transport value chain.
| Leading Market Players |
|---|
| Trinity Industries |
| GATX Corporation |
| Union Tank Car Company |
| The Greenbrier Companies |
| American Railcar Industries |
| National Steel Car |
| VTG |
| Procor Limited |
| Japan Oil Transportation |
| Others |
Value Network & Pricing Analysis
Multi-year fleet commitments from Gulf Coast petrochemical exporters are compressing delivery timelines and forcing supply-side prioritization of pressure-rated units, which in turn concentrates pricing power among foundry-integrated manufacturers with captive steel casting capacity.
Pricing Analysis
Contract-based long-term offtake with embedded escalation clauses dominates lease structures for chemical shippers, while spot procurement persists for seasonal agricultural volume. Premium-mid-economy pricing differentiation separates DOT-117 pressure-rated units from general service cars and legacy retrofits, with certification grade and lining technology as the primary tiering mechanisms. Cost compression in the standard tier is intensifying because normalized steel plate volatility feeds directly into manufacturing quotations. Logistics companies exhibit the highest price sensitivity due to thin margin structures, whereas integrated chemical manufacturers prioritize specification compliance over lease rate minimization.
Supply Chain Analysis
Certified pressure vessel welder scarcity in the US Midwest foundry belt and Ontario manufacturing corridors is constraining production scaling and extending delivery timelines for both new builds and retrofits. Supply draws from normalized steel plate mills in the United States, specialty alloy foundries in Canada, and rubber lining compound suppliers in Germany. Single-source vulnerability concentrates in railcar component casting operations clustered around Chicago and Cleveland. Distribution feeds from captive lessor manufacturing through long-term lease contracts to chemical shippers, with independent repair shops capturing unbundled maintenance volume in the ethanol belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The railroad tank car market reads as a late-cycle quality story where regulatory-driven specification upgrades are shifting procurement preference toward premium pressure-rated units with advanced lining systems and telematics integration.
For Market Incumbents: Extend foundry-integrated manufacturing advantages by accelerating pressure car retrofit capacity before regulatory deadlines compress shop availability. Lock in multi-year lease extensions with Gulf Coast chemical exporters now, before modular lease bundling fragments long-term relationships. Defensive consolidation around captive steel casting operations insulates against input cost volatility that independent operators cannot absorb.
For New Entrants and Emerging Players: The mid-tier price-point gap between premium DOT-117 specifications and economy-grade general service units creates entry space for regional specialists with food-grade aluminum construction capabilities. Target California and Florida food processing hubs where fuel efficiency premiums justify material cost differentials. White-space exists in third-party maintenance networks with certified pressure vessel capabilities, particularly in the Midwest ethanol belt where shippers are unbundling service obligations from original lessors.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated lessor-manufacturers with captive foundry operations and established long-term chemical shipper contracts. The five-to-ten year viability window favors firms with backward integration into steel casting rather than assembly-only operators exposed to component supply shocks. Monitor Transport Canada enforcement timelines for vapor pressure containment thresholds as the inflection signal for accelerated fleet replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Casting | Captive foundry operations insulate Trinity Industries and Union Tank Car Company from Midwest supply concentration risk. |
| Modular Lease Bundling | GATX Corporation's flexible capacity pools attract logistics companies seeking balance-sheet-light deployment without ownership. |
| Telematics Platform Integration | Sensor-enabled pressure monitoring enables usage-based rate structures that displace flat daily lease pricing. |
| Food-Grade Aluminum Capacity Expansion | Lighter-weight construction for edible oil transport captures fuel efficiency premiums in California processing corridors. |
| Third-Party Maintenance Network Partnership | Independent repair shops with pressure vessel certification capture volume from fragmented service relationships in the ethanol belt. |
Research Methodology
Coverage spans the United States, Canada, Germany, Japan, and India, with primary inputs from each regional chemical transport corridor. The analysis combines structured interviews with fleet operations directors, chemical shipper procurement leads, pressure vessel welding supervisors, and railcar lessor lease structuring specialists with secondary validation from FRA 49 CFR dockets, Transport Canada TDG Act amendments, customs trade data on railcar component imports, and SEC 10-K filings from publicly traded lessor-manufacturers. Bottom-up triangulation across regional production clusters and top-down validation against petrochemical export terminal buildout announcements anchor volume estimates.
Rate-of-change decomposition separates replacement cycle demand from net fleet expansion, with segment-level CAGRs derived from regulatory phase-out timelines, export capacity commissioning schedules, and lease contract duration patterns across the projection horizon. Segmentation modeling incorporates product type tiering, material grade differentiation, application hazard class, and end-user ownership economics. Industry-specific forecast inputs include normalized steel plate price indices and certified welder availability metrics from Bureau of Labor Statistics regional employment data.
Caveats apply where EPA or Transport Canada rulemaking on vapor pressure limits and thermal protection upgrades could materially shift the outlook through accelerated legacy fleet retirement. Forecasts reflect assumptions about regulatory enforcement timing, petrochemical export terminal completion schedules, and foundry capacity expansion plans that remain subject to revision. Material deviation in steel input costs, welder certification pipeline throughput, or cross-border regulatory harmonization progress warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Radar and Lidar Technology for Railways Application Market
Railway Transportation
Railway Sliding Bearing Market
Railway Transportation
High Speed Rail Coating Market
Railway Transportation
Railway Connectors Market
Railway Transportation
Digital Axle Counter Market
Railway Transportation
Global Railcar Leasing Market
Railway Transportation
Railway Traction Inverter Market
Railway Transportation
Canada Rail Freight Transport Market
Railway Transportation
Railway Couplers Market
Railway Transportation
Rail Fasteners Market
Railway Transportation
Global Rail Freight Transport Market
Railway Transportation
Overhead Catenary System Market
Railway Transportation
Global Train Communication Gateways Systems Market
Railway Transportation
Railway After-Cooler Market
Railway Transportation
Global Autonomous Trains Market
Railway Transportation
Composites in Passenger Rail Market