
 Locomotive Maintenance Market | 2026-2036
Locomotive Maintenance Market Size, Share, and Industry Trends Forecast 2026-2036
Locomotive Maintenance Market Analytics
Modular overhaul bundling is hardening as the dominant procurement pattern across major rail operators. Wabtec Corporation leverages its integrated component portfolio to capture multi-year service contracts. Alstom competes through technology leadership in predictive diagnostics for electric locomotive fleets. Siemens Mobility anchors European overhaul demand with software-embedded maintenance platforms that unify fleet data across operator networks.
Locomotive maintenance encompasses the systematic inspection, repair, component replacement, and performance restoration of railway propulsion units to ensure operational safety, regulatory compliance, and fuel efficiency across freight and passenger service. The discipline covers diesel-electric prime mover overhauls, traction motor rewinding, and control system recalibration, typically executed at intervals measured in running hours or mileage cycles. Preventive maintenance and corrective repairs together constitute the core revenue base, though IoT solutions within the technology dimension represent the fastest-expanding margin pool as operators shift from calendar-based to condition-based intervention models. Freight operators dominate end-user demand volume, while passenger railways generate premium pricing through stringent uptime requirements and contracted availability clauses.
The Federal Railroad Administration enforces mechanical safety standards that mandate periodic inspection intervals and documentation protocols for interstate operations. The EPA Tier 4 emission regulations compel freight operators to schedule engine rebuilds or repowering projects to maintain compliance across existing diesel locomotive assets. Stakeholders must weigh the capital trade-off between extended overhaul cycles and accelerated fleet modernization commitments as regulatory thresholds tighten and alternative propulsion technologies mature.
Market Dynamics
The locomotive maintenance sector is experiencing a fundamental restructuring as freight operators extend asset life cycles rather than acquiring new-build locomotives facing multi-year delivery backlogs. This operational pivot toward overhaul-intensive models concentrates demand around integrated service providers capable of bundling mechanical, electrical, and emission-compliance workstreams.
Growth Catalysts
- EPA Tier 4 retrofit mandates:Freight operators across the United States must schedule engine rebuilds or repowering projects to maintain compliance, compressing overhaul intervals and expanding addressable service volume.
- Aging diesel fleet demographics:North American Class I railroads operate locomotive fleets averaging 25-30 years in service age, creating sustained demand for traction motor rewinding and control system recalibration.
- Condition-based maintenance platforms:IoT-enabled predictive diagnostics allow operators to shift from calendar-based interventions to running-hour optimization, expanding the technology-enabled service margin pool.
Market Restraints
- Specialized technician scarcity:Diesel-electric prime mover expertise concentrates among aging workforce cohorts, constraining service provider expansion and inflating labor rates.
- Component supply concentration:Critical power assembly and emissions aftertreatment components source from limited North American and European supplier bases, exposing maintenance schedules to input volatility.
- Electrification substitution threat:Battery-electric and hydrogen fuel cell locomotive pilots on European and Asian passenger corridors threaten long-term diesel overhaul demand in those geographies.
Strategic Opportunities
- Indian Railways electrification backlog:The national operator maintains substantial diesel locomotive assets requiring overhaul support as electrification rollout lags behind fleet transition timelines.
- Digital twin convergence:Integration of physics-based modeling with real-time sensor streams enables remote diagnostic capabilities that reduce unplanned downtime and create recurring software revenue.
- CSRD disclosure requirements:European operators face mandated sustainability reporting that elevates maintenance-as-circular-economy positioning against new-build capital expenditure.
Industry Challenges
- Multi-system integration complexity:Modern locomotive control architectures blend legacy relay-logic with programmable automation controllers, demanding cross-functional engineering teams that remain scarce.
- FRA certification timeline compression:Mechanical safety standard revisions require documentation protocol updates that strain quality assurance bandwidth at independent service shops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Locomotive Maintenance Market |
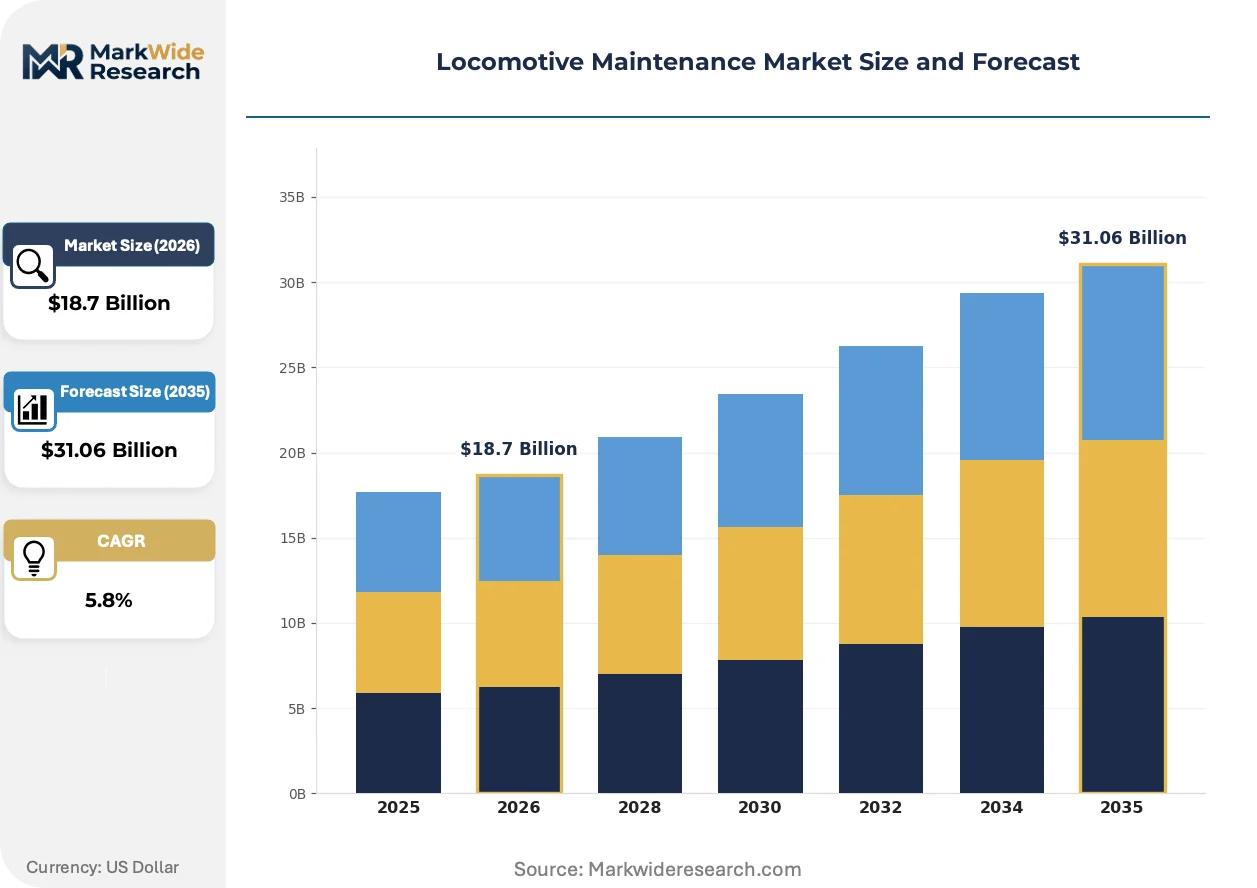
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Preventive Maintenance, Corrective Repairs, Overhauls, Inspections Technology: IoT Solutions, Diagnostic Tools, Automated Systems, Software Platforms End User: Freight Operators, Passenger Railways, Rail Management Companies, Maintenance Depots Deployment: Onsite Solutions, Offsite Facilities, Mobile Units, Integrated Systems |
| Companies Covered | CRRC Corporation Limited, Wabtec Corporation, Alstom, Siemens Mobility, Hitachi Rail, Progress Rail, Stadler Rail, Vossloh, CAD Railway Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Locomotive Maintenance Market Evolving Landscape
Predictive analytics and modular platform architectures are displacing reactive maintenance paradigms across freight and passenger rail operations. This technological reorientation favors service providers with embedded software capabilities over pure mechanical specialists.
Edge-computing sensor arrays mounted on traction motors and turbochargers transmit vibration and thermal data to cloud-based diagnostic engines. Class I railroads in the United States are deploying these systems across thousand-unit diesel fleets. Condition-monitoring infrastructure is expanding into warranty and availability-guarantee contracting structures that transfer operational risk to maintenance vendors.
REACH chemical restrictions and EU Green Deal carbon-border adjustments are compelling European overhaul facilities to phase out solvent-based cleaning processes and chrome-plating techniques. Component remanufacturers must certify alternative surface treatments and aqueous cleaning systems. German and French maintenance depots face the most accelerated compliance timelines as national rail operators prioritize scope-three emission reductions in supplier scorecards.
Freight operators are unbundling traditional full-service contracts into discrete component-level agreements with specialized providers. This procurement fragmentation allows railroad procurement departments to benchmark traction motor, power assembly, and aftertreatment services separately. The pattern is most advanced among United States-based Class I operators seeking to diversify supplier concentration risk following consolidation among integrated maintenance providers.
Locomotive Maintenance Market Segmentation
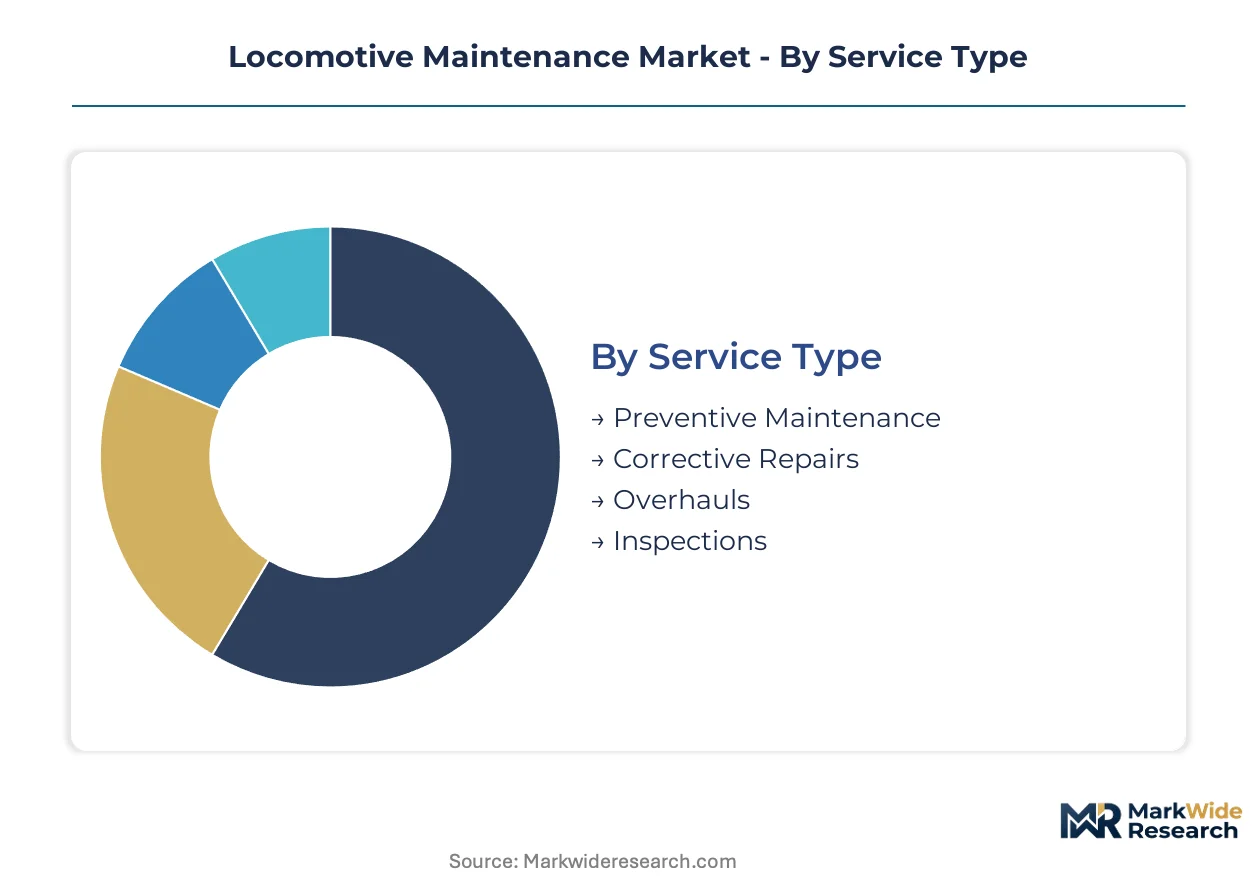
Locomotive maintenance procurement fragments across service delivery models, technology integration levels, and operational contexts. Understanding these segment boundaries clarifies where margin pools concentrate and where competitive positioning shifts most rapidly.
Service Type:
Technical sophistication and regulatory intensity define the service hierarchy, with intervention depth determining pricing power and contract duration.
- Preventive Maintenance:Scheduled inspection protocols and component replacement cycles executed at running-hour intervals. Freight operators in the United States concentrate procurement here as EPA Tier 4 mandates compress service windows for aging diesel assets.
- Corrective Repairs:Unplanned interventions addressing component failures, traction motor faults, and control system malfunctions. Passenger railways generate premium pricing through contracted availability clauses that penalize downtime.
- Overhauls:Comprehensive prime mover rebuilds and emission system retrofits.
- Inspections:Regulatory-mandated mechanical safety assessments and documentation protocols.
Preventive maintenance leads on scale; overhauls lead on momentum.
Technology:
Margin migration follows the shift from mechanical execution to data-enabled prediction, with software and sensor platforms capturing expanding value share.
- IoT Solutions:Edge-computing sensor arrays transmitting vibration and thermal data from traction motors and turbochargers. Class I railroads deploy these across thousand-unit diesel fleets to enable condition-based intervention models.
- Diagnostic Tools:Portable and fixed equipment for fault isolation and performance measurement.
- Automated Systems:Robotic inspection platforms and automated component testing rigs.
- Software Platforms:Cloud-based fleet management systems unifying maintenance data across operator networks. European overhaul demand anchors on these platforms as CSRD disclosure requirements elevate digital traceability.
IoT solutions lead on scale; software platforms lead on momentum.
End User:
Operational context shapes procurement patterns, with freight volume and passenger uptime requirements creating divergent contract structures.
- Freight Operators:North American Class I railroads dominate demand volume through extended overhaul cycles for 25-30 year diesel fleets facing new-build delivery constraints.
- Passenger Railways:Stringent reliability requirements and contracted availability clauses generate premium pricing.
- Rail Management Companies:Third-party fleet operators bundling maintenance into asset-light service offerings.
- Maintenance Depots:Independent service shops competing on component-level specialization.
Freight operators lead on scale; passenger railways lead on momentum.
Deployment:
Facility configuration and mobility determine capital intensity and customer proximity trade-offs.
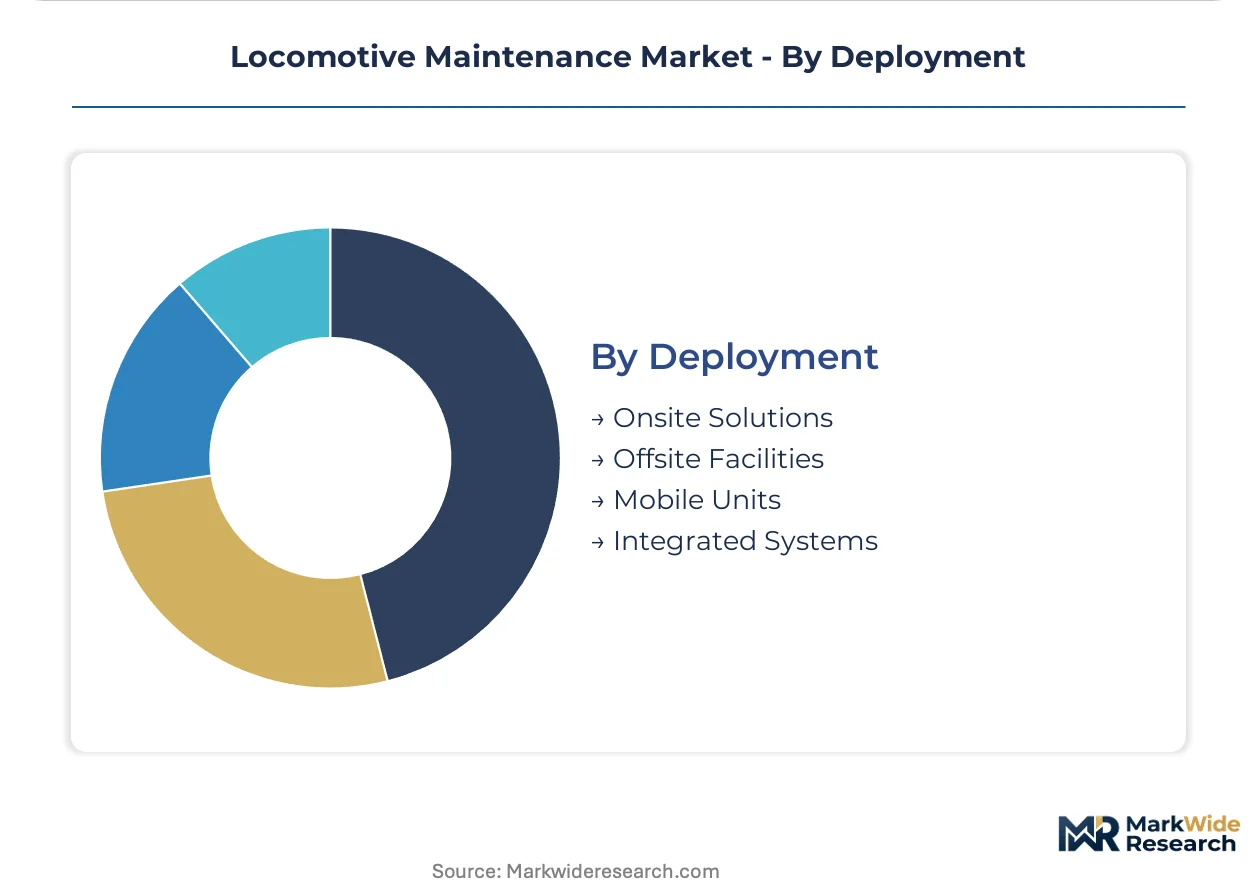
- Onsite Solutions:Maintenance execution at customer rail yards and operational facilities.
- Offsite Facilities:Centralized depots with specialized equipment for overhaul and remanufacturing. German and French maintenance depots face accelerated REACH compliance timelines for solvent phase-out.
- Mobile Units:Self-contained service vehicles deploying to remote track locations.
- Integrated Systems:Combined onsite-offsite networks with unified scheduling platforms.
Offsite facilities lead on scale; integrated systems lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The locomotive maintenance industry traces its modern foundation to the United States, where Class I railroads pioneered systematic diesel-electric overhaul protocols during the mid-20th century transition from steam propulsion.
United States
Class I railroads operate 25-30 year average fleet ages under EPA Tier 4 retrofit mandates that compress overhaul intervals. The Federal Railroad Administration enforces mechanical safety standards with periodic inspection documentation protocols. Chicago and Omaha anchor the heaviest maintenance concentration, where Union Pacific and BNSF operate centralized remanufacturing facilities.
Germany
Deutsche Bahn's freight and passenger electrification programs sustain demand for legacy diesel overhauls while REACH chemical restrictions accelerate solvent phase-out timelines. The KBA oversees rolling stock certification requirements that strain independent service shop quality assurance bandwidth. Maintenance depots in North Rhine-Westphalia face the most accelerated compliance deadlines as national operators prioritize scope-three emission reductions.
India
Indian Railways maintains substantial diesel locomotive assets requiring overhaul support as electrification rollout lags behind fleet transition timelines. The Central Electricity Authority coordinates infrastructure standards that affect maintenance facility power requirements. Diesel locomotive workshops in Varanasi and Patiala concentrate remanufacturing capacity for the broad-gauge fleet.
China
CRRC's integrated manufacturing-service model dominates domestic overhaul demand through captive maintenance networks for high-speed and freight electric fleets. The Ministry of Industry and Information Technology sets equipment standards that influence component replacement cycles. Qingdao and Changchun host the largest consolidated maintenance complexes serving both domestic and export contract obligations.
France
SNCF's stringent availability clauses for TGV and regional passenger services generate premium pricing for contracted maintenance outcomes. The EU Green Deal carbon-border adjustments and CSRD disclosure requirements elevate maintenance-as-circular-economy positioning. Alstom's Belfort facility anchors European electric locomotive overhaul capacity with embedded predictive diagnostics platforms.
Locomotive Maintenance Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth, with software-embedded platforms commanding sustained pricing power over pure mechanical execution. The vendor base organizes into three tiers: integrated OEM-service hybrids, specialized component remanufacturers, and independent depot operators. Two strategic archetypes dominate competitive positioning—technology-forward diagnosticians bundling predictive analytics with mechanical workstreams, and scale-driven consolidators capturing multi-year fleet contracts through geographic density. Dominant competitive moves include portfolio diversification into IoT-enabled service layers and strategic partnerships with national rail operators for captive maintenance volumes.
Within the integrated OEM tier, CRRC Corporation Limited, Wabtec Corporation, and Alstom exemplify divergent geographic anchoring and technology positioning. CRRC represents the state-linked manufacturing giant with captive domestic service networks. Wabtec occupies a position as the North American integrated component portfolio consolidator. Alstom sits within the European technology leadership archetype for predictive diagnostics in electric fleets.
| Leading Market Players |
|---|
| CRRC Corporation Limited |
| Wabtec Corporation |
| Alstom |
| Siemens Mobility |
| Hitachi Rail |
| Progress Rail |
| Stadler Rail |
| Vossloh |
| CAD Railway Industries |
| Others |
Value Network & Pricing Analysis
Steel scrap price indices and rare earth magnet benchmarks cascade through locomotive maintenance supply chains, compressing margins on remanufactured traction motors while elevating premium-tier pricing for EPA-certified emission retrofits among North American freight operators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement contracts, with differentiation anchored in EPA Tier 4 certification grade and bundled availability guarantees. Cost compression in economy-tier component remanufacturing is intensifying because steel alloy input volatility feeds directly into power assembly pricing. Freight operators exhibit highest price sensitivity on preventive maintenance schedules, while passenger railways absorb premium rates for contracted uptime performance.
Supply Chain Analysis
Regional distribution centers in Chicago, Omaha, and North Rhine-Westphalia anchor hub-and-spoke patterns for critical power assemblies and aftertreatment components. Supply concentrates in the United States, Germany, and China for traction motor laminations, turbocharger cartridges, and emission control substrates. Single-source vulnerability runs through specialized diesel-electric prime mover casting facilities. Distribution runs through integrated OEM captive networks and independent depot consignment arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in locomotive maintenance hinges on technology-enabled service tier migration, as condition-based platforms capture premium pricing while IoT deployment costs decline across fleet-scale implementations.
For Market Incumbents: Hedge against electrification substitution by deepening predictive diagnostics capabilities and securing multi-year availability contracts with Class I railroads. Battery-electric locomotive pilots in European corridors threaten long-term diesel overhaul demand. Vertical integration into edge-computing sensor manufacturing protects component margin pools.
For New Entrants and Emerging Players: Independent maintenance depots in the United States Midwest represent an underserved buyer archetype seeking component-level specialization outside consolidated OEM networks. Procurement fragmentation among Class I operators creates entry points for traction motor and aftertreatment specialists. Digital twin convergence offers a software-first go-to-market angle with lower capital barriers than mechanical execution.
For Investors and Strategic Acquirers: Asymmetric upside sits with IoT-enabled diagnostic platforms capable of embedding into warranty and availability-guarantee contracting structures. Long-term viability favors technology-forward diagnosticians over pure mechanical consolidators. Watch EPA enforcement intensity and Tier 4 compliance deadline acceleration as inflection indicators for overhaul volume expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Platform Integration | Edge-computing sensor deployment across Union Pacific and BNSF fleets transfers operational risk to vendors. |
| Emission Compliance Certification | EPA Tier 4 retrofit mandates compress overhaul intervals and expand addressable service volume for certified providers. |
| Component Remanufacturing Scale-Up | REACH chemical restrictions in German depots accelerate aqueous cleaning system investments and alternative surface treatment adoption. |
| Long-Term Service Contracting | Availability-guarantee structures with SNCF and Deutsche Bahn generate recurring revenue and captive maintenance volumes. |
| Digital Twin Development | Physics-based modeling integration with real-time sensor streams enables remote diagnostics and software subscription revenue. |
Research Methodology
Coverage spans the United States, Germany, India, China, and France, with primary inputs from each market cluster combining interviews with locomotive maintenance directors, Class I railroad procurement officers, OEM aftermarket service heads, and independent depot operators with secondary validation from FRA mechanical safety standards documentation, EPA emission compliance filings, EU CSRD disclosure frameworks, and customs trade data on locomotive component imports. Bottom-up service volume estimates triangulate against top-down fleet size and overhaul interval projections.
Granularity-level modeling disaggregates revenue across preventive maintenance, corrective repairs, overhauls, and inspections by technology tier, end-user operational context, and deployment configuration throughout the forecast period. CAGRs derive from running-hour optimization trends, EPA regulatory timeline assumptions, and electrification substitution elasticity parameters. Fleet age demographics and new-build delivery backlogs inform addressable market expansion rates.
Underlying measurement precision varies by segment; IoT-enabled service tiers carry tighter precision than traditional mechanical execution due to disclosed software subscription metrics. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and alternative propulsion pilot scalability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Railway Telematics Market
Railway
Rail Composites Market
Railway
Global Smart Locomotive Market
Railway
Railway Rolling Stock Market
Railway
Locomotive Radiator Fan Market
Railway
Railway Horn Market
Railway
Railway Draft Gears Market
Railway
Automatic Train Control Market
Railway
Check Rails Market
Railway
Train HVAC Market
Railway
Railroad Brake Shoe Market
Railway
Global Train Brake Market
Railway
Railway Braking System Market
Railway
Railway Digital Signal Axle Counters Market
Railway
Train Exterior Lighting Market
Railway
Solar Powered Train Market