
 Railroad Tie Market | 2026-2036
Railroad Tie Market Size, Share, and Industry Trends Forecast 2026-2036
Railroad Tie Market Analysis
The EPA's revised creosote risk assessment is decoupling traditional wood tie demand from volume growth in North American freight rail. Stella-Jones leverages its vertically integrated timber and treating network to sustain supply continuity despite chemical scrutiny. Koppers anchors its position through broad preservative chemistry expertise, while Integrico Composites specializes in thermoplastic composite formulations that bypass creosote entirely.
A railroad tie is a structural support member, typically measuring seven by nine inches in cross-section and eight to nine feet in length, that transfers wheel loads from steel rails to track ballast and maintains gauge alignment under cyclic fatigue. Wooden ties retain dominant installed base across legacy networks, though concrete ties capture margin pools in high-speed passenger corridors where dimensional stability matters. Composite ties represent the fastest-growing product type as polymer formulations achieve axle-load parity with hardwood alternatives.
The EPA regulates wood preservative emissions under the Federal Insecticide, Fungicide, and Rodenticide Act, while the Federal Railroad Administration governs track safety standards that indirectly specify tie performance grades. State-level environmental agencies in California and New York impose additional chemical disclosure burdens that shape supplier qualification protocols. Stakeholders must monitor whether pending EPA creosote determinations trigger accelerated material substitution timelines before existing treated-wood inventories deplete.
Market Dynamics
Freight railroads face a structural inflection as the EPA's creosote risk assessment forces simultaneous compliance with chemical restrictions and track safety mandates under FRA standards. This regulatory compression is accelerating material substitution timelines faster than existing treated-wood inventories can deplete.
Growth Catalysts
- Heavy-haul axle load expansion:Class I railroads in the United States are testing composite formulations rated for 286,000-pound carloads, creating specification pull for polymer-based alternatives.
- REACH chemical authorization pressure:European wood preservative restrictions are narrowing creosote's allowable applications, redirecting R&D investment toward thermoplastic composite chemistry.
- Recycled feedstock availability:Post-consumer polyethylene and rubber supply chains in North America are achieving scale sufficient to displace virgin resin costs in tie manufacturing.
Market Restraints
- Hardwood supply concentration:Oak and mixed hardwood procurement depends on sawmill capacity clustered in the southeastern United States, exposing buyers to weather-driven fiber shortages.
- Composite fatigue validation gaps:Polymer ties lack century-long performance datasets that underwrite hardwood's insurance and liability acceptance.
- Concrete tie weight penalty:Pre-stressed concrete's 600-plus pound mass restricts deployment to mechanized maintenance corridors, excluding low-density branch lines.
Strategic Opportunities
- California emissions disclosure mandates:State-level chemical transparency requirements are qualifying thermoplastic suppliers ahead of competitors locked into creosote-treated wood.
- Hybrid tie architectures:Glass-reinforced polymer shells bonded to recycled plastic cores offer stiffness-to-weight ratios unachievable in monolithic materials.
- Railroad maintenance outsourcing:Third-party track service contractors in the United States are specifying composite ties to reduce crew lifting injuries and speed installation cycles.
Industry Challenges
- Preservative applicator workforce attrition:Creosote treatment facilities face recruitment gaps as younger workers avoid chemical-handling roles, compressing treating capacity before substitution scales.
- Cross-material specification harmonization:FRA track safety standards implicitly benchmark performance to wood tie behavior, forcing composite innovators to demonstrate equivalence through costly parallel testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railroad Tie Market |
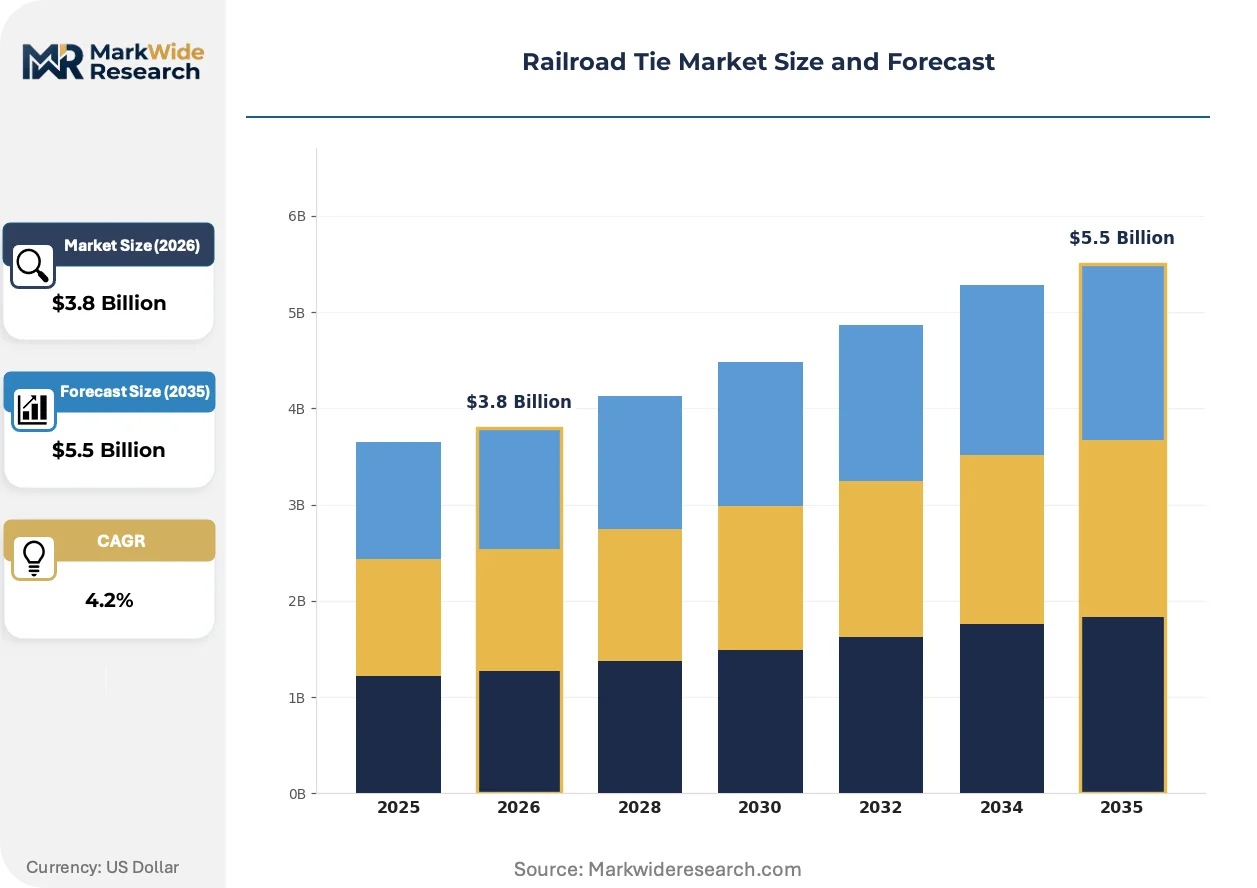
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wooden Ties, Concrete Ties, Steel Ties, Composite Ties End User: Railroad Operators, Contractors, Government Agencies, Industrial Users Application: Freight Transport, Passenger Transport, Maintenance of Way, Landscaping Distribution Channel: Direct Sales, Distributors, Online Retail, Specialty Stores |
| Companies Covered | Stella-Jones, Koppers, Vossloh, Gross & Janes, L.B. Foster, TieTek, Integrico Composites, Evertrak, Narstco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railroad Tie Market Emerging Trajectories
Material science advances are collapsing the performance gap between engineered polymers and traditional hardwood while regulatory chemistry restrictions simultaneously narrow preservative options. These parallel pressures are restructuring supplier qualification criteria and procurement specifications.
Glass-fiber-reinforced recycled HDPE formulations are converging with railroad demand for maintenance-interval extension. Class I freight operators in heavy-haul corridors are piloting these composites at 50-tie test sections, measuring gauge retention and spike-holding torque against oak benchmarks. The technology is converging with lifecycle cost accounting that internalizes disposal and worker-safety externalities previously excluded from capital planning.
The EPA's revised creosote risk assessment under FIFRA is triggering state-level chemical disclosure requirements that exceed federal baselines. Industrial users must now track preservative migration into soil and groundwater at treatment facilities and in-service track segments. Tie suppliers serving California and New York face the steepest compliance burdens, accelerating qualification of alternative materials that bypass creosote entirely.
Buying committees at major freight railroads are consolidating supplier rosters around vertically integrated manufacturers capable of certifying chain-of-custody from raw fiber through final treatment. This concentration is displacing fragmented procurement patterns that previously sourced ties through regional distributors. The shift is most visible in Union Pacific and BNSF specifications that now require single-source accountability for warranty claims and performance failures.
Railroad Tie Market Segmentation
Railroad tie procurement specifications diverge sharply across operational contexts, with freight corridors demanding fatigue-rated hardwood while passenger lines prioritize dimensional stability. Material selection directly governs maintenance intervals, crew safety protocols, and regulatory compliance burdens across each segment.
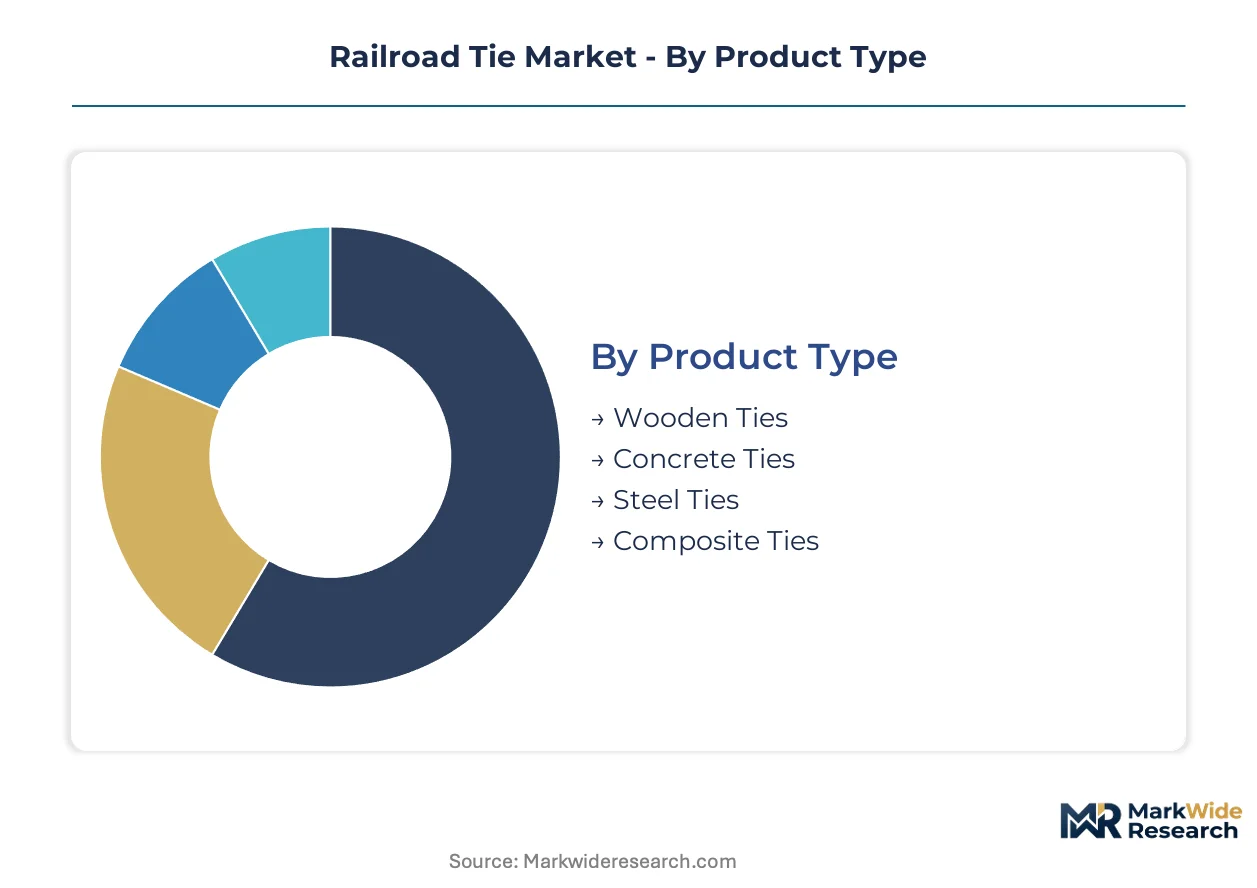
Product Type:
Standardization dominates wooden and concrete tie specifications, while composite formulations remain highly customized to axle-load ratings and climate exposure profiles.
- Wooden Ties:Pressure-treated oak and mixed hardwood members measuring seven by nine inches in cross-section, creosote-impregnated to resist fungal decay and insect attack. Demand concentrates in Class I freight networks across the southeastern United States, where existing treating infrastructure and century-long performance datasets sustain procurement preference despite EPA chemical scrutiny.
- Composite Ties:Thermoplastic formulations—typically glass-fiber-reinforced recycled HDPE or rubber-polymer blends—engineered to match hardwood spike-holding torque and gauge retention. Specifications are expanding most quickly in California and New York corridors where state-level chemical disclosure mandates accelerate qualification of creosote-free alternatives.
- Concrete Ties:Pre-stressed monoblock or twin-block designs weighing 600-plus pounds, deployed in high-speed passenger corridors requiring absolute dimensional stability under thermal cycling.
- Steel Ties:Rolled or cast profiles with integrated rail fastening systems, specified in tunnels and limited-clearance industrial spurs where timber depth is constrained.
Leading the category by volume: Wooden Ties. Expanding most quickly: Composite Ties.
End User:
Procurement scale and specification authority concentrate with network-owning operators, while contractor and agency buyers fragment across project-based demand patterns.
- Railroad Operators:Class I freight carriers and regional passenger authorities specifying tie performance grades under FRA track safety standards, consolidating supplier rosters around vertically integrated manufacturers capable of single-source warranty accountability.
- Contractors:Third-party track service firms in the United States increasingly specifying composite ties to reduce crew lifting injuries and accelerate installation cycles on maintenance outsourcing contracts.
- Government Agencies:State departments of transportation and transit authorities procuring ties for publicly funded corridor improvements, subject to prevailing wage and domestic content requirements.
- Industrial Users:Mining, logging, and manufacturing operations maintaining private spur connections, sourcing through regional distributors with limited specification leverage.
Volume concentrates with Railroad Operators. Contractor segment shows steepest specification shift toward engineered polymers.
Application:
Load intensity and speed regimes dictate material selection, with heavy-haul freight and high-speed passenger applications driving premium specification tiers.
- Freight Transport:Heavy-haul corridors rated for 286,000-pound carloads testing composite formulations at 50-tie pilot sections, measuring performance against oak benchmarks under cyclic fatigue.
- Passenger Transport:High-speed and commuter lines specifying concrete ties for dimensional stability, with composite alternatives penetrating light-rail and streetcar networks.
- Maintenance of Way:Spot replacement programs and full renewal projects, with outsourcing trends shifting procurement authority from operator engineering departments to contractor fleets.
- Landscaping:Decorative and structural reuse of retired ties, subject to environmental handling restrictions on creosote-impregnated material.
Freight Transport commands the largest installed base. Composite penetration is climbing fastest in Maintenance of Way outsourcing contracts.
Distribution Channel:
Channel selection correlates with buyer scale and specification complexity, with direct relationships displacing fragmented procurement patterns.
- Direct Sales:Long-term supply agreements between Class I railroads and treating facilities or composite manufacturers, incorporating chain-of-custody certification and performance warranties.
- Distributors:Regional inventory positions serving contractor and industrial accounts with shorter lead times and lower minimum order quantities.
- Online Retail:Limited to landscaping and small-scale industrial applications, with freight costs constraining shipment economics for bulk structural members.
- Specialty Stores:Localized availability for maintenance-of-way consumables and replacement hardware, not primary tie procurement.
Direct Sales captures the highest volume concentration. Distributor channel is gaining share fastest among mid-tier contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Railroad tie production clusters in timber-rich regions with established treating infrastructure, while consumption concentrates in freight-dense corridors where replacement cycles accelerate. The United States dominates both fabrication volume and specification-setting authority for North American networks.
United States
Class I freight carriers in the United States are driving composite tie pilots rated for 286,000-pound carloads across heavy-haul corridors. The EPA regulates wood preservative emissions under FIFRA, tightening creosote exposure limits that redirect procurement toward thermoplastic alternatives. Treating capacity concentrates in the southeastern states, where hardwood sawmill networks supply oak and mixed hardwood feedstock to regional impregnation facilities.
Canada
Canadian National and Canadian Pacific Kansas City operate transcontinental networks requiring tie replacement across extreme climate zones from prairie cold to coastal moisture. Health Canada and PMRA govern preservative chemistry approvals, maintaining alignment with EPA risk assessments while enforcing domestic environmental impact standards. Quebec and Ontario host treating facilities serving both domestic operators and cross-border supply contracts to United States railroads.
Germany
Deutsche Bahn's high-speed passenger corridors specify concrete ties for dimensional stability under thermal cycling, while freight branches retain wooden alternatives. ECHA administers REACH chemical authorizations that have narrowed creosote's allowable applications, redirecting R&D investment toward polymer-based formulations. Manufacturing clusters in North Rhine-Westphalia and Bavaria produce prestressed concrete monoblocks for export across European rail networks.
China
China State Railway Group operates the world's largest rail network, consuming ties across both high-speed passenger and heavy-haul freight corridors. MIIT and GB standards govern track component specifications, with MEE enforcing environmental compliance at treatment facilities. Manufacturing concentrates in Shandong Province and the Yangtze River Delta, where integrated steel-concrete-wood supply chains serve domestic replacement cycles and Belt and Road export projects.
Australia
Australian rail operators face hardwood supply constraints as native forest harvesting restrictions tighten, accelerating interest in composite and steel alternatives. The country's national environmental regulator imposes chemical disclosure requirements at treatment facilities that exceed baseline standards. Queensland and Western Australia host mining rail corridors with intensive tie consumption, while New South Wales passenger networks pilot concrete and polymer alternatives in coastal humidity zones.
Railroad Tie Market Vendor Landscape
The competitive structure tilts toward vertically integrated hardwood treaters with captive timber supplies and specialized composite formulators bypassing preservative chemistry entirely. Market concentration remains moderate, with regional treating networks coexisting alongside emerging polymer specialists. Two strategic archetypes dominate: legacy wood treaters leveraging century-long performance datasets, and engineered material innovators achieving axle-load parity through thermoplastic formulations. Competitive moves center on backward integration into timber procurement and strategic partnerships with Class I railroads for pilot program validation.
Within the legacy treatment tier, Stella-Jones and Koppers exemplify archetypes of scale-driven hardwood impregnation with established distribution networks. Integrico Composites occupies a position among polymer specialists, representing the engineered-material vector that bypasses creosote regulatory exposure entirely. These three companies illustrate the structural bifurcation between chemical-dependent wood preservation and thermoplastic innovation pathways reshaping supplier qualification criteria.
| Leading Market Players |
|---|
| Stella-Jones |
| Koppers |
| Vossloh |
| Gross & Janes |
| L.B. Foster |
| TieTek |
| Integrico Composites |
| Evertrak |
| Narstco |
| Others |
Supply Flow & Price Mechanics
Thermoplastic composite formulation advances are collapsing production cost differentials against creosote-treated hardwood while simultaneously redistributing supply power toward polymer feedstock processors and away from traditional timber-treating networks. This dual shift concentrates procurement leverage with Class I railroads capable of specifying performance-tier contracts across material categories.
Pricing Analysis
Margin tightening in creosote-treated wood ties reflects EPA chemical scrutiny compressing treating capacity ahead of composite substitution scale. Three-tier pricing structure across premium composite, standard hardwood, and economy mixed-grade tiers separates buyers by axle-load rating and warranty length. Cost-down pressure on standard hardwood accelerates because preservative applicator workforce attrition is raising labor premiums at treating facilities. Contractor buyers show highest price sensitivity, while Class I freight operators prioritize lifecycle cost over unit price.
Supply Chain Analysis
Single-source vulnerability sits with oak and mixed hardwood procurement concentrated in the southeastern United States, where sawmill capacity feeds regional creosote impregnation facilities. Raw material dependencies center on post-consumer polyethylene supply from North American recycling streams, glass fiber reinforcement from domestic manufacturers, and rubber crumb from tire processors. Tariff exposure on polymer resin imports presents structural risk for composite formulators lacking captive feedstock arrangements. Distribution runs through direct long-term supply agreements for railroad operators, with regional distributors serving contractor and industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The railroad tie market is consolidating around vertically integrated manufacturers capable of certifying chain-of-custody accountability, as EPA regulatory compression forces fragmented regional treaters toward exit or acquisition.
For Market Incumbents: Cement supply continuity through backward integration into hardwood procurement in the southeastern United States, insulating against weather-driven fiber shortages that disrupt competitor treating schedules. Secure composite formulation partnerships ahead of FRA specification harmonization deadlines, positioning for dual-material qualification that locks out pure-play hardwood competitors facing creosote restriction timelines. For New Entrants and Emerging Players: Begin with thermoplastic composite pilots targeting California and New York corridors where state-level chemical disclosure mandates have already qualified alternative materials ahead of federal baseline shifts. Focus initial production capacity on 286,000-pound axle-load ratings for heavy-haul freight applications, leveraging recycled feedstock cost advantages against virgin resin-dependent incumbents. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by Class I railroads seeking captive supply security, or financial sponsor roll-ups of regional treating facilities facing workforce attrition pressures. Long-term viability favors composite specialists with validated fatigue datasets and polymer chemistry IP, while pure-play hardwood treaters face stranded asset risk from pending EPA determinations. Watch for FRA composite equivalence rulings as the inflection signal accelerating material substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Timber Procurement | Captive hardwood supply insulates Stella-Jones and Koppers against weather-driven fiber shortages in southeastern sawmill networks. |
| Composite Formulation R&D Partnership | Glass-reinforced HDPE development with Class I railroads accelerates FRA equivalence certification ahead of regulatory deadlines. |
| Recycled Feedstock Supply Agreement | Post-consumer polyethylene contracts with North American recyclers displace virgin resin cost volatility for Integrico Composites. |
| Regional Treating Facility Acquisition | Consolidation of southeastern impregnation capacity captures stranded asset discounts as EPA scrutiny intensifies. |
| California Market Qualification Program | State chemical disclosure compliance opens specification access ahead of competitors locked into creosote-dependent supply chains. |
Methodological Framework
Document review covered FRA track safety standards, EPA FIFRA regulatory filings, and railroad capital expenditure disclosures, complemented by interviews with Class I railroad engineering directors, tie procurement managers at Union Pacific and BNSF, composite manufacturing technical leads, and southeastern hardwood sawmill operators. Secondary validation drew from SEC 10-K filings of publicly traded treaters, customs trade data on polymer resin imports, and state environmental agency chemical disclosure records. Bottom-up unit demand modeling triangulated against top-down replacement cycle estimates across the analysis window.
Volume and value projections reflect segment-level modeling across product type, end user, application, and distribution channel dimensions, with freight transport axle-load ratings and passenger corridor speed tiers as railroad-specific segmentation inputs. CAGRs were derived from historical replacement volumes, projected traffic growth, and material substitution elasticity assumptions. Composite penetration curves incorporated pilot program timelines from Class I railroad disclosures and state regulatory acceleration factors.
Underlying measurement precision varies by segment; wooden tie demand carries tighter precision from century-long replacement datasets, while composite forecasts reflect greater uncertainty pending FRA equivalence rulings. Forecasts reflect assumptions about EPA creosote determination timing, recycled feedstock cost trajectories, and Class I railroad capital allocation priorities. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Train Exterior Lighting Market
Railway
Solar Train Market
Railway
Train Suspension System Market
Railway
Railway System Market
Railway
Railway Track Market
Railway
Locomotive Radiator Fan Market
Railway
Automatic Train Supervision Market
Railway
Asia Pacific Rail Freight Transport Market
Railway
Rail Damper Market
Railway
Rail Brace Market
Railway
Railway Bearing Market
Railway
Railway Buffer Stops Market
Railway
Railway Rolling Stock Market
Railway
Rail Bellows Market
Railway
Automatic Train Control Market
Railway
Railway Window Market