
 Rail Components Market | 2026-2036
Rail Components Market Size, Share, and Industry Trends Forecast 2026-2036
Rail Components Market Analysis
Chinese steel foundries and forging cooperatives is recalibrating output schedules to match locomotive build rates across Asia. Wabtec Corporation leverages its North American service network to sustain aftermarket revenue streams. CRRC Corporation Limited anchors domestic supply security through captive production of traction motors and couplers. Siemens Mobility differentiates via digital component integration for predictive maintenance platforms.
Rail components encompass the engineered subsystems—brakes, couplers, traction motors, and trailer bogies—fabricated from alloy steel, aluminum extrusions, and fiber-reinforced composites to withstand cyclic loading, thermal stress, and impact forces exceeding 1,000 kN. These assemblies translate prime-mover torque into adhesion-limited tractive effort while modulating deceleration through friction or regenerative absorption. Traction motors and braking systems capture the deepest margin pools due to electrification mandates and safety-critical certification requirements. Composite material adoption is expanding fastest among interior and non-structural trailer elements where mass reduction yields direct energy savings.
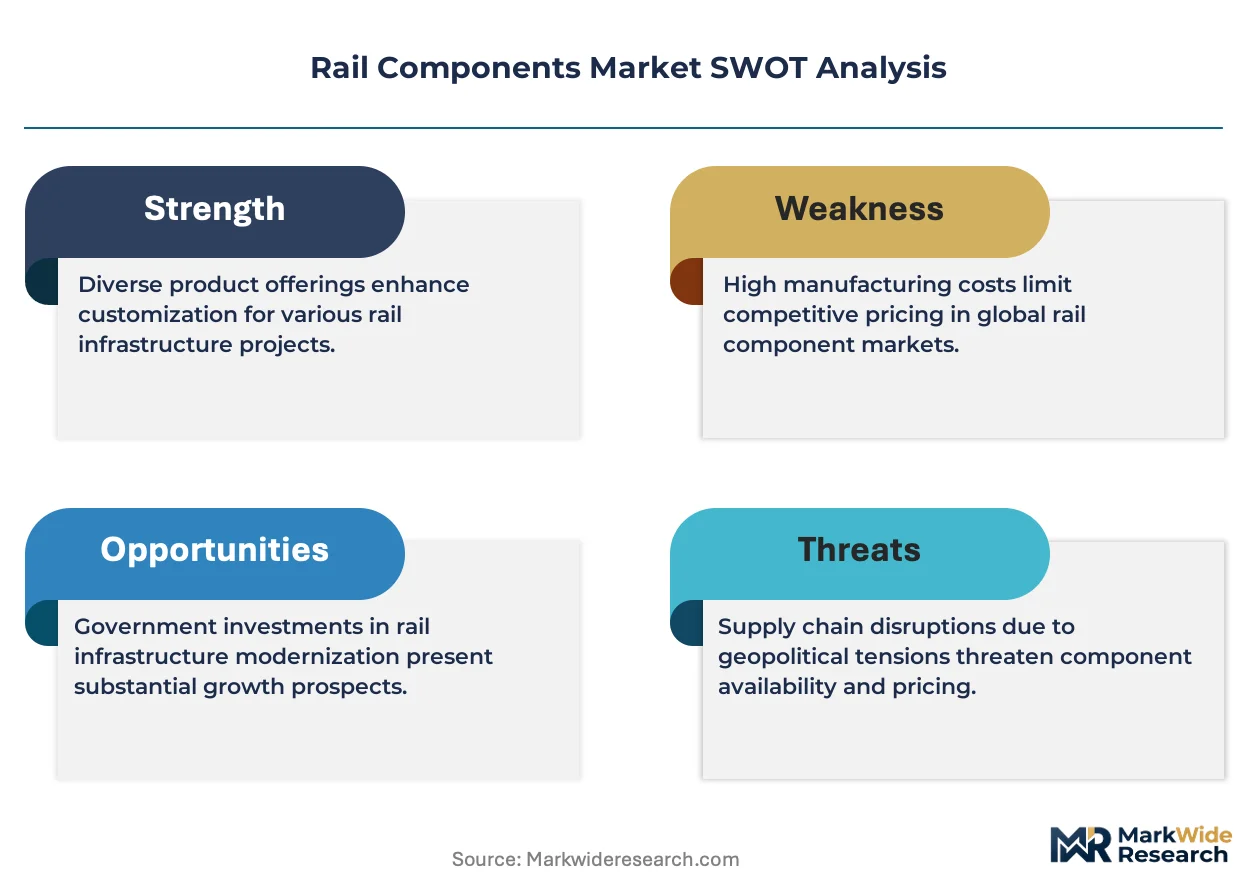
The Federal Railroad Administration enforces crashworthiness and brake performance standards that OEMs must validate through full-scale dynamic testing, elevating engineering barriers for new entrants. China's NMPA and GB standards, alongside the EU's CE marking and MDR-aligned supplier audits, impose divergent conformity pathways that fragment component qualification costs. Stakeholders must monitor how interoperability mandates between national rail networks reshape procurement specifications and supplier qualification timelines.
Market Dynamics
The electrification of mainline freight corridors is compressing procurement cycles for high-voltage traction systems while simultaneously elevating supplier qualification barriers around thermal management and electromagnetic compatibility testing protocols.
Growth Catalysts
- F-Gas Regulation:The European Union's phasedown of fluorinated greenhouse gases in mobile air conditioning and braking systems is forcing rapid supplier retooling toward CO₂-based or magnetic braking alternatives, expanding addressable market for compliant subsystem vendors.
- Freight Fleet Modernization:North American Class I railroads are replacing legacy DC traction with AC propulsion systems across heavy-haul corridors, generating replacement demand for traction motors, inverters, and transformer packages in 4,000+ horsepower locomotives.
- High-Speed Rail Expansion:China's CRRC and domestic forging cooperatives are scaling output of forged wheelsets and axle assemblies to match 350 km/h corridor buildouts across Southeast Asia and Central Asia, concentrating component demand in Chengdu and Changzhou manufacturing clusters.
Market Restraints
- Alloy Steel Price Volatility:Nickel and molybdenum input costs for bogie frames and coupler castings fluctuate with Indonesian ore export policies and Russian supply disruptions, compressing foundry margins on fixed-price OEM contracts.
- Supply Concentration Risk:Forged railway wheels and axles depend on a narrow base of German, Austrian, and Chinese suppliers with limited excess heat-treatment capacity, creating vulnerability to single-source bottlenecks during demand surges.
- Regulatory Fragmentation:Divergent crashworthiness standards between the Federal Railroad Administration's Tier III passenger rules and China's GB/T rail vehicle safety specifications force parallel validation programs that extend qualification timelines by 18-24 months.
Strategic Opportunities
- Digital Component Integration:Predictive maintenance platforms combining vibration sensors, thermal imaging, and edge computing are creating aftermarket revenue streams for component suppliers who embed diagnostics into traction motors and brake control units.
- Southeast Asian Corridor Buildouts:Indonesia's Java high-speed rail and Vietnam's North-South Express Railway represent greenfield procurement opportunities for signaling, track, and rolling stock component vendors without legacy incumbent relationships.
- Composite Material Substitution:Fiber-reinforced polymer interior panels and HVAC ducting in passenger coaches offer 30-40% mass reduction versus aluminum extrusions, opening specification wins with operators prioritizing energy efficiency metrics.
Industry Challenges
- Electromagnetic Compatibility Certification:Traction inverter and auxiliary power unit suppliers face extended validation cycles against IEC 61000 and EN 50121 standards as power electronics switching frequencies increase interference risks with signaling systems.
- Welding and NDT Specialist Scarcity:Alloy steel bogie fabrication requires certified EN 15085 welders and phased-array ultrasonic technicians in concentrations that outpace vocational training pipeline output across Central European manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rail Components Market |
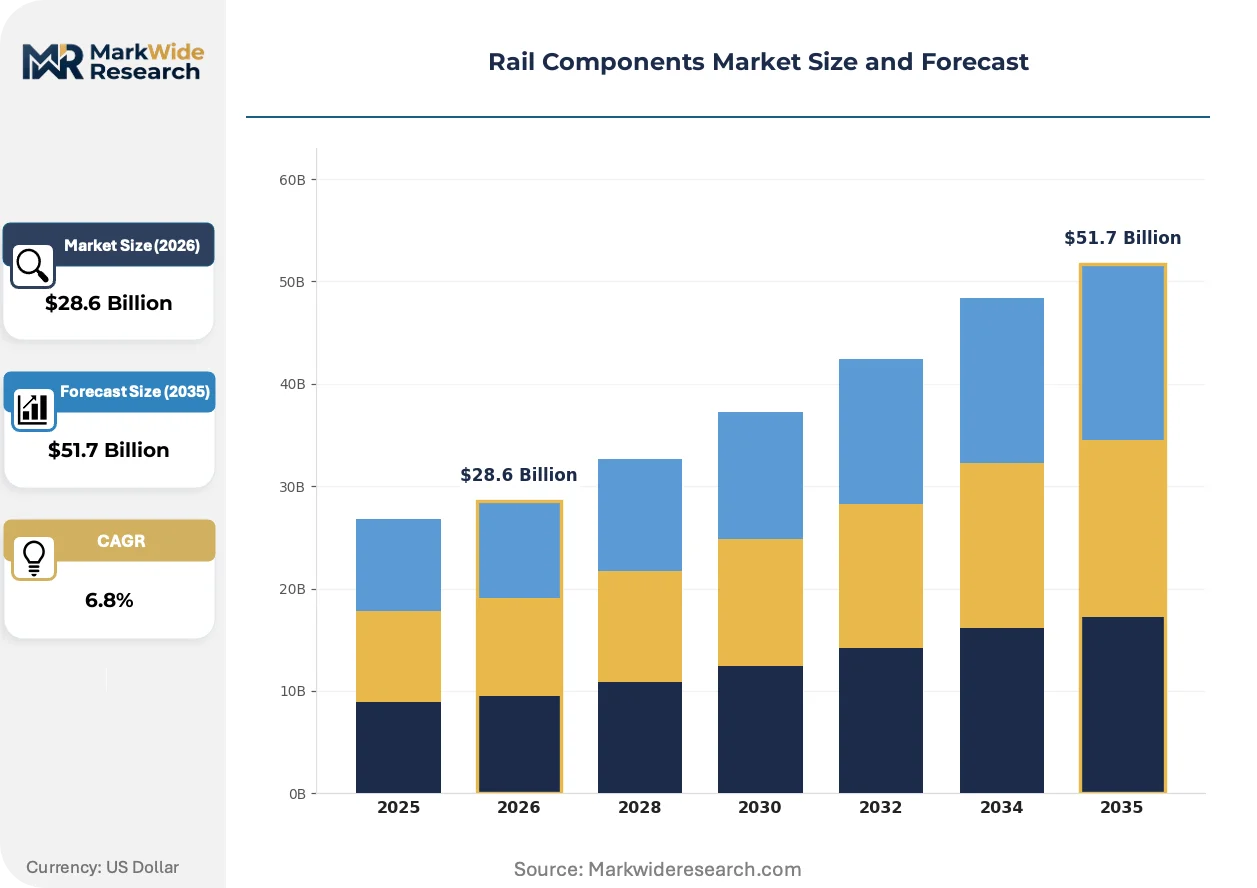
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Brakes, Couplers, Traction Motors, Trailers Material: Steel, Composite, Aluminum, Plastic Application: Freight, Passenger, Light Rail, High-Speed End User: OEMs, Maintenance Providers, Transport Authorities, Private Operators |
| Companies Covered | Wabtec Corporation, Hitachi Rail, CRRC Corporation Limited, Vossloh AG, Knorr-Bremse AG, Alstom SA, Stadler Rail AG, CAF, Siemens Mobility, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rail Components Market Emerging Trajectories
Active integration of digital sensing layers into mechanical subsystems is compressing maintenance intervals while enabling condition-based replacement models that alter traditional spare parts economics.
Silicon carbide power semiconductors are replacing insulated-gate bipolar transistors in traction inverters, enabling higher switching frequencies and reduced cooling system mass. Japanese and European OEMs are adopting these devices in 2024-2025 locomotive platforms. This transition is modularizing power electronics architectures by separating thermal management, gate drivers, and DC-link capacitors into swappable sub-assemblies.
REACH authorization requirements for chromium trioxide in corrosion-resistant coatings are forcing foundries to qualify trivalent chrome and plasma electrolytic oxidation alternatives for brake calipers and suspension components. The restriction affects suppliers serving EU passenger fleets most acutely, with German and French operators now specifying coating-free material specifications in new tenders.
Freight operators are unbundling component-level service contracts from rolling stock procurement, creating direct purchasing relationships with brake, coupler, and traction motor specialists previously captive to system integrators. This disintermediation is most pronounced in Australian iron ore and North American coal corridors where maintenance cost transparency drives procurement autonomy.
Rail Components Market Segmentation
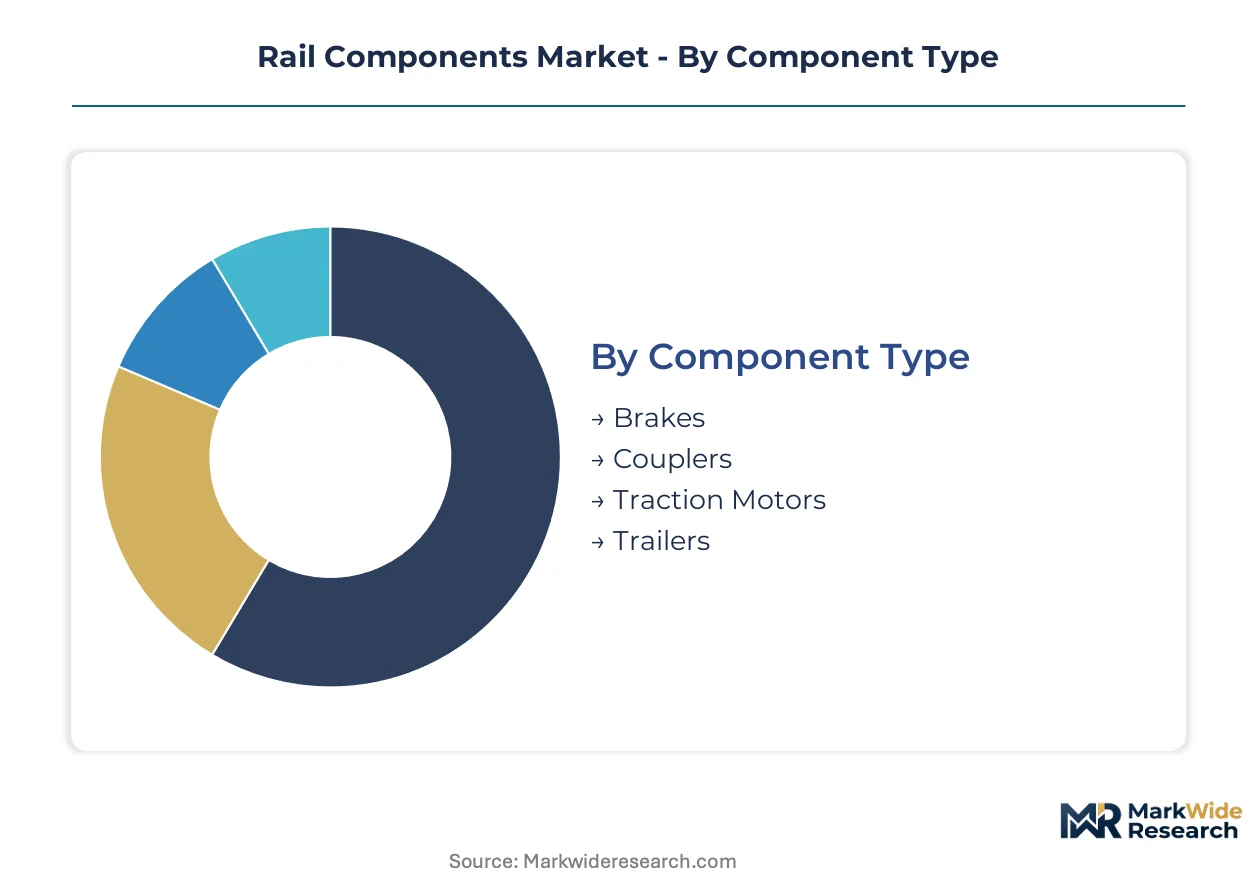
Rail component procurement splits sharply between high-volume standard assemblies and premium certified subsystems. Understanding where margin pools concentrate across material grades and application tiers shapes supplier positioning and R&D allocation decisions.
Component Type:
Volume concentrates in mechanical assemblies with established forge patterns; premium pools sit in electrified propulsion and electronically controlled braking.
- Brakes:Friction and regenerative assemblies incorporating sintered pads, cast iron discs, and eddy current retarders. European F-Gas Regulation is compressing procurement timelines toward CO₂-based and magnetic alternatives as operators in Germany and France phase out fluorinated systems.
- Traction Motors:AC induction and permanent magnet synchronous machines converting inverter output to axle torque. China's CRRC and domestic suppliers are scaling high-speed rail motor output for 350 km/h corridors across Southeast Asia and Central Asia, anchoring demand in Chengdu manufacturing clusters.
- Couplers:Automatic and semi-permanent connection systems forged from alloy steel billets.
- Trailers:Non-powered bogies, axle boxes, and suspension modules for passenger coaches and freight wagons.
Today's leader: Traction Motors. Tomorrow's challenger: Brakes.
Material:
Cost tiers separate structural load-bearing grades from interior finish specifications, with energy efficiency mandates reshaping substitution economics.
- Steel:Alloy and carbon grades for bogie frames, wheelsets, and coupler castings requiring EN 15085 welding certification. Nickel and molybdenum input volatility tied to Indonesian ore export policies is compressing foundry margins on fixed-price OEM contracts.
- Composite:Fiber-reinforced polymer panels and HVAC ducting delivering 30-40% mass reduction versus metal extrusions. Passenger operators in France and Germany are specifying composite interiors in new tenders to meet energy efficiency metrics.
- Aluminum:Extruded profiles for body shells and structural members in light rail and metro applications.
- Plastic:Interior trim, cable management, and non-structural housings.
Steel dominates tonnage. Composites are climbing the fastest on energy efficiency mandates.
Application:
Freight corridors drive replacement volume; passenger segments command specification premiums through safety certification requirements.
- Freight:Heavy-haul locomotives and wagon fleets operating on North American Class I and Australian iron ore corridors. AC propulsion retrofits across 4,000+ horsepower locomotives are generating replacement demand for traction motors and transformer packages.
- High-Speed:Passenger trains exceeding 250 km/h requiring forged wheelsets, active suspension, and aerodynamic components. China's corridor buildouts across Southeast Asia and Central Asia are concentrating axle and wheel assembly demand in Changzhou forging cooperatives.
- Passenger:Intercity and regional rolling stock with moderate speed requirements.
- Light Rail:Tram and metro systems with frequent stop-start cycles and tight curvature constraints.
Freight commands unit volume. High-Speed offers the steepest expansion trajectory.
End User:
Procurement autonomy is fragmenting as operators disintermediate system integrators for direct component relationships.
- OEMs:Rolling stock manufacturers integrating subsystems into complete trainsets. Divergent FRA Tier III and China's GB/T crashworthiness standards are forcing parallel validation programs that extend qualification timelines.
- Private Operators:Freight and mining railroads unbundling service contracts from rolling stock procurement. Australian iron ore and North American coal corridors are driving direct purchasing relationships with brake and traction motor specialists.
- Maintenance Providers:Independent service shops and captive railway workshops performing component overhaul and replacement.
- Transport Authorities:Government entities specifying component standards for publicly funded networks.
OEMs retain design control. Private Operators are gaining share fastest on cost transparency demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates high-speed rail component manufacturing while the United States drives freight modernization demand. Germany anchors European braking system innovation under tightening environmental mandates. Each geography shapes distinct procurement patterns through regulatory divergence and industrial clustering.
United States
Class I railroads are retrofitting AC propulsion systems across 4,000+ horsepower locomotive fleets. The Federal Railroad Administration enforces Tier III crashworthiness standards that extend supplier qualification timelines. Manufacturing activity clusters around Pittsburgh and Chicago, where Wabtec Corporation maintains extensive service networks for aftermarket brake and coupler systems.
Germany
Knorr-Bremse AG and Siemens Mobility anchor production of electronically controlled braking and traction systems for European corridors. The EU F-Gas Regulation is accelerating CO₂-based brake alternatives as operators phase out fluorinated systems. Industrial concentration in Munich and Berlin supports precision forging and electromagnetic compatibility testing facilities serving cross-border rail networks.
China
CRRC Corporation Limited scales output of traction motors, forged wheelsets, and axle assemblies for 350 km/h corridors across Southeast Asia and Central Asia. GB standards and NMPA certification requirements create captive domestic supply chains. Manufacturing gravity centers on Chengdu and Changzhou, where forging cooperatives match locomotive build rates with heat-treatment capacity expansion.
Japan
Hitachi Rail advances silicon carbide traction inverters for next-generation Shinkansen platforms. METI efficiency mandates push permanent magnet synchronous motor adoption in commuter and intercity fleets. Industrial activity concentrates in Kanto around Tokyo and Kansai around Osaka, where precision machining clusters serve both domestic operators and export markets.
India
Dedicated freight corridors and metro expansion in Mumbai, Delhi, and Bangalore are generating procurement for bogies, brakes, and traction packages. BIS certification and the PLI scheme for rail component manufacturing are reshaping supplier qualification pathways. Domestic foundries in Jharkhand and Odisha are scaling alloy steel casting capacity to reduce import dependence for wheel and axle assemblies.
Rail Components Market Vendor Landscape
Chinese producers anchor volume manufacturing through integrated steel forging and captive component supply; European specialists hold premium positions in digitally integrated braking and propulsion systems. The vendor base splits between scale-driven fabricators serving freight operators and certification-heavy subsystem vendors focused on passenger safety. Three archetypes dominate: state-backed national champions with domestic market protection, independent component specialists with deep aftermarket service networks, and diversified industrial conglomerates leveraging cross-sector manufacturing expertise. Competitive moves center on backward integration into alloy steel supply and technology licensing partnerships for silicon carbide power electronics.
Among state-backed fabricators, CRRC Corporation Limited exemplifies vertical control from raw material to finished subsystem. European specialists in braking and digital integration include Knorr-Bremse AG, which occupies a position defined by regulatory compliance depth. North American aftermarket service networks are represented by Wabtec Corporation, anchoring the maintenance-centric competitive vector through proximity to Class I railroad operations.
| Leading Market Players |
|---|
| Wabtec Corporation |
| Hitachi Rail |
| CRRC Corporation Limited |
| Vossloh AG |
| Knorr-Bremse AG |
| Alstom SA |
| Stadler Rail AG |
| CAF |
| Siemens Mobility |
| Others |
Supply Flow & Price Mechanics
North American Class I railroads and European passenger fleet operators concentrate procurement volume, anchoring contract-based long-term offtake pricing with embedded service bundles. This buyer structure elevates qualification premiums for certified subsystems while compressing spot-market leverage for commodity-grade mechanical assemblies.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for forged wheelsets and traction motor assemblies. Three-tier pricing structure across premium, standard, and economy levels separates FRA Tier III-certified braking systems from GB/T-compliant domestic alternatives and uncertified aftermarket rebuilds. Cost compression in standard-grade coupler castings is intensifying because Indonesian nickel export restrictions feed alloy steel volatility. Freight operators in Australian iron ore corridors exhibit the highest price sensitivity, while high-speed rail authorities in Germany and France prioritize certification depth over unit cost.
Supply Chain Analysis
Ocean freight rates and specialized flatcar availability for oversized forging dies shape landed cost differentials between European and Asian supply bases. Geographic supply concentration rests on Germany, China, and Austria for heat-treated railway wheels and axles. Raw material dependencies center on Indonesian nickel, Russian molybdenum, and Chinese rare earth elements for permanent magnet motors. Single-source vulnerability pervades the narrow base of certified forge shops with EN 15085 welding accreditation. Distribution runs through captive OEM supply agreements and direct procurement relationships with maintenance providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rail components market reads as a late-cycle quality story. Electrification mandates and F-Gas regulatory deadlines are displacing legacy friction braking toward certified CO₂-based and magnetic alternatives, concentrating margin capture with specification-compliant vendors.
For Market Incumbents: Acquire heat-treatment capacity and electromagnetic compatibility testing facilities in Central European industrial clusters. Defensive consolidation should prioritize EN 15085 welding certification pipelines and silicon carbide inverter packaging capabilities to offset substitution threats from Chinese integrated suppliers. Backward integration into alloy steel billet supply anchors margin stability against Indonesian ore policy volatility. For New Entrants and Emerging Players: Digital sensing layers embedded in brake control units and traction motors offer technology-first entry into aftermarket predictive maintenance contracts. White-space targets include Southeast Asian greenfield corridors in Indonesia and Vietnam lacking legacy incumbent relationships. Specification engineering services for EU F-Gas compliance represent the most penetrable wedge, with direct sales to private freight operators bypassing established system integrator channels. For Investors and Strategic Acquirers: Diversified industrial conglomerates with cross-sector manufacturing expertise are the most active acquirer in this space. Long-term viability favors vendors with captive certification depth across multiple regulatory regimes rather than single-market fabricators. Acquisition target archetypes include mid-cap brake subsystem specialists with established Knorr-Bremse or Siemens Mobility supplier status. Monitor EU F-Gas phase-down enforcement velocity as the critical inflection signal for compliant technology valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Steel Supply | Captive nickel and molybdenum sourcing insulates CRRC and European forges from Indonesian export volatility. |
| Silicon Carbide Traction Inverter Adoption | Hitachi Rail and Siemens Mobility platforms achieve higher switching frequencies with reduced cooling mass. |
| Digital Component Integration | Embedded vibration sensors in Wabtec brake units enable condition-based replacement revenue streams. |
| EU F-Gas Compliance Certification | CO₂-based braking alternatives qualify Knorr-Bremse for German and French passenger fleet tenders. |
| Southeast Asian Corridor Partnerships | Greenfield procurement in Indonesia's Java high-speed rail bypasses legacy supplier relationships. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement spanned procurement directors at North American Class I railroads, rolling stock platform engineers at CRRC and Alstom, maintenance heads at Australian iron ore operators, and regulatory affairs leads navigating FRA Tier III and EU F-Gas compliance pathways. Secondary validation drew from FRA safety bulletins, ECHA REACH authorization databases, Chinese customs trade data, and SEC filings of listed rail component suppliers. Bottom-up volume modeling triangulated against top-down OEM production forecasts across the analysis window.
Historical reference periods anchored the projection horizon to pre-pandemic baseline capacity utilization and post-electrification demand inflection points. The analytical framework segmented by component type, material grade, application tier, and end-user procurement autonomy, with additional dimensioning around regulatory certification clusters. CAGRs derived from fitted growth curves applied to electrified propulsion and electronically controlled braking subsystems. Industry-specific inputs incorporated alloy steel price indices, forge capacity utilization rates, and electromagnetic compatibility certification queue lengths.
The model holds under stable ore export policies and sustained electrification capital commitment; deviation in Indonesian nickel licensing or EU F-Gas enforcement velocity would shift component substitution timelines and supplier qualification economics. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Ceramic Ball Bearings Market
Vehicle Components
Exhaust Gas Recirculation (EGR) Valve Market
Vehicle Components
Automotive Battery Terminals Market
Vehicle Components
Electric Vehicle High Voltage Connector System Market
Vehicle Components
Electric Wheelbarrow Market
Vehicle Components
Motor Monitoring Market
Vehicle Components
Mobility Aids and Transportation Equipment Market
Vehicle Components
HCV Axles Market
Vehicle Components
Composite Bearings Market
Vehicle Components
Hooklift Trailer Market
Vehicle Components
Refrigerated Trailer Hinges Market
Vehicle Components
CV Brake Controls Market
Vehicle Components
Steering Tie Rod Market
Vehicle Components
Automotive Composite Suspension Components Market
Vehicle Components
Gas-Powered Chainsaw Market
Vehicle Components
Global Motorcycle Chain Sprocket Market