
 Railway Buffer Stops Market | 2026-2036
Railway Buffer Stops Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Buffer Stops Market Analytics
The EU Green Deal is consolidating demand around low-emission buffer stop specifications across European rail networks. voestalpine Railway Systems leverages its integrated steel production to supply certified low-carbon buffer systems. SPITZKE MAST- UND STAHLBAU anchors German domestic demand through specialized fabrication capabilities for heavy-duty terminal installations. Gantrex competes internationally with modular buffer stop designs suited to diverse track gauges and loading profiles.
Railway buffer stops are terminal track safety devices engineered to absorb kinetic energy from rolling stock during overrun events, typically incorporating elastomeric pads, hydraulic dampers, or friction-based deceleration mechanisms rated for specific impact velocities and mass loadings. Their primary purpose is preventing catastrophic derailment, infrastructure damage, and casualty incidents at track termini. Fixed buffer installations still occupy the largest installed base globally, though hydraulic variants are capturing disproportionate growth in high-frequency passenger terminals where resettable operation reduces maintenance downtime. Composite material adoption is accelerating fastest among segments, driven by corrosion resistance and reduced track-bed loading requirements in coastal and chemically exposed environments.
EMA's rail safety directives, the EU F-Gas Regulation's indirect pressure on maintenance depot equipment choices, and Germany's KBA track certification protocols collectively elevate product compliance thresholds and filter market access for non-certified suppliers. India's CEA electrification mandates and BIS infrastructure standards are similarly tightening specification requirements for buffer stops on new broad-gauge corridors. Stakeholders must monitor evolving national rail safety frameworks and material certification timelines to align R&D pipelines with procurement qualification windows.
Market Dynamics
EU Green Deal embodied carbon mandates are compressing specification windows for rail infrastructure materials, forcing manufacturers to requalify steel grades and composite formulations ahead of procurement cycles.
Growth Catalysts
- India's Dedicated Freight Corridors:The Dedicated Freight Corridor Corporation is tendering terminal protection systems for over 3,000 route kilometers of new broad-gauge infrastructure, creating concentrated demand for heavy-duty buffer stops.
- EMA Rail Safety Directives:Updated European Medicines Agency-adjacent rail safety frameworks now mandate energy-absorption certification for all new terminal installations, eliminating uncertified suppliers from public procurement.
- Recycled Composite Materials:Glass-fiber-reinforced polymer formulations derived from industrial waste streams are displacing conventional steel in coastal installations where salt corrosion accelerates maintenance cycles.
Market Restraints
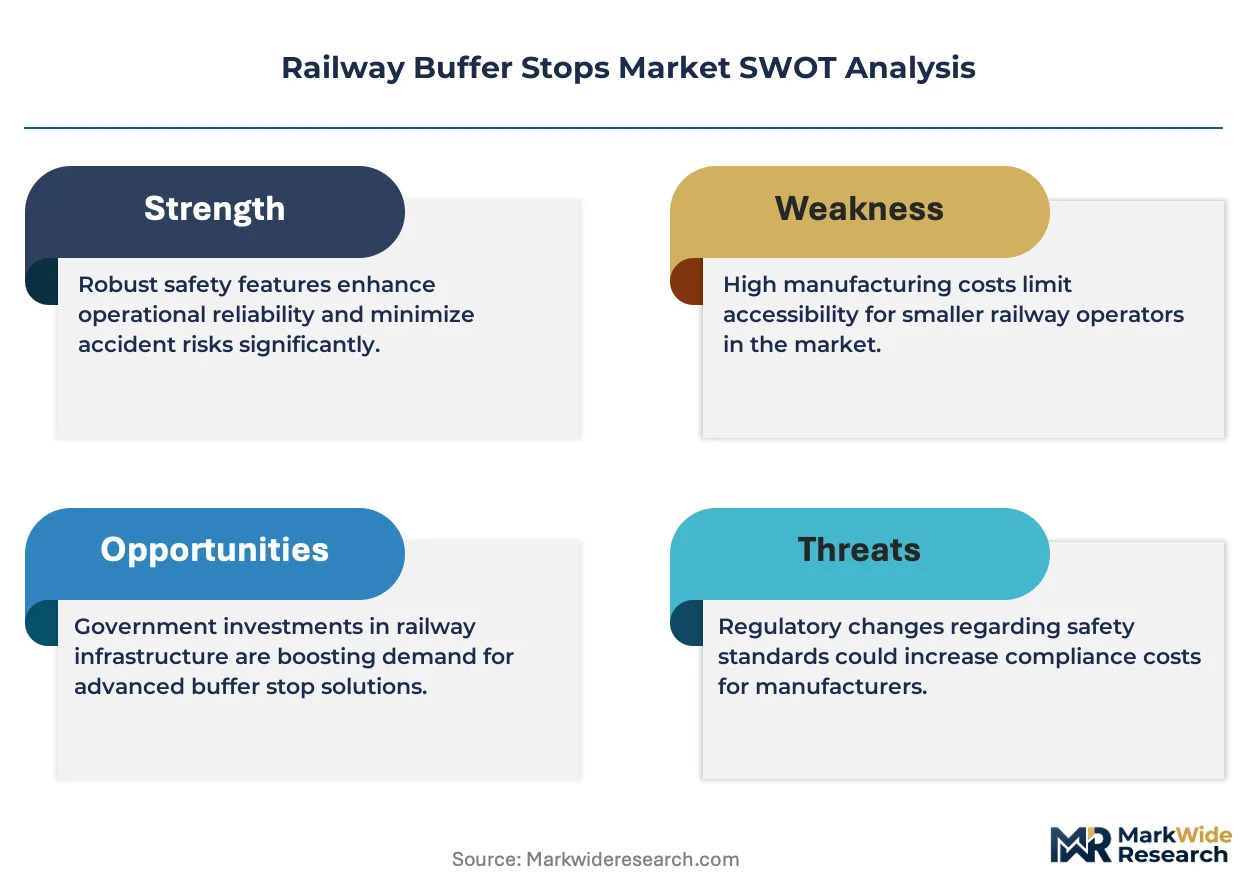
- Low-Carbon Steel Premium:Hydrogen-reduced steel from integrated mills commands 15-25% cost premiums over blast-furnace grades, squeezing margins on EU-compliant buffer system contracts.
- Specialized Fabrication Concentration:Heavy-duty terminal installations requiring 200+ ton impact ratings depend on a limited German and Austrian supplier base with certified welding and damping integration capabilities.
- EU F-Gas Regulation Friction:Hydraulic buffer systems using conventional refrigerant-based damping fluids face retrofit requirements and supply uncertainty, slowing adoption in maintenance-sensitive passenger terminals.
Strategic Opportunities
- Japan's Urban Metro Expansion:Tokyo Metro and Osaka Municipal Subway are procuring resettable hydraulic buffer systems for high-frequency terminals where maintenance access windows are compressed to overnight hours.
- CEA Electrification Mandates:India's Central Electricity Authority requirements for 25kV traction infrastructure on new corridors bundle buffer stop procurement with electrification packages, creating turnkey contract opportunities.
- Digital Twin Convergence:Integration of impact sensor telemetry with predictive maintenance platforms is enabling performance-based service contracts that unbundle hardware from lifecycle management.
Industry Challenges
- KBA Certification Timelines:Germany's Federal Motor Transport Authority track certification protocols require 18-24 month validation cycles for new buffer stop designs, delaying market entry for innovative damping configurations.
- Composite Fire Safety Standards:Glass-fiber-reinforced polymer systems must demonstrate EN 45545-2 fire behavior compliance for passenger rail applications, creating testing bottlenecks for material suppliers without rail-specific certification histories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Buffer Stops Market |
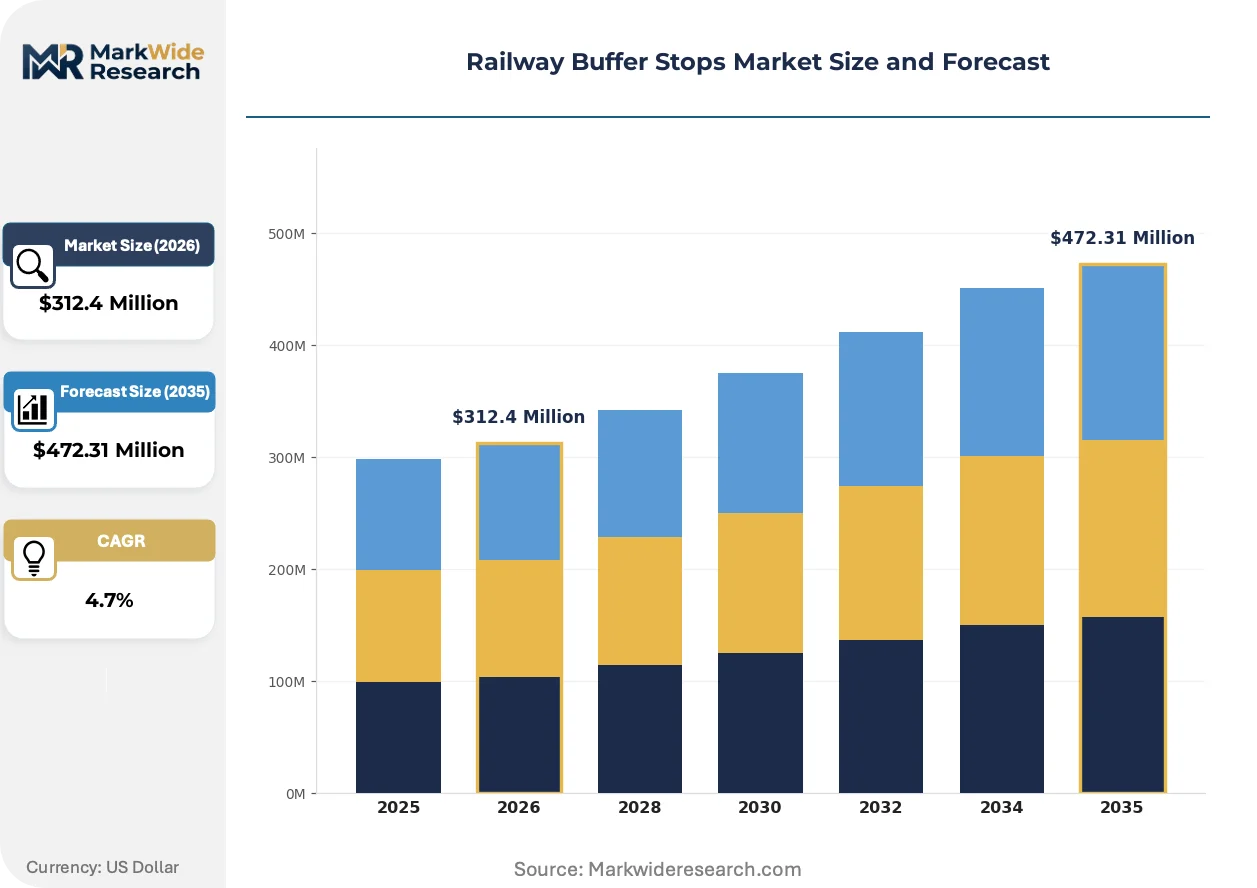
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Fixed, Movable, Hydraulic, Pneumatic Material: Steel, Concrete, Composite, Plastic Application: Passenger Stations, Freight Terminals, Maintenance Depots, Industrial Sites Design: Standard, Custom, Lightweight, Heavy Duty |
| Companies Covered | voestalpine Railway Systems, SPITZKE MAST- UND STAHLBAU, Gantrex, Martinus Rai, Rawie, OLEO International, Salix, Industrispar AB, Vossloh Switch Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Buffer Stops Market Evolving Landscape
Active sensor integration and predictive maintenance architectures are displacing scheduled inspection regimes, while regulatory carbon accounting is redefining material selection criteria across European procurement.
Magnetorheological fluid dampers are integrating real-time viscosity control through embedded electromagnetic coils, enabling adaptive energy absorption across variable impact velocities. Urban metro operators in France and Japan are piloting these systems at high-frequency terminals where standard hydraulic units require weekly reset cycles. This technology is integrating condition-based maintenance protocols that compress downtime windows from hours to minutes.
REACH SVHC disclosure requirements now mandate full material composition transparency for rail infrastructure components above 0.1% concentration thresholds. Manufacturers must maintain extended supply chain documentation for elastomeric pads and hydraulic seals, elevating compliance costs for multi-tier sourcing structures. Composite buffer stop suppliers with captive polymer formulation capabilities are capturing preference in Nordic markets where environmental product declarations carry procurement weight.
Lifecycle cost modeling is displacing first-cost evaluation in European public tenders, with total cost of ownership calculations extending to 30-year maintenance horizons. Infrastructure managers in Germany and Switzerland now weight resettable system premiums against cumulative inspection labor. This shift concentrates demand on suppliers offering integrated sensor packages and remote diagnostic access rather than standalone hardware.
Railway Buffer Stops Market Segmentation
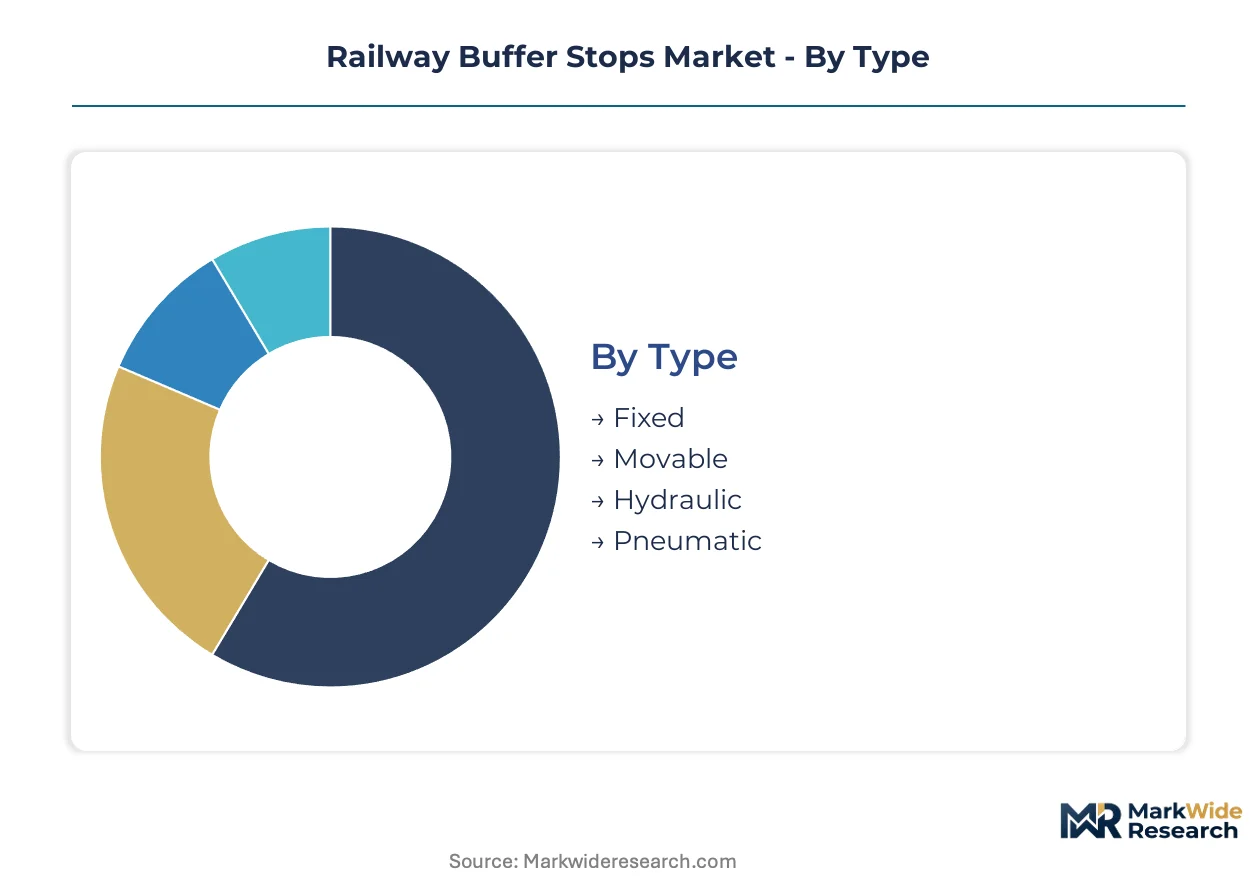
Buffer stop procurement diverges sharply across operating environments, with passenger terminals prioritizing resettable hydraulic systems while freight corridors demand fixed heavy-duty installations. Material selection increasingly reflects lifecycle carbon accounting rather than first-cost optimization.
Type:
Operating frequency and maintenance access windows differentiate buyer preferences more than impact rating alone.
- Fixed:Rigid terminal installations incorporate elastomeric compression pads or friction-based deceleration mechanisms. India's Dedicated Freight Corridor Corporation specifies these for terminal protection across broad-gauge freight infrastructure where reset capability is unnecessary.
- Hydraulic:Piston-based fluid damping systems enable automatic reset after impact events. Tokyo Metro and Osaka Municipal Subway procure these for high-frequency terminals where overnight maintenance windows preclude manual intervention.
- Movable:Rail-mounted units allow repositioning for flexible terminal configurations.
- Pneumatic:Air-spring absorption systems serve specialized industrial applications with moderate velocity constraints.
Fixed buffer stops lead volumes today; hydraulic variants are gaining share fastest.
Material:
Coastal exposure severity and embodied carbon thresholds now override traditional steel dominance in specification decisions.
- Steel:Conventional grades face displacement by hydrogen-reduced low-carbon alternatives. voestalpine Railway Systems supplies certified low-carbon buffer systems meeting EU Green Deal procurement criteria.
- Composite:Glass-fiber-reinforced polymer formulations derived from industrial waste streams deliver corrosion immunity. Nordic infrastructure managers weight environmental product declarations heavily in tender evaluations.
- Concrete:Massive fixed installations leverage local aggregate supply for cost-sensitive heavy freight terminals.
- Plastic:Recycled polymer formulations serve lightweight temporary installations with moderate duty cycles.
Steel retains the largest installed base; composite adoption is climbing the fastest.
Application:
Passenger safety mandates impose stricter energy-absorption certification than freight terminal specifications.
- Passenger Stations:EMA rail safety directives mandate certified energy-absorption for all new terminal installations. French and German urban metro authorities prioritize resettable systems with integrated sensor telemetry.
- Freight Terminals:Impact ratings exceeding 200 tons dominate procurement for heavy-haul corridors. Limited German and Austrian supplier bases control certified fabrication for these specifications.
- Maintenance Depots:Low-velocity protection requirements favor economical fixed installations.
- Industrial Sites:Private rail sidings operate outside public certification frameworks with reduced compliance burden.
Freight terminals generate the highest unit volumes; passenger stations command the steepest technology premiums.
Design:
Standardization pressure from infrastructure managers conflicts with legacy track geometries requiring bespoke solutions.
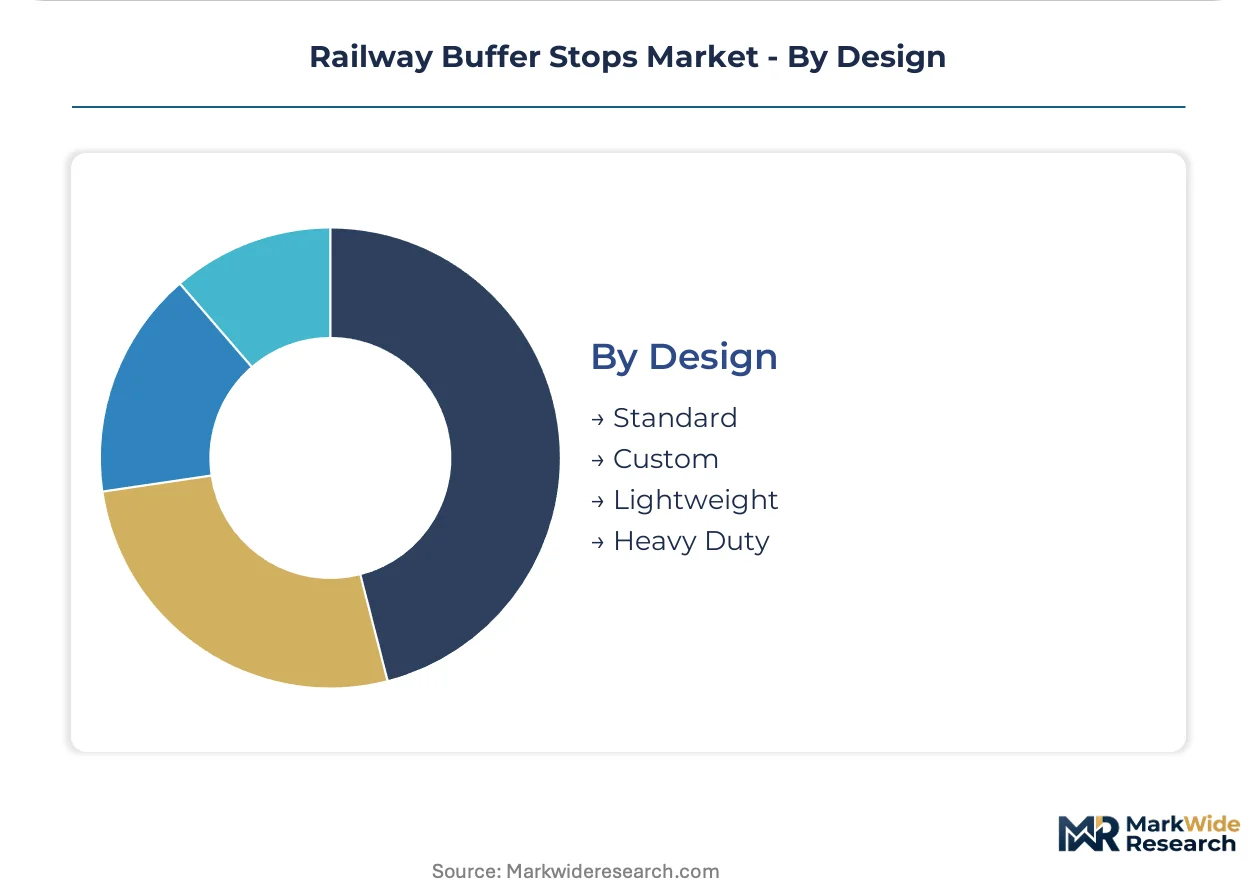
- Heavy Duty:Reinforced structures rated for extreme mass loadings serve dedicated freight corridors. KBA certification protocols in Germany require 18-24 month validation cycles for these designs.
- Standard:Catalog configurations dominate replacement cycles and new-build passenger terminals with conventional track gauges.
- Custom:Non-standard gauges and constrained spatial envelopes necessitate engineering-to-order approaches.
- Lightweight:Reduced track-bed loading suits coastal viaducts and chemically exposed environments.
Standard designs anchor replacement demand; heavy duty specifications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered modern buffer stop engineering during the 19th-century railway expansion, establishing certification protocols that still govern European terminal protection standards today.
Germany
The KBA mandates 18-24 month validation cycles for new buffer stop designs, filtering market access for non-certified suppliers. SPITZKE MAST- UND STAHLBAU anchors domestic demand through specialized fabrication capabilities for heavy-duty terminal installations. The Ruhr industrial corridor concentrates procurement for dedicated freight corridor termini.
France
Urban metro authorities in Paris and Lyon are expanding procurement of energy-absorbing terminal protection systems. The EU Green Deal's embodied carbon requirements push manufacturers toward low-carbon steel and recycled composite materials. The Île-de-France region drives specification innovation for high-frequency passenger terminals.
India
The Dedicated Freight Corridor Corporation is tendering terminal protection systems for over 3,000 route kilometers of new broad-gauge infrastructure. CEA electrification mandates bundle buffer stop procurement with 25kV traction infrastructure packages. The Western Dedicated Freight Corridor from Mumbai to Delhi generates concentrated demand for heavy-duty fixed installations.
Japan
Tokyo Metro and Osaka Municipal Subway procure resettable hydraulic buffer systems for high-frequency terminals. Overnight maintenance windows preclude manual intervention, favoring automatic reset mechanisms. The Kanto and Kansai metropolitan clusters drive technology premiums for adaptive damping systems.
United States
Freight rail operators prioritize heavy-duty terminal protection for Class I railroad termini and intermodal facilities. FRA safety guidelines influence procurement specifications without mandating specific energy-absorption certifications. The Chicago rail hub and Gulf Coast petrochemical corridors sustain demand for corrosion-resistant composite installations.
Railway Buffer Stops Market Competitive Landscape
Capital-heavy integrated steel producers compete with asset-light specialized fabricators across the buffer stop value chain. The market structure concentrates around three tiers: metallurgical conglomerates with captive rail divisions, dedicated infrastructure fabricators with certified welding capabilities, and modular system designers serving international gauge diversity. Strategic moves center on material requalification for EU Green Deal compliance and sensor integration partnerships for predictive maintenance offerings.
Among European integrated metallurgical suppliers, voestalpine Railway Systems exemplifies the low-carbon steel archetype through certified buffer system production. German specialized fabricators SPITZKE MAST- UND STAHLBAU and Gantrex occupy distinct positioning vectors—one anchoring heavy-duty domestic terminal installations, the other competing internationally with modular designs suited to diverse track gauges and loading profiles.
| Leading Market Players |
|---|
| voestalpine Railway Systems |
| SPITZKE MAST- UND STAHLBAU |
| Gantrex |
| Martinus Rai |
| Rawie |
| OLEO International |
| Salix |
| Industrispar AB |
| Vossloh Switch Systems |
| Others |
Value Network & Pricing Analysis
India's CEA electrification mandates bundling buffer stop procurement with 25kV traction infrastructure packages are forcing suppliers to absorb certification costs and localize fabrication, compressing margins on turnkey contracts while elevating price premiums for integrated sensor telemetry.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates resettable hydraulic systems with predictive maintenance integration from fixed elastomeric installations and basic friction-based units. Price differentiation hinges on KBA certification grade and after-sales service bundling, with EU Green Deal compliance adding cost premiums for low-carbon steel grades. Pricing pressure stems from hydrogen-reduced steel sourcing requirements squeezing margins on European contracts. Freight terminal operators exhibit highest price sensitivity, while Japanese urban metro authorities prioritize lifecycle cost over first-cost outlays.
Supply Chain Analysis
Domestic-content mandates in India's Dedicated Freight Corridor Corporation tenders are reshaping sourcing, compelling international suppliers to establish local welding and damping integration partnerships. Manufacturing concentrates in Germany, Austria, and India, with specialized fabrication capabilities for heavy-duty 200+ ton impact ratings anchored in the Ruhr industrial corridor and Upper Austrian steel belt. Raw material dependencies include hydrogen-reduced steel grades, glass-fiber-reinforced polymer formulations, and magnetorheological fluid compounds. Single-source vulnerability persists for certified damping system integration. Distribution runs through rail infrastructure EPC contractors and direct procurement by national railway authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Railway Buffer Stops Market functions as a regulatory compounder, with EU Green Deal embodied carbon thresholds and EMA rail safety directives continuously ratcheting specification requirements and consolidating procurement around certified suppliers.
For Market Incumbents: Deploy sensor integration partnerships to lock in performance-based service contracts that unbundle hardware from lifecycle management. Incumbents must secure captive supply of low-carbon steel grades through backward integration into hydrogen-reduced production or exclusive offtake agreements with voestalpine Railway Systems, while accelerating EN 45545-2 fire safety certification for composite formulations to preempt Nordic market displacement by specialized polymer suppliers. For New Entrants and Emerging Players: Capture maintenance depot and industrial site segments where public certification frameworks do not mandate energy-absorption testing, offering economical fixed installations with reduced compliance burden. New entrants should target India's Western Dedicated Freight Corridor expansion with localized fabrication partnerships, leveraging CEA electrification bundling requirements to embed buffer stops within turnkey traction infrastructure packages without standalone KBA validation cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized fabricators possessing certified welding capabilities for heavy-duty terminal installations and captive polymer formulation for glass-fiber-reinforced systems. Long-term viability rests on positioning for 30-year lifecycle cost evaluation dominance in European public tenders. The signal to watch is accelerating procurement of resettable hydraulic systems with integrated impact sensor telemetry by French and German urban metro authorities.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Carbon Steel Qualification | EU Green Deal procurement criteria filter market access to certified low-carbon buffer system suppliers. |
| Predictive Maintenance Platform Integration | Tokyo Metro and Osaka Municipal Subway compress downtime windows through remote diagnostic access contracts. |
| Localized Fabrication Partnership | India's CEA electrification mandates bundle buffer stop procurement with 25kV traction infrastructure turnkey awards. |
| Composite Material Certification | EN 45545-2 fire behavior compliance creates testing bottlenecks for glass-fiber-reinforced polymer suppliers without rail histories. |
| Magnetorheological Damper Development | Adaptive viscosity control through embedded electromagnetic coils enables real-time energy absorption adjustment across variable impact velocities. |
Research Methodology
Bottom-up terminal protection system modeling reconciled against top-down steel and composite material supply tracking forms the analytical core of this study. Primary interviews with rail infrastructure procurement officers, EPC contract managers, certified welding fabricators, and predictive maintenance platform engineers were validated against secondary sources including KBA track certification protocols, EU F-Gas Regulation implementation guidance, CEA electrification mandate documentation, and Dedicated Freight Corridor Corporation tender disclosures. Trade data from Indian customs authorities and European rail infrastructure investment databases provided shipment-level triangulation.
Historical tender award analysis and installed base depreciation modeling underpin the projection framework across the analysis window. Segmentation dimensions include buffer stop type, material composition, application environment, and design specification tier, with CAGRs derived from regression against rail infrastructure capital expenditure trajectories and electrification corridor completion schedules. Magnetorheological fluid damper pilot deployments and REACH SVHC disclosure requirement phase-ins served as technology adoption and regulatory compliance forecast inputs.
Commodity price volatility in hydrogen-reduced steel, KBA certification timeline extensions, and composite fire safety standard revision delays are the dominant revision risks to modeled outcomes. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Automatic Train Operation System Market
Railway
Automatic Train Supervision Market
Railway
Bullet Train Market
Railway
Global Train Lighting Market
Railway
Rail Brace Market
Railway
Railway Automated Inspection Equipment Market
Railway
Hydrogen Fuel Cell Train Market
Railway
Railway Braking System Market
Railway
Road-Rail Vehicles Market
Railway
Connected Rail Market
Railway
Maglev Train Market
Railway
Train HVAC Market
Railway
Locomotive Parking Brake Market
Railway
Gearbox for Rail Vehicles Market
Railway
Rolling Stocks Market
Railway
Railway Management System Market