
 Automotive Multi-Layer Display Market | 2026-2036
Automotive Multi-Layer Display Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Multi-Layer Display Market Outlook
Multi-source procurement for display modules is broadening as automakers reduce single-supplier risk in cockpit electronics. Continental AG leverages its integrated electronics architecture to sustain long-term supply contracts with European OEMs. Bosch anchors its position through deep manufacturing scale in TFT-LCD and emerging OLED capacity. Japan Display Inc. competes on specialized thin-film transistor know-how for high-brightness automotive applications.
An automotive multi-layer display consists of stacked optical films, polarizers, touch sensors, and illumination units bonded between glass or polymer substrates, typically measuring 10 to 17 inches diagonally for central console applications, designed to present navigation, instrumentation, and entertainment data under variable ambient lighting and vibration loads. Head-up displays command premium positioning due to optical combiner complexity and safety-critical certification requirements, while OLED technology captures fastest-growing share as black-level performance and form-factor flexibility displace conventional LCD in luxury vehicle segments. Instrument clusters retain the largest volume base but face margin compression from standardization across mid-range vehicle platforms.
FDA vehicle electronics guidelines, NHTSA distraction-mitigation protocols, and ECE R79 driver-visibility standards collectively mandate luminance consistency, response-time thresholds, and glare reduction that shape display validation cycles and OEM sourcing criteria. REACH substance restrictions and RoHS hazardous-material limits further constrain adhesive and phosphor chemistries, elevating compliance costs for non-European suppliers. Stakeholders must monitor regulatory divergence between North American and European human-machine interface standards when allocating R&D across regional product lines.
Market Dynamics
The automotive multi-layer display market is being restructured by OLED and MicroLED technology maturation, which is collapsing manufacturing cost curves while simultaneously tightening optical performance specifications demanded by safety regulators across multiple jurisdictions.
Growth Catalysts
- ECE R79 Compliance Mandates:European driver-visibility standards are forcing specification upgrades in instrument clusters and head-up displays, pulling advanced optical film stacks into mid-range vehicle platforms.
- German Automotive Electronics Cluster:Concentrated R&D infrastructure around Stuttgart and Munich accelerates prototype-to-production cycles for bonded glass-polymer substrate assemblies.
- Head-Up Display Safety Certification:Optical combiner complexity creates durable demand for specialized thin-film transistor know-how that commands long-term supply contracts.
Market Restraints
- Rare Earth Phosphor Cost Volatility:Supply concentration in Chinese processing facilities creates input price instability for illumination unit manufacturers.
- REACH Substance Restrictions:European adhesive chemistry constraints elevate compliance costs for non-European suppliers seeking OEM qualification.
- LCD Substitution Pressure:Conventional TFT-LCD capacity faces margin compression as black-level performance requirements displace legacy technology in premium segments.
Strategic Opportunities
- United States Manufacturing Reshoring:NHTSA distraction-mitigation protocols and domestic content incentives create opening for regional display module assembly.
- Japan Display Technology Convergence:Specialized thin-film transistor expertise combined with emerging OLED capacity enables next-generation high-brightness automotive applications.
- RoHS-Compliant Adhesive Innovation:Hazardous-material limits are accelerating development of alternative bonding chemistries with patent-protected formulation advantages.
Industry Challenges
- Optical Engineer Talent Scarcity:Specialized expertise in polarizer-stack design and ambient-light compensation algorithms commands premium compensation and extends hiring timelines.
- Dual Certification Burden:Simultaneous FDA vehicle electronics guideline validation and ECE R79 compliance creates parallel testing tracks that compress product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Multi-Layer Display Market |
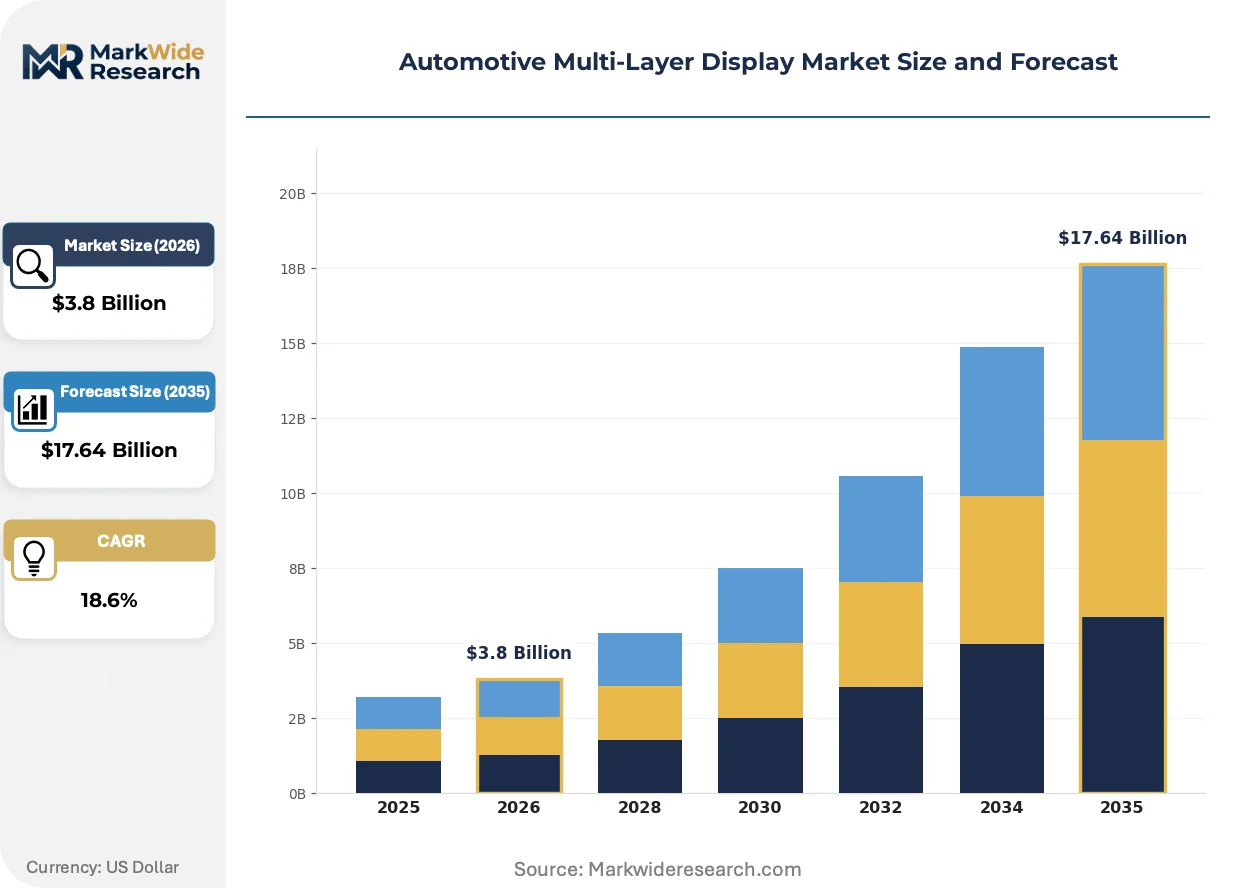
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Head-Up Displays, Central Displays, Instrument Clusters, Rear Seat Displays Technology: LCD, OLED, MicroLED, TFT End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers Application: Navigation, Entertainment, Vehicle Diagnostics, Driver Assistance |
| Companies Covered | Continental AG, Bosch, LG Display, Denso Corporation, Panasonic Automotive Systems, Hyundai Mobis, Visteon Corporation, Japan Display Inc., Magna International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Multi-Layer Display Market Strategic Shifts
Display architecture is fragmenting into specialized optical subsystems as automakers decouple instrument cluster, head-up display, and central console development cycles to accelerate platform refresh rates.
MicroLED backlighting is modularizing the traditional illumination unit supply chain. Tier 1 cockpit electronics suppliers are adopting discrete LED-array designs that permit field-replaceable optical engines without full display replacement. This structural shift is compressing after-sales service margins while enabling over-the-air calibration updates that reduce warranty exposure.
REACH substance restrictions and RoHS hazardous-material limits are constraining adhesive and phosphor chemistries across European supply chains. Manufacturers are responding by reformulating bonding agents and relocating final assembly to jurisdictions with aligned environmental standards. High-brightness automotive applications face the steepest reformulation costs due to thermal-load requirements.
Fleet procurement managers are consolidating specification authority previously dispersed across regional engineering centers. Centralized cockpit electronics sourcing is displacing legacy tiered supplier relationships in Germany, Japan, and the United States, compressing qualification timelines while elevating volume-commitment thresholds for display module vendors.
Automotive Multi-Layer Display Market Segmentation
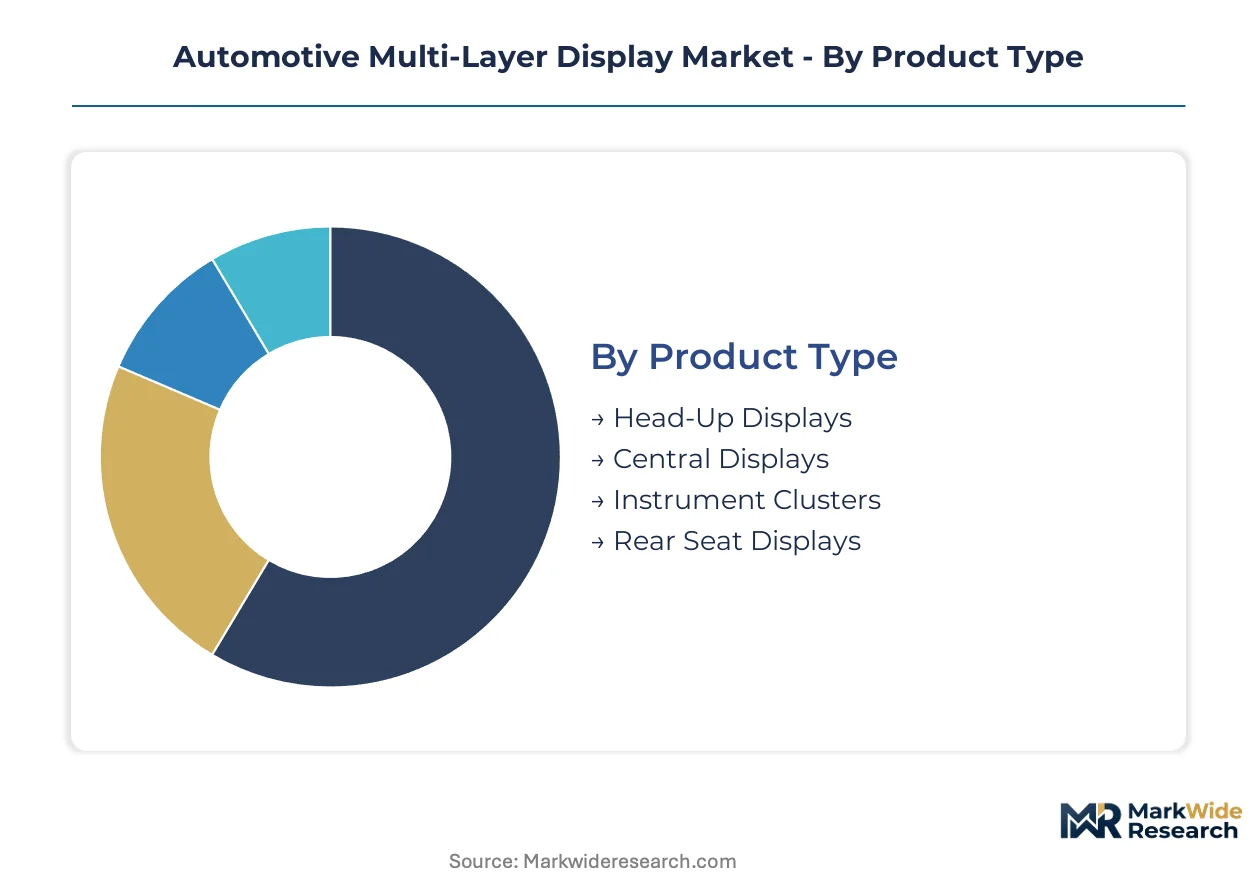
Multi-layer display architectures fragment across cockpit electronics based on optical complexity, safety certification burden, and thermal management requirements. Each segment carries distinct validation cycles, margin structures, and supplier qualification barriers that reshape procurement strategies for premium and volume vehicle platforms.
Product Type:
Optical complexity and safety-critical certification requirements stratify product categories by engineering intensity and unit economics.
- Head-Up Displays:Optical combiner assemblies project navigation and instrumentation data onto windshields or dedicated screens, requiring precision-bonded polarizer stacks and ambient-light compensation algorithms. Demand concentrates in Germany and Japan where ECE R79 driver-visibility standards and KBA certification protocols mandate luminance consistency across variable lighting conditions. NHTSA distraction-mitigation protocols in the United States further tighten response-time thresholds for augmented-reality overlays.
- Central Displays:Stacked optical films and touch sensors bonded between glass or polymer substrates measure 10 to 17 inches diagonally, presenting navigation and entertainment data under vibration loads. OEMs in Stuttgart and Munich accelerate prototype-to-production cycles for bonded assemblies, pulling advanced film stacks into mid-range vehicle platforms as specification authority consolidates.
- Instrument Clusters:Retain the largest volume base but face margin compression from standardization across mid-range platforms.
- Rear Seat Displays:Lower certification burden enables faster refresh cycles and modular supplier relationships.
Instrument clusters lead on scale; head-up displays lead on momentum.
Technology:
Manufacturing cost curves and black-level performance specifications are restructuring technology adoption across luxury and volume segments.
- OLED:Self-emissive pixel architecture eliminates backlight units, enabling form-factor flexibility and superior black-level performance that displaces conventional LCD in luxury vehicle segments. Japan Display Inc. and Korean panel makers are expanding automotive-qualified capacity as thermal management solutions mature for high-brightness applications.
- MicroLED:Discrete LED-array designs modularize illumination unit supply chains, permitting field-replaceable optical engines without full display replacement. Bosch and Continental AG are qualifying microLED backlighting for next-generation head-up displays where optical precision commands premium positioning.
- LCD:Conventional TFT-LCD capacity faces margin compression as performance requirements escalate.
- TFT:Thin-film transistor know-how remains foundational for high-brightness automotive qualification.
LCD retains volume dominance; OLED climbs the fastest.
End User:
Procurement authority consolidation and long-term supply contract structures differentiate end-user relationships.
- OEMs:Premium passenger vehicle manufacturers in Germany, Japan, and the United States are expanding multi-layer display adoption for instrument clusters and head-up displays, leveraging concentrated R&D infrastructure around Stuttgart, Munich, and Nagoya to compress qualification timelines.
- Tier-1 Suppliers:Continental AG and Bosch anchor positions through deep manufacturing scale and emerging OLED capacity, sustaining long-term contracts via integrated electronics architecture.
- Vehicle Assemblers:Face compressed launch windows from dual certification burdens across FDA vehicle electronics guidelines and ECE R79 standards.
- Aftermarket Providers:Modular LED-array designs enable service-margin compression through field-replaceable optical engines.
OEMs command specification authority; tier-1 suppliers capture contract durability.
Application:
Functional safety requirements and user-interaction intensity segment applications by validation rigor and hardware redundancy.
- Navigation:Real-time route guidance demands luminance consistency under direct sunlight and rapid response-time thresholds for turn-by-turn overlays, driving adoption of high-brightness OLED and advanced polarizer-stack designs in German and Japanese premium platforms.
- Driver Assistance:Safety-critical collision warnings and lane-departure alerts mandate FDA vehicle electronics guideline compliance and NHTSA distraction-mitigation protocol adherence, elevating qualification costs and supplier concentration.
- Entertainment:Rear-seat and central console streaming applications prioritize form-factor flexibility over optical precision.
- Vehicle Diagnostics:Instrument cluster integration standardizes across mid-range platforms with reduced customization.
Navigation leads on unit deployment; driver assistance leads on specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Stuttgart-Munich corridor anchors automotive multi-layer display engineering, with concentrated OEM procurement authority and tier-1 supplier manufacturing scaling across three continents.
United States
NHTSA distraction-mitigation protocols and domestic content incentives are reshaping cockpit electronics sourcing. The Inflation Reduction Act's manufacturing credits accelerate display module assembly reshoring. Michigan and Ohio electronics clusters host prototype-to-production cycles for bonded glass-polymer substrate assemblies.
Germany
ECE R79 driver-visibility standards and KBA certification protocols mandate luminance consistency for head-up displays. REACH substance restrictions constrain adhesive chemistries, elevating compliance costs for imported components. The Baden-Württemberg electronics cluster around Stuttgart compresses qualification timelines for instrument cluster suppliers.
Japan
METI industrial policy and JIS standards govern high-brightness automotive display qualification. The Nagoya-Tokyo corridor concentrates specialized thin-film transistor know-how for OLED thermal management. Japan Display Inc. and Korean panel makers are expanding automotive-qualified capacity.
China
MIIT automotive electronics standards and dual carbon goals accelerate domestic OLED capacity expansion. GB standards for vehicle human-machine interfaces tighten response-time thresholds. The Yangtze River Delta cluster hosts emerging microLED backlighting manufacturing for tier-1 cockpit electronics suppliers.
South Korea
MFDS-equivalent automotive safety protocols and national semiconductor subsidies support display panel manufacturing scale. Seoul-Incheon electronics infrastructure enables rapid prototyping for bonded optical film stacks. Korean panel makers are capturing share in luxury vehicle OLED segments.
Automotive Multi-Layer Display Market Competitive Environment
Global majors compete with regional champions across technology licensing and manufacturing scale, producing a tiered structure where integrated electronics architecture anchors long-term supply contracts. The vendor base stratifies between full-stack cockpit integrators, specialized display panel fabricators, and optical component specialists. Three archetypes dominate: European tier-1 systems integrators leveraging electronics architecture control; East Asian panel makers exploiting manufacturing scale; and Japanese thin-film transistor specialists commanding premium positioning. Capacity expansion and strategic technology licensing represent the dominant competitive moves.
Within the integrated systems tier, Continental AG and Bosch exemplify European tier-1 positioning through deep manufacturing scale and emerging OLED capacity. Japan Display Inc. occupies a specialist position anchored in thin-film transistor know-how for high-brightness automotive qualification. LG Display represents East Asian panel-scale manufacturing with expanding automotive-qualified capacity.
| Leading Market Players |
|---|
| Continental AG |
| Bosch |
| LG Display |
| Denso Corporation |
| Panasonic Automotive Systems |
| Hyundai Mobis |
| Visteon Corporation |
| Japan Display Inc. |
| Magna International Inc. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between ECE R79-compliant head-up displays and standard instrument clusters splits pricing power across safety-critical and commodity tiers, with German OEM procurement consolidating around qualified suppliers while mid-range platforms absorb cost compression through bonded glass-polymer substrate standardization.
Pricing Analysis
Rare earth phosphor cost pass-through from Chinese processing facilities compresses margins for illumination unit manufacturers serving mid-range vehicle platforms. Three-tier pricing structure across premium HUD, standard cluster, and economy rear-seat configurations tracks optical complexity and thermal management requirements. Pricing pressure stems from OLED substitution in luxury segments as black-level performance thresholds escalate. Fleet procurement managers exhibit highest price sensitivity, while safety-critical HUD buyers accept premium positioning for KBA-certified optical combiner assemblies.
Supply Chain Analysis
Polarizer-stack supply rests on Japanese specialty chemical producers and Korean optical film fabricators, with glass substrate sourcing concentrating in German and Chinese electronics clusters. Critical inputs span indium tin oxide for transparent conductors, rare earth phosphors for backlight units, and REACH-compliant adhesive formulations. Single-source vulnerability in Chinese rare earth processing creates input price instability. Distribution runs through tier-1 cockpit electronics integrators holding long-term OEM contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive multi-layer display market functions as a stable compounder, with ECE R79 and NHTSA regulatory upgrades mandating recurrent specification refreshes that sustain replacement demand across vehicle platform cycles.
For Market Incumbents: Anticipate margin compression in conventional TFT-LCD capacity as OLED thermal management solutions mature for high-brightness automotive qualification. Defensive consolidation around microLED backlighting intellectual property and backward integration into optical film stack manufacturing anchors long-term contract durability with Stuttgart and Munich OEM procurement centers. For New Entrants and Emerging Players: Begin with modular LED-array designs for aftermarket field-replaceable optical engines, where service-margin compression creates white-space opportunity outside tier-1 incumbent relationships. Target United States manufacturing reshoring incentives under domestic content provisions for display module assembly qualification. For Investors and Strategic Acquirers: Consolidation pressure builds where thin-film transistor expertise overlaps with emerging OLED capacity, as Japan Display Inc. and Korean panel makers expand automotive-qualified production. Acquisition candidates with specialized polarizer-stack know-how and ECE R79 certification history offer defensive positioning. Watch OLED thermal management breakthroughs as inflection signal for technology substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| MicroLED Backlighting Qualification | Bosch and Continental AG secure premium HUD positioning through optical precision certification. |
| REACH-Compliant Adhesive Reformulation | European suppliers capture compliance margin from non-European competitors facing chemistry constraints. |
| United States Manufacturing Reshoring | Michigan and Ohio clusters exploit IRA manufacturing credits for bonded substrate assembly. |
| OLED Thermal Management Investment | Japan Display Inc. and Korean panel makers target high-brightness automotive expansion. |
| Integrated Electronics Architecture Control | Continental AG sustains long-term supply contracts through cockpit system integration depth. |
Study Parameters
Multiple input streams — primary interviews with tier-1 supplier procurement officers, OEM platform engineers, and aftermarket distributors; secondary validation against vehicle production databases, IHS Markit registration data, and SEC filings from display panel manufacturers; plus customs records for optical film trade flows — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across the analysis window applied vehicle class, propulsion architecture, content per vehicle, and regional production cluster segmentation dimensions. CAGRs derived from modeled unit deployment trajectories and average selling price evolution incorporated OLED penetration curves and microLED backlighting adoption rates as industry-specific inputs.
Several conditions sit outside the modeled scope, including geopolitical disruption to rare earth supply chains and unilateral regulatory divergence between NHTSA and ECE R79 standards. Forecasts reflect documented assumptions about thermal management solution maturation and OEM platform consolidation timelines. A small set of named triggers — OLED burn-in failure rates in automotive duty cycles and REACH substance restriction expansion — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Sound Proofing Material Market
Automotive Interior & Exterior
Automotive Insulation Market
Automotive Interior & Exterior
Global Automotive Roof Systems Market
Automotive Interior & Exterior
Impact-Modified PCR Plastics for Automotive Interiors Market
Automotive Interior & Exterior
Auto Ventilated Seats Market
Automotive Interior & Exterior
Automotive Roof Liners Market
Automotive Interior & Exterior
Automotive Grab Handle Market
Automotive Interior & Exterior
Automotive Steering Wheel Covers Market
Automotive Interior & Exterior
Automotive Smart Window Market
Automotive Interior & Exterior
Global Automotive Rear Window Blinds Market
Automotive Interior & Exterior
Automotive Soft Trim Interior Materials Market
Automotive Interior & Exterior
North America Automotive Upholstery Market
Automotive Interior & Exterior
Float Glass for Automotive Market
Automotive Interior & Exterior
Automotive Automatic Liftgate Market
Automotive Interior & Exterior
North America Automotive Interior Materials Market
Automotive Interior & Exterior
North America Automotive Flooring Market