
 Global Train Lighting Market | 2026-2036
Global Train Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Train Lighting Market Outlook
Aftermarket service revenue is rewriting margin distribution across the value chain. Koito Manufacturing leverages its Tier-1 supplier relationships with Japanese rail OEMs to sustain captive aftermarket streams. Osram Licht anchors LED module replacement cycles through direct service contracts with European operators. Dräxlmaier Group competes on integrated wiring-and-lighting architectures that reduce installation labor for retrofit projects.
Train lighting encompasses interior, exterior, emergency, and indicator illumination systems engineered to EN 13272 photometric standards, with LED arrays now dominant due to 50,000-hour rated lifespans and 30-40% lower energy draw versus fluorescent predecessors. Interior lights command the largest installed base, while exterior LED retrofits represent the fastest-expanding segment as operators pursue crashworthiness-compliant sealed housings. Modular installation types are gaining share against fixed configurations, enabling rapid field replacement without full fixture removal.
Japan's MLIT, the EU's ERA through TSIs, and the US FRA each mandate emergency lighting autonomy and fire-smoke toxicity thresholds that dictate component sourcing. China's NRA enforces GB/T railcar illumination standards that favor domestic LED module certification, shaping market access for foreign suppliers. Stakeholders must track evolving photobiological safety standards and battery-backed emergency duration requirements as decarbonization targets intensify specification stringency.
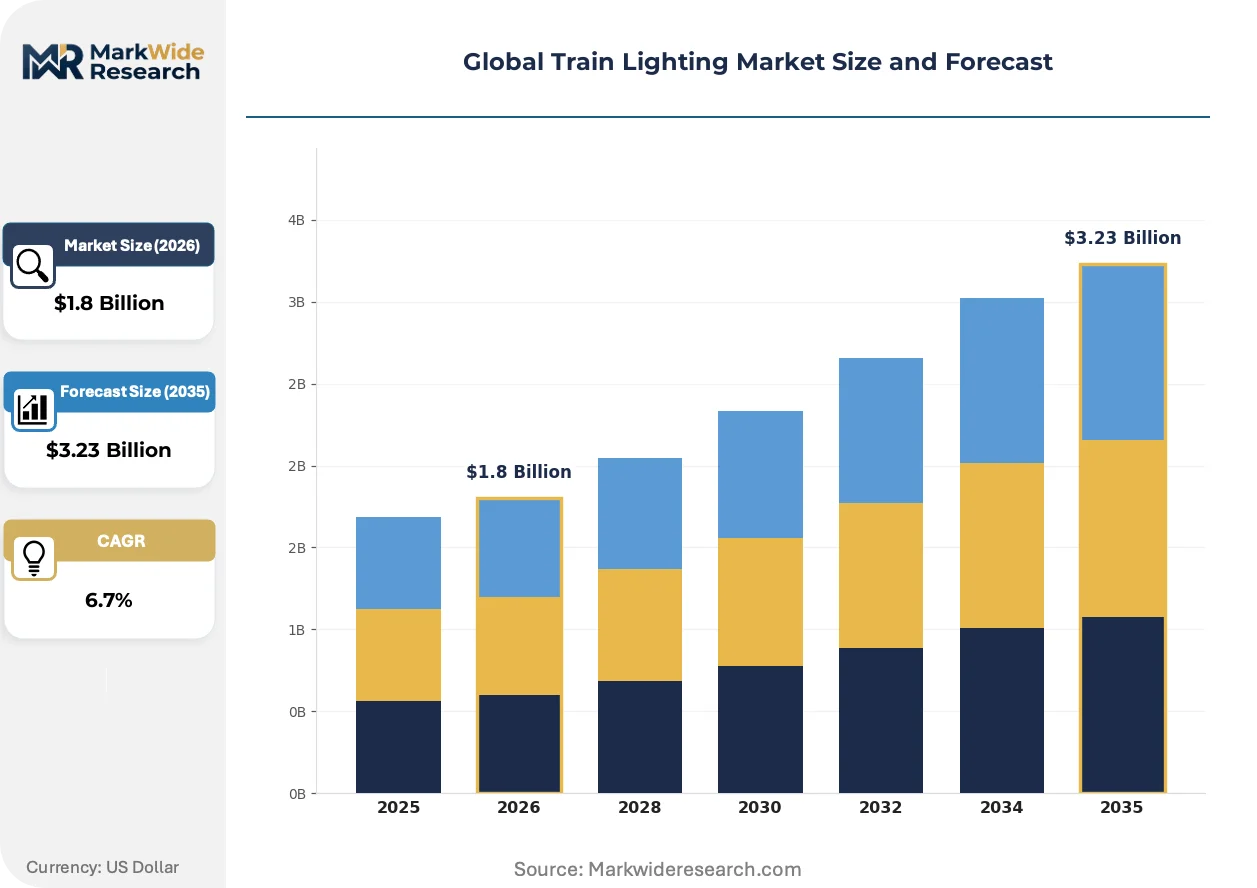
Market Dynamics
Retrofit urgency is compressing replacement cycles as EN 13272 photometric standards and China's GB/T railcar illumination rules force operators to abandon fluorescent systems before natural end-of-life. Modular LED platforms now dominate procurement specifications, reshaping supplier relationships and installation economics.
Growth Catalysts
- LED lifespan economics:50,000-hour rated LED arrays slash maintenance intervals for high-speed corridors. Operators in Germany and France now mandate LED-only specifications for new rolling stock.
- Emergency autonomy mandates:Japan's MLIT requires 90-minute battery-backed illumination autonomy. This drives replacement of legacy systems unable to meet duration thresholds without full fixture overhaul.
- Urban metro expansion:China's state-backed procurement for high-speed rail corridors favors modular installation platforms. Volume concentration in this segment pulls component standardization across Asian supply chains.
Market Restraints
- Domestic certification barriers:China's NRA enforces GB/T railcar illumination standards that favor domestic LED module certification. Foreign suppliers face extended approval timelines and testing costs.
- Technical integration complexity:Sealed crashworthiness-compliant housings for exterior LED retrofits require specialized thermal management. Few suppliers possess simultaneous competence in optical engineering and structural rail safety.
- Input cost volatility:Rare earth elements in LED phosphors and driver electronics concentrate processing in limited geographies. Price swings in these inputs compress margin predictability for fixture assemblers.
Strategic Opportunities
- Aftermarket service unbundling:Direct service contracts with European operators for LED module replacement cycles bypass traditional OEM channels. Osram Licht anchors this model through captive technician networks.
- Integrated wiring-lighting architectures:Combined harness-and-luminaire systems reduce installation labor hours for retrofit projects. Dräxlmaier Group competes on this convergence, cutting field deployment time.
- Photobiological safety premium:Evolving IEC 62471 standards for blue light hazard assessment create tiered product positioning. Certified low-risk modules command specification preference in Scandinavian passenger segments.
Industry Challenges
- Fire-smoke toxicity compliance:EN 45545-2 materials testing for rail applications requires reformulation of LED housing polymers. Suppliers face 18-24 month recertification cycles for existing product lines.
- Legacy system interoperability:Retrofit projects must interface with 30-year-old train control and power distribution architectures. Field integration complexity drives cost overruns and warranty disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Train Lighting Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interior Lights, Exterior Lights, Emergency Lights, Indicator Lights Technology: LED, Halogen, Fluorescent, Xenon Installation Type: Fixed, Retractable, Modular, Integrated End User: Passenger Trains, Freight Trains, High-Speed Trains, Trams |
| Companies Covered | Koito Manufacturing Co., Ltd., Osram Licht AG, Toshiba Corporation, Teknoware, Dräxlmaier Group, General Electric, Grupo Antolin, Autolite Ltd., Hitachi, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Train Lighting Market Strategic Shifts
Active illumination control is displacing static lighting schemes across passenger rail segments. Smart systems now adjust output based on occupancy, time-of-day, and ambient conditions, compressing energy draw while extending component life.
Human-centric lighting is hybridizing circadian-tuned spectral output with standard cabin illumination functions. Scandinavian operators led adoption, programming 2700K-6500K tunable white systems for long-haul sleeper services. This convergence of wellness science and LED driver electronics is forcing fixture suppliers to recruit optical biologists and abandon pure engineering hiring profiles.
Europe's Ecodesign Directive and F-Gas Regulation are accelerating fluorescent phase-out timelines for rolling stock. The industrial consequence is a surge in emergency-only LED retrofit kits that satisfy minimum compliance without full interior refurbishment. Operators in Italy and Spain favor this partial-upgrade route, stretching full LED conversion budgets across multiple capital cycles.
Specification authority is migrating from rolling stock OEMs to direct operator procurement teams. Deutsche Bahn and SNCF now publish standalone lighting technical requirements that Tier-1 suppliers must meet independently of train builder contracts. This disintermediation concentrates purchasing power with asset owners and fragments legacy supplier relationships in German and French markets.
Global Train Lighting Market Segmentation
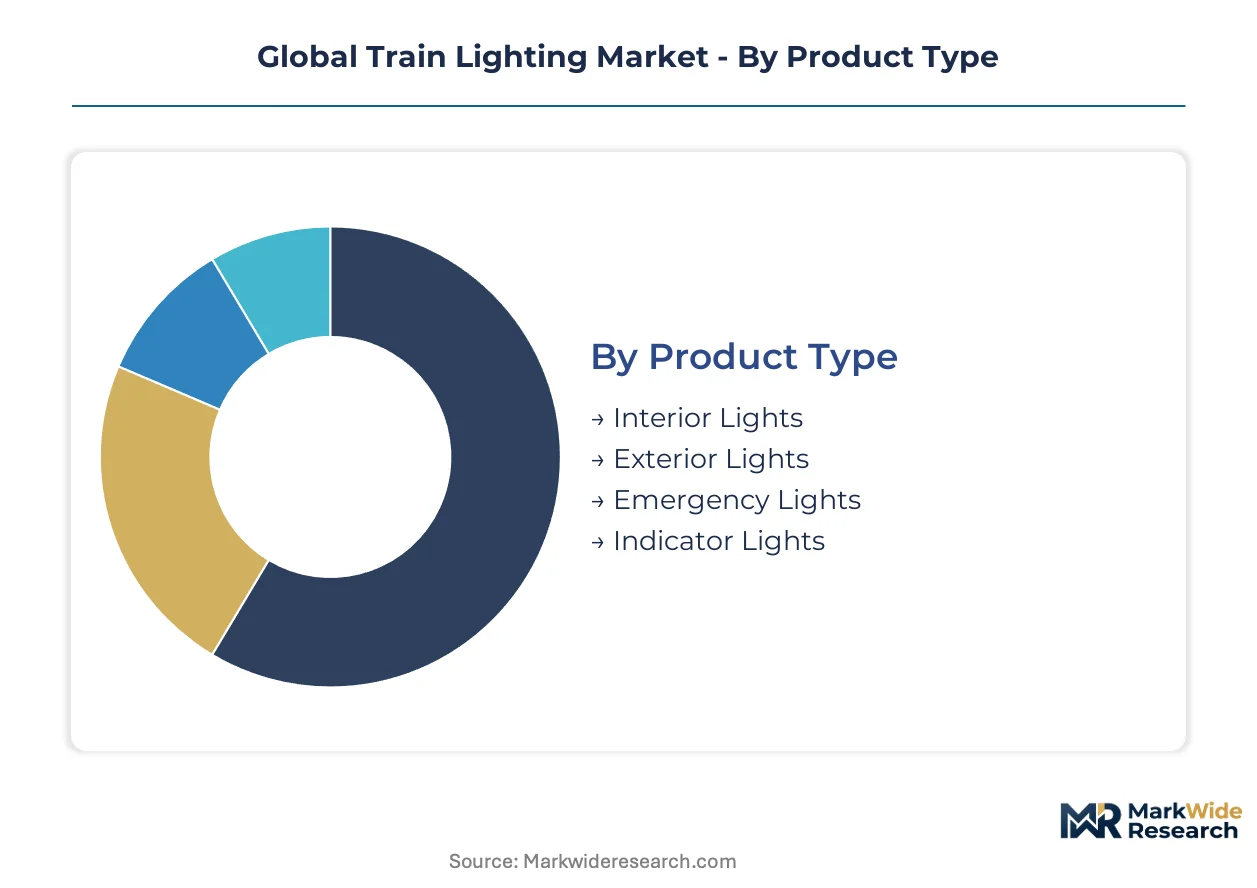
Segmentation in train lighting reveals how procurement specifications diverge across operating environments and regulatory jurisdictions. Each dimension—product function, technology maturity, installation architecture, and end-use application—carries distinct margin profiles and supplier qualification barriers that reshape competitive positioning.
Product Type:
Application context determines photometric requirements, housing durability, and replacement cycle economics across the four functional categories.
- Interior Lights:Cabin and saloon illumination systems engineered to EN 13272 photometric uniformity standards. Deutsche Bahn and SNCF procurement teams now publish standalone technical specifications independent of train builder contracts, concentrating purchasing power with asset owners in Germany and France.
- Exterior Lights:Headlights, marker lamps, and taillights housed in sealed crashworthiness-compliant enclosures. Scandinavian operators prioritize IEC 62471 photobiological safety certification for blue light hazard assessment, creating tiered specification preference for low-risk modules.
- Emergency Lights:Battery-backed autonomous systems mandated by Japan's MLIT for 90-minute duration minimums.
- Indicator Lights:Door status, destination display, and fault signal illumination with high-visibility requirements.
Interior lights command the established base. The steepest expansion runs through exterior LED retrofits as crashworthiness standards tighten.
Technology:
Cost tier and performance characteristics stratify the technology landscape from legacy incumbent to dominant replacement platform.
- LED:Solid-state arrays delivering 50,000-hour rated lifespans and 30-40% energy reduction versus fluorescent predecessors. China's NRA enforces GB/T railcar illumination standards favoring domestic LED module certification, shaping market access for foreign suppliers.
- Fluorescent:Legacy tube-based systems facing accelerated phase-out under Europe's Ecodesign Directive and F-Gas Regulation.
- Halogen:Incandescent-halogen hybrid technology retained in niche exterior applications requiring instant-on performance.
- Xenon:High-intensity discharge lamps for specialized high-beam applications in high-speed corridors.
LED arrays anchor replacement demand. The fastest technology transition occurs in fluorescent-to-LED retrofits driven by regulatory compliance deadlines.
Installation Type:
Architecture choices reshape field deployment economics and supplier relationships across new build and aftermarket channels.
- Modular:Field-replaceable LED engines and driver modules enabling rapid swap without full fixture removal. China's state-backed high-speed rail procurement explicitly favors modular platforms, pulling component standardization across Asian supply chains.
- Fixed:Permanent integrated fixtures with lower upfront cost but higher lifecycle replacement burden.
- Retractable:Mechanically stowed luminaires for multi-purpose cabin configurations in sleeper services.
- Integrated:Combined wiring harness-and-luminaire systems reducing installation labor hours for retrofit projects.
Fixed installations retain legacy fleet penetration. Modular platforms are gaining share fastest as operators prioritize maintainability over first-cost minimization.
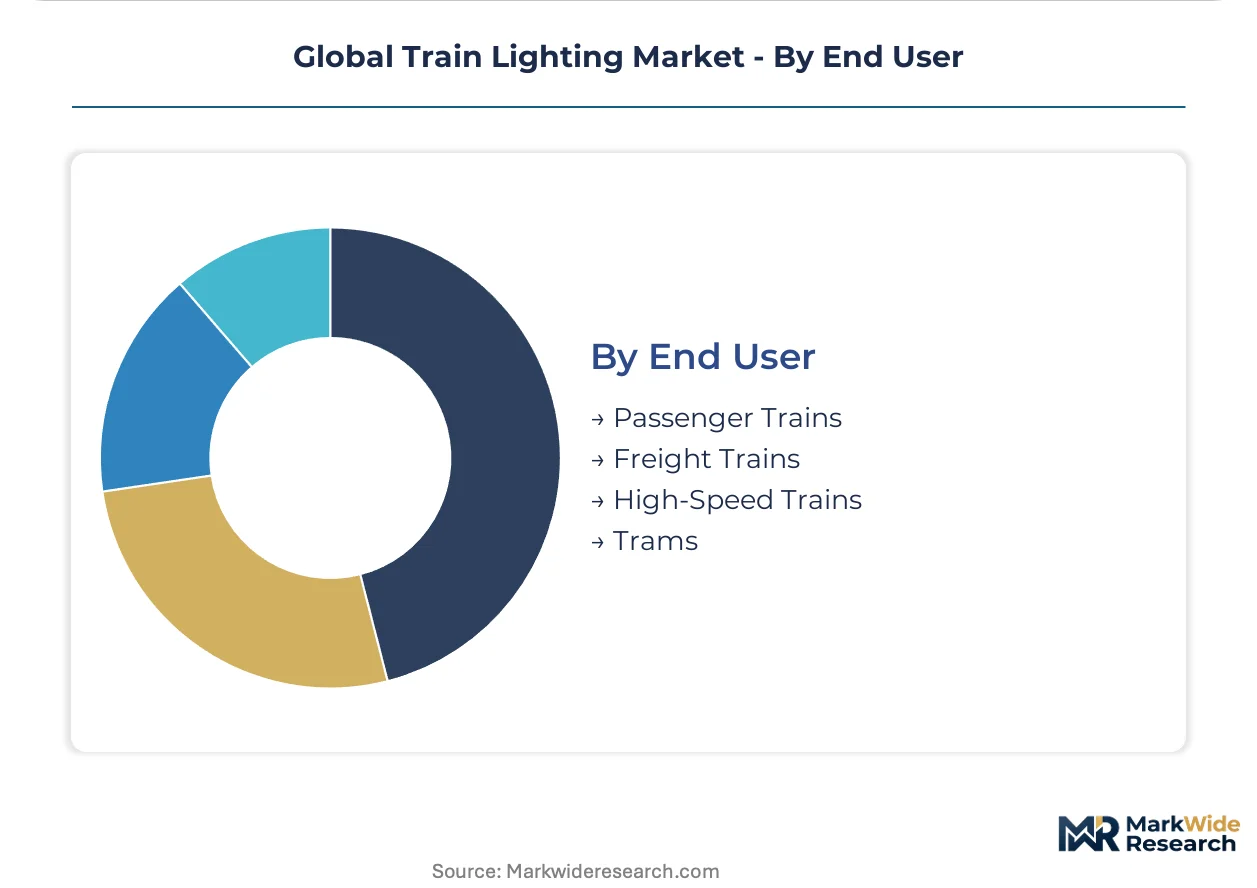
End User:
Customer type dictates duty cycle intensity, specification stringency, and procurement channel structure.
- Passenger Trains:Urban metro and regional services with high-frequency stop-start cycles demanding rapid-failover redundancy. Human-centric lighting with circadian-tuned 2700K-6500K spectral output is hybridizing with standard cabin functions in Scandinavian long-haul sleeper segments.
- High-Speed Trains:Aerodynamic exterior housing requirements and vibration-resistant interior systems for 300+ km/h operation.
- Freight Trains:Minimal interior illumination with focus on exterior visibility and rear-end marker compliance.
- Trams:Street-level operation with pedestrian visibility mandates and frequent door-cycle indicator demands.
Passenger trains anchor volume concentration. High-speed rail applications are expanding most quickly as corridor investments accelerate across China, Spain, and Turkey.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese operators demonstrate the lowest price elasticity, accepting premium modular systems through state-backed procurement. European markets split between Germany and France, where asset owners concentrate purchasing power, and Southern Europe, where emergency-only retrofits stretch budgets across capital cycles.
China
High-speed rail corridor investments drive concentrated LED module demand through state procurement channels. The National Railway Administration enforces GB/T railcar illumination standards that favor domestic certification pathways for LED suppliers. Qingdao and Changchun host rolling stock manufacturing clusters where modular installation platforms dominate technical specifications.
Germany
Deutsche Bahn's direct procurement of standalone lighting specifications disintermediates traditional OEM supplier relationships. The EU Ecodesign Directive and F-Gas Regulation accelerate fluorescent phase-out timelines for existing fleets. Siemens Mobility and Alstom manufacturing sites in Berlin and Mannheim anchor component demand for retrofit projects.
Japan
Urban metro operators expand rolling stock fleets with LED-based interior systems requiring 90-minute emergency autonomy. The Ministry of Land, Infrastructure, Transport and Tourism mandates battery-backed illumination duration thresholds that obsolete legacy systems. Kawasaki and Nagoya house Tier-1 supplier relationships sustaining captive aftermarket revenue streams.
France
SNCF publishes independent technical requirements that Tier-1 suppliers must meet outside train builder contracts. EN 13272 photometric standards and EN 45545-2 fire-smoke toxicity testing reshape materials selection for LED housings. Alstom's manufacturing presence in Saint-Ouen and Valenciennes concentrates specification authority with asset owners.
United States
Freight operators prioritize exterior visibility compliance with minimal interior illumination investment. The Federal Railroad Administration mandates emergency lighting autonomy and crashworthiness standards for sealed housings. Chicago and Los Angeles anchor commuter rail retrofit activity as operators pursue LED exterior upgrades.
Global Train Lighting Market Competitive Environment
Capability concentration sits with optical engineering specialists; scale advantage sits with diversified industrial conglomerates. The vendor base organizes around three archetypes: Japanese and German Tier-1 automotive suppliers with rail-adjacent competencies, dedicated lighting technology firms with LED module expertise, and diversified electrical engineering conglomerates with broad transportation portfolios. M&A activity targets wiring-harness integration capabilities, while strategic partnerships lock in direct service contract channels with European operators.
Among Japanese manufacturers, Koito Manufacturing Co., Ltd. and Hitachi, Ltd. occupy positions reflecting Tier-1 supplier heritage and diversified industrial engineering scale respectively. German lighting specialists Osram Licht AG and Dräxlmaier Group exemplify divergent strategic anchors: one represents direct-to-operator service model penetration, the other integrated wiring-and-lighting system convergence. These three names illustrate how geographic origin and corporate structure map to competitive positioning without requiring specific product or financial disclosure.
| Leading Market Players |
|---|
| Koito Manufacturing Co., Ltd. |
| Osram Licht AG |
| Toshiba Corporation |
| Teknoware |
| Dräxlmaier Group |
| General Electric |
| Grupo Antolin |
| Autolite Ltd. |
| Hitachi, Ltd. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in European LED module foundries is pushing contract manufacturers toward longer lead-time commitments and selective customer prioritization, compressing pricing flexibility for retrofit project bidders while amplifying aftermarket service premiums.
Pricing Analysis
Aftermarket service revenue streams anchor lifetime value capture across the installed base. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and emergency autonomy compliance. Cost compression in modular LED engines is intensifying because rare earth phosphor volatility feeds through driver electronics. Freight operators exhibit the highest price sensitivity, while urban metro authorities in Asia accept premium positioning for human-centric lighting systems.
Supply Chain Analysis
Contract manufacturing concentration sits with Taiwanese and South Korean electronics manufacturing services holding capacity for LED driver modules and thermal management substrates. Production gravity centers on China for LED die fabrication, Germany for optical lens precision molding, and Japan for battery-backed emergency system assembly. The supply chain draws from rare earth elements concentrated in Chinese processing facilities, copper interconnects, and flame-retardant polymer compounds. Single-source vulnerability in phosphor rare earths poses structural risk. Distribution runs through Tier-1 rail OEM captive channels and direct operator procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment moat: EN 13272, GB/T, and MLIT certification timelines create switching costs that lock in approved suppliers across multi-year replacement cycles.
For Market Incumbents: Build certification moats by accelerating EN 45545-2 materials recertification ahead of competitor product cycles. Deepen backward integration into LED die sourcing to offset phosphor cost volatility. Koito Manufacturing's captive aftermarket technician networks demonstrate how channel control neutralizes price pressure from modular platform competitors. For New Entrants and Emerging Players: Establish a beachhead in emergency-only LED retrofit kits for Southern European operators stretching full conversion budgets across capital cycles. Target direct service contract channels with mid-size French and German regional operators outside SNCF and Deutsche Bahn central procurement. Lead with rapid-install modular platforms that cut field deployment labor versus integrated fixture competitors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across wiring-harness integration capabilities as Dräxlmaier-style convergence reduces component count per trainset. Long-term viability favors suppliers with simultaneous optical engineering and rail safety structural competence. Acquisition target archetype: mid-cap LED module specialists with GB/T certification progress and European operator service relationships. Monitor NRA certification timeline announcements as inflection signal for foreign supplier market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Service Contract Expansion | Osram Licht's captive technician networks bypass OEM channels and capture replacement cycle revenue. |
| Integrated Wiring-Lighting Convergence | Dräxlmaier Group's harness-and-luminaire systems cut field installation hours for retrofit projects. |
| GB/T Certification Investment | Foreign suppliers face extended NRA approval timelines without domestic testing partnerships. |
| Human-Centric Lighting Development | Scandinavian operators program 2700K-6500K tunable white systems for sleeper service differentiation. |
| Modular Platform Standardization | China's state-backed high-speed procurement pulls component interoperability across Asian supply chains. |
Study Parameters
A standing panel of rolling stock procurement directors, Tier-1 supplier account managers, rail operator maintenance chiefs, and regulatory compliance officers provided ongoing calibration against secondary validation. Primary fieldwork combined structured interviews with EN 13272 technical committee participants and aftermarket service contract negotiators. Secondary sources included ERA TSI documentation, NRA GB/T standard filings, EU Ecodesign Directive implementation reports, and customs records for LED module trade flows. Bottom-up trainset installation data triangulated against top-down operator capital expenditure disclosures.
Scenario bracketing around regulatory phase-out deadlines and rare earth price bands shaped volume and value outputs across the projection horizon. Segmentation dimensions modeled include product function, installation architecture, technology maturity, and end-use application intensity. CAGRs derived from fitted growth curves applied to operator fleet replacement schedules and corridor investment pipelines. Industry-specific inputs encompassed EN 45545-2 recertification cycle durations and MLIT emergency autonomy mandate compliance thresholds.
Stress conditions across phosphor rare earth price volatility, NRA certification timeline extensions, and European retrofit budget compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and operator capital availability. Quarterly review of GB/T certification approval rates and EN 13272 amendment announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Heritage Railways Trains Market
Railway
Rolling Stocks Market
Railway
Rail Damper Market
Railway
Europe 40-Foot Platform Wagons Market
Railway
Train Exterior Lighting Market
Railway
Solar Train Market
Railway
Railroad Brake Shoe Market
Railway
Bullet Train Market
Railway
Smart Railways Market
Railway
Rail Seat Market
Railway
South Korea Connected Rail Market
Railway
Global Smart Locomotive Market
Railway
Freight Cars Market
Railway
Maglev Train Market
Railway
Rail Glazing Market
Railway
Train Locomotive Suspension Market