
 Automatic Train Control Market | 2026-2036
Automatic Train Control Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Train Control Market Analysis
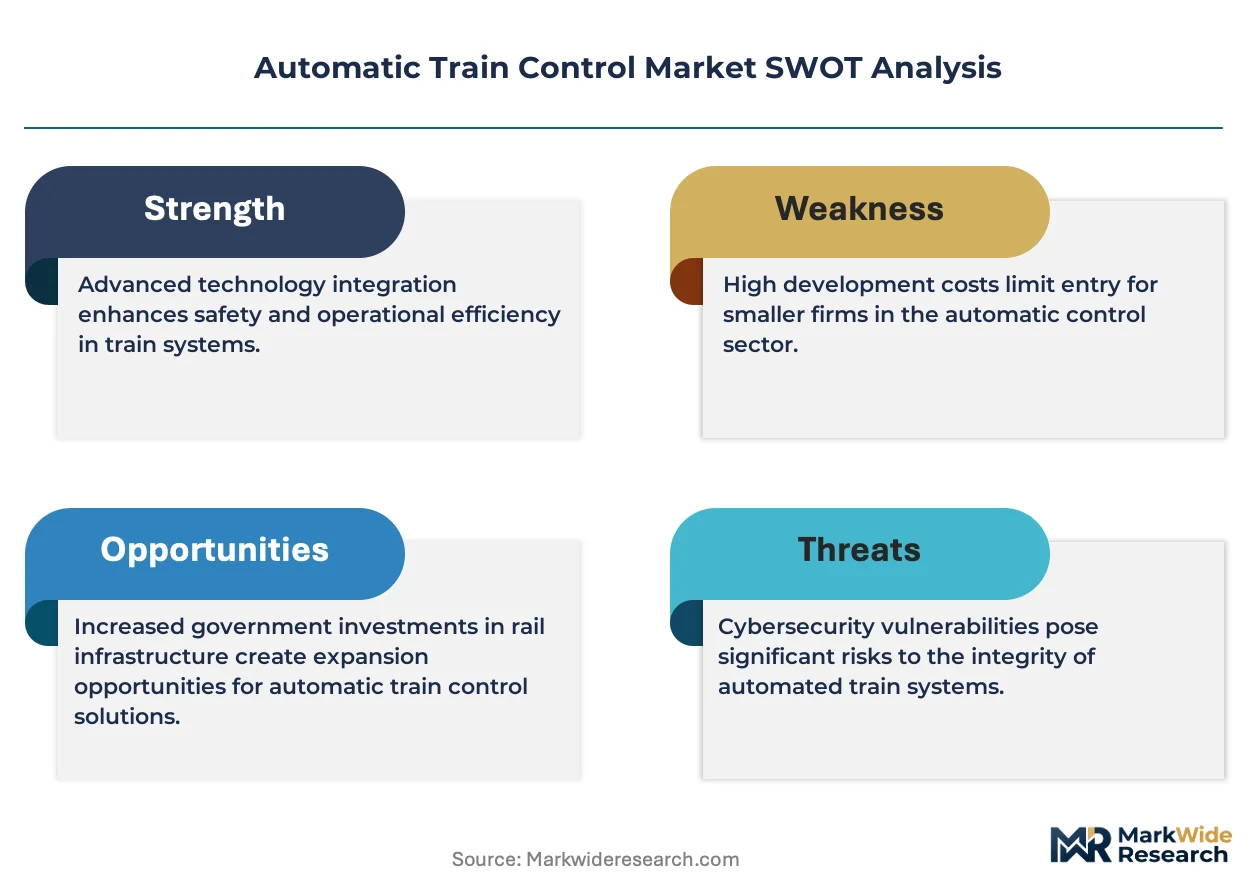
Urban metro buildouts is hardening as the dominant demand vertical for automatic train control infrastructure. Siemens leverages its signaling heritage across European and Asian metro tenders. Alstom sustains competitive intensity through integrated platform-screen door and CBTC bundling. Thales specializes in communication-based overlays for legacy line retrofits.
Automatic Train Control denotes integrated signaling and speed supervision systems that enforce safe braking curves, typically through continuous two-way track-to-train data exchange at millisecond cycle times. Its primary commercial purpose is to compress headways while eliminating human error as a collision causal factor. Communication-Based Train Control is displacing legacy fixed-block signaling in brownfield upgrades across mature networks. Positive Train Control occupies the regulatory-mandated tier in North American freight corridors, creating captive demand pools with constrained vendor eligibility. Metro Systems represent the fastest-growing end-user category, driven by driverless operation grade-of-automation targets.
The EU's ERTMS deployment mandate under the TEN-T regulation shapes product roadmaps for cross-border interoperability. China's NMPA and Ministry of Railways jointly enforce GB-standard certification that gates market access for foreign subsystem suppliers. India's CEA and Railway Board prescribe automatic train protection for all new dedicated freight corridors. Stakeholders must calibrate R&D allocation between legacy retrofit compatibility and greenfield autonomous operation architectures.
Market Dynamics
Communication-Based Train Control is consolidating market architecture as metro operators abandon fixed-block signaling for continuous two-way data exchange, compressing headways while eliminating human-error collision risks.
Growth Catalysts
- ERTMS Deployment Mandate:The EU's TEN-T regulation mandates cross-border interoperability standards, forcing legacy line retrofits across Germany, France, and Italy while opening tender pipelines for certified subsystem vendors.
- Urban Metro Buildouts:Asian megacities including Shanghai, Delhi, and Jakarta are accelerating driverless grade-of-automation targets, hardening metro systems as the dominant demand vertical for CBTC infrastructure.
- Freight Corridor Mandates:India's CEA and Railway Board prescribe automatic train protection for all new dedicated freight corridors, creating captive procurement pools with constrained vendor eligibility.
Market Restraints
- Certification Timeline Friction:China's NMPA and Ministry of Railways jointly enforce GB-standard certification gates that extend market access timelines for foreign subsystem suppliers by 18-36 months.
- Legacy Integration Burden:Brownfield upgrades require maintaining interoperability with existing fixed-block signaling during transition periods, doubling engineering complexity and commissioning risk.
- Specialized Labor Scarcity:The shallow pool of engineers proficient in both safety-critical software validation and rail-specific electromagnetic compatibility constraints limits deployment velocity.
Strategic Opportunities
- Autonomous Operation Architectures:Greenfield metro projects in Saudi Arabia's Riyadh Metro and Qatar's Doha Metro are specifying GoA4 fully unattended operation, demanding next-generation sensor fusion and AI-enhanced obstacle detection.
- Modular Retrofit Kits:Communication-based overlays for legacy lines enable phased upgrades without full line closures, opening addressable market in mature European networks with constrained maintenance windows.
- Digital Twin Integration:Convergence of CBTC with real-time simulation platforms allows predictive maintenance and scenario testing, creating new recurring revenue streams from software subscriptions.
Industry Challenges
- Safety Validation Bottlenecks:SIL4 software certification under CENELEC standards requires exhaustive fault-tree analysis and formal methods verification, extending development cycles and compressing margin structures.
- Cross-Vendor Interoperability:Mixed-fleet environments where trains from multiple OEMs must operate on shared infrastructure demand costly custom interface engineering and prolonged system integration testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Train Control Market |
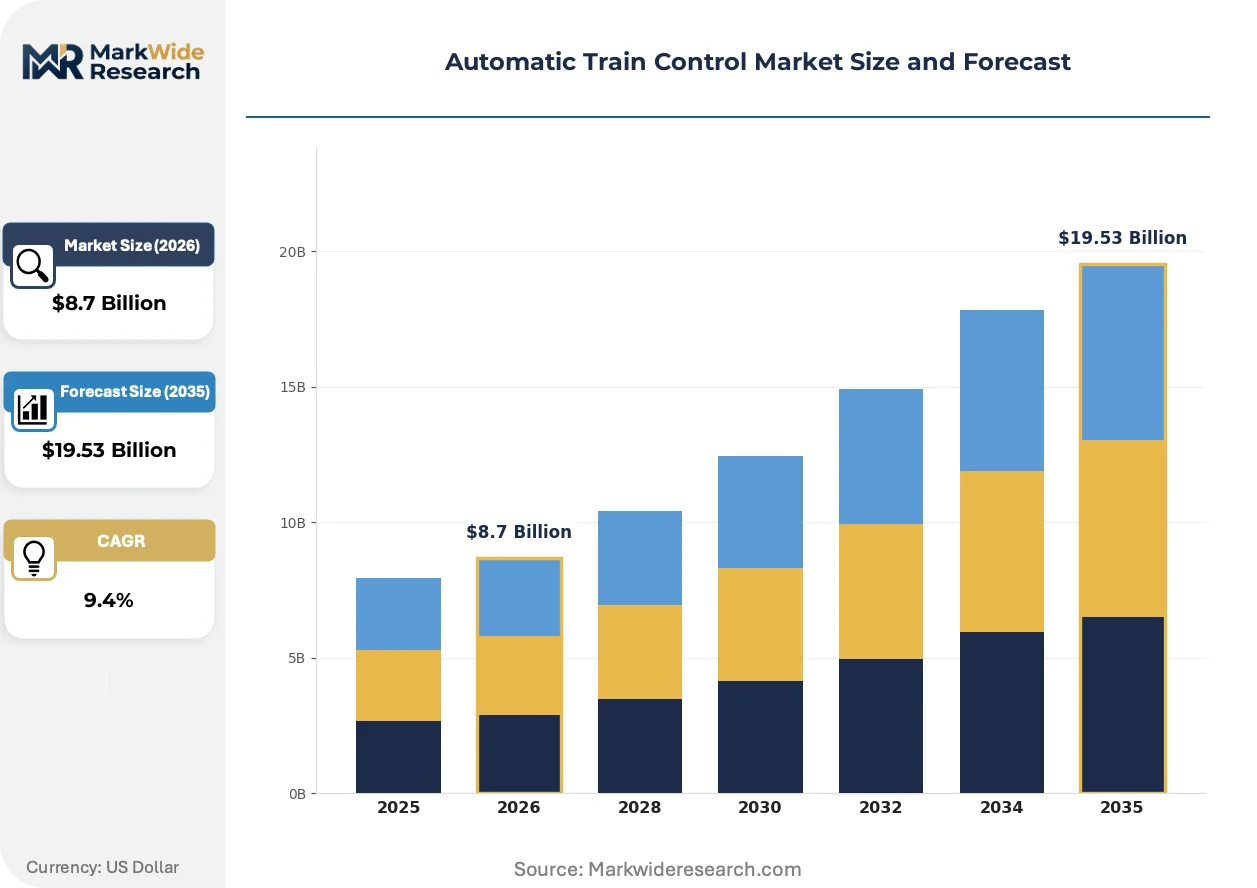
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Centralized, Decentralized, Distributed, Hybrid Technology: Signaling, Communication-Based, Automatic Train Protection, Positive Train Control End User: Rail Operators, Government Agencies, Private Operators, Metro Systems Application: Passenger Trains, Freight Trains, Subways, Light Rail |
| Companies Covered | Siemens, Alstom, Thales, Hitachi, Toshiba, Bombardier, General Electric, WSP, CRRC Corporation Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Train Control Market Emerging Trajectories
Digitalization of rail infrastructure is compressing procurement cycles while elevating software-defined functionality over hardware-centric legacy architectures, reshaping vendor competitive moats toward data analytics and predictive capabilities.
Moving-block signaling is consolidating train control architecture by replacing fixed track circuits with continuous position reporting via onboard odometry and wayside radio loops. Metro operators in Singapore, Dubai, and São Paulo are adopting this technology to achieve 90-second headways on congested lines. The shift is consolidating vendor portfolios around integrated platform-train interface management and automated train supervision suites.
Europe's F-Gas Regulation and complementary Ecodesign directives are phasing out sulfur hexafluoride in high-voltage trackside switchgear, compelling signaling OEMs to redesign power distribution architectures. The industrial consequence is accelerated R&D allocation toward vacuum interrupters and dry-air insulation systems. Urban metro electrification projects in Spain, Poland, and the Netherlands are most affected, with procurement specifications now mandating SF6-free substations as gate criteria.
Performance-based maintenance contracts are displacing traditional time-and-materials service agreements as transit authorities seek to transfer availability risk to system integrators. Rolling stock operators in Australia and Canada are piloting contracts where vendors guarantee 99.5% signaling system uptime against fixed annual fees. The model is most visible in mature networks with constrained capital budgets, where Toronto's TTC and Sydney Trains have structured tenders around outcome-based service level agreements.
Automatic Train Control Market Segmentation
Automatic train control procurement varies sharply by infrastructure vintage and operational mandate. Certification requirements from CENELEC, China's GB standards, and India's CEA create tiered barriers that reshape competitive access across each segment category.
System Type:
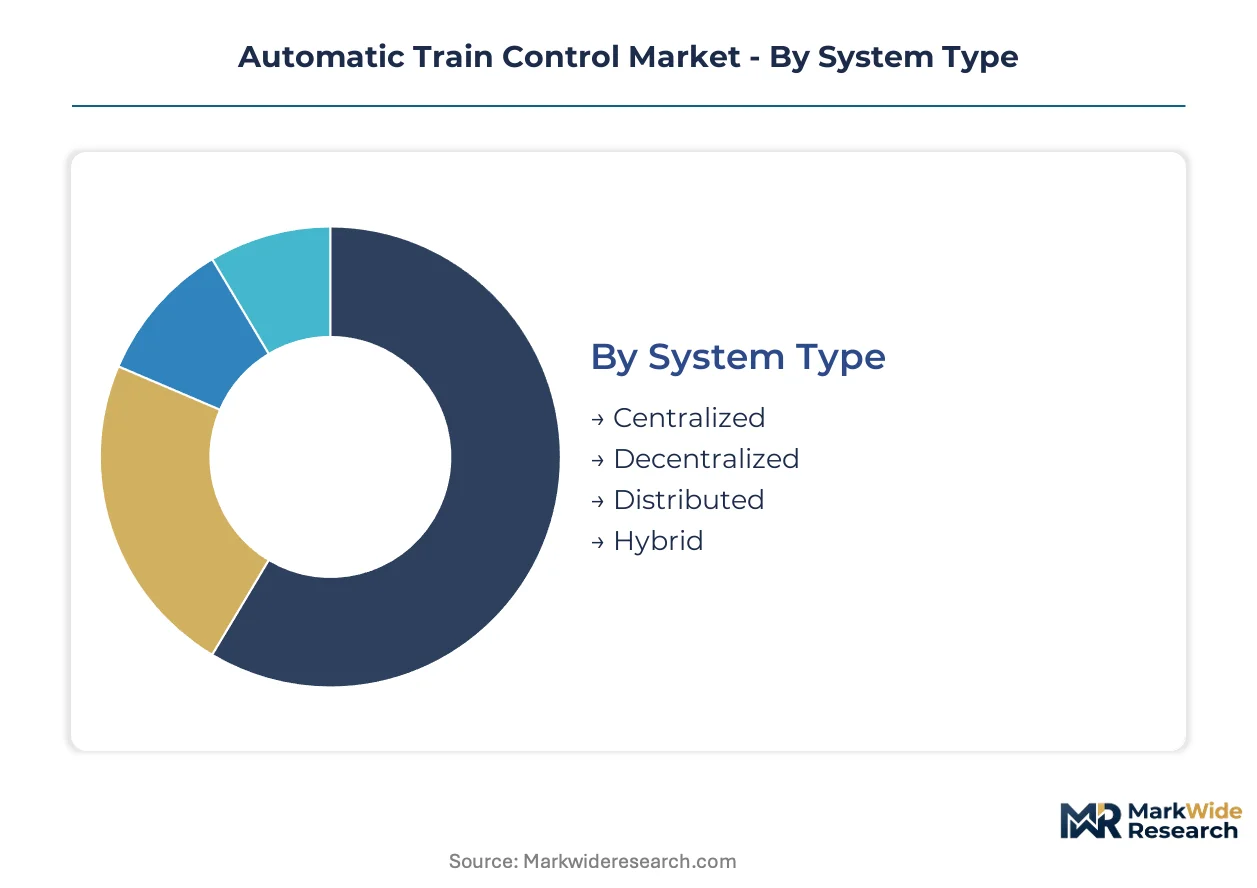
Centralized architectures demand SIL4 software validation under CENELEC 50128/50129, extending commissioning timelines. Decentralized and distributed systems face lighter conformance burdens but require electromagnetic compatibility certification under IEC 61000 series. Hybrid configurations trigger dual-track approval processes.
- Centralized:Single control center manages all trackside and onboard subsystems through redundant fiber-optic backbones. Metro operators in Shanghai and Delhi specify this architecture for high-density corridors where 90-second headways are mandatory. CENELEC SIL4 certification gates market access for European deployments.
- Decentralized:Regional control nodes operate autonomously with limited inter-node dependency, reducing single-point failure exposure. India's dedicated freight corridors under CEA mandate favor this topology for 1,500-kilometer stretches with sparse traffic. The Railway Board's automatic train protection prescriptions accelerate procurement here.
- Distributed:Intelligence resides primarily in wayside equipment with minimal central oversight.
- Hybrid:Combines centralized supervision with distributed fallback capabilities for resilience.
Centralized systems sit at the top of the volume ranking, with distributed configurations climbing the fastest.
Technology:
Technology selection tracks directly to line vintage and regulatory mandate. New-build metros gravitate toward continuous two-way data exchange, while freight corridors face statutory protection system requirements.
- Signaling:Legacy fixed-block architectures using track circuits and axle counters retain installed base in mature European networks. Germany's KBA and France's ANSM oversee safety validation for brownfield retrofits where interoperability with existing infrastructure is compulsory.
- Communication-Based:Continuous track-to-train data exchange via radio or leaky feeder cables enables moving-block operation. Singapore's Land Transport Authority and Dubai's RTA have standardized on this technology for driverless GoA4 operation.
- Automatic Train Protection:Speed supervision and emergency braking enforcement systems mandated for high-speed lines.
- Positive Train Control:Regulatory-mandated overlay for North American freight corridors under FRA jurisdiction.
Communication-based systems command the largest procurement volume, with positive train control expanding most quickly in mandated freight corridors.
End User:
End-user procurement authority determines specification stringency and contract structure. Government-funded programs emphasize interoperability certification, while private operators prioritize availability guarantees.
- Rail Operators:Incumbent national railways with established maintenance workforces and legacy asset bases. SNCF Réseau and Deutsche Bahn specify ERTMS baseline 3 for cross-border corridors under TEN-T regulation.
- Government Agencies:Transport ministries and urban development authorities funding greenfield metro construction. Saudi Arabia's Ministry of Transport and Qatar's Ministry of Municipality specify fully unattended operation for Riyadh and Doha metro expansions.
- Private Operators:Concession-based rail franchises and airport link operators.
- Metro Systems:Urban rapid transit authorities with grade-of-automation upgrade programs.
Metro systems lead procurement volume, with government agencies gaining share fastest through sovereign-funded megaprojects.
Application:
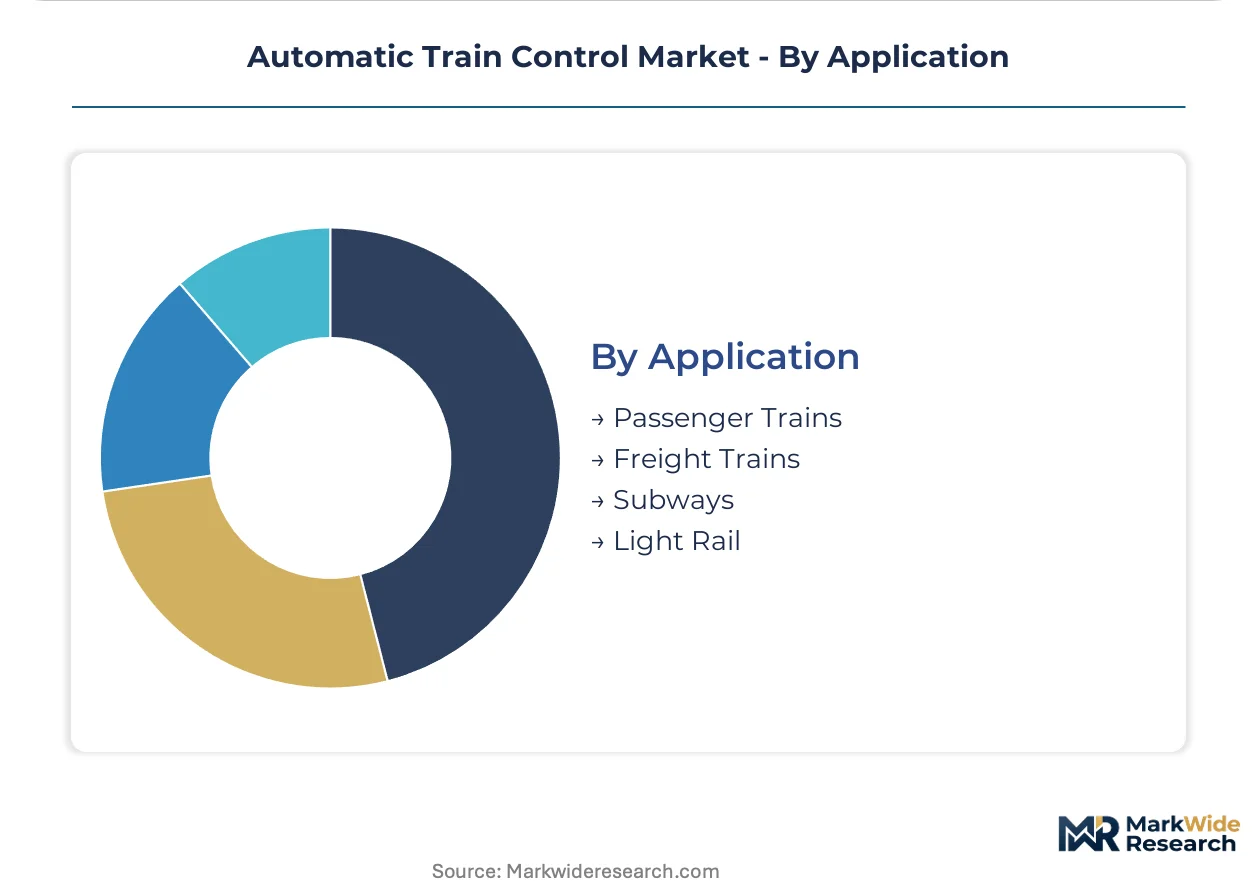
Application context dictates safety integrity level requirements and operational availability targets. Passenger service demands 99.9% uptime guarantees, while freight prioritizes interoperability across mixed-fleet environments.
- Passenger Trains:High-speed and intercity services requiring ETCS Level 2 or equivalent for speeds exceeding 250 km/h. China's Ministry of Railways enforces GB/T 25119 certification for onboard equipment on Beijing-Shanghai and Chengdu-Guiyang corridors.
- Freight Trains:Heavy-haul and intermodal services with distributed power configurations. India's Eastern and Western Dedicated Freight Corridors under CEA mandate require automatic train protection compatible with 25-ton axle loads.
- Subways:Underground metro networks with constrained tunnel envelopes and high-frequency service patterns.
- Light Rail:Surface tram and streetcar systems with mixed-traffic operation segments.
Subways dominate current procurement volume, with freight trains posting the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting procurement toward jurisdictions with streamlined certification pathways, as China's GB-standard gates extend foreign vendor timelines by 18-36 months while India's CEA mandates create captive demand pools with constrained eligibility.
China
High-speed rail network expansion drives concentrated demand for Communication-Based Train Control systems across Beijing-Shanghai and Chengdu-Guiyang corridors. NMPA and Ministry of Railways jointly enforce GB/T 25119 certification that gates market access for foreign subsystem suppliers. Shanghai's metro authority accelerates driverless GoA4 procurement, hardening the Yangtze River Delta as Asia's dominant deployment cluster.
India
Dedicated freight corridor buildouts under Eastern and Western routes mandate automatic train protection for 25-ton axle load operations. CEA and Railway Board prescriptions create procurement pools with vendor eligibility constraints favoring domestic-foreign joint ventures. The Delhi-Mumbai Industrial Corridor anchors signaling infrastructure deployment across Gujarat and Maharashtra sub-regions.
Germany
ERTMS baseline 3 deployment for cross-border corridors under TEN-T regulation forces legacy line retrofits across Deutsche Bahn's network. KBA oversees safety validation for brownfield upgrades where interoperability with existing fixed-block signaling remains compulsory. Berlin and Munich metro operators specify centralized CBTC architectures for 90-second headway targets.
United States
Positive Train Control mandates under FRA jurisdiction dominate freight corridor procurement across Class I railroads. Regulatory overlay requirements create captive demand with constrained vendor certification pathways. Chicago's rail hub concentration and California's high-speed rail authority drive specialized signaling procurement for mixed-fleet environments.
Saudi Arabia
Riyadh Metro and Doha Metro expansions specify GoA4 fully unattended operation, demanding next-generation sensor fusion architectures. Ministry of Transport funding prioritizes greenfield autonomous operation over legacy retrofit compatibility. The Riyadh-Qiddiya corridor anchors Gulf Cooperation Council procurement for sovereign-funded megaprojects.
Automatic Train Control Market Vendor Landscape
Strategic partnerships dominate the current landscape as signaling specialists seek to bridge capability gaps through subsystem integration alliances. The vendor base organizes around three tiers: integrated platform providers with rolling stock heritage, pure-play signaling specialists with certification depth, and state-affiliated champions with domestic market protection. Two archetypes define competitive positioning: full-system integrators bundling CBTC with platform-screen door solutions, and overlay specialists targeting brownfield retrofit niches. Geographic expansion through joint ventures and technology licensing agreements represent the dominant competitive vectors.
Within the integrated-system tier, Siemens and Alstom occupy positions shaped by their rolling stock and infrastructure heritage across European and Asian metro tenders. Thales exemplifies the communication-based overlay specialist archetype, anchoring competitive intensity in legacy line retrofit segments where millisecond-cycle track-to-train data exchange demands specialized expertise. CRRC Corporation Limited represents the state-affiliated champion model, with market access shaped by domestic certification regimes and sovereign-funded project pipelines.
| Leading Market Players |
|---|
| Siemens |
| Alstom |
| Thales |
| Hitachi |
| Toshiba |
| Bombardier |
| General Electric |
| WSP |
| CRRC Corporation Limited |
| Others |
Supply Flow & Price Mechanics
Engineers proficient in CENELEC SIL4 safety-critical software validation cluster in Germany and France, creating labor-cost differentials that widen pricing-tier spreads between premium-certified and standard-grade automatic train control subsystems.
Pricing Analysis
Distributor margins for trackside equipment range from 12-18% in European markets, compressing to 8-12% in Asian procurement where direct-to-OEM channels dominate. Project-based pricing structures prevail for greenfield metro deployments, with cost differentiation driven by CENELEC SIL4 certification grade and after-sales service bundling. Pricing pressure stems from China's GB-standard certification gates extending foreign vendor timelines. Government agencies exhibit lowest price sensitivity due to sovereign funding guarantees, while private operators in concession markets demonstrate highest sensitivity to availability-guarantee premiums.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from China's Ministry of Railways and India's Railway Board, bypassing traditional distribution layers for multi-corridor contracts. Manufacturing concentrates in Germany, France, and China, with critical component dependencies on specialized fiber-optic transceivers, redundant safety processors, and electromagnetic shielding materials. Single-source vulnerability runs through legacy semiconductor foundries producing radiation-hardened controllers. Distribution runs through systems integrators who bundle CBTC with platform-screen door solutions for metro operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automatic train control market functions as a stable compounder, with regulatory-mandated upgrade cycles across European and Asian rail networks ensuring predictable procurement pipelines.
For Market Incumbents: Deploy certification depth as a moat against modular retrofit specialists encroaching on brownfield segments. Accelerate backward integration into safety-critical semiconductor sourcing to mitigate single-source foundry exposure. Deepen ERTMS baseline 3 compliance investments ahead of TEN-T mandate deadlines, locking out vendors with lighter regulatory footprints. For New Entrants and Emerging Players: AI-enhanced obstacle detection for GoA4 unattended operation offers the most penetrable wedge into greenfield Gulf Cooperation Council megaprojects. Target Saudi Arabia's Riyadh-Qiddiya corridor and Qatar's Doha Metro expansion where incumbent relationships remain unformed. Pursue joint venture structures with domestic certification holders in India to bypass CEA eligibility constraints on dedicated freight corridors. For Investors and Strategic Acquirers: Rolling stock OEMs are the most active acquirer in this space, seeking to bundle signaling with platform-train interface management. Long-term viability centers on software-defined architectures displacing hardware-centric legacy systems over the coming decade. Monitor F-Gas Regulation compliance timelines as inflection indicator for vacuum interrupter technology substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| ERTMS Baseline 3 Certification | Unlocks tender eligibility for Deutsche Bahn cross-border corridors under TEN-T mandates. |
| GB-Standard Joint Venture Formation | Accelerates market access timelines for foreign suppliers bidding China's high-speed rail expansion. |
| Digital Twin Platform Integration | Creates recurring SaaS revenue from predictive maintenance contracts with Sydney Trains and Toronto TTC. |
| SF6-Free Switchgear Redesign | Secures procurement gate criteria for Spain and Netherlands metro electrification projects. |
| GoA4 Sensor Fusion Development | Captures Riyadh and Doha metro specifications for fully unattended operation architectures. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with signaling system procurement directors, CENELEC certification auditors, railway board technical advisors, and CBTC integration engineers with secondary validation against ERTMS deployment databases, TEN-T corridor planning documents, and national railway capital expenditure disclosures. Bottom-up project pipeline enumeration triangulated against top-down market sizing from OEM revenue segment reporting.
Historical reference periods anchored volume and value projections across the analysis window, with segmentation modeling across system architecture type, technology generation, end-user procurement authority, and application safety integrity level. CAGRs derived from corridor-specific deployment timelines and regulatory mandate schedules, incorporating dedicated freight corridor buildout pacing in India and high-speed network expansion cadence in China as industry-specific forecast inputs.
The model holds under stable certification timeline assumptions; deviation in GB-standard enforcement intensity or ERTMS mandate acceleration would shift vendor competitive positioning and procurement volume timing. Periodic stress-testing of base assumptions against actual tender award announcements and commissioning completion rates is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
40-Foot Platform Wagons Market
Railway
Gangway for Railway Vehicles Market
Railway
Rail Transit Traction Converter Market
Railway
Maglev Train Market
Railway
Hydrogen Fuel Cell Train Market
Railway
Rolling Stock Management Market
Railway
Locomotive Parking Brake Market
Railway
Connected Rail Market
Railway
Rail Glazing Market
Railway
Electro-Pneumatic Train Brakes Market
Railway
Global High-Speed Train Seat Market
Railway
Railway Digital Signal Axle Counters Market
Railway
Rail Brake Frame Market
Railway
Freight Cars Market
Railway
Railway Pantograph Market
Railway
Railway Telematics Market