
 Train Bogie Market | 2026-2036
Train Bogie Market Size, Share, and Industry Trends Forecast 2026-2036
Train Bogie Market Outlook
Modular bogie platform architectures is expanding buyer choice across freight, passenger, and high-speed configurations. CRRC Corporation Limited leverages its integrated supply chain to dominate domestic tenders and export markets across Asia and Africa. Alstom SA anchors its competitive position through technology leadership in tilting and active suspension systems for European corridors. Siemens Mobility GmbH differentiates via digital bogie health monitoring bundled with long-term service contracts.
A train bogie is a wheeled chassis assembly comprising axles, bearings, suspension elements, and braking systems, typically manufactured through welded steel fabrications or cast aluminum structures, designed to support rail vehicle bodies while guiding wheels along track geometry. Its primary purpose is to ensure ride stability, distribute axle loads, and enable curving performance across varying operational speeds. Passenger bogies command the largest value pool due to stringent comfort and safety specifications, while high-speed bogies capture premium margins through advanced active damping and lightweight composite integration. Freight bogies remain volume-dense but face margin compression from standardized designs and price-sensitive procurement by railway operators.
The EU's F-Gas Regulation and EN 15227 crashworthiness standards shape material selection and brake system architectures across European supply chains, while China's NMPA-equivalent rail safety authority and GB/T national standards enforce localized testing protocols for domestic deployments. India's CEA and RDSO specifications drive bogie localization mandates under the country's PLI scheme for rail component manufacturing. Stakeholders must monitor how diverging regional certification regimes affect platform standardization strategies and aftermarket parts interoperability.
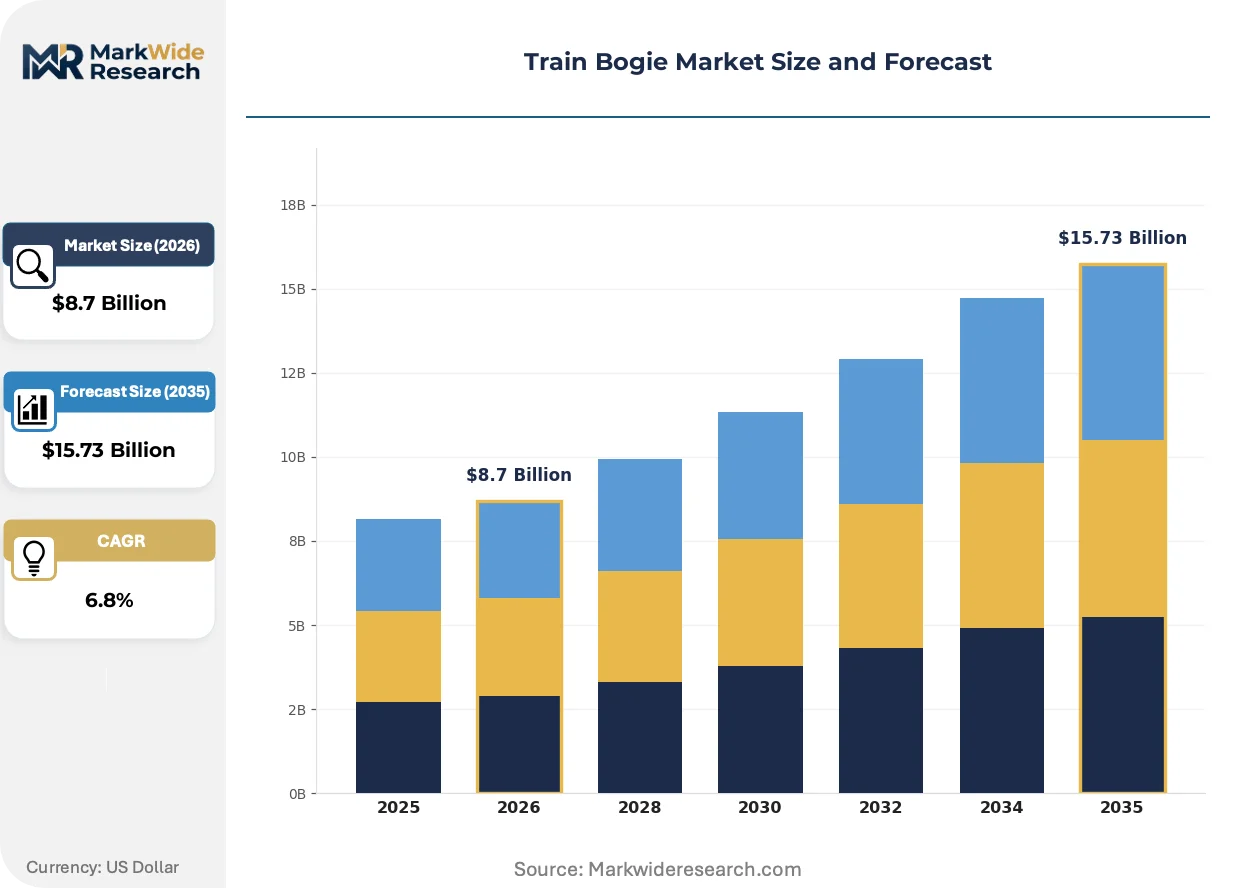
Market Dynamics
Lightweight material substitution is compressing traditional steel fabrication margins while forcing foundries to retool for aluminum and composite casting processes. EN 15227 crashworthiness mandates and China's GB/T standards are accelerating this transition across European and Asian supply chains.
Growth Catalysts
- High-speed rail expansion:China's CR450 prototype and Germany's Stuttgart-Ulm corridor are driving demand for active suspension bogies rated above 350 km/h.
- EN 15227 compliance deadlines:European operators must retrofit or replace legacy bogie frames by 2028, creating replacement demand across regional fleets.
- Aluminum-lithium alloys:Advanced wrought alloys from aerospace supply chains are enabling 15-20% weight reduction in passenger bogie structures.
Market Restraints
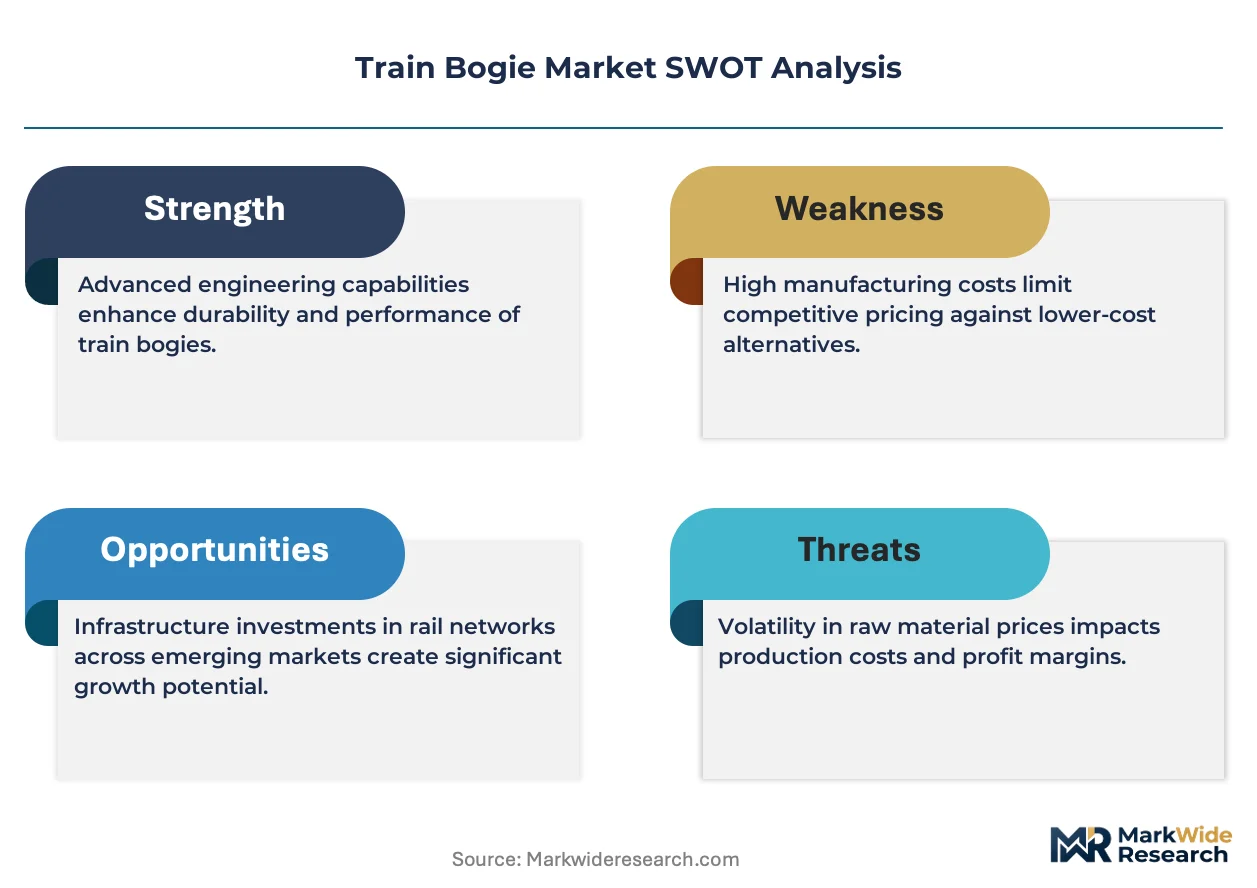
- Specialized casting capacity:Vacuum-assisted aluminum casting for hollow axles concentrates among a handful of European and Chinese suppliers.
- Composite certification timelines:Carbon fiber-reinforced bogie frames face extended validation cycles under GB/T and EN standards.
- Steel price volatility:Microalloyed steel plate for freight bogies remains exposed to scrap metal and energy input fluctuations.
Strategic Opportunities
- India's PLI scheme:Component localization mandates for metro and suburban fleets create captive manufacturing incentives for foreign joint ventures.
- Digital twin integration:Real-time bogie health monitoring converging with edge computing platforms opens recurring software revenue streams.
- Active magnetic levitation retrofit:Hybrid bogie designs for existing track infrastructure represent unpenetrated white space in intercity corridors.
Industry Challenges
- Welding technician scarcity:Automated aluminum MIG and friction stir welding require specialized certification programs that outpace vocational training output.
- Legacy fleet interoperability:New active suspension bogies must maintain mechanical coupling compatibility with 30-40 year old rolling stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Train Bogie Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freight Bogies, Passenger Bogies, Tilt Bogies, High-Speed Bogies Material: Steel, Aluminum, Composite, Cast Iron End User: Railway Operators, OEMs, Maintenance Providers, Contractors Design Type: Standard Design, Modular Design, Custom Design, Lightweight Design |
| Companies Covered | Kawasaki Heavy Industries, Ltd., Bombardier Transportation Inc., CRRC Corporation Limited, Titagarh Rail Systems Limited, CAF - Construcciones y Auxiliar de Ferrocarriles, S.A., Alstom SA, Amsted Rail, Hitachi Rail Ltd., Siemens Mobility GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Train Bogie Market Strategic Shifts
Predictive maintenance architectures and active suspension algorithms are displacing passive mechanical systems. Material science breakthroughs from adjacent aerospace and automotive sectors are cross-pollinating into rail bogie design.
Sensor-embedded axle bearings with vibration analysis algorithms are automating failure detection before temperature thresholds trigger traditional hot-box detectors. European freight operators are piloting these systems on Poland-Germany corridors. The technology is automating scheduled inspection intervals and compressing maintenance crew deployment costs.
EU F-Gas Regulation phase-down schedules are forcing refrigerant-dependent brake cooling systems toward CO2-based architectures. Compressor redesigns add engineering overhead but eliminate supply exposure to hydrofluorocarbon quota restrictions. High-speed passenger segments in France and Spain are absorbing these compliance costs earliest.
Indian Railways and suburban metro corporations are consolidating procurement under framework agreements spanning 10-15 year horizons. Long-term service contracts bundling bogie overhaul, wheelset replacement, and spare parts provisioning are displacing spot purchasing. This pattern concentrates most visibly in Mumbai, Delhi, and Bangalore urban rail expansions.
Train Bogie Market Segmentation
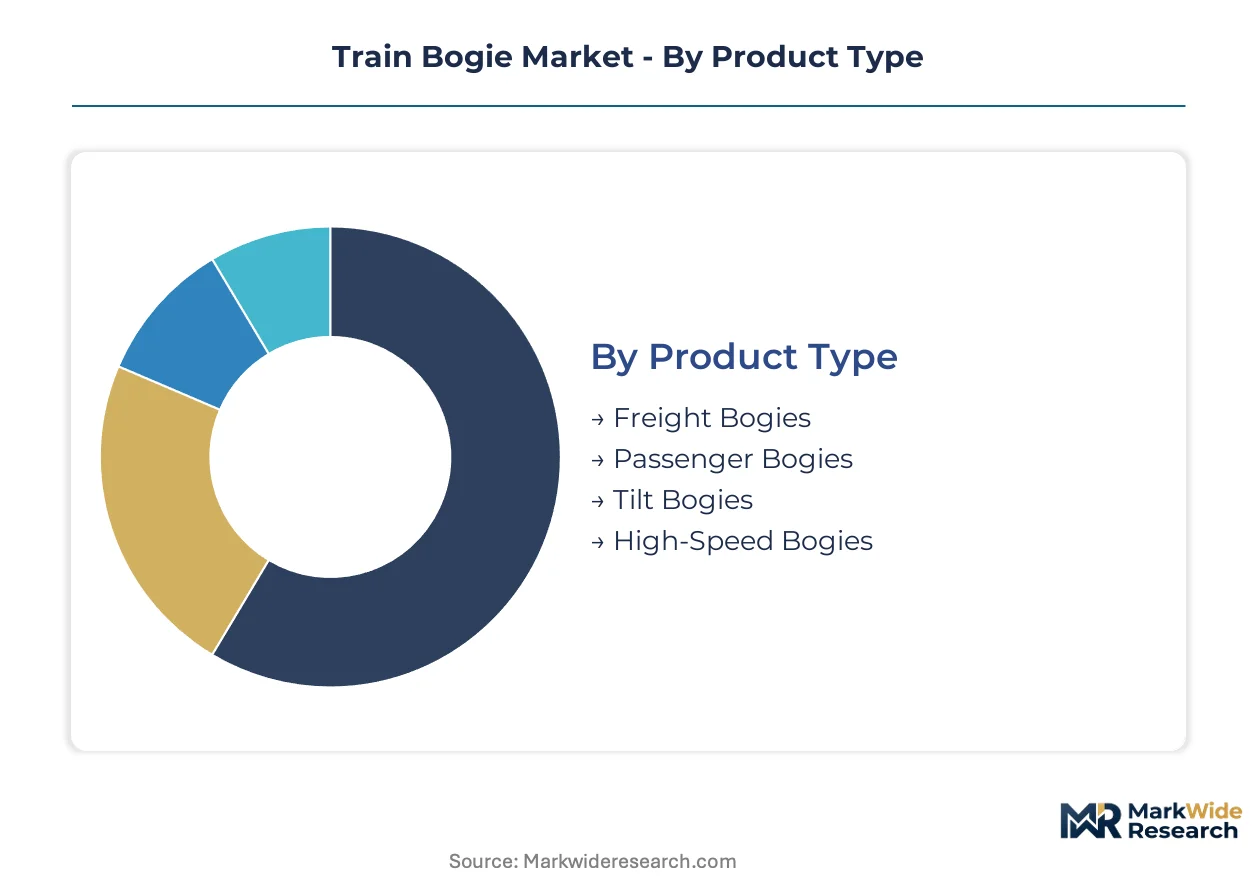
Train bogie segmentation reflects divergent engineering priorities across operational speeds, regulatory regimes, and lifecycle cost structures. Product architecture choices cascade through material selection, manufacturing processes, and aftermarket service economics. Understanding these interdependencies enables suppliers to align R&D investments with buyer procurement patterns.
Product Type:
Standardization dominates freight and legacy passenger segments while high-speed and tilt configurations demand bespoke engineering.
- Freight Bogies:Welded steel H-frame constructions with passive suspension systems predominate. Procurement concentrates among Indian and Chinese railway operators expanding bulk cargo corridors under cost-per-tonne constraints.
- Passenger Bogies:Secondary air suspension and disc brake architectures ensure ride comfort compliance. Metro and suburban deployments in India, Germany, and Japan absorb the highest unit volumes under EN 15227 and GB/T crashworthiness mandates.
- Tilt Bogies:Active hydraulic or electromechanical tilting mechanisms enable higher speeds on legacy curves. Limited deployment on European intercity routes where infrastructure upgrade costs exceed bogie premium.
- High-Speed Bogies:Active damping, lightweight aluminum-lithium frames, and aerodynamic fairings rated above 300 km/h. China's CR450 program and Germany's Stuttgart-Ulm corridor drive qualification requirements.
Leading the category by volume: Passenger Bogies. Expanding most quickly: High-Speed Bogies.
Material:
Cost tiers separate commodity steel from aerospace-derived alloys and certified composites.
- Steel:Microalloyed plate and forged axles remain the default for freight and regional passenger applications. Scrap metal price volatility compresses foundry margins across Polish and Ukrainian supply bases.
- Aluminum:Vacuum-assisted casting of hollow axles and welded frame extrusions enable 15-20% weight reduction. European high-speed OEMs and Chinese CRRC subsidiaries dominate qualified supplier pools.
- Composite:Carbon fiber-reinforced polymer frames face extended GB/T and EN validation cycles. Early adoption limited to prototype demonstrators and select Japanese Shinkansen iterations.
- Cast Iron:Brake discs and suspension brackets leverage established foundry infrastructure. Volume production concentrates in Indian joint ventures serving domestic PLI scheme requirements.
Dominant by procurement spend: Steel. Steepest expansion trajectory: Aluminum.
End User:
Customer type determines contract structure, from spot component sales to decade-long service bundling.
- Railway Operators:State-owned incumbents in India, China, and Germany drive framework agreements spanning 10-15 years. Long-term service contracts bundle overhaul, wheelset replacement, and predictive maintenance software.
- OEMs:Rolling stock manufacturers source complete bogie modules or subassemblies. CRRC, Alstom, and Siemens Mobility maintain captive supply or preferred supplier relationships.
- Maintenance Providers:Third-party overhaul specialists procure spare axles, bearings, and brake components. Consolidation among European freight operators creates procurement leverage.
- Contractors:Project-specific procurement for new line construction or fleet refurbishment. India's metro expansions in Mumbai, Delhi, and Bangalore generate concentrated demand spikes.
Highest contract value: Railway Operators. Fastest-growing procurement autonomy: Maintenance Providers.
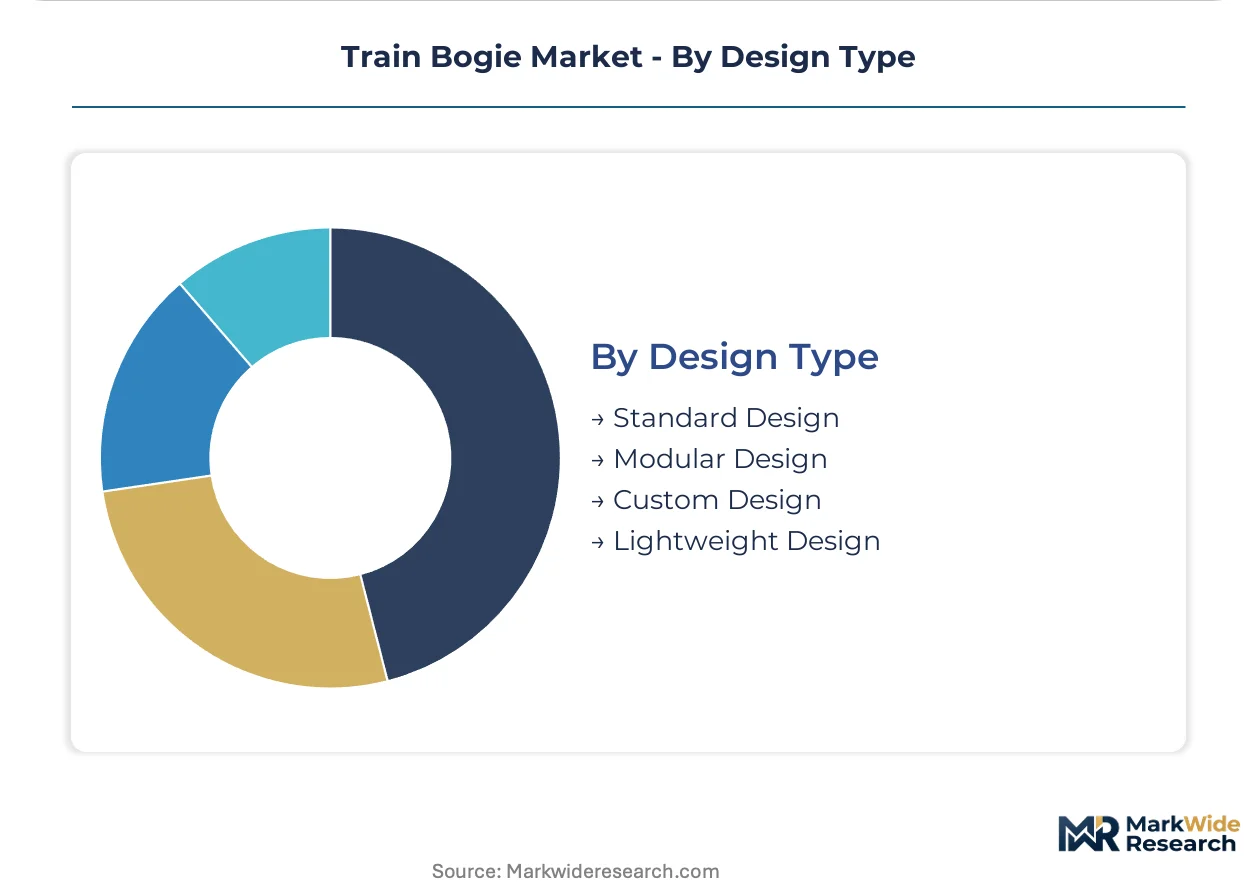
Design Type:
Maturity gradients separate proven architectures from emerging platform strategies.
- Standard Design:Fixed-parameter bogies for predictable operational profiles. Freight and regional passenger fleets in Eastern Europe and Southeast Asia rely on these configurations.
- Modular Design:Interchangeable suspension, brake, and axle subsystems across freight, passenger, and high-speed variants. CRRC leverages this architecture to compress tender response times.
- Custom Design:Bespoke engineering for gauge-constrained networks or extreme climate conditions. Russian broad-gauge and Australian heavy-haul corridors require specialized adaptations.
- Lightweight Design:Topology-optimized frames and hollow axle geometries. Active magnetic levitation hybrid prototypes represent unpenetrated white space in intercity corridors.
Widest installed base: Standard Design. Gaining share fastest: Modular Design.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in China and Germany while consumption spreads across expanding metro networks in India and high-speed corridors in Spain. Foundry capacity for aluminum-lithium alloys clusters near CRRC subsidiaries and Siemens supply bases. Regulatory divergence between EN 15227 and GB/T standards fragments certification pathways.
China
CR450 prototype development and domestic metro expansion absorb the highest bogie volumes globally. GB/T national standards enforce localized testing protocols that foreign suppliers must satisfy through joint ventures. Qingdao and Changchun industrial corridors host integrated manufacturing clusters serving both domestic tenders and export markets across Asia and Africa.
Germany
Stuttgart-Ulm high-speed corridor and Rhine freight networks drive demand for active suspension systems. EN 15227 crashworthiness mandates require retrofit or replacement of legacy bogie frames by 2028. Berlin-Brandenburg and Munich regions concentrate engineering centers for tilting mechanism development and digital health monitoring platforms.
India
Mumbai, Delhi, and Bangalore metro expansions generate concentrated demand spikes under 10-15 year framework agreements. CEA and RDSO specifications enforce component localization mandates through the PLI scheme for rail component manufacturing. Titagarh Rail Systems and joint venture partners are establishing captive foundry capacity in West Bengal and Maharashtra.
Spain
High-speed passenger segments absorb compliance costs for F-Gas Regulation phase-down schedules earliest among European corridors. Barcelona and Madrid industrial zones maintain foundry infrastructure for vacuum-assisted aluminum casting. Tilt bogie deployment on legacy curves exceeds penetration rates in neighboring France and Italy.
Japan
Shinkansen network iterations pioneer carbon fiber-reinforced polymer frame prototypes despite extended validation cycles. METI standards and JIS certification protocols govern material substitution timelines. Kawasaki and Nagoya manufacturing clusters supply bearing and suspension subassemblies across Pacific Rim export markets.
Train Bogie Market Competitive Environment
The competitive structure tilts toward integrated rolling stock manufacturers with captive bogie production. State-backed champions and diversified industrial conglomerates occupy distinct tiers. Strategic differentiation runs through modular platform architectures, active suspension technology licensing, and long-term service contract bundling. Geographic expansion through joint ventures and backward integration into aluminum casting represent the dominant competitive moves.
Among integrated rolling stock manufacturers, CRRC Corporation Limited, Alstom SA, and Siemens Mobility GmbH anchor the premium tier. CRRC exemplifies the state-backed champion archetype leveraging domestic scale for export competitiveness. Alstom occupies a position emphasizing tilting and active suspension technology leadership. Siemens Mobility sits within the digital services integration archetype through predictive maintenance software bundling. These three represent divergent strategic paths: vertical supply chain control, technology specialization, and recurring revenue platformization.
| Leading Market Players |
|---|
| Kawasaki Heavy Industries, Ltd. |
| Bombardier Transportation Inc. |
| CRRC Corporation Limited |
| Titagarh Rail Systems Limited |
| CAF - Construcciones y Auxiliar de Ferrocarriles, S.A. |
| Alstom SA |
| Amsted Rail |
| Hitachi Rail Ltd. |
| Siemens Mobility GmbH |
| Others |
Value Chain & Pricing Dynamics
Certified aluminum welders in Germany's Ruhr industrial corridor command 40-60% labor-cost premiums over Polish and Indian counterparts, widening spreads between premium active-suspension bogies and standardized freight configurations. This workforce concentration shapes three-tier pricing stratification across European supply chains, with EN 15227-certified frames absorbing compliance overhead while Asian producers exploit aluminum-casting labor arbitrage.
Pricing Analysis
Margin tightening in high-speed passenger segments reflects aluminum-lithium alloy sourcing constraints and EN 15227 crashworthiness certification overhead. Three-tier pricing structure across premium active-suspension, standard air-spring, and economy welded-steel levels separates buyers by operational speed tier and regulatory jurisdiction. Freight operators in India and Eastern Europe exhibit highest price sensitivity under cost-per-tonne procurement models, while China's state-backed railway corporations absorb premium pricing for CR450 prototype deployment.
Supply Chain Analysis
Regional distribution centers in Qingdao, Berlin-Brandenburg, and Mumbai coordinate hub-and-spoke patterns for axle bearing and brake component fulfillment. Vacuum-assisted aluminum casting capacity concentrates in China, Germany, and Spain, with hollow axle production drawing from aerospace-qualified foundry infrastructure. Single-source vulnerability pervades carbon fiber-reinforced frame certification under GB/T and EN standards. Distribution runs through OEM captive networks and third-party maintenance providers under long-term service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized welding technician scarcity props pricing power for certified European suppliers, constraining capacity expansion timelines across aluminum bogie frame production.
For Market Incumbents: Lock in captive aluminum-lithium supply agreements with aerospace-tier foundries before CR450-scale demand absorbs qualified capacity. Deepen backward integration into vacuum-assisted casting for hollow axles to defend margin position against Chinese state-backed competitors exploiting domestic GB/T certification pathways. For New Entrants and Emerging Players: Digital twin integration for predictive maintenance software offers the lowest capital-barrier entry route into railway operator service contracts. Target India's PLI-scheme joint venture structures in West Bengal and Maharashtra, where component localization mandates create penetrable procurement windows for foreign technology partners. For Investors and Strategic Acquirers: Re-rating potential sits with modular platform architects given India's 10-15 year framework agreement consolidation. Long-term viability hinges on recurring software revenue attachment rates rather than spot component sales. Watch EN 15227 retrofit deadline compliance across German and French fleets as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum-Lithium Supply Agreement | Secures aerospace-grade alloy access for CR450 and Stuttgart-Ulm high-speed programs. |
| Digital Twin Platform Launch | Enables predictive maintenance software bundling with 10-15 year operator contracts. |
| GB/T Certification Investment | Opens Chinese domestic tender access through localized testing protocol compliance. |
| India PLI Joint Venture | Captures metro expansion demand under CEA and RDSO localization mandates. |
| Composite Frame Validation Program | Accelerates carbon fiber-reinforced bogie qualification under EN 15227 timelines. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across rolling stock procurement directors, foundry operations managers, railway maintenance chiefs, and aluminum alloy sourcing specialists. UNIFE sector reports, Chinese railway GB/T submission databases, Indian RDSO certification registries, and EU F-Gas Regulation compliance disclosures supplied quantitative foundations. Bottom-up segment sizing triangulated against top-down production capacity assessments.
Production volume, material grade tier, end-use speed classification, and regional regulatory cluster reconciliation shaped the analytical framework across the projection horizon. CAGRs derived from segment-level elasticity modeling against infrastructure investment pipelines. Forecast inputs incorporated high-speed rail corridor commissioning schedules and EN 15227 retrofit compliance deadlines without year-specific anchoring.
The model holds under stable aluminum alloy supply and sustained infrastructure investment; deviation in steel scrap volatility or welding certification program expansion would shift capacity-constraint assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Railroad Brake Shoe Market
Railway
Global Hyperloop Train Market
Railway
Railway Pantograph Market
Railway
Rail Damper Market
Railway
Rail Seat Market
Railway
Gangway for Railway Vehicles Market
Railway
Asia Pacific Rail Freight Transport Market
Railway
Railway Braking System Market
Railway
Latin America Connected Rail Market
Railway
India Rail Freight Transport Market
Railway
Global Train Lighting Market
Railway
Railway Horn Market
Railway
Rolling Stock Management Market
Railway
Rail Composites Market
Railway
Locomotive Radiator Fan Market
Railway
Railway Draft Gears Market