
 Sanitary Systems for Rail Transit Market | 2026-2036
Sanitary Systems for Rail Transit Market Size, Share, and Industry Trends Forecast 2026-2036
Sanitary Systems for Rail Transit Market Insights
EN 45545-2 fire safety compliance is redrawing procurement criteria across European rail sanitary equipment. Wabtec Corporation leverages its North American manufacturing scale to supply EPA-compliant retention tank systems for commuter rail authorities. Knorr-Bremse Systeme für Schienenfahrzeuge GmbH anchors continental European demand through integrated vacuum waste modules that meet ECHA REACH material restrictions. Guangdong Huatie Tongda High-speed Railway Equipment Corporation dominates China's high-speed fleet with domestically certified toilet platforms aligned to GB standards.
Sanitary systems for rail transit encompass vacuum collection, waste retention, treatment, and disposal equipment engineered for mobile rail environments, typically operating with 0.5–1.2 bar differential pressure in vacuum toilet modules to ensure reliable waste transport at varying altitudes and speeds. These systems serve the essential function of maintaining passenger hygiene standards while minimizing water consumption and environmental discharge during rail operations. Vacuum toilets command the largest installed base among product types due to their proven reliability in high-frequency service cycles across intercity networks. Water recycling technology represents the fastest-expanding segment as drought-prone jurisdictions impose mandatory freshwater reduction targets on rolling stock operators. Bio-digestion systems occupy a niche but growing position in sleeper coach applications where extended journey times enable longer waste processing cycles.
EPA effluent guidelines and ECHA REACH chemical restrictions jointly determine material selection and treatment chemistry for rail sanitary equipment sold in North America and Europe. China's MEE enforces dual carbon goals that push domestic manufacturers toward low-energy vacuum systems and reduced chemical usage in waste processing. India's CEA railway electrification mandates indirectly shape sanitary system specifications as operators modernize rolling stock alongside power infrastructure upgrades. Stakeholders must monitor evolving national discharge standards to determine whether localized treatment or centralized offloading infrastructure delivers lower total cost of ownership across their fleet networks.
Market Dynamics
EN 45545-2 fire safety mandates are forcing rail operators to replace legacy foam insulation and plastic waste tanks with certified halogen-free alternatives, compressing procurement cycles and disqualifying incumbent suppliers lacking material traceability documentation.
Growth Catalysts
- China MEE effluent discharge standards:High-speed rail operators must retrofit vacuum toilet systems to meet stricter environmental rules, triggering fleet-wide upgrade programs across intercity corridors.
- Water recycling technology maturation:Drought-prone jurisdictions in Australia and Spain now mandate freshwater reduction targets per passenger kilometer for new rolling stock procurements.
- Sleeper coach bio-digestion adoption:Extended overnight routes in India and Russia enable longer waste processing cycles, creating viable deployment conditions for biological treatment systems.
Market Restraints
- Stainless steel and specialty polymer input costs:Waste retention tank fabrication depends on nickel-priced alloys and flame-retardant thermoplastics subject to commodity volatility.
- European supplier concentration:Vacuum waste module production clusters in Germany and France, exposing buyers to single-source risk during capacity constraints.
- REACH chemical restriction compliance:ECHA limitations on brominated flame retardants force reformulation of sealing gaskets and tank linings, extending qualification timelines.
Strategic Opportunities
- India CEA electrification corridors:Railway modernization alongside power infrastructure upgrades creates synchronized demand for sanitary system replacements in newly electrified routes.
- Modular retrofit kits:Standardized drop-in vacuum toilet platforms reduce installation downtime from weeks to days, opening aftermarket revenue streams for maintenance depots.
- EU Green Deal operational targets:Carbon reduction mandates for public transport operators favor low-energy vacuum systems with regenerative blower technologies.
Industry Challenges
- EN 45545-2 HL3 certification timelines:Fire safety testing for new material combinations extends product validation by 12-18 months, delaying fleet deployment schedules.
- Legacy pneumatic system integration:Mixed fleets containing 1980s-era pressure-differential toilets require custom adapter hardware, complicating standardization efforts across operator networks.
- Specialized technician scarcity:Vacuum system maintenance demands expertise in both plumbing and rail-specific electrical systems, constraining depot service capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sanitary Systems for Rail Transit Market |
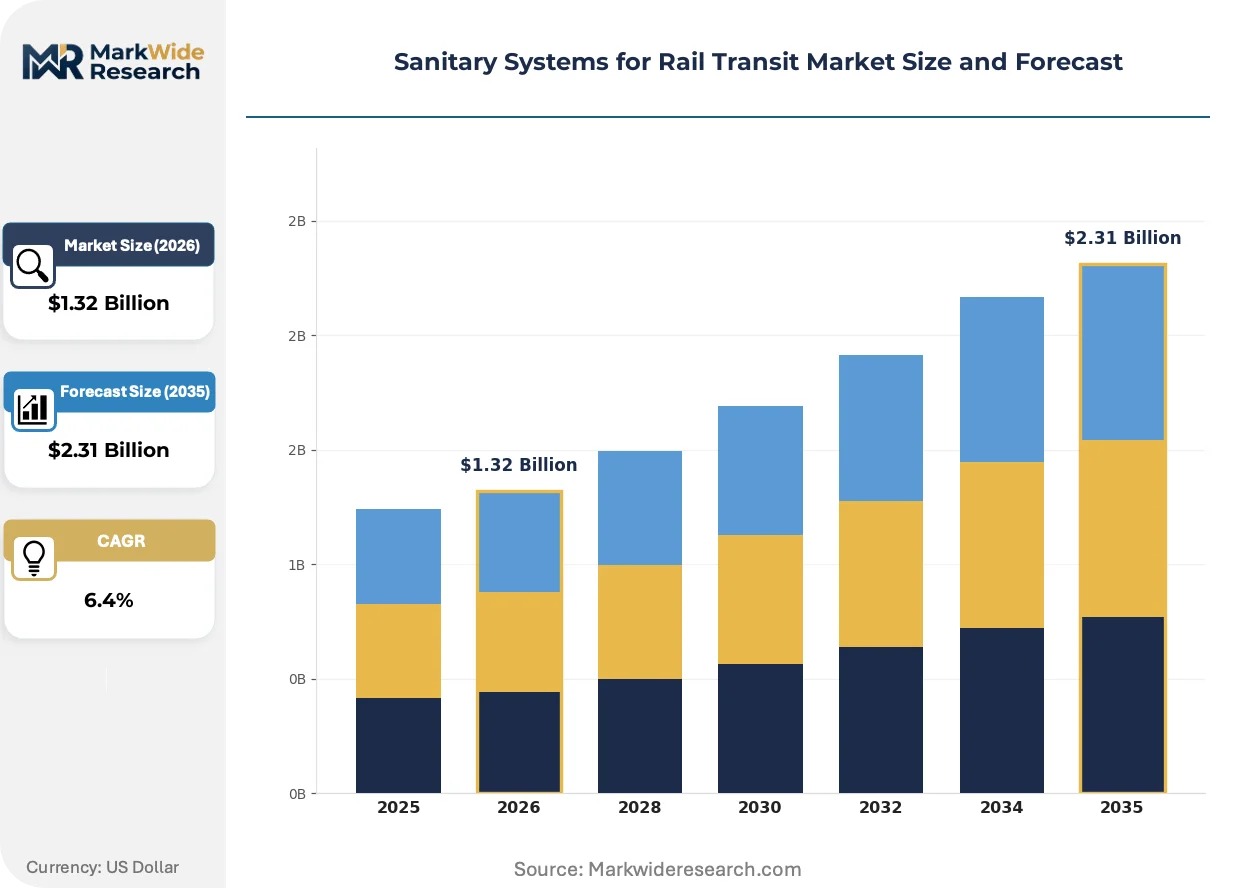
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.31 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
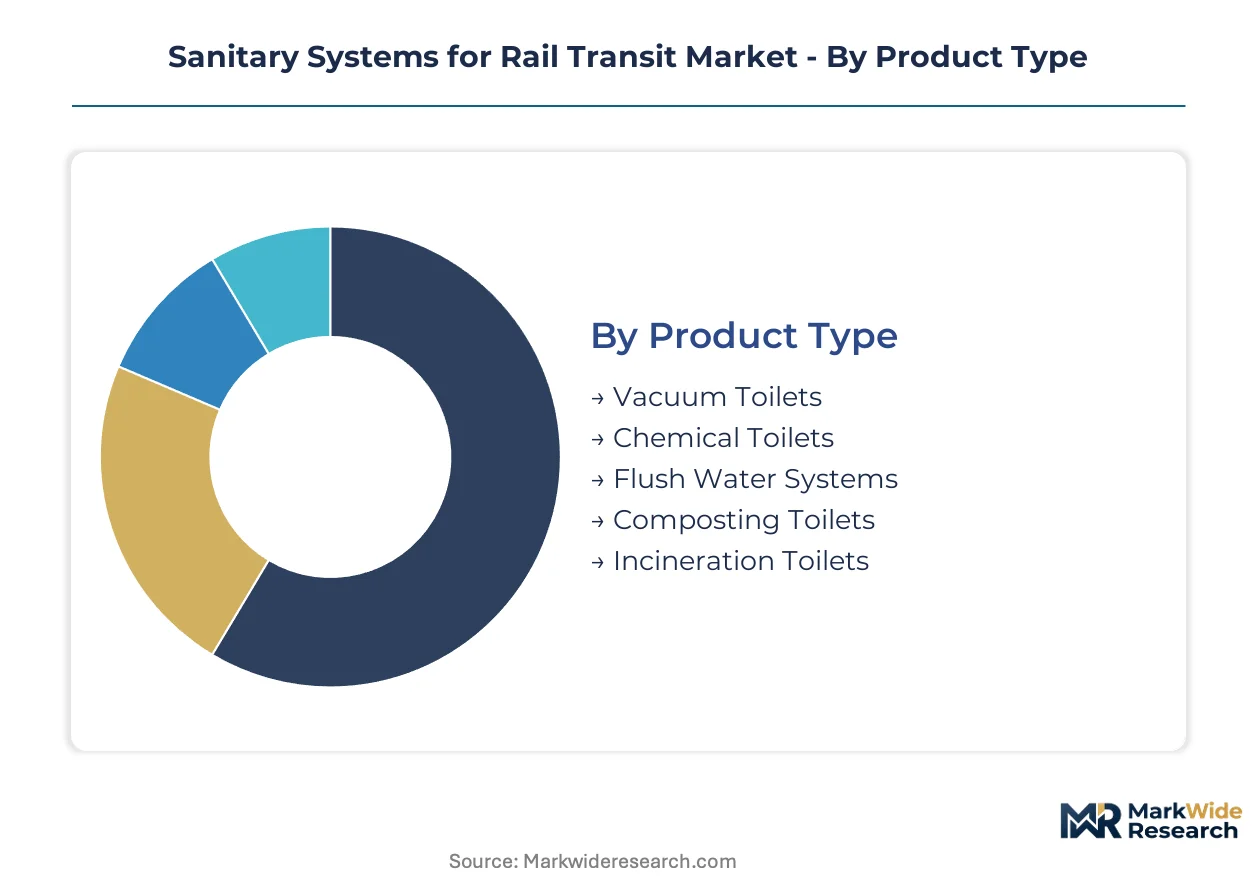
| Segmentation | Product Type: Vacuum Toilets, Chemical Toilets, Flush Water Systems, Composting Toilets, Incineration Toilets Technology: Water Recycling, Bio-Digestion, Electrolytic Treatment, UV Sterilization, Ozone Treatment Application: Urban Passenger Trains, High-Speed Trains, Light Rail Vehicles, Freight Locomotives, Sleeper Coaches End User: Rail Operators, Maintenance Providers, Transit Authorities, Private Railcar Owners |
| Companies Covered | Wabtec Corporation, Guangdong Huatie Tongda High-speed Railway Equipment Corporation, Trainvac, Knorr-Bremse Systeme für Schienenfahrzeuge GmbH, EVAC, Roediger Vacuum GmbH, Dowaldwerke GmbH, Goko Seisakusho, Glova Rails, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sanitary Systems for Rail Transit Market Trends and Innovations
Active regulatory pressure and operational efficiency targets are fragmenting procurement approaches across geographic corridors, with technology selection increasingly tied to localized environmental mandates rather than universal performance benchmarks.
Vacuum toilet technology is bifurcating between high-speed rail applications demanding 0.5 bar differential pressure for altitude compensation and urban metro systems prioritizing compact footprint over pressure range. Chinese operators are deploying the high-performance variant across mountain corridors, while European tram networks adopt simplified low-pressure modules. This divergence is compressing the addressable market for universal product platforms and rewarding specialized engineering capabilities.
EPA effluent guidelines for rail operations are tightening discharge limits for ammonia and suspended solids in retention tank offload procedures. US commuter authorities must now install secondary treatment stages or construct dedicated rail-servicing facilities at terminal stations. The Northeast Corridor bears the highest compliance burden, with operators testing mobile vacuum extraction trucks as an alternative to fixed infrastructure.
After-sales service unbundling is disrupting traditional supply relationships as rail authorities separate component procurement from long-term maintenance contracts. Deutsche Bahn and SNCF now tender sanitation system upkeep through independent facility management consortia rather than original equipment manufacturers. France exhibits the most advanced contracting sophistication, with performance-based agreements tying service payments to system availability rates rather than scheduled interventions.
Sanitary Systems for Rail Transit Market Segmentation
Rail sanitary procurement splits sharply across operating environments, with altitude tolerance, journey duration, and discharge infrastructure availability dictating technology selection. Understanding where specification requirements diverge enables suppliers to align R&D investment with margin-rich deployment corridors.
Product Type:
Vacuum toilets command the deepest margin pools due to their complexity and regulatory certification barriers, while chemical systems compete primarily on upfront cost in budget-constrained fleets.
- Vacuum Toilets:These systems operate at 0.5–1.2 bar differential pressure to ensure reliable waste transport across varying altitudes and speeds. Demand concentrates in China's high-speed corridors where MEE effluent discharge standards mandate fleet retrofits, and in European intercity networks where EN 45545-2 fire safety compliance requires certified halogen-free material construction.
- Chemical Toilets:Portable self-contained units utilizing chemical biocides for waste breakdown and odor control. Operators in India's non-electrified rural routes and heritage railway services favor these for minimal infrastructure dependency, though ECHA REACH restrictions on formaldehyde-based formulations are narrowing chemical options in Europe.
- Flush Water Systems:Conventional freshwater-based toilets requiring onboard storage tanks and discharge connections.
- Composting Toilets:Biological decomposition systems for organic waste conversion.
- Incineration Toilets:High-temperature combustion units for complete waste elimination.
The dominant share belongs to Vacuum Toilets, while Bio-Digestion-enabled composting variants are closing the gap fastest in sleeper coach deployments.
Technology:
Technology selection tracks regional water stress indices, with recycling and bio-digestion systems gaining procurement preference in drought-prone jurisdictions.
- Water Recycling:Closed-loop filtration systems reducing freshwater consumption per passenger kilometer through multi-stage membrane and activated carbon treatment. Deutsche Bahn's intercity express corridors anchor European adoption, while Australian and Spanish mandates for freshwater reduction targets are accelerating procurement across new rolling stock.
- Bio-Digestion:Anaerobic bacterial processing of organic waste extending treatment cycles over 12-24 hours. Extended overnight routes in India and Russia create viable deployment conditions, with Indian Railways testing integrated bio-digestion modules in Rajdhani Express sleeper coaches to eliminate intermediate discharge stops.
- Electrolytic Treatment:Salt-based electrochemical generation of disinfectant compounds.
- UV Sterilization:Ultraviolet irradiation for pathogen inactivation in treated effluent.
- Ozone Treatment:Oxidative gas injection for advanced organic compound breakdown.
Water Recycling holds the installed base lead, yet Bio-Digestion is expanding most quickly in jurisdictions with extended-route topography.
Application:
Application segmentation reflects divergent engineering priorities, with high-speed networks prioritizing weight reduction and metro systems optimizing for spatial efficiency.
- High-Speed Trains:Vacuum systems with altitude-compensating pressure regulation dominate procurement. China's CR400 series fleet and European TGV networks specify 0.5 bar differential pressure modules for mountain corridor reliability, with fire safety certification to EN 45545-2 HL3 mandatory for European tenders.
- Sleeper Coaches:Extended journey durations enable longer waste processing cycles. Indian Railways and Russian Railways are piloting bio-digestion integration in premium overnight services, where 18-24 hour transit times align with biological treatment horizons.
- Urban Passenger Trains:High-frequency short-haul services with rapid turnaround requirements.
- Light Rail Vehicles:Tram and streetcar networks with severe space and weight constraints.
- Freight Locomotives:Crew cabin sanitation for long-haul freight operations.
High-Speed Trains absorb the largest capital deployment, though Sleeper Coaches are gaining share fastest as overnight rail tourism revives across Asia and Europe.
End User:
End user structure is fragmenting as maintenance unbundling separates component procurement from long-term service contracts.
- Rail Operators:Integrated national carriers and private concessionaires specifying fleet-wide sanitary standards. SNCF and Deutsche Bahn now tender sanitation upkeep through independent facility management consortia rather than OEMs, with French performance-based agreements tying payments to system availability rates.
- Maintenance Providers:Independent depot operators and rolling stock refurbishment specialists. These entities drive aftermarket demand for modular retrofit kits, with standardized drop-in vacuum toilet platforms reducing installation downtime from weeks to days in North American commuter authorities.
- Transit Authorities:Municipal and regional public transport agencies.
- Private Railcar Owners:Luxury charter operators and heritage railway preservation societies.
Rail Operators retain the dominant procurement volume, yet Maintenance Providers are capturing influence fastest through aftermarket service unbundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in rail sanitary equipment reveal concentrated manufacturing hubs supplying cross-border fleet retrofits. Germany and China maintain net export positions in vacuum waste modules, while India and the United States absorb significant import volumes for electrification-linked rolling stock modernization.
Germany
Deutsche Bahn's intercity express corridors drive demand for water recycling systems with reduced freshwater consumption targets. ECHA REACH chemical restrictions govern material selection for sealing gaskets and tank linings across domestic manufacturing. Baden-Württemberg hosts specialized vacuum module production clusters serving continental European rail operators.
China
High-speed rail fleet expansion and MEE effluent discharge standards trigger widespread vacuum toilet retrofits across CR400 series trains. The dual carbon goals framework pushes manufacturers toward low-energy vacuum systems with reduced chemical usage. Pearl River Delta manufacturing bases supply domestically certified toilet platforms aligned to GB standards for both domestic deployment and Belt and Road export contracts.
United States
Commuter rail authorities in the Northeast Corridor face EPA effluent guideline tightening for ammonia and suspended solids discharge limits. Mobile vacuum extraction trucks are emerging as alternatives to fixed rail-servicing infrastructure at terminal stations. Chicago and New York metropolitan maintenance depots drive aftermarket demand for modular retrofit kits reducing installation downtime.
India
Indian Railways bio-digestion pilots in Rajdhani Express sleeper coaches align extended overnight routes with biological treatment horizons. CEA railway electrification mandates synchronize sanitary system replacements across newly electrified corridors. Tamil Nadu and Maharashtra rolling stock refurbishment centers are expanding capacity for vacuum system installations.
France
SNCF performance-based sanitation service contracts tie payments to system availability rates rather than scheduled interventions. EN 45545-2 fire safety compliance mandates halogen-free material construction for all new procurements. Île-de-France transit authorities unbundle component procurement from long-term maintenance through independent facility management consortia.
Sanitary Systems for Rail Transit Market Competitive Landscape
Concentration sits with diversified industrial conglomerates and specialized rail equipment suppliers rather than pure-play sanitary system vendors. The competitive structure spans three tiers: integrated braking and HVAC conglomerates offering vacuum waste modules as portfolio extensions; dedicated rail sanitation specialists with EN 45545-2 certification depth; and regional fabricators serving localized retrofit markets. Strategic moves center on modular platform standardization to reduce fleet deployment timelines and aftermarket service unbundling to capture recurring revenue streams.
Among Germany-based system integrators, Knorr-Bremse Systeme für Schienenfahrzeuge GmbH exemplifies the conglomerate-tier positioning with continental European market anchoring, while Roediger Vacuum GmbH and Dowaldwerke GmbH represent specialized engineering houses with vacuum technology heritage. Wabtec Corporation occupies the North American scale-driven position, and Guangdong Huatie Tongda High-speed Railway Equipment Corporation anchors Chinese domestic supply for high-speed fleet deployments. These archetypes reflect geographic clustering around regulatory certification requirements and manufacturing scale thresholds rather than technology differentiation alone.
| Leading Market Players |
|---|
| Wabtec Corporation |
| Guangdong Huatie Tongda High-speed Railway Equipment Corporation |
| Trainvac |
| Knorr-Bremse Systeme für Schienenfahrzeuge GmbH |
| EVAC |
| Roediger Vacuum GmbH |
| Dowaldwerke GmbH |
| Goko Seisakusho |
| Glova Rails |
| Others |
Pricing and Supply Chain Analysis
EN 45545-2 fire safety certification gates both supplier qualification and price differentiation simultaneously, as halogen-free material traceability documentation compresses procurement cycles and disqualifies incumbent suppliers lacking compliance depth. Rail operators face tiered cost structures where certified vacuum waste modules command substantial premiums over uncertified alternatives, while stainless steel and specialty polymer input volatility feeds directly into retention tank fabrication costs.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with EN 45545-2 HL3-certified halogen-free systems commanding the top tier and chemical toilet platforms occupying the budget segment. Price differentiation stems from certification grade and after-sales service bundling, with performance-based availability contracts in France and Germany adding recurring revenue premiums. Cost compression in the standard tier is intensifying because nickel-priced alloy volatility and REACH reformulation timelines extend qualification cycles. Regional rail operators in India and heritage railway services exhibit the highest price sensitivity, while high-speed rail authorities in China and European intercity networks prioritize certification reliability over unit cost.
Supply Chain Analysis
Strait of Hormuz transit underwrites specialty polymer feedstock flows for flame-retardant thermoplastics, though European vacuum waste module production clusters in Baden-Württemberg and the Pearl River Delta manufacturing bases in China dominate finished system output. Raw material dependencies center on nickel-priced stainless steel alloys, bromine-free flame retardants, and precision-molded sealing gaskets. Single-source vulnerability concentrates in German and French vacuum module fabrication capacity, exposing buyers to disruption during fleet-wide retrofit surges. Distribution runs through OEM-direct contracts for new rolling stock and independent facility management consortia for aftermarket service unbundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, as EN 45545-2 certification timelines and MEE effluent compliance create structural barriers that extend 12-18 months beyond typical product development cycles. Switching costs compound through fleet-wide standardization requirements and specialized technician scarcity that constrains depot service capacity.
For Market Incumbents: Fortify certification depth by accelerating halogen-free material validation pipelines ahead of REACH restriction expansions, while securing captive supply of nickel-priced alloys through backward integration into stainless steel fabrication. Capacity addition in Tamil Nadu and Maharashtra addresses Indian Railways electrification-linked demand surges. Threat from modular retrofit kit specialists demands channel control through maintenance depot partnerships that lock in aftermarket revenue streams. For New Entrants and Emerging Players: Anchor in bio-digestion technology for sleeper coach applications, where extended overnight routes in India and Russia enable 18-24 hour biological treatment horizons with limited incumbent penetration. White-space targets include Australian drought-mandated water recycling retrofits and US Northeast Corridor mobile vacuum extraction truck services as EPA effluent guidelines tighten. Go-to-market leverage rests on standardized drop-in platforms that compress installation downtime from weeks to days. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across water recycling technology segments as multi-stage membrane and activated carbon treatment systems require specialized manufacturing infrastructure. Long-term viability across the projection horizon favors suppliers with integrated vacuum waste module and treatment chemistry capabilities. Acquisition target archetype: specialized engineering houses with EN 45545-2 certification depth and established Deutsche Bahn or SNCF service relationships. Signal to watch: performance-based contracting penetration rates in French and German sanitation service tenders as unbundling accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Retrofit Platform Standardization | Reduces installation downtime from weeks to days for North American commuter authorities. |
| Backward Integration into Stainless Steel Fabrication | Secures captive supply of nickel-priced alloys amid commodity volatility in retention tank production. |
| Bio-Digestion Technology Certification | Unlocks Rajdhani Express sleeper coach deployments aligned with Indian Railways extended-route topography. |
| Performance-Based Service Contracting | Captures recurring revenue through SNCF-style availability-rate payment structures in European markets. |
| REACH-Compliant Material Reformulation | Accelerates qualification timelines for halogen-free sealing gaskets and tank linings ahead of regulatory deadlines. |
Research Methodology
Operator-level perspectives from fleet procurement directors, maintenance depot managers, rolling stock refurbishment specialists, and regulatory compliance officers anchored the qualitative base. Primary interviews combined with secondary validation from EPA effluent guideline filings, ECHA REACH restriction updates, MEE environmental rule publications, and Deutsche Bahn sustainability disclosures. Bottom-up unit economics across vacuum toilet, water recycling, and bio-digestion product categories triangulated against top-down rail operator capex projections.
Sensitivity analysis framed volume and value outputs across the projection horizon, with segmentation dimensions spanning product type, technology, application, and end user. Modeled variables included differential pressure specifications for altitude compensation, freshwater consumption targets per passenger kilometer, and fire safety certification tiers. CAGRs derived from fleet retrofit program timelines, electrification corridor expansion schedules, and regulatory compliance deadline clustering.
Underlying assumptions cover MEE effluent discharge standard enforcement consistency, EN 45545-2 HL3 certification timeline stability, and stainless steel alloy price band persistence, with deviation risk concentrated in REACH chemical restriction acceleration and Indian CEA electrification corridor prioritization shifts. Practitioners should keep alternative scenarios live as dual carbon goals implementation intensity and EPA guideline tightening trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Trams Market
Railway
South Korea Connected Rail Market
Railway
Locomotive Maintenance Market
Railway
Global Hyperloop Train Market
Railway
Europe Intermodal Terminals Market
Railway
Railway Engine Market
Railway
Heritage Railways Trains Market
Railway
Railway Track Market
Railway
Connected Rail Market
Railway
Locomotive Parking Brake Market
Railway
Latin America Connected Rail Market
Railway
Railway Bearing Market
Railway
Rail Brace Market
Railway
Train Exterior Lighting Market
Railway
Rail Damper Market
Railway
Train HVAC Market