
 Railroad Brake Shoe Market | 2026-2036
Railroad Brake Shoe Market Size, Share, and Industry Trends Forecast 2026-2036
Railroad Brake Shoe Market Insights
North American foundry capacity for rail friction products is broadening as domestic producers respond to reshoring incentives. Wabtec Corporation leverages its integrated braking systems portfolio to capture aftermarket replacement cycles across North American freight corridors. Knorr-Bremse sustains European engineering standards while extending manufacturing presence into Asian supply chains. Amsted Rail anchors its position through captive supply of cast steel components to major Class I railroads.
A railroad brake shoe is a friction device pressed against the wheel tread or disc to convert kinetic energy into thermal energy during deceleration, typically manufactured from cast iron, composite resin-bonded materials, or sintered steel formulations with specified coefficients of friction and thermal thresholds. Its primary purpose is to ensure controlled stopping distance for freight and passenger rolling stock under variable load and speed conditions. Composite materials segments are gaining traction as railroads pursue longer replacement intervals and reduced wheel wear compared to traditional cast iron alternatives. Heavy haul applications dominate volume demand due to extreme axle loads and frequent braking cycles on mountain-grade routes, while high-speed segments concentrate margin pools where specialized sintered formulations command technical premiums.
The Federal Railroad Administration enforces brake force compliance and thermal performance standards that directly shape product qualification requirements for suppliers serving US railroads. The EPA regulates particulate emissions from brake wear, pushing manufacturers toward low-copper and copper-free composite formulations in domestic production. China's NMPA and GB standards govern friction material imports, creating divergent certification pathways for multinational suppliers. Stakeholders must monitor evolving material restrictions and thermal performance benchmarks as regulatory fragmentation between North American and Asian compliance regimes intensifies sourcing complexity.
Market Dynamics
Composite friction materials are systematically displacing cast iron formulations across North American freight corridors, driven by FRA-mandated thermal performance thresholds and Class I railroad fleet renewal programs. This material transition reconfigures supplier qualification requirements and foundry capacity allocation.
Growth Catalysts
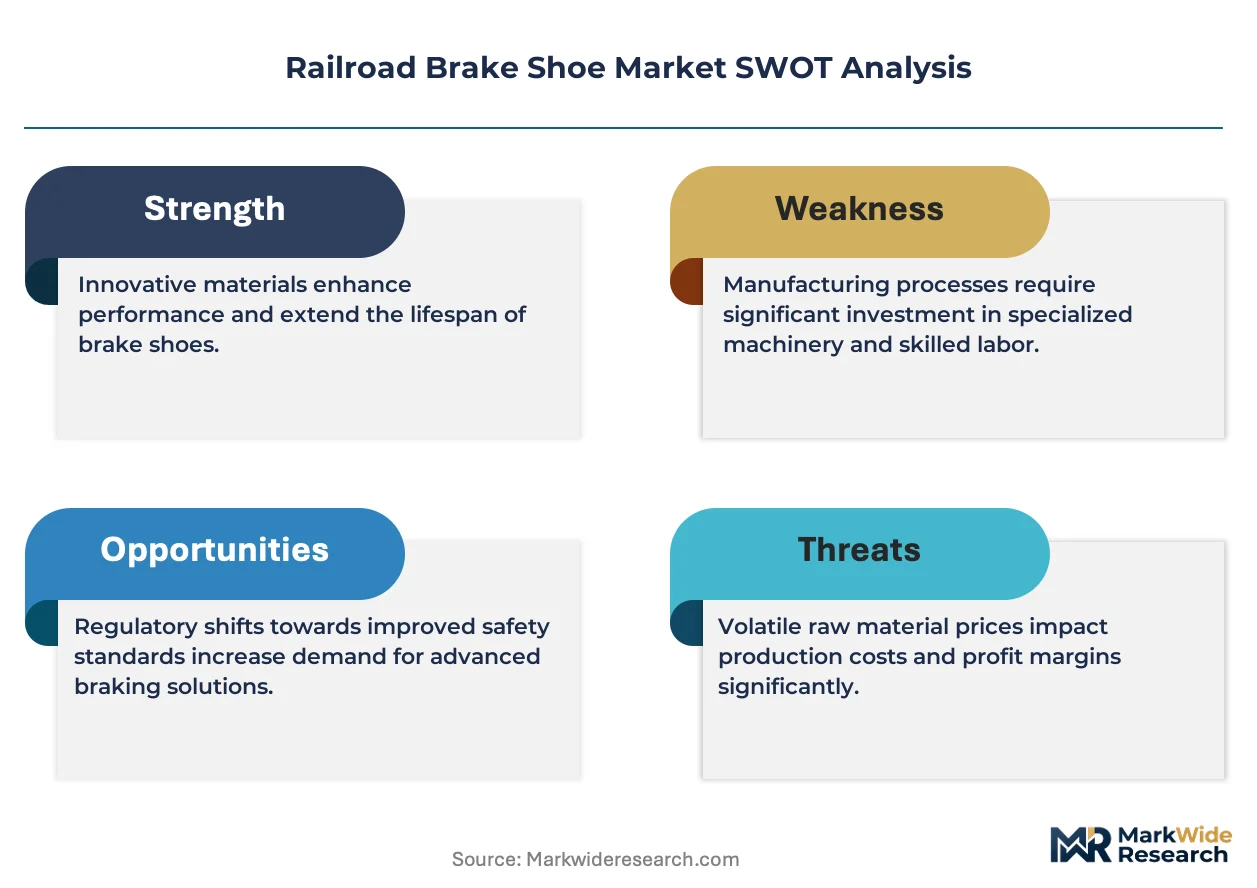
- EPA Particulate Mandates:Emissions regulations targeting brake wear dust push railroads toward low-copper composite formulations, accelerating material substitution cycles.
- Heavy Haul Axle Loads:Mountain-grade freight routes with extreme weight configurations generate concentrated friction material consumption from frequent braking cycles.
- Reshoring Incentives:Domestic production credits under US industrial policy broaden North American foundry capacity for rail friction products.
Market Restraints
- Pig Iron Volatility:Input cost swings for metallurgical raw materials compress margin predictability for cast iron brake shoe producers.
- Chinese Supply Concentration:Sintered steel formulation capacity clusters in Asian manufacturing hubs, creating import dependency for specialized grades.
- REACH Chemical Restrictions:European substance regulations complicate formulation flexibility for multinational suppliers serving dual compliance regimes.
Strategic Opportunities
- Copper-Free Formulations:Next-generation composite chemistry eliminates regulatory exposure while extending replacement intervals for freight operators.
- High-Speed Rail Certification:Sintered steel segments command technical premiums in passenger corridors requiring specialized thermal thresholds.
- Direct Fleet Contracts:Bypassing traditional distribution layers through captive supply agreements with Class I railroads captures full replacement cycles.
Industry Challenges
- FRA Qualification Timelines:Extended brake system certification protocols delay new material commercialization and lock in incumbent formulations.
- Legacy Wheel Compatibility:Composite shoe deployment requires coordinated tread profile management to prevent thermal damage to existing rolling stock.
- Formulation IP Fragmentation:Patent thickets around resin-bonded friction chemistry create licensing complexity for mid-tier compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railroad Brake Shoe Market |
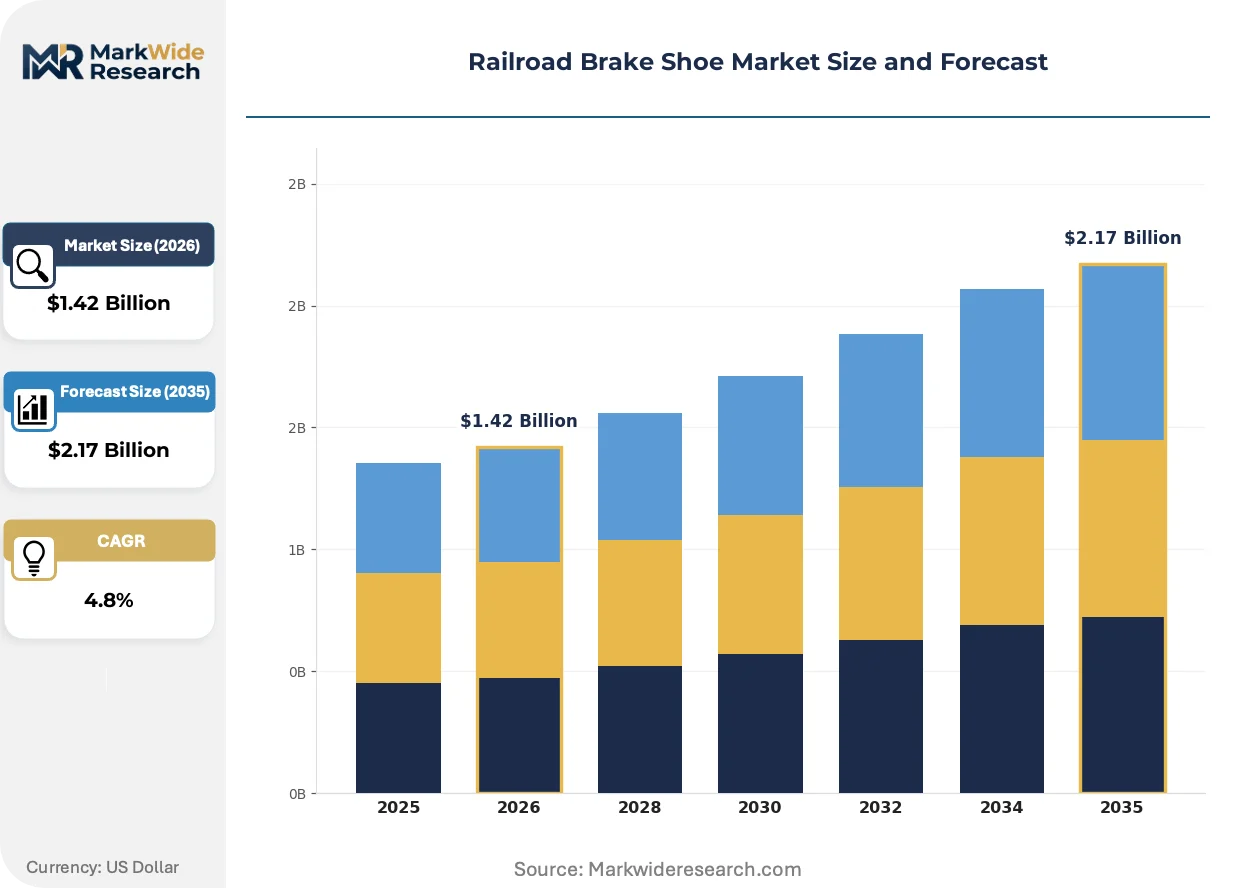
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Casting, Forging, Composite Materials, Steel End User: Freight Railroads, Passenger Rail, Maintenance of Way, Industrial Application: Heavy Haul, Intermodal, Light Rail, High-Speed Installation Method: Wheel Attach, Brake Assembly, Retrofits, OEM |
| Companies Covered | Knorr-Bremse, Wabtec Corporation, Akebono Brake Industry, Nabtesco Corporation, DAKO-CZ, CRRC, Becorit, Beijing Puran Railway Braking Technology Company Limited, Amsted Rail, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railroad Brake Shoe Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are converging to transform friction product specifications. Suppliers must simultaneously manage thermal performance validation and environmental compliance across divergent national standards.
Non-asbestos organic composites with ceramic reinforcement are expanding into heavy haul freight applications previously dominated by cast iron. BNSF Railway and Union Pacific have accelerated pilot programs on Powder River Basin coal routes. This penetration is expanding into aftermarket replacement cycles as railroads quantify wheel wear reduction and extended service intervals.
EPA copper-free mandates under the Clean Water Act are forcing reformulation of legacy friction materials across domestic production. The rule eliminates copper content thresholds for brake wear emissions by 2025. Suppliers serving California and Pacific Northwest corridors face the most compressed compliance timelines due to state-level water quality enforcement.
Class I railroads are consolidating brake shoe procurement through multi-year sole-source agreements that bundle friction materials with integrated braking system overhauls. Traditional aftermarket distributors lose volume to direct OEM-channel relationships. This concentration is most visible in Union Pacific and CSX maintenance-of-way programs across the Midwest and Southeast corridors.
Railroad Brake Shoe Market Segmentation
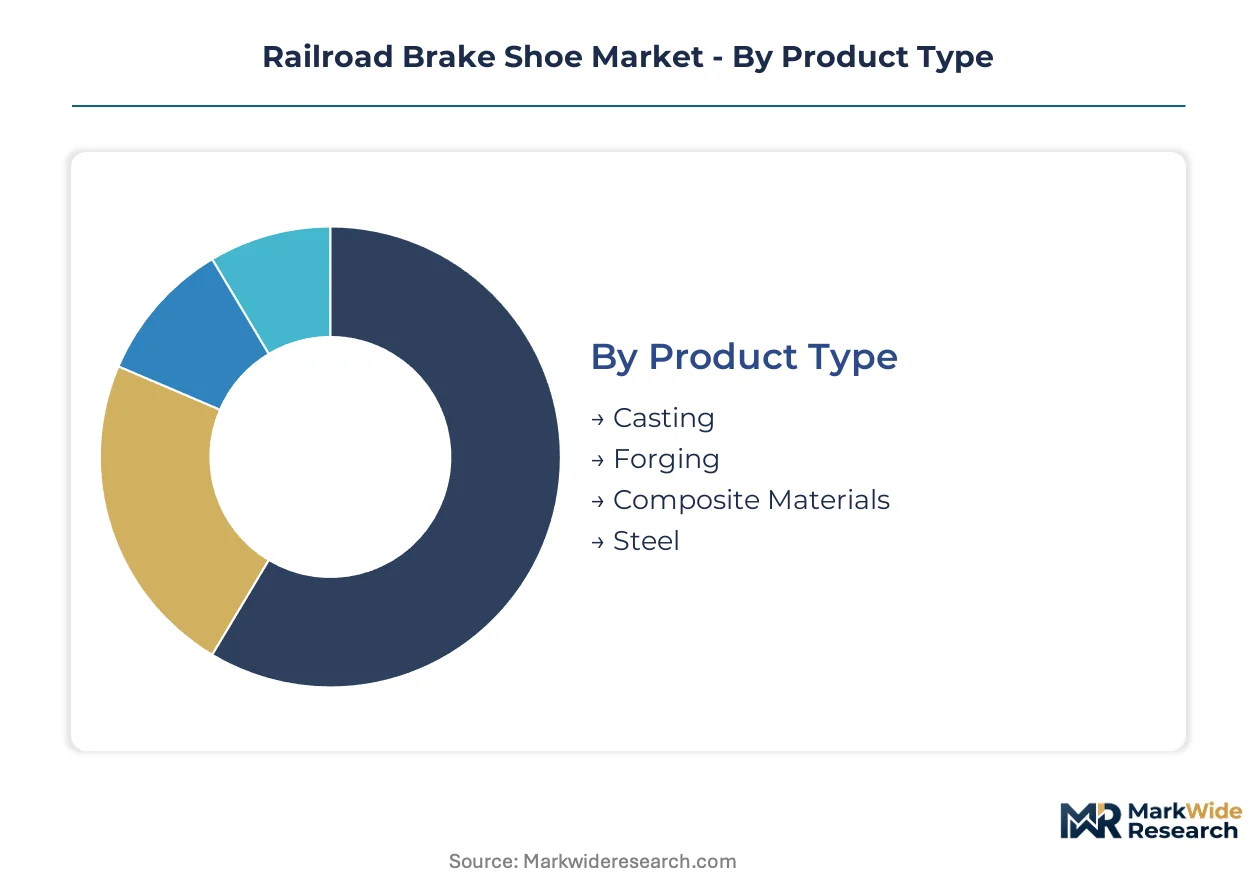
Material composition and operational intensity create distinct procurement patterns across railroad brake shoe categories. Fleet operators prioritize thermal performance thresholds and replacement interval economics when segmenting supplier relationships.
Product Type:
Cost tier differentiation separates commodity foundry outputs from engineered composite formulations requiring resin chemistry IP.
- Casting:Traditional gray iron formulations dominate replacement cycles for legacy freight fleets. Demand concentrates in United States Class I railroads maintaining aging rolling stock on secondary corridors where thermal stress remains moderate.
- Composite Materials:Resin-bonded friction elements with ceramic reinforcement extend service intervals 40-60% versus cast iron. United States heavy haul routes on mountain grades drive specification upgrades as Union Pacific and BNSF quantify wheel wear reduction.
- Forging:Pressed steel architectures serve specialized intermodal applications requiring uniform pressure distribution.
- Steel:Sintered metal formulations command technical premiums in high-speed passenger corridors.
Volume sits with Casting; growth tilts toward Composite Materials.
End User:
Application intensity and fleet scale determine procurement centralization versus distributed purchasing.
- Freight Railroads:Class I operators in the United States consume the majority of friction material volume through direct OEM-channel contracts. Mountain-grade routes with 286,000-pound axle loads generate extreme thermal cycling demands.
- Passenger Rail:Amtrak and regional commuter authorities specify sintered formulations for high-speed corridors. Northeast Corridor electrified operations prioritize consistent friction coefficients across variable weather conditions.
- Maintenance of Way:Track maintenance equipment requires specialized brake shoes for low-speed, high-torque applications.
- Industrial:Private mining and logging railroads purchase through aftermarket distributors with limited technical specification.
Procurement scale concentrates with Freight Railroads; specification complexity peaks with Passenger Rail.
Application:
Axle loading and braking frequency create divergent material durability requirements across operational profiles.
- Heavy Haul:Coal and ore movements on 2-3% grades subject brake shoes to sustained thermal stress. Powder River Basin routes in Wyoming and Montana represent the most intensive consumption geography for friction materials.
- High-Speed:Passenger corridors above 125 mph require sintered steel formulations with validated fade resistance. California and Texas emerging corridors drive certification demand for specialized thermal thresholds.
- Intermodal:Container stack trains with distributed braking systems balance wear across multiple axles.
- Light Rail:Urban transit systems prioritize low-noise composite formulations for community acceptance.
Consumption intensity clusters in Heavy Haul; margin expansion tracks with High-Speed.
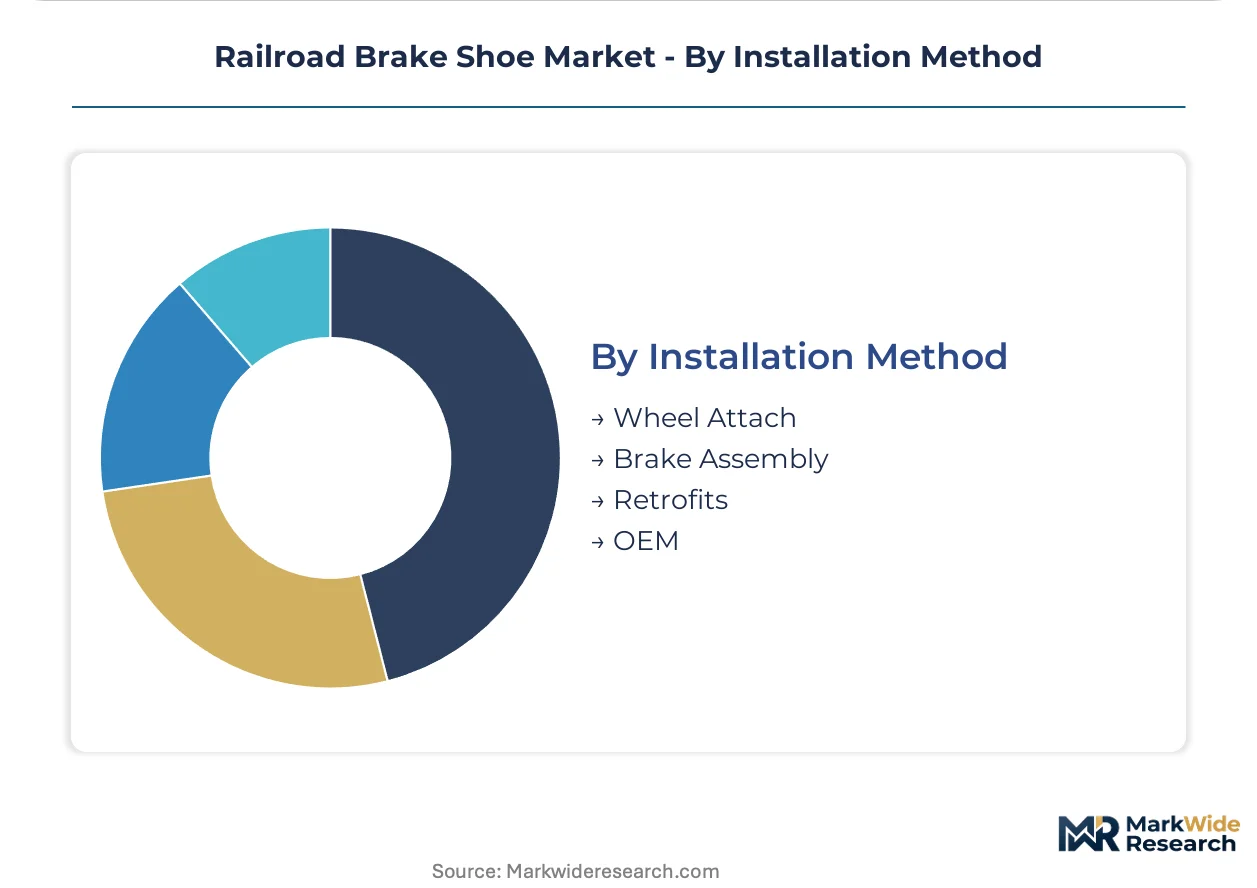
Installation Method:
Channel structure and technical integration depth separate captive supply relationships from aftermarket transactions.
- OEM:Wabtec and Knorr-Bremse integrate brake shoes with complete braking system packages for new rolling stock. United States locomotive and freight car builders specify qualified suppliers through multi-year sole-source frameworks.
- Wheel Attach:Direct shoe replacement on existing wheelsets requires compatibility validation with legacy tread profiles. Chicago and Los Angeles maintenance facilities handle high-volume replacement cycles.
- Brake Assembly:Caliper-integrated designs for disc applications demand precision machining tolerances.
- Retrofits:Composite material upgrades on cast iron-equipped fleets require FRA qualification protocols.
Revenue concentration flows through OEM; aftermarket expansion concentrates in Wheel Attach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pig iron foundries in the United States anchor North American friction material supply chains. Metallurgical coke from Pennsylvania and West Virginia feeds gray iron casting operations serving Class I railroads.
United States
Union Pacific and BNSF Railway drive composite brake shoe adoption across Powder River Basin coal routes. The Federal Railroad Administration mandates thermal performance thresholds under 49 CFR Part 232. Chicago and Los Angeles maintenance facilities handle the highest-volume replacement cycles for heavy haul fleets.
China
CRRC's integrated rail manufacturing base generates captive demand for sintered steel formulations. The NMPA and GB standards govern friction material imports through divergent certification pathways. Sichuan-Chongqing industrial clusters concentrate domestic brake shoe production for high-speed rail corridors.
Germany
Knorr-Bremse sustains European engineering standards for friction materials serving Deutsche Bahn passenger networks. REACH chemical restrictions complicate formulation flexibility for suppliers serving dual compliance regimes. Bavaria's industrial corridor anchors Continental European brake system R&D.
Japan
Nabtesco Corporation and Akebono Brake Industry supply precision friction components for Shinkansen operations. METI industrial policy supports domestic sintered steel capacity against import competition. Nagoya's Chubu manufacturing belt concentrates specialized brake system assembly.
India
Indian Railways' freight modernization program expands demand for cast iron brake shoes on legacy rolling stock. The Bureau of Indian Standards governs friction material specifications for domestic procurement. Maharashtra's Mumbai-Pune industrial corridor hosts emerging brake component fabrication.
Railroad Brake Shoe Market Competitive Landscape
Global majors compete with regional champions across integrated braking systems versus standalone friction materials. The vendor base clusters around three tiers: full-system integrators, specialized friction compounders, and captive foundry operations serving single railroads. Strategic archetypes include technology licensors, reshoring beneficiaries, and commodity foundry operators. Capacity expansion and direct fleet contracting represent the dominant competitive moves reshaping aftermarket channel structures.
Among Germany-based system integrators, Knorr-Bremse occupies a position exemplifying European engineering standards extended into Asian supply chains. Wabtec Corporation represents the North American integrated systems archetype, leveraging aftermarket replacement cycles across freight corridors. Amsted Rail anchors the captive supply model through in-house production of cast steel components for Class I railroads.
| Leading Market Players |
|---|
| Knorr-Bremse |
| Wabtec Corporation |
| Akebono Brake Industry |
| Nabtesco Corporation |
| DAKO-CZ |
| CRRC |
| Becorit |
| Beijing Puran Railway Braking Technology Company Limited |
| Amsted Rail |
| Others |
Pricing and Supply Chain Analysis
Composite resin-bonded chemistry migration is compressing foundry economics while concentrating procurement leverage among Class I railroads with direct OEM-channel volume. Pig iron volatility and EPA copper-free mandates simultaneously reshape input costs and supplier qualification barriers, locking margin pressure into domestic production.
Pricing Analysis
Service-bundling separates integrated braking system contracts from standalone friction material transactions, with Wabtec and Knorr-Bremse capturing premium positioning through multi-year overhaul packages. Three-tier pricing structure across premium sintered formulations, standard composite grades, and economy cast iron segments reflects certification tier and thermal performance thresholds. Cost compression in commodity foundry outputs is intensifying because metallurgical coke price swings transmit directly to gray iron brake shoe margins. Maintenance-of-way and industrial railroad segments exhibit highest price sensitivity, while high-speed passenger corridors prioritize fade resistance over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from Union Pacific and BNSF mandate qualified backup suppliers for all friction material grades, preventing single-source dependency on Wabtec or Amsted Rail captive operations. Geographic supply concentration centers on United States foundry capacity in Pennsylvania and West Virginia, Chinese sintered steel formulation clusters, and German engineering-grade resin chemistry. Raw material dependencies rest on metallurgical coke, ceramic reinforcement fibers, and copper-free friction modifiers. Tariff exposure on Chinese sintered steel imports creates supply chain risk for specialized high-speed grades. Distribution runs through direct fleet contracts consolidating volume away from traditional aftermarket distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domestic foundry capacity expansion lags composite formulation demand acceleration, propping supplier pricing power through extended FRA qualification timelines that constrain new entrant supply.
For Market Incumbents: Hedge against resin chemistry IP fragmentation by securing licensing positions with ceramic reinforcement patent holders before REACH chemical restrictions tighten. Add composite formulation capacity in Ohio or Indiana industrial corridors to capture reshoring incentives and reduce logistics exposure to Powder River Basin routes. Defensive consolidation of aftermarket distributor relationships prevents volume leakage to direct OEM-channel competitors. For New Entrants and Emerging Players: EPA copper-free mandates in the United States open a window for copper-free composite specialists to penetrate California and Pacific Northwest corridors ahead of compressed compliance timelines. Target maintenance-of-way equipment segments where technical specification requirements remain limited and procurement runs through aftermarket channels. Pursue FRA qualification partnerships with established brake system integrators to bypass extended certification protocols. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by full-system integrators seeking captive friction material supply. Long-term viability favors compounders with validated copper-free formulations and direct Class I railroad contract relationships. Watch composite brake shoe penetration rates on BNSF and Union Pacific heavy haul routes as the inflection signal for material substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Copper-Free Formulation Certification | EPA Clean Water Act compliance secures California corridor access before enforcement deadlines. |
| Direct Fleet Contracting | Union Pacific and CSX sole-source agreements bypass aftermarket distributors capturing full replacement cycles. |
| Foundry Capacity Expansion | Pennsylvania and Ohio metallurgical coke proximity reduces input cost volatility for gray iron production. |
| Resin Chemistry IP Licensing | Patent access from ceramic reinforcement holders unlocks heavy haul qualification for mid-tier compounders. |
| FRA Qualification Partnership | Collaborative testing with Wabtec or Knorr-Bremse accelerates commercialization timelines for new entrants. |
Research Methodology
Document review covered FRA brake system inspection protocols, EPA emissions rulemakings, and Class I railroad procurement disclosures, complemented by interviews with fleet maintenance directors at Union Pacific and BNSF, brake system procurement leads at Amtrak, foundry operations managers in Pennsylvania, composite formulation R&D directors, and aftermarket distribution channel heads. Secondary validation drew from SEC 10-K filings by Wabtec and Knorr-Bremse, Bureau of Transportation Statistics freight traffic data, and American Association of Railroads equipment reports. Bottom-up unit consumption models and top-down market sizing triangulated volume estimates across material segments.
Market value and unit volume outputs across the projection horizon reflect segmented modeling by material composition, end-user category, and application intensity. The analytical framework incorporated heavy haul route braking frequency data, high-speed corridor certification requirements, and maintenance-of-way equipment fleet counts. CAGRs were derived from replacement cycle analysis and fleet renewal program disclosures. Industry-specific inputs included FRA thermal performance threshold evolution and EPA copper-free mandate implementation timelines.
The model assumes a particular technology adoption path; alternative pathways for composite resin-bonded chemistry penetration would alter the outlook if cast iron foundries achieve cost parity through metallurgical coke price stabilization. Deviation in FRA qualification timeline compression or REACH chemical restriction expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Railway Digital Signal Axle Counters Market
Railway
Europe Intermodal Terminals Market
Railway
Gearbox for Rail Vehicles Market
Railway
Rail Brace Market
Railway
Tugger Trains Market
Railway
Rail Transit Traction Converter Market
Railway
Train Bogie Market
Railway
Automatic Train Control Market
Railway
Global High-Speed Train Seat Market
Railway
Railway Draft Gears Market
Railway
Rail Composites Market
Railway
Railway Braking System Market
Railway
Europe 40-Foot Platform Wagons Market
Railway
40-Foot Platform Wagons Market
Railway
Rail Bellows Market
Railway
Latin America Connected Rail Market