
 Rail Seat Market | 2026-2036
Rail Seat Market Size, Share, and Industry Trends Forecast 2026-2036
Rail Seat Market Analysis
A shortage of certified rail interior engineers is reorganizing supplier priorities across the value chain. Grammer AG leverages its European manufacturing footprint to sustain long-term contracts with state rail operators. Freedman Seating Company anchors North American transit authority bids through its domestic production base. Minda Industries Ltd. specializes in cost-optimized seating assemblies for emerging-market rolling stock programs.
Rail seats are structural interior components engineered to withstand cyclic loading, fire resistance per EN 45545 or equivalent national standards, and impact criteria defined by crashworthiness regulations, with primary purpose to secure passenger safety and comfort during transit operations. Composite materials lead seat construction for high-speed applications where weight reduction directly reduces energy consumption, while modular seat designs represent the fastest-growing configuration as operators seek flexible interior reconfiguration for peak versus off-peak service patterns. Standard designs still occupy the largest installed base across commuter fleets where replacement cycles extend beyond fifteen years.
Europe's ECHA enforces REACH restrictions on flame retardant chemistry, the US FRA mandates crash energy management for passenger equipment, and India's BIS certification governs seating material specifications for domestic railway procurement. These frameworks collectively raise compliance costs for suppliers while creating technical barriers that favor incumbents with established testing protocols. Stakeholders must monitor evolving fire safety thresholds and localization requirements as procurement authorities tighten domestic content rules.
Market Dynamics
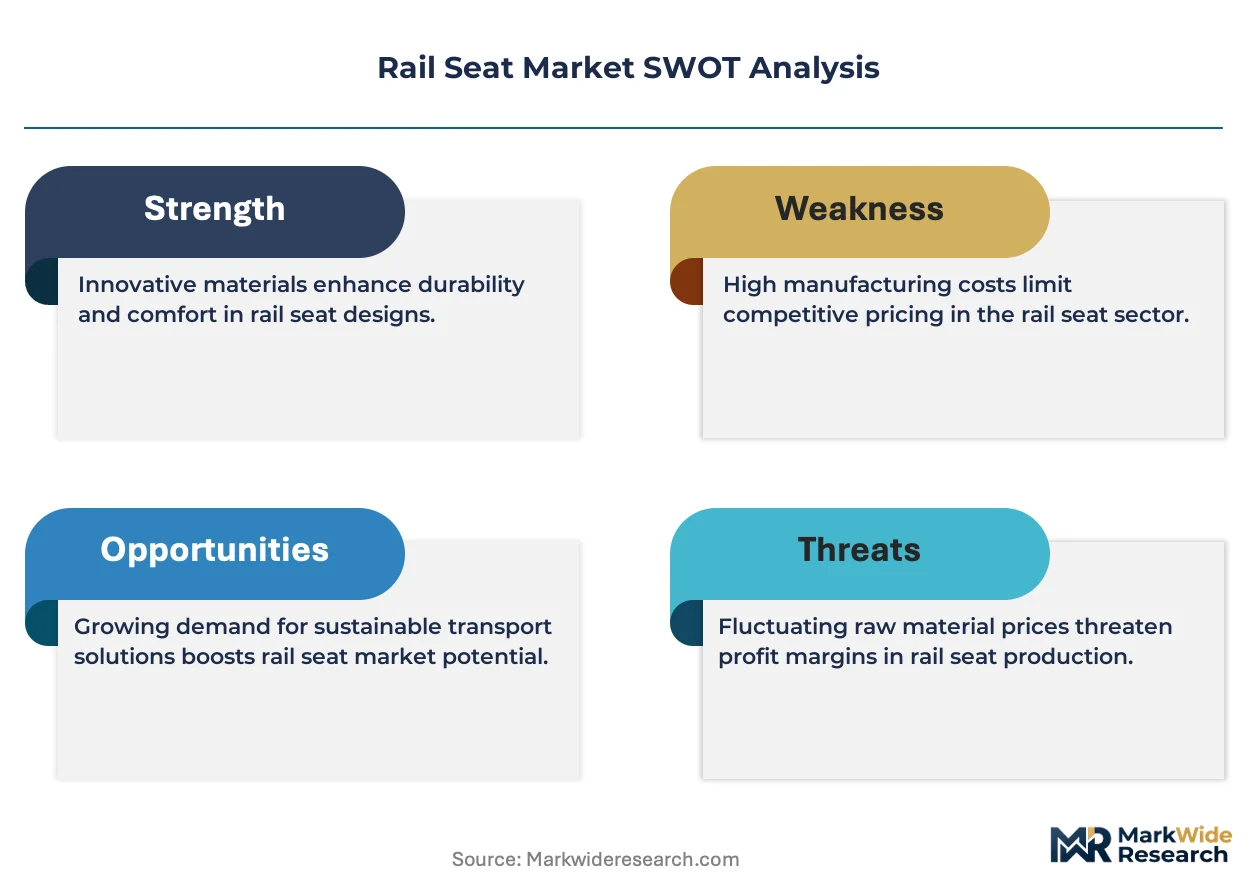
Fire safety compliance under EN 45545 and equivalent national standards is forcing material transitions across the rail seat supply chain, compressing margins for suppliers while elevating technical barriers to entry.
Growth Catalysts
- High-speed rail fleet expansion:Operators in China and Japan are placing multi-year orders for lightweight seating systems to support energy efficiency targets on new rolling stock lines.
- REACH flame retardant restrictions:ECHA enforcement is accelerating adoption of halogen-free composite materials among European seating manufacturers seeking sustained market access.
- Modular reconfiguration demand:Commuter rail authorities require rapid interior layout changes for peak-load management, driving specification of detachable seat platforms.
Market Restraints
- Raw material cost volatility:Glass fiber and specialized resin prices fluctuate with energy markets, squeezing margin predictability for composite seat producers.
- Supplier concentration risk:China's CRRC supply chain dominates high-volume seating procurement, limiting diversification options for tier-two subcontractors.
- Technical limitation in fire testing:Extended certification timelines for novel low-smoke materials delay product commercialization by 18-24 months.
Strategic Opportunities
- India's domestic procurement mandates:BIS certification requirements and localization rules create protected market space for indigenous seating assembly operations.
- Smart seat integration:Convergence of IoT sensors and composite structures enables real-time occupancy monitoring for predictive maintenance contracts.
- Refurbishment service channels:Direct operator partnerships for 15-year lifecycle seat renewal bypass traditional OEM distribution tiers.
Industry Challenges
- Certified engineer scarcity:Shortage of rail interior specialists with EN 45545 testing experience extends project timelines and inflates labor costs.
- Legacy fleet integration complexity:Retrofit seat designs must interface with obsolete mounting hardware, complicating engineering validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rail Seat Market |
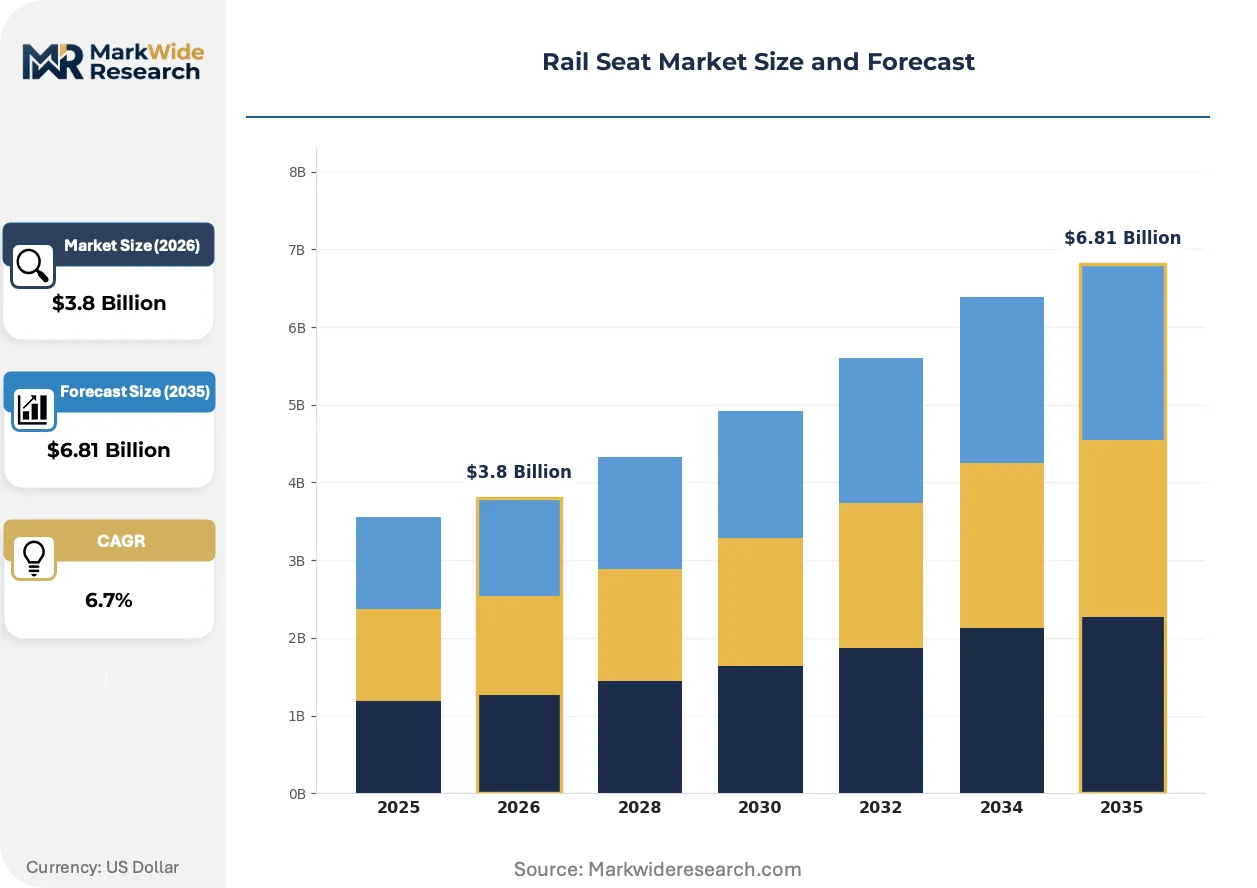
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Steel, Aluminum, Plastic, Composite Seat Design: Standard, Ergonomic, Modular, Foldable End User: Passenger Trains, Freight Trains, Light Rail, Metros Installation Type: Integrated, Bolt-On, Snap-In, Retrofit |
| Companies Covered | Grammer AG, Magna International Inc., Freedman Seating Company, Faurecia, Seats Incorporated, Minda Industries Ltd., Saira Seats, Transcal Holdings Ltd., Harita Seating Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rail Seat Market Emerging Trajectories
Material substitution and regulatory tightening are compressing traditional product lifecycles while creating openings for specialized compliance services and modular system architectures.
Low-smoke, zero-halogen thermoset composites are supplanting conventional polyurethane foam and PVC upholstery in high-speed applications. European operators specify these materials for new fleet orders to satisfy EN 45545-2 smoke density requirements. The transition is compressing demand for legacy flame-retardant chemistries and elevating compounders with certified polymer formulations.
REACH Annex XVII restrictions on halogenated flame retardants are restructuring supplier qualification protocols. ECHA enforcement actions have disqualified several incumbent material formulations from EU rail procurement. Seat manufacturers serving German and French state operators now prioritize suppliers with pre-validated REACH compliance dossiers.
Lifecycle service contracting is displacing discrete seat procurement across Nordic commuter authorities. Operators in Sweden and Norway now bundle seat supply with 20-year maintenance and replacement commitments. This model transfers obsolescence risk to manufacturers while locking in long-term revenue streams for vertically integrated seating specialists.
Rail Seat Market Segmentation
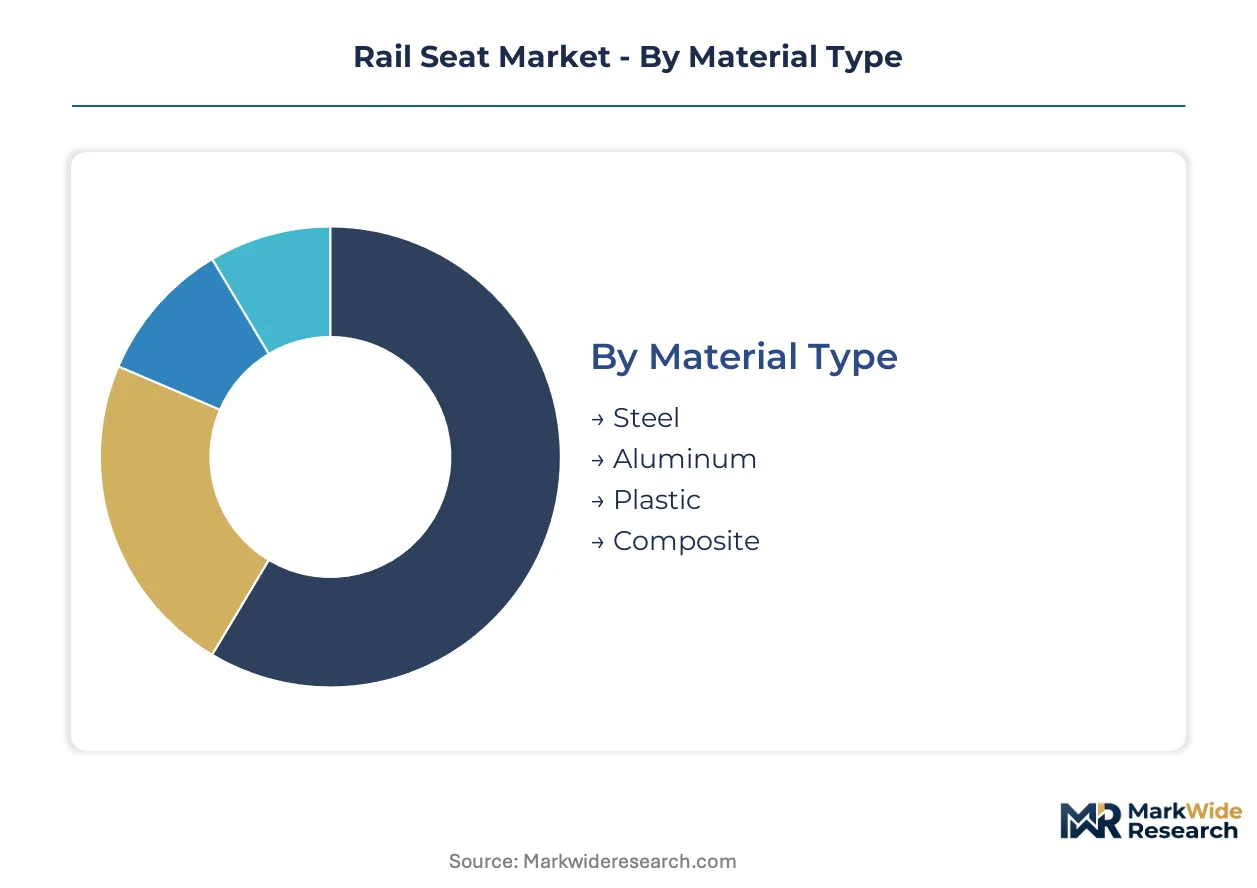
Rail seat procurement divides across material chemistry, structural configuration, and operational deployment. Each dimension carries distinct certification burdens and margin profiles that reshape supplier positioning.
Material Type:
EN 45545 fire safety tiers separate materials into compliance classes that determine market access across European procurement channels.
- Steel:Cold-rolled carbon and stainless grades dominate commuter rail installations where crashworthiness regulations mandate proven impact absorption. Indian Railways and Deutsche Bahn specify steel frames for high-density urban routes where replacement cycles exceed fifteen years.
- Aluminum:Extruded 6000-series alloys reduce seat mass by 40% versus steel equivalents, enabling energy efficiency gains on high-speed lines. Chinese CRRC procurement favors aluminum for new fleet orders connecting Beijing, Shanghai, and Guangzhou.
- Plastic:Glass-reinforced polypropylene serves cost-optimized regional train programs in Southeast Asia and Latin America.
- Composite:Low-smoke, zero-halogen thermoset laminates command premium positioning in European high-speed tenders governed by REACH Annex XVII restrictions.
Steel handles the majority of throughput; composite is climbing the fastest on share as fire safety standards tighten.
Seat Design:
Operator reconfiguration requirements are fragmenting demand between fixed installations and adaptable platforms.
- Standard:Fixed-back designs with molded polyurethane cushioning retain dominance across legacy commuter fleets where interior layouts remain static. These configurations minimize upfront capital outlay for state rail operators in Eastern Europe and South America.
- Ergonomic:Lumbar-adjustable seating with pressure-mapped foam distribution targets premium intercity services. Japan's JR East and France's SNCF specify ergonomic platforms for business-class carriages on competitive routes.
- Modular:Detachable seat platforms enable rapid interior reconfiguration between peak commuter density and off-peak comfort configurations. Nordic operators in Sweden and Norway now mandate modular specifications for lifecycle service contracts spanning twenty years.
- Foldable:Stowable seating accommodates wheelchair spaces and bicycle storage on mixed-use regional trains.
Standard designs anchor the installed base; modular platforms are expanding most quickly as fleet flexibility becomes a procurement priority.
End User:
Passenger density and journey duration dictate structural specifications across rolling stock categories.
- Passenger Trains:Intercity and high-speed services prioritize fire-rated composites and ergonomic adjustability for journeys exceeding three hours. China's expanding HSR network and India's Vande Bharat program drive concentrated demand for premium seating assemblies.
- Freight Trains:Crew cabin seating requires basic crash compliance without passenger-grade amenities. Russian Railways and North American Class I operators specify minimal configurations for locomotive cabs.
- Light Rail:Streetcar and tram systems favor lightweight aluminum and plastic constructions for frequent stop-start operations.
- Metros:High-density urban underground networks specify steel-framed, vandal-resistant platforms with anti-graffiti surface treatments.
Passenger trains generate the dominant revenue pool; metro specifications are gaining share fastest as urban rail expansion accelerates across developing economies.
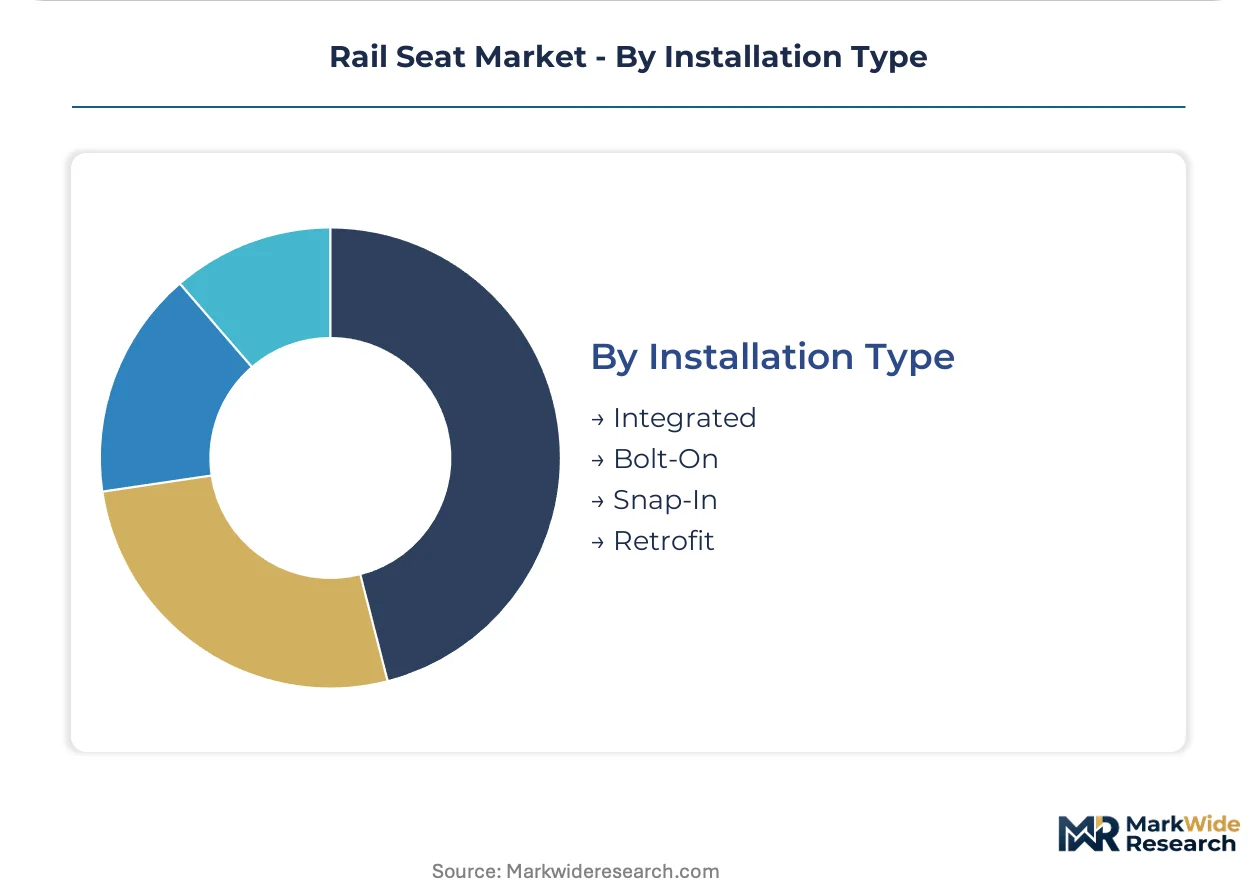
Installation Type:
Mounting methodology determines supplier technical support requirements and aftermarket revenue potential.
- Integrated:Seats welded or bonded directly to carbody structures during initial manufacturing. CRRC and Alstom favor integrated approaches for new-build high-speed trains to minimize weight and eliminate fastener fatigue points.
- Bolt-On:Mechanical fastening to pre-installed floor rails enables field replacement without structural modification. Deutsche Bahn and SNCF specify bolt-on standards for maintenance accessibility.
- Snap-In:Tool-free attachment systems support rapid reconfiguration for special event services and seasonal demand fluctuations.
- Retrofit:Adaptation kits interface with obsolete mounting hardware from 1990s-era rolling stock. British Rail Mark 3 carriage refurbishments and Amtrak Superliner renewals create protected demand for specialized engineering services.
Bolt-on platforms handle the majority of current procurement volume; retrofit specifications are expanding most quickly as lifecycle renewal contracts displace discrete seat sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in European procurement channels where EN 45545 certification creates technical barriers, while Asian manufacturers compete on scale within China's CRRC supply chain. This asymmetry reshapes supplier investment priorities across both regions.
China
CRRC Corporation anchors the world's largest rolling stock production base, driving concentrated demand for aluminum-framed seating assemblies on Beijing-Shanghai and Guangzhou-Shenzhen high-speed corridors. MIIT domestic content rules protect indigenous seating subcontractors from foreign competition. Qingdao and Changchun manufacturing clusters host tier-one seat fabricators supplying CRRC's export orders to Southeast Asia and Latin America.
Germany
Deutsche Bahn's multi-year fleet renewal program sustains premium demand for REACH-compliant composite seating with 20-year lifecycle service contracts. ECHA enforcement of Annex XVII flame retardant restrictions disqualifies non-compliant material formulations from federal procurement. KBA technical standards for crash energy management drive specification of steel-reinforced platforms on regional commuter routes through Bavaria and North Rhine-Westphalia.
India
Vande Bharat high-speed train expansion and metro rail projects in Mumbai, Delhi, and Bengaluru generate accelerating demand for fire-rated seating assemblies. BIS certification requirements and PLI scheme incentives create protected market space for domestic manufacturers. Tamil Nadu and Maharashtra industrial corridors host emerging seating fabricators serving Indian Railways' localization mandates.
United States
Amtrak's Superliner refurbishment program and transit authority fleet renewals sustain demand for bolt-on retrofit seating compatible with 1990s-era mounting hardware. FRA crashworthiness regulations mandate specific impact absorption criteria for passenger equipment. Chicago-based Freedman Seating Company anchors domestic production capacity for municipal transit bids across the Midwest and Northeast corridors.
Japan
JR East and JR Central prioritize ergonomic seating platforms for premium intercity services on competitive Tokyo-Osaka routes. METI energy efficiency standards drive lightweight aluminum specifications to reduce power consumption on Shinkansen networks. Nagoya and Osaka manufacturing basins concentrate specialized seating engineers with JIS fire testing certification experience.
Rail Seat Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure across the rail seat supply chain. European and North American incumbents dominate premium certification-intensive segments while Asian manufacturers capture high-volume standardized procurement. Three archetypes define the competitive landscape: vertically integrated seating specialists with lifecycle service capabilities, regional fabricators serving protected domestic markets, and tier-two subcontractors feeding OEM supply chains. Consolidation pressures favor M&A activity among mid-cap European players, while capacity expansion concentrates in India and Southeast Asia to serve localization mandates.
Among European-headquartered specialists, Grammer AG exemplifies the vertically integrated archetype with sustained state rail operator relationships, while Faurecia occupies a position within diversified automotive-interior groups extending into rail applications. Freedman Seating Company represents the geographically anchored regional fabricator model with domestic production-based procurement advantages. These three named entities illustrate the competitive positioning spectrum without exhausting the participant base.
| Leading Market Players |
|---|
| Grammer AG |
| Magna International Inc. |
| Freedman Seating Company |
| Faurecia |
| Seats Incorporated |
| Minda Industries Ltd. |
| Saira Seats |
| Transcal Holdings Ltd. |
| Harita Seating Systems Ltd. |
| Others |
Supply Flow & Price Mechanics
CRRC's Qingdao and Changchun manufacturing clusters operate at unit-cost floors that reshape competitive entry across the rail seat value chain. This scale concentration compresses margin structures for non-integrated suppliers while elevating technical compliance premiums in European procurement channels governed by ECHA REACH enforcement.
Pricing Analysis
Configured-to-order pricing for EN 45545-certified composite seating commands substantial premiums over standard steel-frame commuter configurations. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant European tenders from cost-optimized emerging-market procurement. Cost compression in standard aluminum frames is intensifying because CRRC's domestic content rules limit foreign supplier participation. State rail operators in Germany and France exhibit lowest price sensitivity due to lifecycle service contracting, while Southeast Asian regional operators prioritize capital efficiency over certification grade.
Supply Chain Analysis
Container availability constraints on Shanghai-Rotterdam and Shenzhen-Hamburg trade lanes are extending lead times for specialized resin compounds. Glass fiber supply concentrates in China, Germany, and the United States, while low-smoke thermoset formulations draw from Belgian and Dutch compounders. Single-source vulnerability in halogen-free flame retardant chemistry creates exposure to ECHA Annex XVII enforcement actions. Distribution runs through tier-one seating fabricators supplying CRRC, Alstom, and Siemens Mobility assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across fire safety standards is fragmenting procurement into certification-defined niches. Modular reconfiguration demand from Nordic commuter authorities creates specialized service-contract opportunities distinct from commodity seat supply.
For Market Incumbents: Compound certification depth in EN 45545 testing protocols to outpace emerging Asian competitors seeking European market access. Backward integration into low-smoke thermoset compounding defends margin position against REACH-driven material substitution. Priority investment in lifecycle service infrastructure captures 20-year renewal contracts displacing discrete procurement. For New Entrants and Emerging Players: Anchor in India's BIS-certified domestic supply chain to exploit PLI scheme protection and Vande Bharat fleet expansion. White-space concentration exists in retrofit adaptation kits for British Rail Mark 3 and Amtrak Superliner refurbishment programs. Go-to-market execution through direct operator partnerships bypasses entrenched OEM distribution tiers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated seating specialists with lifecycle service capabilities and pre-validated REACH compliance dossiers. Long-term viability favors acquisition targets combining modular platform engineering with established state rail operator relationships. Signal to monitor: ECHA enforcement acceleration dislodging incumbent material formulations from German and French federal procurement.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Certification | ECHA Annex XVII validation secures access to Deutsche Bahn and SNCF procurement channels. |
| Lifecycle Service Contracting | 20-year maintenance bundling transfers obsolescence risk from Swedish and Norwegian operators. |
| Retrofit Engineering Specialization | Mark 3 and Superliner adaptation kits create protected demand outside OEM supply chains. |
| Modular Platform Development | Detachable seat systems enable rapid reconfiguration for peak-load management across Nordic authorities. |
| Domestic Production Footprint | Indian PLI scheme incentives and BIS certification requirements protect indigenous assembly operations. |
Methodological Framework
Desk research of customs trade databases, rolling stock procurement registers, and ECHA regulatory filings preceded structured interviews with rail interior engineering directors, tier-one seating procurement managers, and composite material compounders. Primary fieldwork with CRRC supply chain coordinators and Deutsche Bahn technical specification teams validated secondary estimates. Bottom-up unit demand modeling triangulated against top-down fleet expansion projections from national rail authorities.
Variance decomposition across material type, seat design, and installation methodology segments isolated growth contribution by configuration category. Volume and value outputs reflect reconciliation between OEM order backlogs and operator refurbishment schedules throughout the forecast period. CAGRs derived from rolling stock delivery timelines and replacement cycle analysis incorporating EN 45545 regulatory phase-in assumptions.
Underlying assumptions cover stable ECHA enforcement intensity, continued MIIT domestic content protection in China, and CRRC export order momentum, with deviation risk concentrated in raw material cost volatility and certified engineer availability constraints. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Automatic Train Control Market
Railway
Rail Brace Market
Railway
Global Train Lighting Market
Railway
Railway Buffer Stops Market
Railway
Hydrogen Fuel Cell Train Market
Railway
Global Train Brake Market
Railway
Global Hyperloop Train Market
Railway
France Rail Freight Transport Market
Railway
Rail Glazing Market
Railway
Railcar Vehicle Toilet Market
Railway
Rail Bellows Market
Railway
Electro-Pneumatic Train Brakes Market
Railway
India Rail Freight Transport Market
Railway
Railway Track Market
Railway
Smart Railways Market
Railway
Railway Digital Signal Axle Counters Market