
 Global High-Speed Train Seat Market | 2026-2036
Global High-Speed Train Seat Market Size, Share, and Industry Trends Forecast 2026-2036
Global High-Speed Train Seat Market Analysis
Urban transit authorities are broadening their procurement scope beyond intercity corridors into commuter high-speed networks. Hitachi leverages its integrated rail systems expertise to bundle seat supply with rolling stock platforms. Grammer AG anchors European manufacturing through specialized automotive-to-rail seating adaptation capabilities. Alstom competes on modular interior architectures that reduce per-car outfitting time.
High-speed train seats are engineered passenger accommodation systems built to withstand sustained velocities exceeding 250 km/h, incorporating fire-retardant foam cores, anti-vibration mountings, and crashworthy aluminum or composite frames designed for rapid evacuation compliance. The primary purpose is occupant safety and comfort across extended journeys at speeds incompatible with conventional seating geometries. Standard seats occupy the volume base across operator fleets globally, while business and first-class configurations command concentrated margin pools through premium upholstery and powered adjustment features. Modular seating designs are gaining fastest traction as operators prioritize reconfigurable cabin layouts for peak-demand flexibility.
Europe's ECHA REACH framework and the EU's F-Gas Regulation constrain foam and synthetic material selection, pushing suppliers toward bio-based alternatives and recycled polymer streams. China's MIIT mandates GB-standard fire performance and electromagnetic compatibility testing that filter market access for non-domestic seat producers. Japan's METI JIS standards enforce ergonomic benchmarking that shapes R&D allocation among tier-one suppliers. Stakeholders must monitor diverging material compliance timelines across these jurisdictions when locating regional production footprints.
Market Dynamics
China's MIIT rail modernization mandates and Japan's METI decarbonization directives are compressing procurement cycles across Asia-Pacific corridors, forcing seat suppliers to accelerate fire-retardant foam certification and electromagnetic compatibility testing timelines.
Growth Catalysts
- MIIT Fleet Expansion Mandates:China's GB-standard fire performance requirements are pulling demand for crashworthy aluminum-frame seating systems across CRRC-led corridor buildouts.
- India's Dedicated Freight Corridor:Linked passenger rail expansions are generating tender volumes for modular, reconfigurable cabin layouts in high-speed commuter segments.
- Bio-Based Foam Substitution:Europe's ECHA REACH framework is redirecting R&D spend toward recycled polymer streams and plant-derived cushioning cores.
Market Restraints
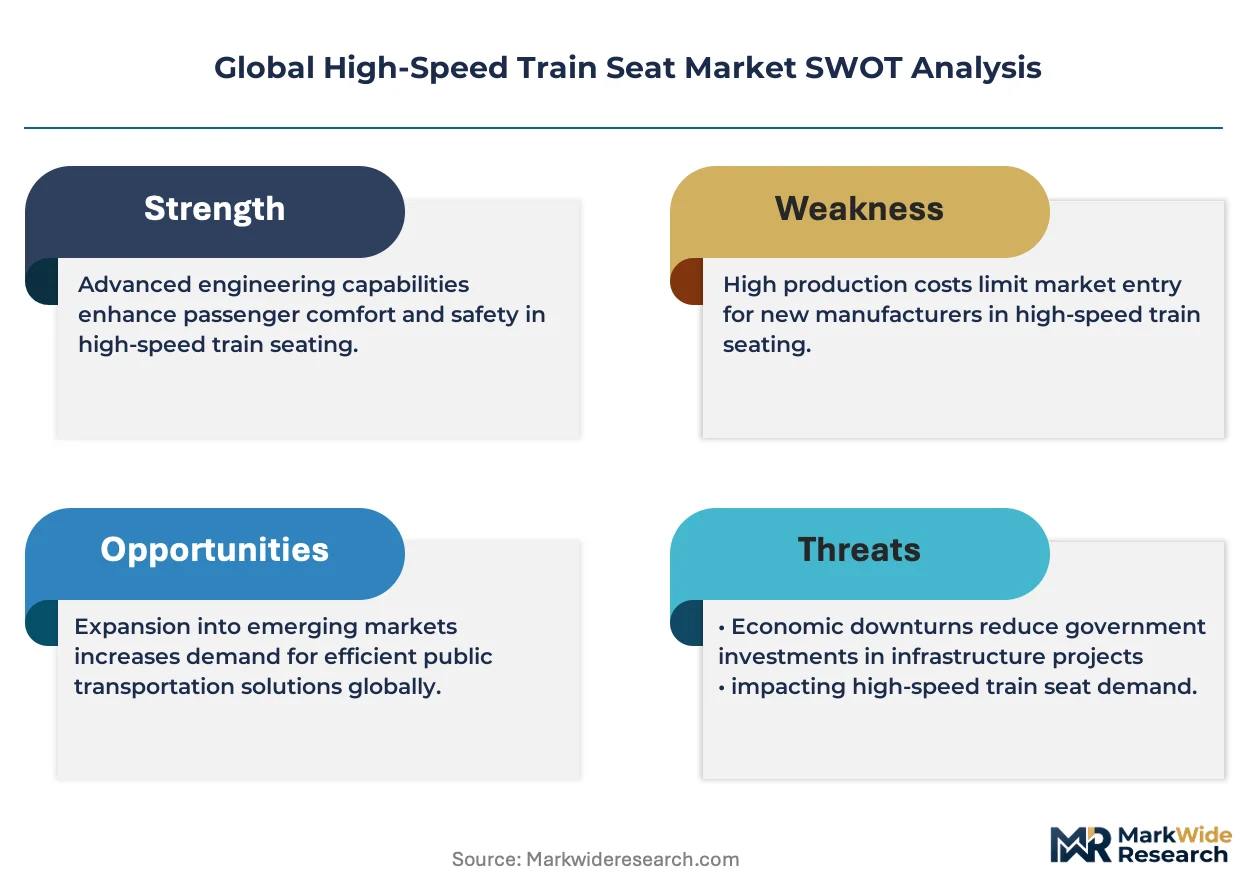
- Aluminum Alloy Price Volatility:Crashworthy frame production faces input cost pressure from aerospace-sector competition for high-strength aluminum grades.
- East Asian Supply Concentration:Fire-retardant textile weaving and foam core molding capacity clusters in China and South Korea, creating single-source exposure.
- JIS Ergonomic Benchmarking:Japan's METI standards enforce multi-year certification timelines that filter non-domestic producers from premium cabin segments.
Strategic Opportunities
- Southeast Asia Greenfield Networks:Vietnam and Indonesia's nascent high-speed rail programs lack established seat supplier relationships, opening first-mover positioning.
- EU F-Gas Regulation Tailwind:Synthetic foam phase-out mandates are accelerating procurement of bio-based seating systems in German and French rolling stock renewals.
- Digital Twin Integration:Seat-mounted IoT sensors are converging with predictive maintenance platforms, creating recurring revenue streams beyond hardware supply.
Industry Challenges
- Multi-Jurisdiction Certification Burden:Suppliers must parallel-track GB-standard testing for China, JIS benchmarking for Japan, and REACH compliance for Europe.
- Legacy Fleet Retrofit Complexity:Older rolling stock platforms require structural floor modifications to accommodate anti-vibration mounting systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High-Speed Train Seat Market |
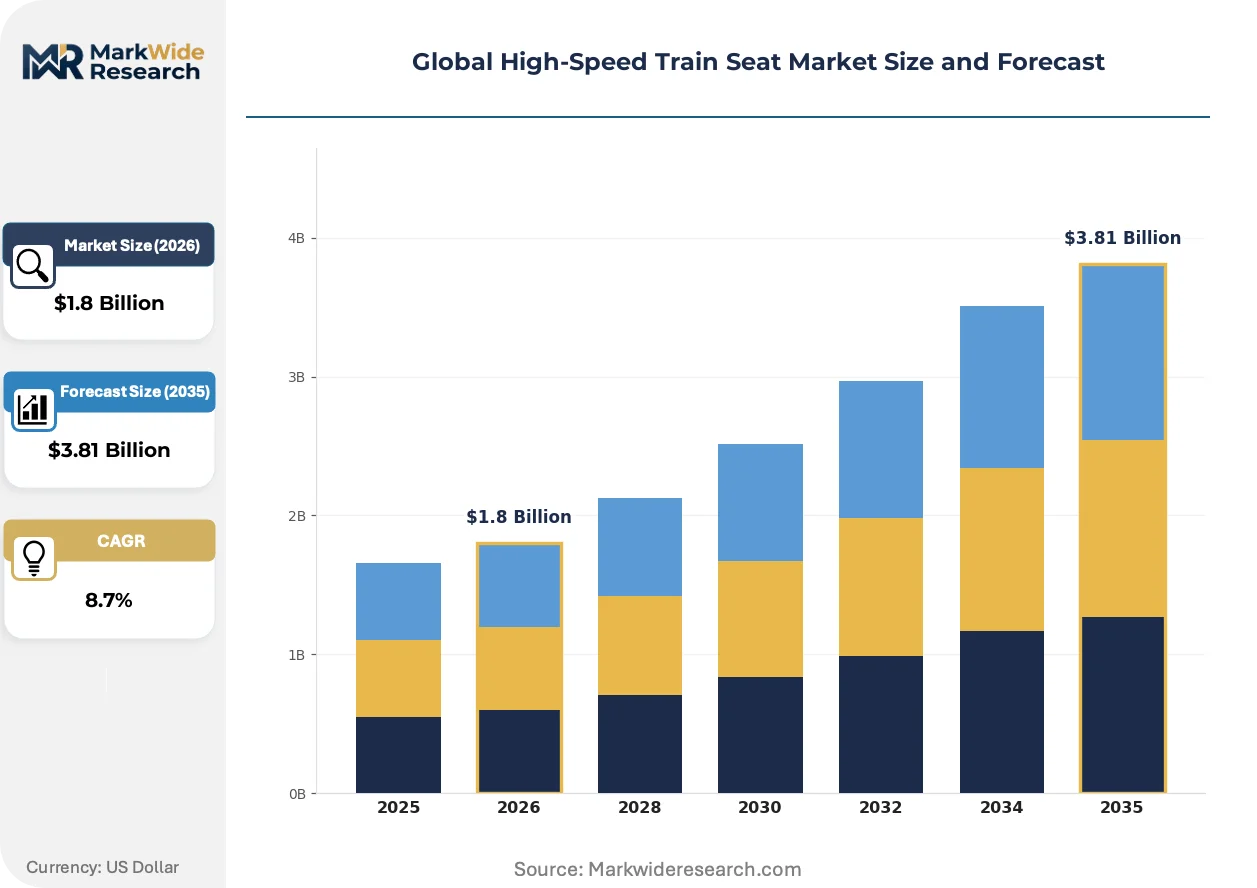
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Seats, Business Seats, First-Class Seats, Premium Seats Material: Leather, Fabric, Foam, Plastic End User: Rail Operators, Transport Authorities, Private Operators, Contractors Design Feature: Reclining Seats, Ergonomic Design, Modular Seating, Child Safety Features |
| Companies Covered | Hitachi, Grammer AG, Alstom, Faurecia Automotive Seating, Magna International Inc., Siemens, CRRC Corporation, Kawasaki Heavy Industries, Bombardier, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High-Speed Train Seat Market Emerging Trajectories
Active materials integration and predictive cabin systems are compressing the traditional hardware-only supplier model toward software-enabled seating platforms with embedded diagnostics.
Shape-memory alloy actuators are converging with powered adjustment mechanisms to enable lighter, faster-responding seat position controls. European operators in Germany and France are piloting these systems in business-class configurations. This convergence is compressing the weight-to-function ratio that has constrained premium cabin density.
Europe's F-Gas Regulation is phasing down hydrofluorocarbon-based foam blowing agents, forcing reformulation of fire-retardant cushioning cores. Seat producers are redirecting compound development toward water-blown and hydrocarbon alternatives. German KBA-type approval processes are extending by six to nine months as suppliers validate new foam thermal stability.
Operators are unbundling seat supply from rolling stock procurement, creating direct vendor relationships separate from trainset OEMs. French and Italian rail authorities now issue standalone seating tenders for interior refresh cycles. This pattern is most visible in Western Europe where fleet ages exceed fifteen years and cabin retrofit frequency is accelerating.
Global High-Speed Train Seat Market Segmentation
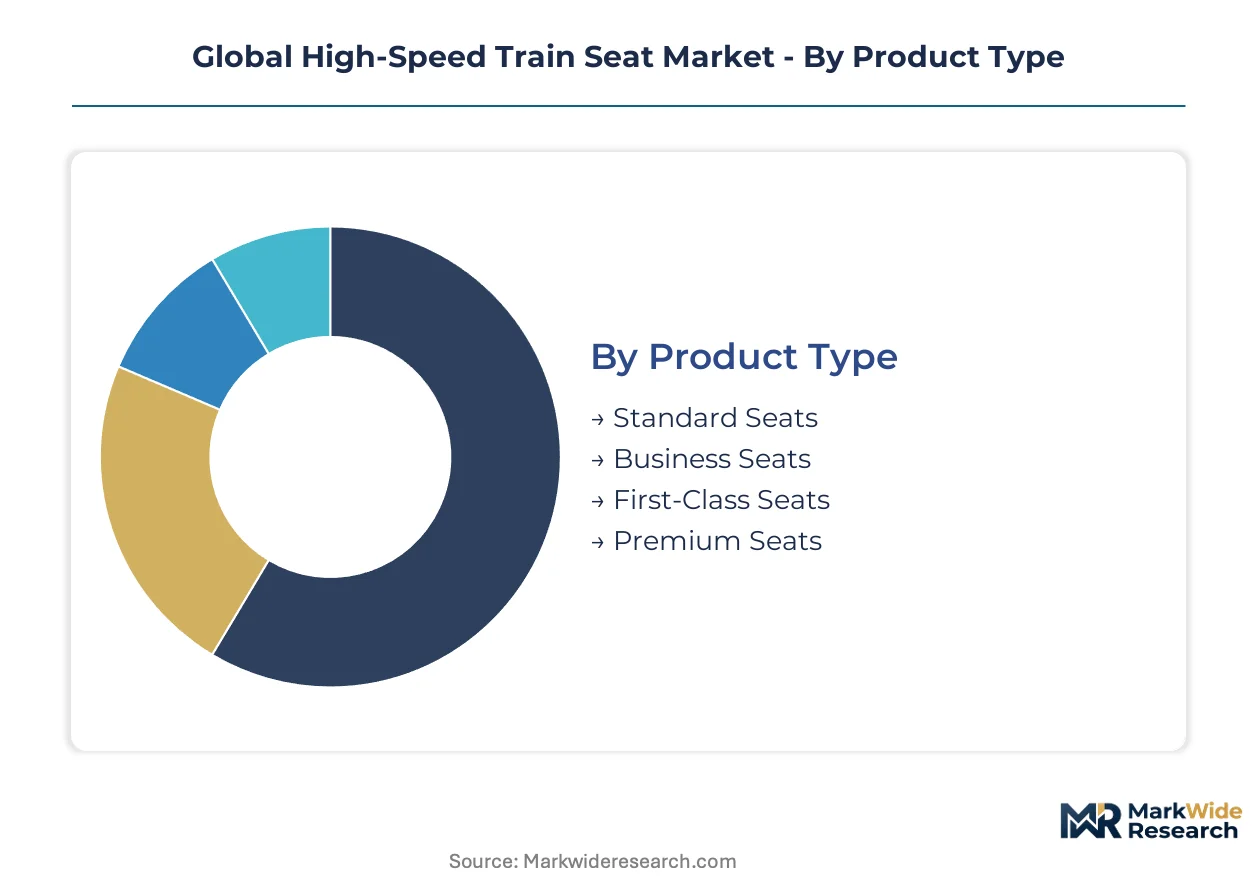
Seat procurement in high-speed rail diverges sharply across operator business models, with intercity corridors prioritizing premium density and commuter networks demanding rapid reconfiguration flexibility. Material selection and fire-safety certification requirements further fragment supplier targeting strategies across regional regulatory regimes.
Product Type:
Operator revenue models dictate cabin configuration investments, with yield-management systems directly linking seat mix to ticket pricing algorithms.
- Standard Seats:High-density polyurethane foam cores with fire-retardant polyester upholstery dominate volume procurement across CRRC and Alstom trainset deliveries. China's MIIT-mandated fleet expansions concentrate demand here, though margin compression from aluminum frame cost volatility constrains supplier profitability.
- Business Seats:Powered adjustment mechanisms with memory-foam cushioning and extended pitch dimensions command dedicated tender streams from French and German rail authorities. Japan's METI JIS ergonomic benchmarking filters non-domestic producers from this segment, creating protected margin pools for certified suppliers.
- First-Class Seats:Lie-flat configurations with composite shell structures and integrated entertainment mountings.
- Premium Seats:Limited-deployment luxury cabins with bespoke upholstery and concierge service integration.
Standard seats lead on scale; business seats lead on momentum.
Material:
Regulatory phase-outs of synthetic compounds are redirecting compound development timelines and supplier qualification pathways.
- Leather:Full-grain hides with moisture-resistant surface treatments persist in premium cabin segments despite ECHA REACH pressure on tanning chemistry. Italian and French operators maintain procurement of aviation-grade leather for first-class configurations, though bio-alternative testing is accelerating.
- Fabric:Woven aramid and wool-blend upholstery with inherent fire resistance dominates standard-class applications across European rolling stock renewals. Germany's KBA-type approval processes for new textile formulations extend supplier lead times by six to nine months.
- Foam:Reformulated water-blown polyurethane cores replacing hydrofluorocarbon-blown alternatives under F-Gas Regulation mandates.
- Plastic:Glass-fiber-reinforced polyamide shell structures for seat back and pan assemblies.
Fabric commands installed base volume; foam substitution is climbing the fastest.
End User:
Procurement centralization versus fragmentation shapes contract scale and technical specification complexity.
- Rail Operators:State-backed entities like SNCF, Deutsche Bahn, and JR East issue multi-year fleet-wide seating tenders with embedded maintenance clauses. China's CRRC-led corridor buildouts generate the largest single-source contract volumes globally, though payment terms extend 24-36 months.
- Transport Authorities:Urban transit bodies in London, Paris, and Tokyo are unbundling seat supply from rolling stock OEMs for interior refresh cycles. This pattern concentrates in Western Europe where fleet ages exceed fifteen years and cabin retrofit frequency is accelerating.
- Private Operators:Virgin Trains and Italo issue smaller, higher-margin tenders with accelerated customization requirements.
- Contractors:Third-party fleet maintenance providers sourcing replacement seats for damage and wear cycles.
Rail operators lead on contract scale; transport authorities lead on procurement pattern disruption.
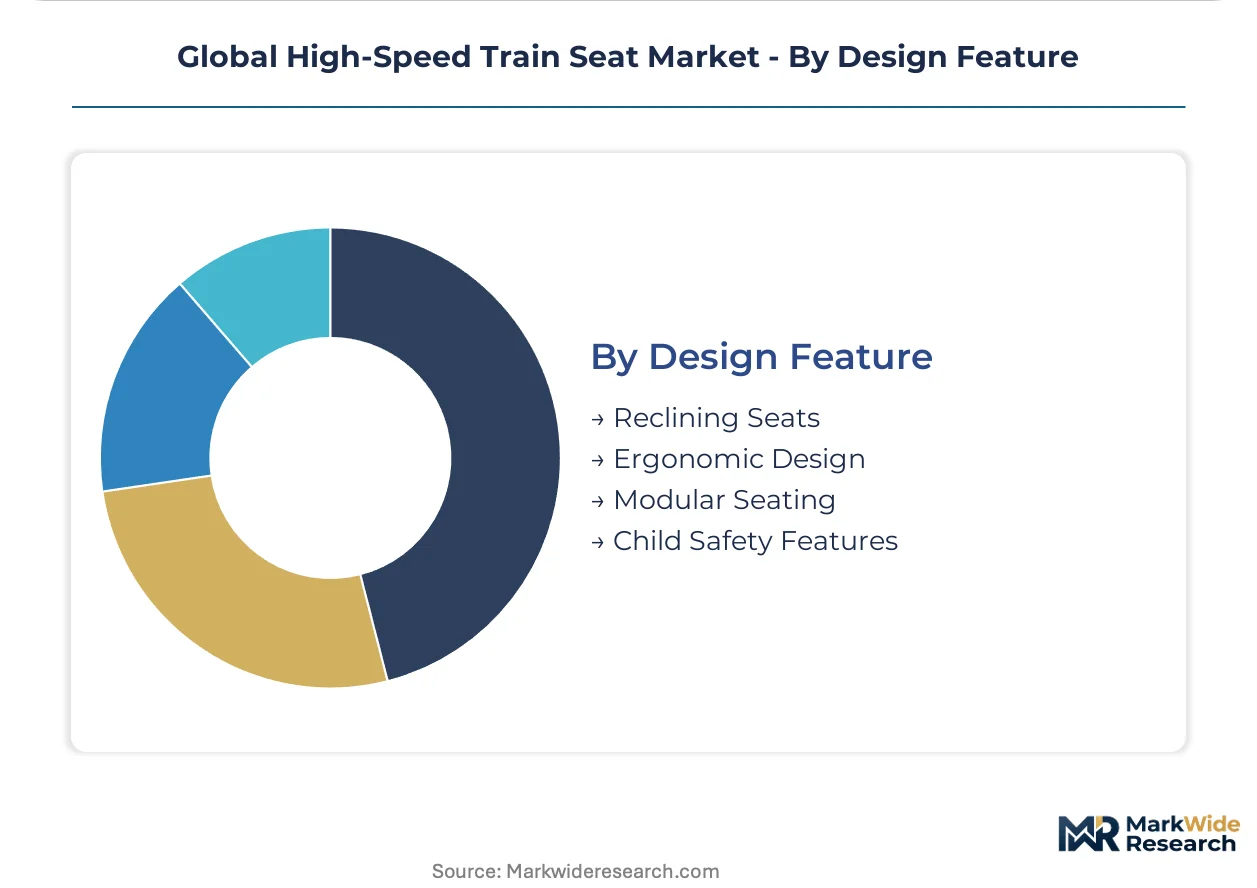
Design Feature:
Passenger experience metrics and evacuation compliance requirements compete for engineering priority in seat development roadmaps.
- Modular Seating:Rapid-release floor mounting systems enabling same-day cabin reconfiguration between commuter and intercity layouts. Indian Dedicated Freight Corridor-linked passenger expansions are generating tender volumes for this capability, as operators prioritize peak-demand flexibility over fixed seating density.
- Ergonomic Design:Pressure-mapping-optimized contours with adjustable lumbar support meeting Japan's METI JIS benchmarking standards. Certification timelines here filter speculative entrants and anchor incumbent supplier relationships in East Asian premium segments.
- Reclining Seats:Pneumatic or electromechanical tilt mechanisms with anti-pinch safety interlocks.
- Child Safety Features:Integrated restraint anchor points and impact-absorbing side wings.
Modular seating leads on technology momentum; ergonomic design leads on certification barrier height.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting seat production toward jurisdictions with streamlined certification pathways. Suppliers now locate molding and assembly capacity where fire-retardant foam testing timelines compress procurement cycles. This migration pattern concentrates investment in corridors with state-backed fleet expansion mandates.
China
MIIT-mandated corridor buildouts generate the largest contract volumes globally. GB-standard fire performance and electromagnetic compatibility testing filter non-domestic producers from CRRC-led tenders. Qingdao and Changchun anchor composite frame manufacturing clusters serving domestic high-speed networks.
Germany
Deutsche Bahn's rolling stock renewal programs drive demand for modular reconfigurable seating. KBA-type approval processes for new foam formulations extend supplier lead times by six to nine months. Bavaria hosts specialized automotive-to-rail adaptation facilities leveraging existing upholstery expertise.
Japan
METI decarbonization directives compress procurement cycles across JR East and JR Central fleets. JIS ergonomic benchmarking enforces multi-year certification timelines that protect domestic suppliers in premium cabin segments. Nagoya and Osaka concentrate precision actuator and memory-foam component production.
India
Dedicated Freight Corridor-linked passenger expansions generate tender volumes for rapid-release floor mounting systems. BIS fire-safety standards are converging with European norms to accelerate foreign supplier qualification. Gujarat and Maharashtra are emerging as assembly hubs for modular commuter seating.
France
SNCF's unbundled interior refresh tenders separate seat supply from rolling stock OEM contracts. ECHA REACH constraints on synthetic tanning chemistry push upholstery suppliers toward bio-alternative validation. The Île-de-France region concentrates design-engineering capacity for business-class powered adjustment systems.
Global High-Speed Train Seat Market Vendor Landscape
Strategic partnerships dominate the current landscape as seat suppliers bundle hardware with predictive maintenance platforms. The vendor base clusters into three tiers: integrated rail systems providers, specialized seating fabricators, and automotive crossover adaptors. Two strategic archetypes predominate: full-service rolling stock integrators leveraging captive seat supply, and component specialists capturing unbundled refresh tenders. M&A activity and geographic licensing agreements represent the primary competitive vectors.
Within the integrated systems tier, Hitachi and Siemens exemplify full-service positioning through bundled rolling stock and interior platform offerings. Grammer AG occupies a distinctive position as an automotive seating specialist pivoting railward through acquired expertise in crashworthy frame adaptation. CRRC Corporation anchors the state-backed tier, representing production scale advantages tied to domestic corridor buildouts. Alstom sits within the modular architecture specialist category, its competitive position tied to reduced per-car outfitting time value propositions.
| Leading Market Players |
|---|
| Hitachi |
| Grammer AG |
| Alstom |
| Faurecia Automotive Seating |
| Magna International Inc. |
| Siemens |
| CRRC Corporation |
| Kawasaki Heavy Industries |
| Bombardier |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between JIS-compliant premium seating and GB-standard commodity frames splits both pricing power and supplier geography. Japan's METI-mandated ergonomic benchmarking commands 40-60% price premiums over standard-class equivalents, while China's MIIT fire-performance requirements compress margins through accelerated testing timelines. This divergence channels procurement toward domestic-certified incumbents in premium tiers and cost-optimized regional assemblers in volume segments.
Pricing Analysis
Direct-to-OEM discount structures dominate high-speed train seat procurement, with rolling stock manufacturers capturing 15-25% channel margins on bundled interior packages. Three-tier pricing structure across premium, standard, and economy levels reflects certification tier and after-sales service bundling. Cost compression in standard-class aluminum frames is intensifying because aerospace-sector competition for high-strength alloys drives input volatility. State-backed rail operators in China and India exhibit lowest price sensitivity due to multi-year fleet mandates, while private operators in Western Europe negotiate hardest on per-unit economics.
Supply Chain Analysis
Regional distribution centers in Qingdao, Nagoya, and Bavaria anchor hub-and-spoke fulfillment patterns for fire-retardant foam cores and crashworthy frame assemblies. Manufacturing concentrates in China, Japan, and Germany, with fire-retardant textile weaving capacity clustering in China and South Korea. Raw material supply draws from high-strength aluminum smelters, polyurethane compounders, and aramid fiber producers. Single-source vulnerability in East Asian foam core molding creates exposure to geopolitical disruption. Distribution runs through captive OEM logistics networks and specialized rail-component distributors serving refresh-cycle demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global High-Speed Train Seat Market compounds steadily through state-backed fleet renewal mandates that institutionalize multi-year procurement visibility. Infrastructure decarbonization targets across Asia-Pacific and Europe cement replacement demand regardless of cyclical passenger traffic fluctuations.
For Market Incumbents: Deepen backward integration into fire-retardant foam compound development to offset F-Gas Regulation reformulation costs and secure KBA-type approval timelines. Anchor capacity expansion in Gujarat and Maharashtra to capture India's Dedicated Freight Corridor-linked passenger expansions before foreign qualification completes. Defend against modular seating specialists by bundling predictive maintenance platforms with hardware supply. For New Entrants and Emerging Players: Southeast Asian greenfield rail operators in Vietnam and Indonesia represent the most penetrable buyer archetype due to absent incumbent relationships and nascent supplier qualification frameworks. Target modular, rapid-release floor mounting systems for Indian commuter networks where peak-demand flexibility commands tender premiums. Enter through joint engineering partnerships with established rolling stock OEMs to bypass multi-year certification barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where JIS ergonomic benchmarking and GB-standard fire testing create dual-certification moats that fragment mid-tier suppliers. Frame long-term viability around captive supply relationships with state rail operators whose fleet renewal horizons extend across decade-long procurement windows. Target automotive-to-rail seating adaptors with acquired crashworthy frame expertise and existing European manufacturing footprints. Monitor BIS-European norm convergence in India as the signal indicating accelerated foreign supplier qualification and competitive entry.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foam Compounding | Secures KBA approval timelines and F-Gas Regulation compliance ahead of German rolling stock renewals. |
| Joint Venture with Southeast Asian Rail Developers | Establishes first-mover positioning in Vietnam and Indonesia's nascent high-speed networks before tender formalization. |
| Predictive Maintenance Platform Launch | Converts seat-mounted IoT sensor data into recurring revenue streams with Deutsche Bahn and SNCF. |
| Capacity Expansion in Western India | Captures Dedicated Freight Corridor-linked passenger seating demand as BIS standards converge with European norms. |
| Shape-Memory Alloy Actuator Development | Reduces weight-to-function ratios for business-class configurations piloted by German and French operators. |
Methodological Framework
Multiple input streams — primary interviews with rail procurement officers, foam compound technical directors, and rolling stock platform engineers; secondary validation through MIIT fleet expansion disclosures, ECHA REACH substance registrations, and JR East maintenance expenditure reports; plus customs data on aluminum alloy and aramid fiber trade flows — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured tender specification evolution across CRRC, Alstom, and Siemens supply chains. Secondary sources included KBA-type approval databases, BIS fire-safety standard drafts, and METI decarbonization directive implementation schedules.
Data-stream reconciliation anchored volume and value outputs across the projection horizon through segmented modeling of seat class tier, material compliance pathway, and operator ownership structure. Segmentation dimensions spanned product type, material category, end-user archetype, and design feature complexity. CAGRs were derived from rolling stock delivery schedules, fleet age profiles, and regulatory mandate enforcement timelines. Industry-specific forecast inputs incorporated aluminum price volatility indices and foam reformulation R&D expenditure patterns.
Inputs from JR East, Deutsche Bahn, and CRRC procurement disclosures were available through the study window; gaps in private operator tender pricing and Southeast Asian greenfield project cost structures introduce uncertainty bands around margin estimates. Forecasts reflect documented assumptions regarding MIIT mandate continuity and F-Gas Regulation phase-down adherence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Locomotive Parking Brake Market
Railway
Light Rail Market
Railway
Solar Powered Train Market
Railway
Gearbox for Rail Vehicles Market
Railway
Railway Axle Market
Railway
Railway Rolling Stock Market
Railway
Railway Horn Market
Railway
Train Exterior Lighting Market
Railway
Europe 40-Foot Platform Wagons Market
Railway
Railroad Brake Shoe Market
Railway
Heritage Railways Trains Market
Railway
Rail and Intermodal Decarbonization Strategy Consulting Market
Railway
Asia Pacific Rail Freight Transport Market
Railway
Rail Maintenance Management System Market
Railway
Railway Digital Signal Axle Counters Market
Railway
Railway Pantograph Market