
 Railway Window Market | 2026-2036
Railway Window Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Window Market Analytics
EN 45545-2 fire safety certification for railway components is unwinding the competitive landscape for window suppliers. Wabtec Corporation leverages its integrated braking and glazing platform to anchor large fleet contracts in North America. Knorr-Bremse AG sustains European market presence through specialized door and window systems for metro operators. Dellner Glass Solutions competes on laminated glass engineering for high-speed train cab fronts.
Railway windows are sealed transparent apertures installed in rolling stock, typically fabricated from thermally toughened glass bonded to aluminum or steel frames with polyurethane structural adhesives, designed to maintain cabin pressure integrity and passenger safety during derailment or collision events. Fixed windows occupy the dominant share across passenger coaches due to simpler sealing requirements and lower maintenance burden, while sliding windows retain niche demand in regional trains requiring emergency ventilation capability. Aluminum framing leads material selection for its strength-to-weight ratio in high-speed applications, though steel persists in freight cars where impact resistance outweighs mass considerations.
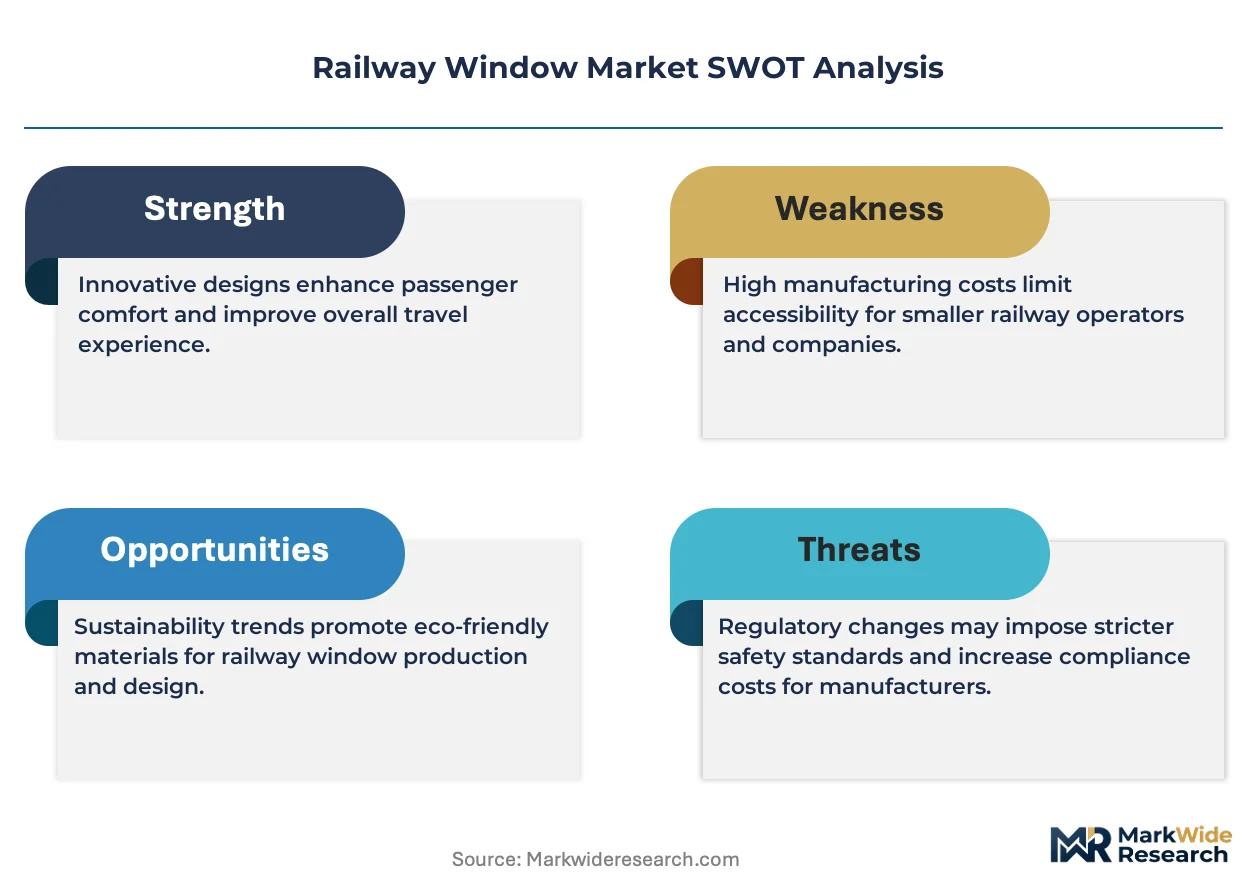
The Federal Railroad Administration in the United States enforces glazing impact standards under 49 CFR Part 223, while the European Union mandates CE marking and EN 45545 compliance for all new rolling stock placed into service. China's National Railway Administration applies GB standards for high-speed train window assemblies that exceed baseline ISO specifications for pressure cycling. Stakeholders must monitor divergence between regional fire toxicity standards and emerging requirements for acoustic attenuation in next-generation trainsets.
Market Dynamics
Crashworthiness standard escalation is compressing supplier qualification timelines while concentrating procurement authority among tier-one rolling stock integrators capable of certifying integrated glazing systems under unified EN and ISO protocols.
Growth Catalysts
- High-speed rail fleet expansion:China's National Railway Administration is procuring trainsets under GB standards that exceed baseline ISO pressure-cycling specifications, pulling demand for aluminum-framed fixed window assemblies.
- Fire safety mandates:EN 45545-2 certification requirements for railway components are disqualifying uncertified glazing suppliers and redirecting contracts toward integrated platform providers.
- Urban metro densification:Metro operators in East Asian corridors are specifying laminated glass cab fronts with acoustic attenuation layers to address tunnel noise exposure.
Market Restraints
- Aluminum input volatility:Framing material cost fluctuations constrain margin predictability for window fabricators serving high-speed rail programs.
- Specialized adhesive supply concentration:Polyurethane structural bonding agents for glass-to-frame assembly concentrate among a limited supplier base in Western Europe.
- Pressure-sealing technical thresholds:Cabin integrity specifications for high-altitude routes exceed conventional sealing technology capabilities without expensive engineering iteration.
Strategic Opportunities
- Southeast Asian corridor development:Vietnam and Indonesia are initiating rolling stock procurement programs without established domestic glazing supply chains.
- Smart glazing convergence:Electrochromic dimming layers are integrating with conventional laminated safety glass for climate-responsive cabin environments.
- Aftermarket service unbundling:Operators are separating window replacement and recertification contracts from original equipment procurement, opening independent service channels.
Industry Challenges
- Multi-standard certification complexity:Suppliers must parallel-track EN 45545-2, GB, and 49 CFR Part 223 compliance for cross-border fleet deployments.
- Laminated glass engineering talent scarcity:Specialized polymer interlayer formulation expertise concentrates among aging technical workforces in Germany and Japan.
- Legacy fleet retrofit integration:Modern pressure-sealed window designs require structural frame modifications incompatible with 1990s-era coach architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Window Market |
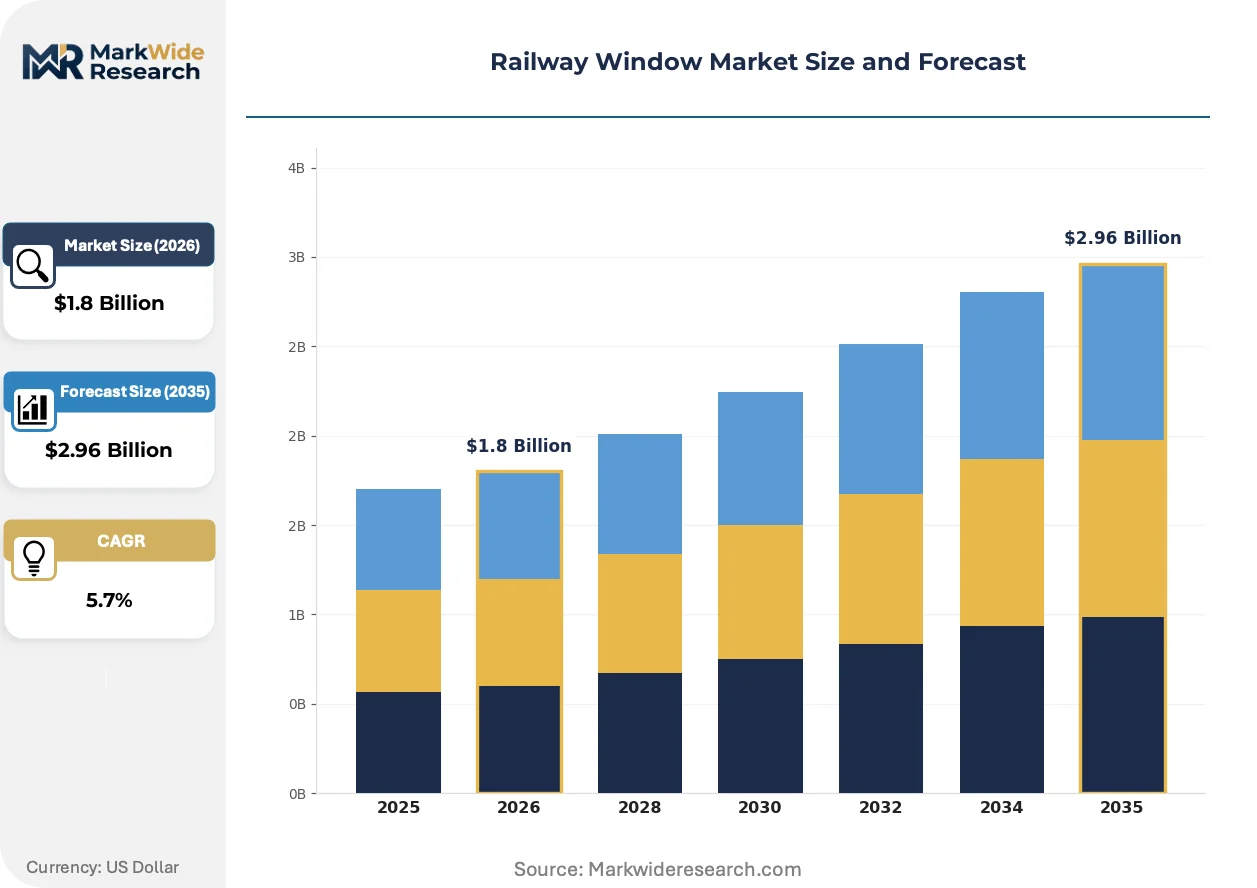
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sliding Windows, Fixed Windows, Hinged Windows, Tinted Windows Material: Aluminum, Fiberglass, Steel, PVC Use Case: Passenger Coaches, Freight Cars, High-Speed Trains, Metro Trains Certification: ISO, EN, ASTM, CE |
| Companies Covered | Lippert Components, Inc., Wabtec Corporation, Knorr-Bremse AG, Dellner Glass Solutions, AGC Inc., Schaltbau Holding, Sessa Klein, Independent Glass Co., KTK Group Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Window Market Evolving Landscape
Material substitution and regulatory harmonization pressures are compressing traditional supplier hierarchies while elevating integrated system platforms over component-level competition.
Polymer-reinforced interlayer formulations are supplanting conventional PVB laminates in high-speed cab front applications. Japanese and Chinese OEMs are specifying these materials for superior impact resistance during bird-strike events. This transition is supplanting established European interlayer suppliers in East Asian procurement competitions.
REACH chemical restriction expansions are forcing reformulation of polyurethane structural adhesives used in frame bonding. The European Chemicals Agency's substance evaluation protocols are extending certification timelines for window assembly suppliers. German and French integrators are accelerating in-house adhesive development to circumvent external dependency risks.
Consolidated fleet procurement by state rail operators is compressing supplier negotiation leverage. Chinese and Saudi national railways are bundling window specifications into rolling stock platform contracts rather than sourcing separately. This concentration is visible most acutely in high-speed programs where single-source glazing commitments span decade-long fleet deployment cycles.
Railway Window Market Segmentation
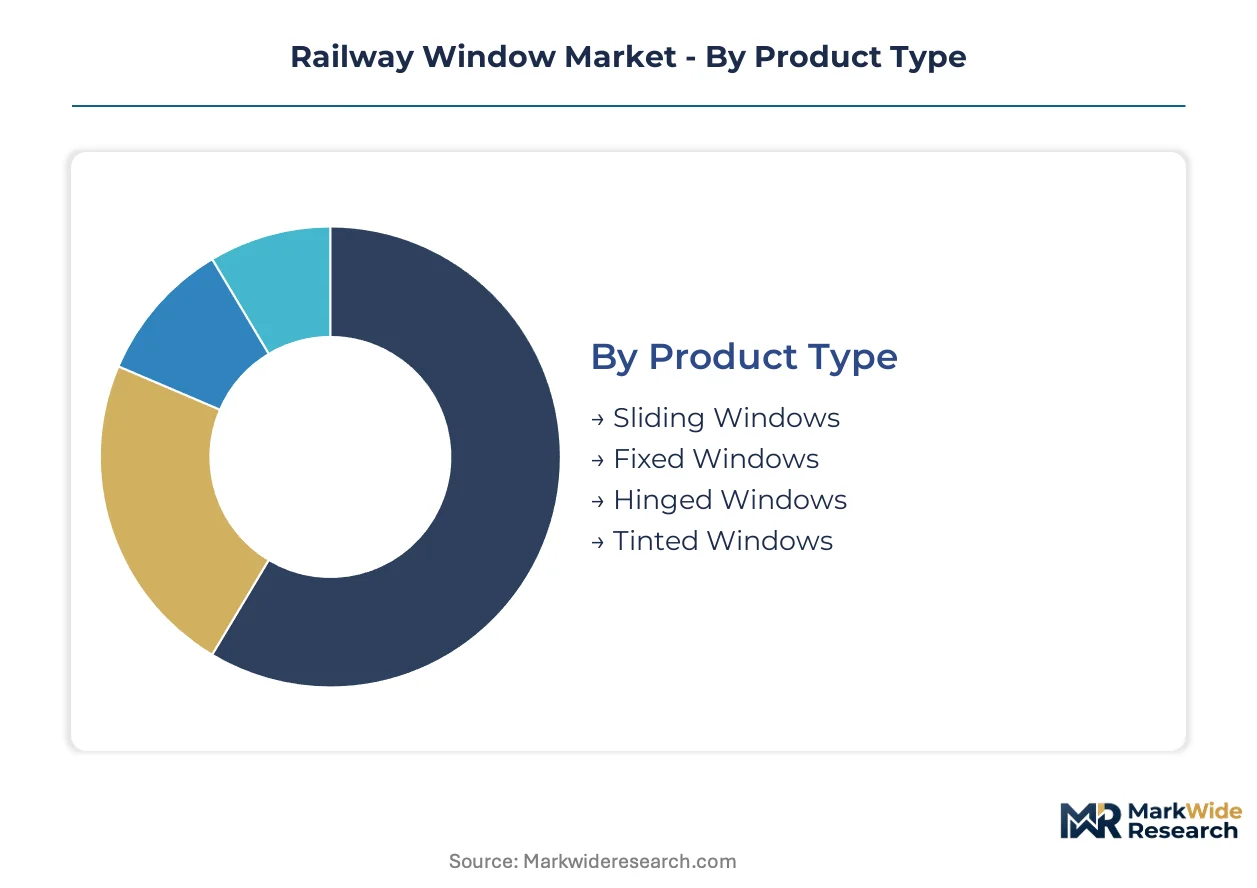
Railway window procurement diverges sharply by operating environment, with high-speed corridors demanding pressure-sealed fixed assemblies while regional networks retain ventilation-capable designs. Certification requirements fragment supplier capabilities across regional regulatory regimes. Material selection and product architecture directly determine qualification for specific fleet programs.
Product Type:
Fixed windows dominate export-led procurement for high-speed trainsets across China, Saudi Arabia, and Morocco, while sliding and hinged variants serve domestic regional operators requiring emergency egress flexibility.
- Sliding Windows:Mechanically actuated sash systems with manual or pneumatic operation, specified for regional passenger coaches in India and Southeast Asia where emergency ventilation protocols override pressure-sealing requirements. Indian Railways mandates these for non-AC sleeper classes under IRWM specifications.
- Fixed Windows:Permanently bonded glass-to-frame assemblies using polyurethane structural adhesives, specified exclusively for high-speed trainsets operating above 250 km/h. China's CR400 series and Saudi Haramain fleet require these for cabin pressure integrity during tunnel transit.
- Hinged Windows:Outward-opening emergency escape configurations with retained hinge hardware, specified for legacy commuter fleets in Poland and Czech Republic where retrofit compatibility constrains design options.
- Tinted Windows:Solar-control glazed units with spectrally selective coatings, specified for Middle Eastern operators including Etihad Rail and UAE metro systems where thermal load management reduces HVAC energy draw.
Fixed windows hold the largest share; momentum sits with tinted variants as Gulf corridor procurement accelerates.
Material:
Cost tiers separate aerospace-grade aluminum framing from commodity steel alternatives, with fiberglass emerging at premium price points for corrosion-resistant coastal applications.
- Aluminum:Extruded 6061-T6 alloy profiles with anodized surface treatment, specified for all high-speed and metro applications where strength-to-weight ratio determines energy efficiency. Japanese Shinkansen and Chinese Fuxing platforms standardize on this material.
- Steel:Cold-formed carbon steel sections with epoxy powder coating, specified for freight car applications across Russian Railways and North American Class I operators where impact resistance dominates mass considerations.
- Fiberglass:Pultruded glass-reinforced polymer profiles with UV-stabilized gel coats, specified for coastal metro systems in Mumbai and Chennai where salt corrosion degrades metal alternatives within seven-year replacement cycles.
- PVC:Rigid polyvinyl chloride extrusions with titanium dioxide stabilization, specified for light rail and tram applications in Germany and Austria where low capital cost outweighs thermal expansion limitations.
Aluminum captures the dominant revenue position; fiberglass is climbing the fastest as coastal urbanization intensifies.
Use Case:
Customer type stratification concentrates design authority among state rail operators versus private freight lessors with divergent specification priorities.
- Passenger Coaches:Panoramic glazing with acoustic interlayers for intercity services, specified by Deutsche Bahn and SNCF for passenger experience differentiation on competitive routes.
- Freight Cars:Small observation apertures with wire-mesh reinforcement, specified by Union Pacific and BNSF for crew visibility without cargo security compromise.
- High-Speed Trains:Aerodynamic cab fronts with bird-strike-resistant laminated glass, specified by CRRC and Alstom for operational safety above 300 km/h.
- Metro Trains:Curved sidewall glazing with anti-graffiti surface treatments, specified by Moscow Metro and Mexico City STC for high-frequency urban density.
High-speed train applications command premium pricing; metro trains represent the steepest expansion trajectory as urban densification accelerates.
Certification:
Supply concentration clusters among Western European testing houses for EN and CE protocols, while Chinese laboratories capture domestic GB certification volume.
- ISO:Baseline quality management and pressure-cycling test protocols referenced in cross-border procurement, mandatory for Russian Railways and Eurasian Economic Union member states.
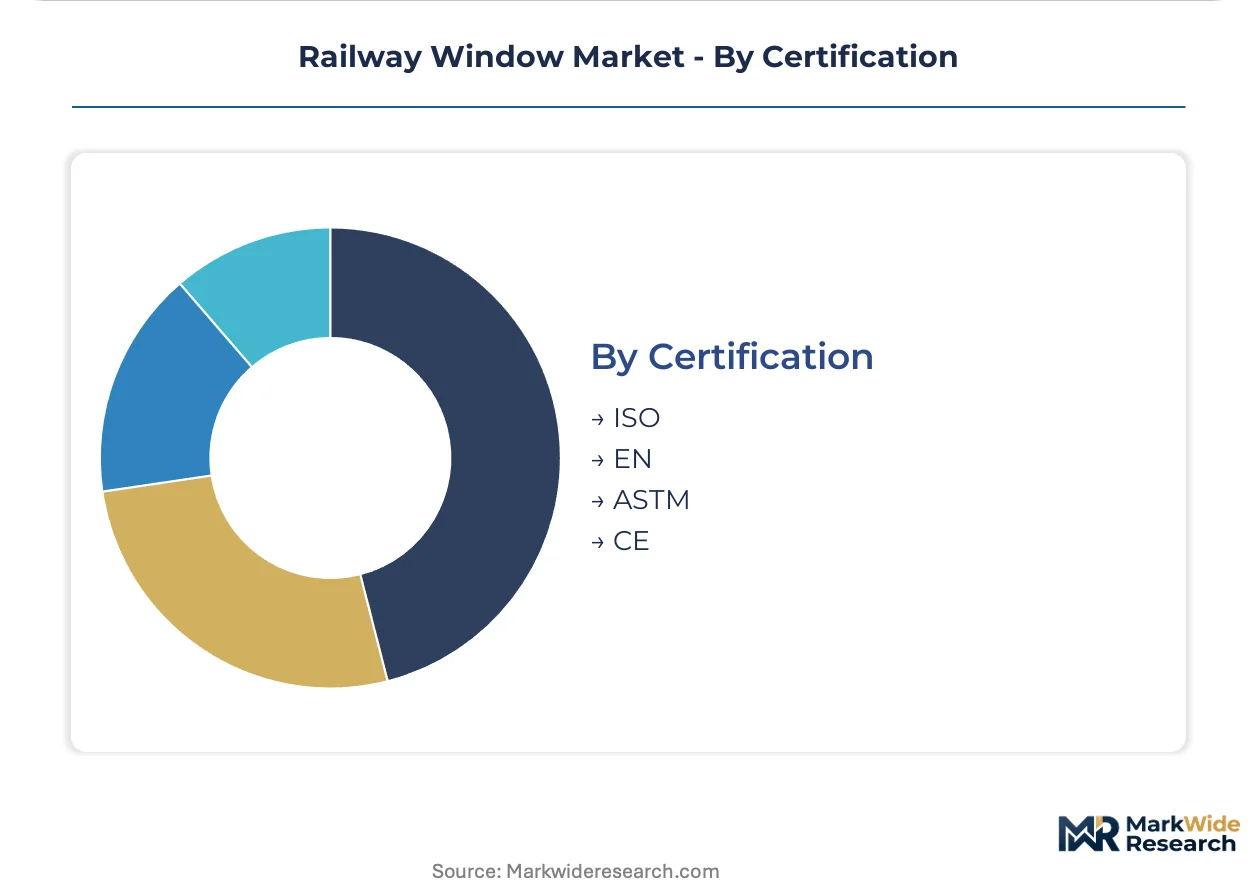
- EN:European Norm fire safety and crashworthiness standards including EN 45545-2 and EN 12663, mandatory for EU member state rolling stock and adopted by Swiss Federal Railways and Norwegian operators.
- ASTM:American Society for Testing and Materials impact and environmental durability protocols, referenced by Amtrak and Canadian VIA Rail for North American fleet procurement.
- CE:European conformity marking integrating multiple EN standards under unified assessment, required for market access across EU-27 plus associated EFTA territories.
EN certification holds the largest share; momentum sits with CE marking consolidation as single-market procurement simplifies supplier qualification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-backed fleet procurement programs are redirecting window demand toward high-speed corridors in East Asia and Middle Eastern metro densification projects. National railway administrations in China, Saudi Arabia, and Germany are bundling glazing specifications into rolling stock platform contracts rather than sourcing separately.
China
CRRC's CR400 series procurement under GB standards exceeding baseline ISO pressure-cycling specifications is pulling demand for aluminum-framed fixed window assemblies. The National Railway Administration mandates these pressure-sealed designs for all trainsets operating above 250 km/h. Manufacturing concentrates in Changchun and Qingdao where CRRC subsidiaries integrate glazing into complete carriage production.
Saudi Arabia
The Haramain high-speed rail expansion and Riyadh Metro Phase 2 are specifying laminated glass cab fronts with solar-control coatings for thermal load management. The Saudi Railway Authority applies GB-influenced standards for pressure integrity alongside local fire safety protocols. Production activity clusters in Jeddah where Alstom-Saudi joint ventures localize window assembly for Gulf corridor deployment.
Germany
Deutsche Bahn's ICE 4 fleet renewal and S-Bahn modernization programs are specifying panoramic glazing with acoustic interlayers for passenger experience differentiation. The Federal Railway Authority enforces EN 45545-2 fire safety certification alongside KBA crashworthiness approvals. Industrial activity concentrates in Berlin-Brandenburg and Bavaria where Schaltbau and Sessa Klein maintain glazing integration facilities.
Japan
JR Central's N700S series expansion and Tokyo Metro line extensions are driving demand for bird-strike-resistant laminated glass with polymer-reinforced interlayers. METI's JIS standards for railway components mandate specific impact resistance thresholds for cab front assemblies. Manufacturing centers in Aichi Prefecture around Nagoya host specialized glass bonding operations serving Shinkansen programs.
India
Indian Railways' Vande Bharat trainset procurement and metro expansions in Mumbai and Chennai are creating dual demand tracks for pressure-sealed fixed windows and emergency-ventilation sliding designs. The Research Designs and Standards Organization mandates IRWM specifications for non-AC coaches requiring manual sash operation. Production activity concentrates in Chennai and Bengaluru where KTK Group and domestic fabricators serve regional fleet requirements.
Railway Window Market Competitive Landscape
Player mix skews toward diversified rolling stock integrators with captive glazing capabilities alongside specialized component suppliers. The vendor base separates into three distinct tiers: multinational platform providers certifying integrated systems under unified EN and ISO protocols, regional specialists concentrating on laminated glass engineering for high-speed cab fronts, and domestic fabricators serving localized fleet procurement with cost-optimized designs. Competitive dynamics center on M&A activity consolidating adhesive and interlayer supply chains, alongside strategic partnerships between European testing houses and Asian OEMs accelerating multi-standard certification.
Within the multinational platform tier, Wabtec Corporation and Knorr-Bremse AG exemplify the integrated braking-and-glazing model anchoring large fleet contracts in North America and Europe respectively. Dellner Glass Solutions occupies a specialist position in laminated glass engineering for high-speed train cab fronts, representing the technical-depth archetype competing on impact-resistance specifications rather than bundled system scope. These three entities illustrate the competitive divergence between breadth-driven platform consolidation and depth-driven material science specialization.
| Leading Market Players |
|---|
| Lippert Components, Inc. |
| Wabtec Corporation |
| Knorr-Bremse AG |
| Dellner Glass Solutions |
| AGC Inc. |
| Schaltbau Holding |
| Sessa Klein |
| Independent Glass Co. |
| KTK Group Co. Ltd. |
| Others |
Value Network & Pricing Analysis
Long-term fleet procurement contracts spanning decade-long deployment cycles lock in aluminum framing and laminated glass supply while stripping price volatility from window assembly costs for Chinese and Saudi state rail operators. These bundled rolling stock agreements concentrate purchasing power among tier-one integrators capable of certifying integrated glazing systems under unified EN and ISO protocols.
Pricing Analysis
Certification level creates the primary spread between EN 45545-2 compliant assemblies and uncertified alternatives, with CE-marked fixed windows commanding substantial premiums over baseline ISO-grade products for high-speed corridors. Three-tier pricing structure separates premium aluminum-framed cab fronts from standard coach glazing and economy steel-framed regional variants. Cost compression in the economy tier is intensifying because Indian Railways and Southeast Asian operators are unbundling window specifications from carriage contracts. Freight car operators exhibit highest price sensitivity, while high-speed rail programs prioritize crashworthiness certification over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are extending lead times for polyurethane structural adhesives sourced from Western European chemical producers. Manufacturing gravity centers on China, Germany, and Japan, with raw material flows drawing from bauxite processing in Australia and polymer interlayer production in Germany and Japan. Single-source vulnerability concentrates in specialized adhesive formulations where REACH chemical restrictions are forcing reformulation cycles. Distribution runs through rolling stock OEM assembly plants rather than independent window fabricators, compressing supplier negotiation leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket recertification and replacement services are expanding faster than original equipment procurement as operators separate lifecycle maintenance from initial fleet acquisition. This service-attach layer offers recurring revenue streams detached from lumpy rolling stock procurement cycles.
For Market Incumbents: Fortify adhesive supply security through backward integration into polyurethane formulation or captive partnerships with German chemical specialists, insulating margin positions from REACH-driven raw material disruption. Deepen certification capabilities across GB, EN, and 49 CFR Part 223 protocols simultaneously to defend against emerging Chinese integrators bundling glazing into export trainset contracts. For New Entrants and Emerging Players: EN 45545-2 fast-track certification through European testing house partnerships opens procurement access for Southeast Asian corridor developments in Vietnam and Indonesia lacking domestic glazing supply chains. Target coastal metro operators in Mumbai and Chennai specifying fiberglass-framed corrosion-resistant designs where salt degradation creates replacement demand cycles incompatible with incumbent aluminum portfolios. Lead with acoustic attenuation layer integration as passenger experience differentiation. For Investors and Strategic Acquirers: Specialized laminated glass engineering firms with polymer-reinforced interlayer expertise represent priority acquisition targets as bird-strike resistance specifications escalate across Shinkansen and CRRC procurement. Long-term viability hinges on positioning upstream of smart glazing convergence where electrochromic dimming layers integrate with conventional safety glass. Monitor consolidation signals among European adhesive suppliers as ECHA substance evaluation protocols extend certification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Standard Certification Investment | Parallel EN 45545-2, GB, and 49 CFR Part 223 qualification opens cross-border fleet deployment for CRRC and Alstom contracts. |
| Polymer Interlayer R&D Partnership | Collaboration with Japanese chemical specialists accelerates bird-strike-resistant formulations for JR Central N700S specifications. |
| Coastal Corrosion-Resistant Product Line | Fiberglass-framed designs capture Mumbai Metro and Chennai replacement cycles where metal degradation drives seven-year refresh demand. |
| Aftermarket Service Unbundling | Independent recertification contracts separate from OEM procurement create recurring revenue streams at Deutsche Bahn and SNCF. |
| Smart Glazing Technology Integration | Electrochromic layer bonding capabilities position suppliers for climate-responsive cabin specifications in Gulf corridor procurement. |
Research Methodology
A standing panel of rolling stock procurement directors, railway safety certification engineers, and aftermarket service managers provided ongoing calibration against secondary validation from customs trade databases, rolling stock production registries, and national railway administration fleet deployment announcements. Primary fieldwork combined structured interviews with OEM platform engineers and adhesive supplier technical directors alongside bottom-up volume triangulation against top-down market sizing from rolling stock manufacturer revenue disclosures.
Consistency checks validated segment-level outputs against external benchmarks including high-speed trainset delivery schedules, metro expansion project announcements, and freight car build forecasts across the analysis window. The analytical framework modeled product type, material grade, use case intensity, and certification tier dimensions throughout the projection horizon. CAGRs were derived from fitted growth curves against historical procurement patterns and announced fleet renewal programs, with aluminum price indices and regulatory compliance cost trajectories feeding sensitivity analyses.
The analysis sits within stated boundaries; outcomes outside sustained state-backed infrastructure investment, stable aluminum input costs, and harmonized fire safety standard adoption would require recalibration. Forecasts reflect documented assumptions regarding certification timeline convergence and adhesive supply chain restructuring. Specific risks including REACH chemical restriction expansion, GB-EN standard divergence, and legacy fleet retrofit technical incompatibility could materially revise trajectory projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Rail Glazing Market
Railway
Sanitary Systems for Rail Transit Market
Railway
Train Bogie Market
Railway
Rail Damper Market
Railway
Gangway for Railway Vehicles Market
Railway
Hydrogen Fuel Cell Train Market
Railway
Heritage Railways Trains Market
Railway
40-Foot Platform Wagons Market
Railway
Global Train Lighting Market
Railway
Europe Intermodal Terminals Market
Railway
Global Train Control and Management Systems Market
Railway
Light Rail Market
Railway
Railway Draft Gears Market
Railway
Railway Overhead Catenary System Market
Railway
Railway Axle Market
Railway
Europe 40-Foot Platform Wagons Market