
 Solar Powered Train Market | 2026-2036
Solar Powered Train Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Powered Train Market Analytics
Photovoltaic-to-rail direct coupling is reshaping how traction power systems are architected, eliminating substation dependency for low-speed corridors. Siemens leverages its rail electrification heritage to anchor European pilot deployments, while Alstom competes through hydrogen-solar hybrid architectures. Suntrain specializes in retrofit kits for existing diesel locomotives, occupying a niche between greenfield projects and fleet modernization.
A solar powered train integrates photovoltaic panels mounted on roof surfaces or trackside arrays with onboard battery storage and electric traction motors, typically operating at 750V to 1500V DC for light-rail applications. The system's primary purpose is to reduce or eliminate grid electricity consumption during daylight operations, cutting carbon emissions and operational energy costs for rail operators. Photovoltaic Systems dominate capital allocation due to panel cost declines and mounting standardization, while Battery Storage captures expanding margin pools as energy density improvements enable longer off-grid stretches. Hybrid Systems represent the fastest-growing configuration, combining solar with grid or hydrogen backup to satisfy reliability requirements for intercity routes.
The EU Green Deal and F-Gas Regulation shape rolling stock standards by mandating progressive carbon reduction and restricting fluorinated greenhouse gases in cooling systems. India's PLI scheme and CEA grid codes influence domestic manufacturing location decisions and interconnection requirements for trackside solar arrays. The US FRA and EPA jointly govern locomotive emissions thresholds and environmental review processes for new rail infrastructure. Stakeholders must monitor how evolving storage chemistry safety standards and country-specific rail certification timelines affect deployment sequencing across target corridors.
Market Dynamics
Photovoltaic-to-traction direct coupling is collapsing the traditional substation infrastructure model, forcing rail operators to rearchitect power delivery around distributed generation and onboard storage rather than centralized grid dependency.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for domestic solar cell manufacturing are compressing panel costs for rolling stock integrators. Suburban rail operators in Mumbai and Delhi corridors are accelerating procurement timelines.
- Battery energy density gains:Lithium iron phosphate chemistries now enable 150-200 kilometer off-grid stretches. This technical threshold unlocks intercity routes previously excluded from solar-hybrid consideration.
- EU Green Deal transport mandates:Binding carbon reduction targets for rail operators are converting pilot programs into fleet-wide deployment schedules. Germany's regional networks are front-loading procurement to meet 2030 checkpoints.
Market Restraints
- Polysilicon supply concentration:Over 80 percent of metallurgical-grade silicon refining sits in Xinjiang and Inner Mongolia. Geopolitical friction creates input cost volatility for panel manufacturers serving rail integrators.
- Trackside land access restrictions:Railway corridors in dense European and Indian urban zones lack contiguous unshaded acreage for ground-mounted arrays. This forces expensive elevated or integrated roof solutions.
- Grid interconnection standards:India's CEA technical standards for renewable injection create certification bottlenecks. Regional utilities impose divergent synchronization protocols that fragment system design.
Strategic Opportunities
- Retrofit diesel locomotive conversions:India's 5,000-plus diesel fleet presents a captive addressable base. Suntrain-style plug-and-play roof kits bypass greenfield infrastructure timelines.
- Hydrogen-solar hybrid architectures:Converging fuel cell range extension with photovoltaic generation addresses reliability anxiety for intercity corridors. Alstom's platform architecture validates the technical pathway.
- Outcome-based energy contracts:Rail operators are piloting kilowatt-hour-as-a-service models where integrators own and operate trackside generation. This shifts capex burden and accelerates deployment decisions.
Industry Challenges
- Rail-specific electrical certification timelines:EN 50155 and IEC 61215 compliance for onboard photovoltaic systems requires 18-24 month validation cycles. This compresses competitive windows for first-mover operators.
- Multimodal integration complexity:Solar-hybrid trains must synchronize with existing 25kV AC electrified networks and diesel-operated branch lines. Control system interoperability demands bespoke engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Powered Train Market |
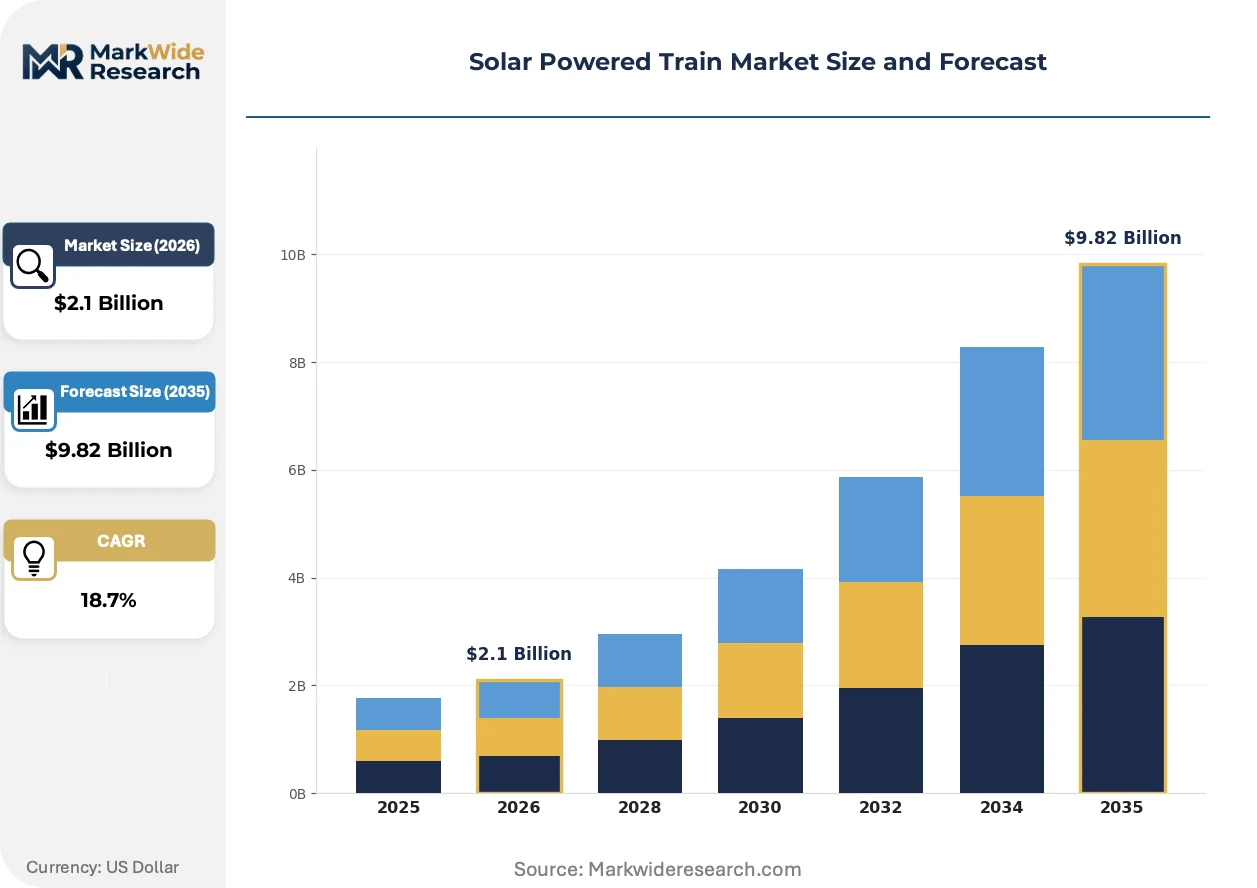
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $9.82 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Photovoltaic Systems, Battery Storage, Hybrid Systems, Regenerative Braking End User: Public Transport, Freight Services, Tourist Transport, Infrastructure Providers Application: Urban Transit, Intercity Travel, Cargo Transport, Shuttle Services Capacity: Lightweight Trains, Heavy-Duty Trains, Long-Distance Trains, Commuter Trains |
| Companies Covered | Siemens, Tesla, Suntrain, First Solar, SunPower, California High-Speed Rail Authority, Alstom, Ørsted, American Solar Rail, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Powered Train Market Evolving Landscape
Active research into perovskite-silicon tandem cells and solid-state battery integration is compressing the performance gap between solar-hybrid trains and fully electrified corridors. Material science breakthroughs are now the primary velocity determinant for market expansion.
Perovskite photovoltaic layers are rendering obsolete the efficiency ceiling that constrained rooftop panel deployment on rolling stock. Indian Institute of Technology researchers and European rail OEMs are co-developing lightweight flexible substrates for curved roof geometries. The structural consequence is collapsing the economic case for diesel retention on 100-150 kilometer suburban spans.
The EU F-Gas Regulation is banning hydrofluorocarbon refrigerants in train cooling systems from 2027. This forces simultaneous redesign of HVAC and battery thermal management architectures. Manufacturers serving German and French regional operators are consolidating supplier relationships to secure CO2-based cooling technology ahead of compliance deadlines.
Indian Railways is unbundling energy procurement from rolling stock acquisition, creating dedicated solar power purchase agreements for traction loads. State-level discoms in Maharashtra and Gujarat are establishing rail-specific renewable energy certificates. This procurement model change is most visible in Western Railway Zone corridors where long-term contracts now dominate capital planning.
Solar Powered Train Market Segmentation
Technology configuration determines capital intensity and operational flexibility across rail corridors. End-user procurement patterns and application requirements further stratify the addressable market by reliability thresholds and route economics.
Technology:
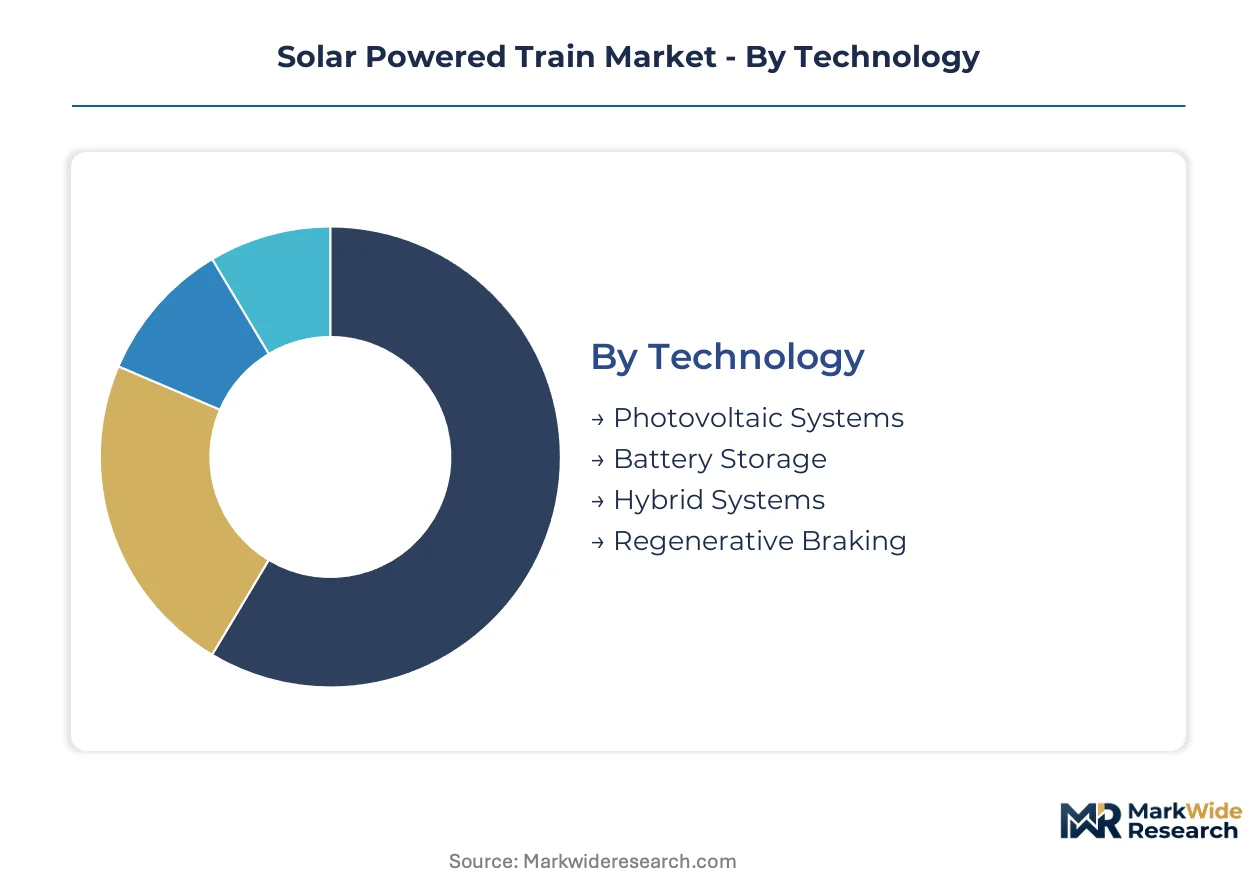
Photovoltaic Systems turn over slowest due to panel durability and mounting standardization, while Battery Storage cycles fastest as energy density improvements trigger replacement decisions.
- Photovoltaic Systems:Roof-mounted and trackside silicon arrays convert solar irradiance into DC traction power at 750V to 1500V. Mumbai Suburban Railway and Deutsche Bahn regional networks concentrate procurement where land availability permits contiguous unshaded installation.
- Battery Storage:Lithium iron phosphate and emerging solid-state chemistries store photovoltaic generation for off-grid traction stretches. India's Western Railway Zone pilots 150-kilometer battery-electric spans where grid interconnection remains costly.
- Hybrid Systems:Combine solar generation with grid or hydrogen backup for reliability-critical intercity routes.
- Regenerative Braking:Recaptures kinetic energy during deceleration, feeding onboard batteries or returning power to trackside storage.
Photovoltaic Systems anchors the volume base while Battery Storage gains share at the steepest rate.
End User:
Public Transport operators command the highest procurement volumes, whereas Infrastructure Providers extract margins through energy-as-a-service contracting models.
- Public Transport:Municipal and regional rail authorities in Germany and India deploy solar-hybrid fleets under decarbonization mandates. Delhi Metro Rail Corporation and Rhein-Main-Verkehrsverbund prioritize operational cost reduction over capital expenditure minimization.
- Freight Services:Cargo operators pilot solar-battery locomotives for last-mile terminal operations where diesel idling costs dominate.
- Tourist Transport:Scenic railway operators in Alpine corridors leverage solar branding for premium passenger experience differentiation.
- Infrastructure Providers:Energy utilities and independent power producers own trackside generation assets, selling kilowatt-hours to rail operators under long-term purchase agreements.
Public Transport commands absolute procurement volume while Infrastructure Providers expand most quickly through outcome-based contracting.
Application:
Urban Transit offers the shortest payback periods due to high daily utilization, while Intercity Travel demands the most complex hybrid architectures.
- Urban Transit:Suburban and metro corridors with frequent stops maximize regenerative braking capture and solar exposure hours. Bangalore Metro and Lyon Tramway systems integrate roof panels with catenary-free operation in historic districts.
- Intercity Travel:Regional express routes require battery range extension or hydrogen fuel cell backup to bridge grid gaps. Germany's Baden-Württemberg network validates 200-kilometer solar-battery feasibility.
- Cargo Transport:Industrial freight spurs demand solar-powered shunting locomotives for port and yard operations.
- Shuttle Services:Airport and campus connectors exploit predictable duty cycles for pure solar-battery operation.
Urban Transit dominates installed base expansion while Intercity Travel climbs the fastest as battery density thresholds cross commercial viability.
Capacity:
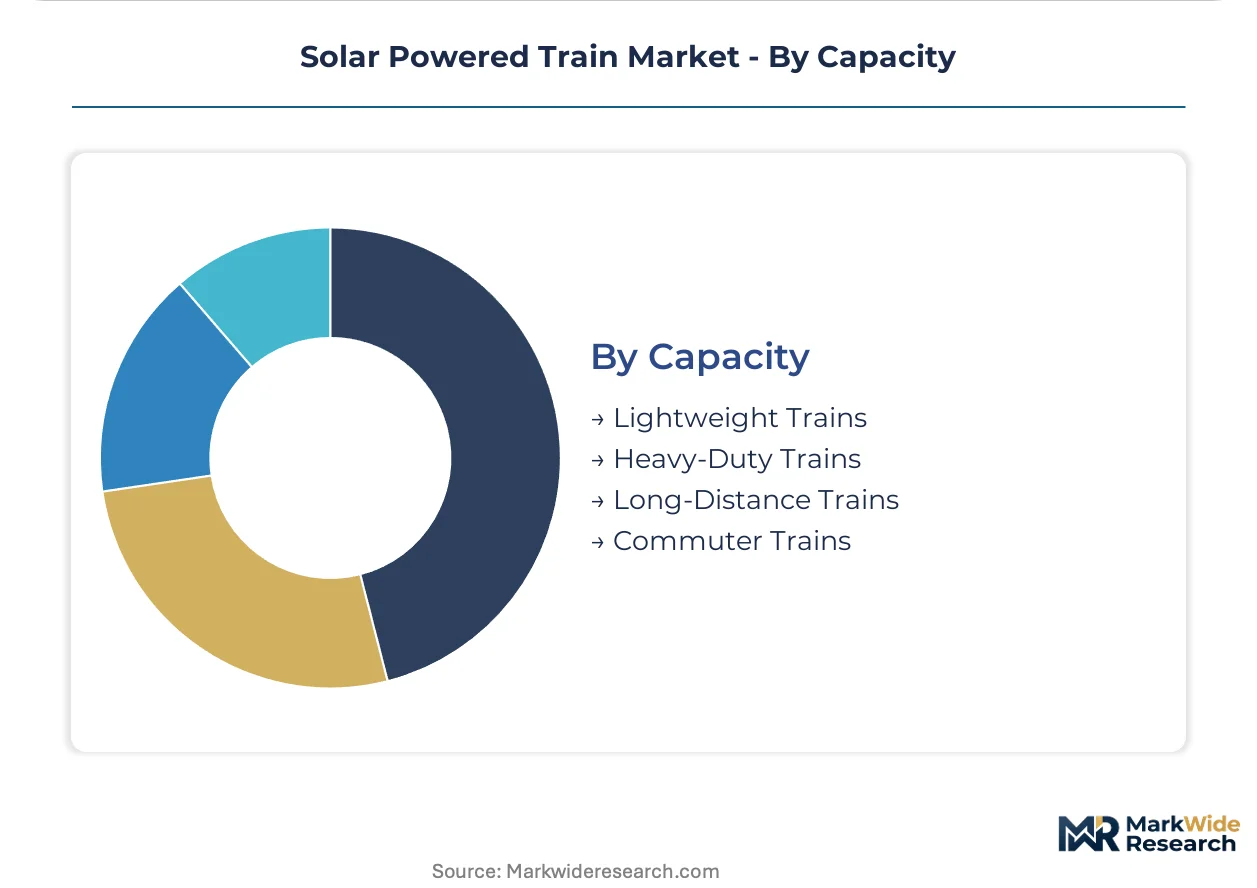
Commuter Trains achieve the fastest technology refresh cycles, whereas Heavy-Duty Trains face the longest certification and replacement timelines.
- Lightweight Trains:Low-floor trams and people-movers optimize roof area-to-weight ratios for maximum solar self-sufficiency. Strasbourg and Melbourne tram networks demonstrate 30-40% traction energy from onboard photovoltaics.
- Heavy-Duty Trains:High-axle-load locomotives for freight and long-distance passenger service require supplemental grid or hydrogen power. Indian Railways' WAG-12 electric fleet trials solar augmentation for auxiliary loads.
- Long-Distance Trains:Sleeper and dining car configurations prioritize passenger amenities over roof panel area.
- Commuter Trains:High-frequency multiple-unit designs with standardized roof geometry enable rapid solar retrofit deployment.
Commuter Trains anchor procurement volume while Lightweight Trains expand most quickly in greenfield urban systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rail operators in Germany and India command the largest procurement volumes for solar-hybrid rolling stock, while Japan and the United States concentrate development efforts around next-generation battery chemistry integration.
Germany
Deutsche Bahn's regional networks drive fleet-wide electrification mandates under the EU Green Deal. The F-Gas Regulation accelerates HVAC redesign timelines for rolling stock manufacturers. Baden-Württemberg's rail corridors validate 200-kilometer solar-battery feasibility studies.
India
Mumbai Suburban Railway and Delhi Metro Rail Corporation scale rooftop photovoltaic deployment across high-frequency corridors. The PLI scheme compresses domestic solar cell costs for rolling stock integrators. Western Railway Zone in Maharashtra pioneers dedicated solar power purchase agreements for traction loads.
Japan
Tokyo Metro and JR East pilot lightweight flexible substrates for curved train roof geometries. METI funding supports solid-state battery integration into commuter rail platforms. Kansai region operators test regenerative braking synchronization with trackside solar arrays.
United States
California High-Speed Rail Authority mandates renewable traction power sourcing for planned corridor segments. The FRA and EPA jointly govern locomotive emissions thresholds and environmental review processes. Pacific Northwest transit agencies explore outcome-based energy contracting models.
France
Région Sud and Auvergne-Rhône-Alpes networks prioritize hydrogen-solar hybrid architectures for mountainous intercity routes. EMA and national rail safety standards shape electrical certification timelines for onboard photovoltaic systems. Alstom's platform development in Saint-Ouen anchors European pilot deployment programs.
Solar Powered Train Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Siemens and Alstom leverage rail electrification heritage to anchor European infrastructure decisions, while Suntrain occupies a retrofit-focused niche between greenfield projects and fleet modernization. Consolidation pressure intensifies as battery energy density improvements expand addressable route lengths. Dominant competitive moves include strategic partnerships between rail OEMs and photovoltaic suppliers, plus geographic expansion into India's suburban corridor procurement cycles.
Within the heritage-rail-equipment tier, Siemens and Alstom exemplify integrated platform providers that bundle electrification infrastructure with rolling stock procurement. Suntrain represents the specialist retrofit archetype, targeting diesel fleet conversions through plug-and-play roof kit architectures. Tesla occupies a position at the energy-storage vector, anchoring battery cell supply relationships that reshape traction power economics. Ørsted and First Solar sit within the utility-scale generation tier, supplying trackside array development for rail-specific power purchase agreements.
| Leading Market Players |
|---|
| Siemens |
| Tesla |
| Suntrain |
| First Solar |
| SunPower |
| California High-Speed Rail Authority |
| Alstom |
| Ørsted |
| American Solar Rail |
| Others |
Value Network & Pricing Analysis
Xinjiang and Inner Mongolia's grip on metallurgical-grade silicon refining funnels margin capture toward photovoltaic panel integrators serving rail OEMs, while downstream rolling stock manufacturers absorb volatility through long-term offtake structures.
Pricing Analysis
Cost-plus contracts with polysilicon indexation dominate procurement between panel suppliers and rolling stock integrators. Three-tier pricing structure across premium, standard, and economy levels separates EN 50155-certified systems from uncertified alternatives and retrofit-only kits. Price differentiation rests on certification grade and volume scale, with municipal rail authorities commanding discounts unavailable to scenic tourist operators. Cost compression in battery storage tiers is intensifying because lithium iron phosphate cell capacity expansion outpaces dedicated rail demand formation.
Supply Chain Analysis
Contract manufacturing concentration sits with Foxconn and Jabil for power electronics assembly, plus CATL and BYD for battery cell fabrication. Polysilicon refining draws from China, Malaysia, and Germany; lithium extraction centers on Australia, Chile, and Argentina; rail-grade steel production rests on Japan and South Korea. Single-source vulnerability in Xinjiang polysilicon creates tariff exposure risk for European integrators. Distribution runs through rail OEM direct procurement channels and energy utility power purchase agreement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solar-hybrid rail equipment demand follows the cyclical infrastructure investment wave triggered by EU Green Deal compliance deadlines and India's PLI scheme renewal windows.
For Market Incumbents: Insulate margin pools by securing captive polysilicon supply through backward integration into Malaysian or German refining capacity. Lock in 18-24 month EN 50155 certification pipelines ahead of competitor submissions. Hydrogen-solar hybrid architectures from Alstom and Siemens represent the primary substitution threat requiring pre-emptive platform investment. For New Entrants and Emerging Players: India's 5,000-plus diesel locomotive fleet awaiting retrofit represents the most penetrable entry point for Suntrain-style plug-and-play roof kit architectures. Maharashtra and Gujarat state-level discoms offer regulatory pathways for independent power producers to own trackside generation assets. Outcome-based energy contracting with Western Railway Zone operators bypasses capital expenditure barriers that stall greenfield competitors. For Investors and Strategic Acquirers: Capital is best deployed toward battery storage specialists with rail-specific thermal management IP and solid-state chemistry development partnerships. Long-term viability hinges on crossing the 300-kilometer off-grid threshold that unlocks intercity route economics. Monitor India's CEA grid code harmonization progress as the signal for procurement acceleration versus certification bottleneck persistence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | Secures supply certainty for Siemens and Alstom against Xinjiang concentration risk. |
| Solid-State Battery Partnership | Positions Tesla and CATL to capture range-extension contracts from Deutsche Bahn. |
| Retrofit Kit Certification Fast-Track | Enables Suntrain to compress 18-month EN 50155 timelines for Indian diesel conversions. |
| Hydrogen-Solar Hybrid Platform | Validates Alstom's technical pathway for Baden-Württemberg intercity reliability requirements. |
| Power Purchase Agreement Unbundling | Allows Ørsted to own Maharashtra trackside assets under Western Railway Zone contracts. |
Research Methodology
A standing panel of rail electrification engineers, procurement officers at Deutsche Bahn and Indian Railways, battery cell R&D directors, and trackside solar project developers provided ongoing calibration. Primary interviews combined with secondary validation from EIA project databases, IEA transport decarbonization reports, FERC interconnection filings, and CEA technical standards documentation. Bottom-up deployment modeling across corridor-specific procurement cycles triangulated against top-down market sizing from OEM revenue disclosures.
Scenario-bracketing framed volume and value outputs across the projection horizon. Segmentation dimensions modeled include technology configuration, end-user archetype, application type, and regional regulatory framework. CAGRs derived from corridor-level procurement pipeline analysis weighted by interconnection cost structures and battery density improvement curves. Rail-specific certification timeline distributions and PLI scheme incentive phase-outs served as key forecast inputs.
Stress conditions across polysilicon price volatility, lithium supply disruption, and CEA grid code revision timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding battery chemistry transition rates and EU F-Gas Regulation compliance pacing. Quarterly review of Indian Railways tender announcements and German regional network electrification schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Railway Telematics Market
Railway
Railroad Brake Shoe Market
Railway
Railcar Vehicle Toilet Market
Railway
Train HVAC Market
Railway
Railway Digital Signal Axle Counters Market
Railway
Railway Buffer Stops Market
Railway
India Rail Freight Transport Market
Railway
Railway Engine Market
Railway
Hydrogen Trains Market
Railway
Automatic Train Supervision Market
Railway
South Korea Connected Rail Market
Railway
Global Hyperloop Train Market
Railway
Railway Horn Market
Railway
Connected Rail Market
Railway
Electro-Pneumatic Train Brakes Market
Railway
Locomotive Maintenance Market