
 Locomotive Radiator Fan Market | 2026-2036
Locomotive Radiator Fan Market Size, Share, and Industry Trends Forecast 2026-2036
Locomotive Radiator Fan Market Foresight
Multi-source procurement for radiator fan assemblies is pivoting toward vertically integrated suppliers with captive motor and blade manufacturing. Ametek Inc. leverages its aerospace-derived motor technologies to anchor premium locomotive cooling contracts. ZIEHL-ABEGG Inc. sustains European market presence through specialized axial fan designs optimized for rail duty cycles. Flexxaire Inc. differentiates via variable-pitch blade systems that reduce engine parasitic load across variable speed operations.
A locomotive radiator fan is a heavy-duty forced-convection device, typically spanning 400–1,200 mm in diameter, engineered to maintain engine coolant and charge-air temperatures within specified thermal envelopes under dynamic load conditions. The assembly comprises a hub-mounted impeller, electric or hydraulic drive motor, and shrouded housing, all rated for continuous vibration exposure and ambient temperature swings from minus 40 to plus 50 degrees Celsius. Axial fan configurations dominate current installations due to their high flow efficiency at low static pressure, while hybrid drive systems pairing electric motors with engine-speed-responsive controls represent the fastest-expanding segment as operators target fuel economy gains. Composite blade materials are displacing aluminum in new-build programs where weight reduction and corrosion resistance justify material cost premiums.
EPA Tier 4 locomotive emissions standards in the United States mandate tighter thermal management, directly expanding demand for high-performance radiator fan systems with precision flow modulation. The EU F-Gas Regulation and REACH compliance frameworks restrict certain refrigerants and material chemistries, pushing European OEMs toward air-cooled and liquid-cooled combination architectures certified to ISO and DIN standards. China's GB standards and dual carbon goals impose parallel efficiency requirements on domestic locomotive production. Stakeholders must weigh regional certification burdens against platform standardization economics when configuring global supply chains.
Market Dynamics
Freight rail operators in the United States are retiring legacy diesel-electric locomotives at an accelerated clip, forcing cooling-system suppliers to reengineer around tighter EPA Tier 4 thermal envelopes and hybrid-electric architectures that demand variable-speed fan modulation.
Growth Catalysts
- EPA Tier 4 Compliance:United States freight carriers must retrofit or replace cooling systems to meet tightened particulate and NOx limits, directly expanding specification-grade radiator fan procurement volumes.
- Composite Blade Materials:Glass-reinforced polymer and carbon-fiber compounds are penetrating new-build locomotive programs where corrosion resistance and rotational inertia reduction justify engineering change orders.
- China Railway Modernization:State Railway Group's fleet renewal targets under GB standards are pulling high-capacity axial fan assemblies into domestic manufacturing lines at scale.
Market Restraints
- Copper and Rare-Earth Magnet Costs:Electric drive motors depend on copper windings and neodymium permanent magnets, exposing OEMs to commodity volatility that compresses margin on fixed-price rail contracts.
- Single-Source Hydraulic Component Supply:Precision hydraulic fan drives for legacy locomotive retrofits concentrate with German and Japanese specialty suppliers, creating geographic concentration risk for North American rebuilders.
- Aluminum Air-Cooled Heat Exchangers:Simplified loop designs in yard switchers and short-line operations substitute passive cooling for forced-convection systems, capping addressable volume in the sub-1,000 hp segment.
Strategic Opportunities
- Indian Railway Electrification:Indian Railways' net-zero freight corridor targets under CEA guidelines will require hybrid cooling architectures for dual-mode locomotives, opening specification windows for variable-pitch fan technologies.
- EU F-Gas Phase-Down:REACH and F-Gas Regulation restrictions on synthetic refrigerants are accelerating air-cooled system adoption in European passenger locomotives, favoring suppliers with ISO-certified thermal design capabilities.
- Predictive Maintenance Integration:Vibration-sensor-equipped fan assemblies paired with edge-computing diagnostics enable condition-based replacement contracts that shift revenue from hardware to recurring service streams.
Industry Challenges
- Thermal Simulation Expertise Shortage:Computational fluid dynamics modeling for multi-physics cooling optimization requires specialized rail-sector experience that outpaces current graduate pipeline output in mechanical engineering programs.
- ISO 9001 and IRIS Recertification Burden:International Railway Industry Standard audits demand 18-to-24-month documentation cycles that delay new supplier qualification for Tier 1 OEM programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Locomotive Radiator Fan Market |
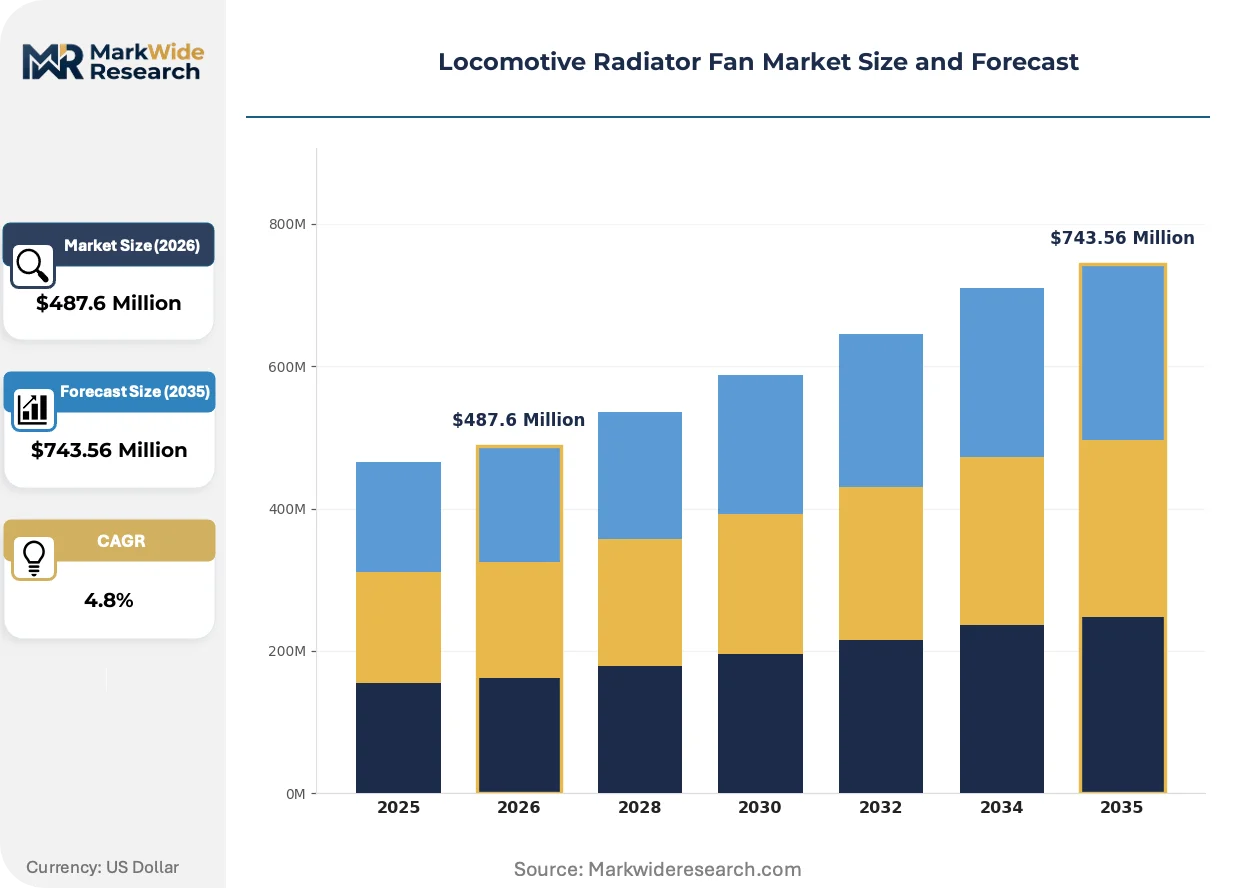
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fan Type: Axial, Centrifugal, Hybrid, Variable Speed Material: Aluminum, Plastic, Steel, Composite Cooling Method: Air-Cooled, Liquid-Cooled, Combination, Direct Ventilation Industry Standard: ISO, ASME, ANSI, DIN |
| Companies Covered | Ametek Inc., Multi Wing America Inc., ZIEHL-ABEGG Inc., Bergstrom Inc., Sunonwealth Electric Machine Industry Co. Ltd, Flexxaire Inc., Valeo SA, Horton Holding Inc., Aerovent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Locomotive Radiator Fan Market Shifts & Advancements
Active grille shutter systems and intelligent thermal management software are converging with mechanical fan hardware, compressing the traditional separation between passive cooling components and engine-control electronics in locomotive architecture decisions.
Variable-pitch blade mechanisms with electromechanical actuation are expanding into mainline freight locomotives where duty cycles swing between idle, notch 8, and dynamic braking. Union Pacific and BNSF are specifying these systems for 2026-2028 delivery slots. The technology is expanding into aftermarket retrofit kits as operators seek fuel economy credits without full power-assembly replacement.
EPA Tier 4 locomotive standards are mandating exhaust gas recirculation coolers and intercoolers with tighter temperature tolerances, forcing fan suppliers to certify precision flow maps across ambient conditions from minus 40 to plus 50 degrees Celsius. United States-based rebuilders are responding with dual-fan redundant configurations that maintain thermal compliance during single-fan maintenance events.
Rail operators are consolidating vendor lists around suppliers offering integrated motor-fan-controller packages rather than discrete component procurement. This pattern concentrates specification influence with vertically integrated OEMs and compresses margin for standalone blade or motor manufacturers. The shift is most visible in Class I freight carrier request-for-proposal structures issued since 2023.
Locomotive Radiator Fan Market Segmentation
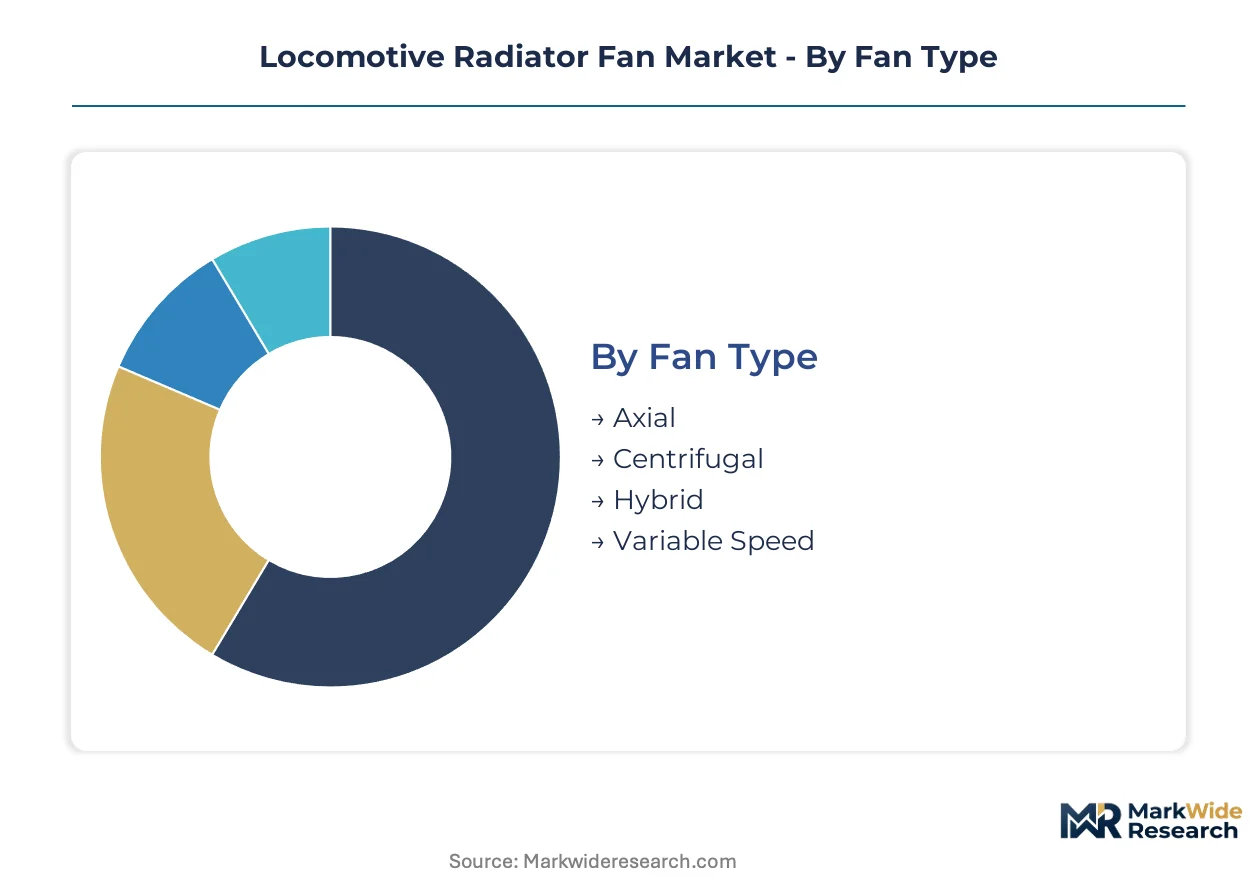
Locomotive radiator fan procurement splits sharply between legacy rebuild specifications and new-build hybrid architectures. Tier 1 OEMs are consolidating vendor lists around integrated motor-fan-controller packages, collapsing the traditional multi-source component model.
Fan Type:
Supply concentration for complete fan assemblies tilts toward suppliers with captive motor manufacturing and blade casting capabilities.
- Axial:Hub-mounted impellers with 400–1,200 mm diameters deliver high flow efficiency at low static pressure. Demand concentrates in United States Class I freight carrier modernization programs where EPA Tier 4 thermal envelopes require continuous duty operation across minus 40 to plus 50 degrees Celsius ambient swings.
- Variable Speed:Engine-speed-responsive controls paired with electric motors enable parasitic load reduction during partial throttle operation. German and Chinese locomotive manufacturers are specifying these systems for new-build programs targeting fuel economy certification under EU F-Gas and GB standards respectively.
- Centrifugal:Radial blade configurations handle higher static pressure requirements in compact engine compartments.
- Hybrid:Dual-mode drives switch between hydraulic and electric power sources based on thermal load.
Today's leader: Axial. Tomorrow's challenger: Variable Speed.
Material:
Cost tier stratification separates premium composite programs from commodity aluminum retrofits.
- Composite:Glass-reinforced polymer and carbon-fiber compounds reduce rotational inertia and eliminate galvanic corrosion. United States new-build locomotive programs specify these materials for mainline freight duty cycles where weight reduction justifies engineering change order premiums.
- Aluminum:Cast and extruded alloys remain the baseline for aftermarket replacement blades. Chinese State Railway Group procurement for domestic refurbishment lines maintains volume concentration here due to established supply chains and repair shop familiarity.
- Plastic:Injection-molded reinforced polymers serve yard switchers and short-line operations with lower thermal loads.
- Steel:Fabricated blades persist in heavy-haul mining locomotives requiring impact resistance.
Composite is climbing the fastest for new-build contracts. Aluminum defends installed base replacement volume.
Cooling Method:
Application severity drives architecture selection from passive yard duty to mainline thermal stress.
- Air-Cooled:Forced-convection systems with shrouded axial fans dominate mainline freight installations. EU F-Gas Regulation phase-down of synthetic refrigerants is accelerating specification of these architectures in European passenger locomotive programs certified to ISO thermal design standards.
- Liquid-Cooled:Closed-loop coolant circuits with integrated heat exchangers manage EGR cooler and intercooler loads. EPA Tier 4 compliance in the United States mandates these systems for precision temperature control across variable ambient conditions.
- Combination:Hybrid air-liquid architectures optimize thermal management across multiple engine subsystems.
- Direct Ventilation:Simplified ducting serves low-horsepower switchers with minimal packaging constraints.
Combination systems are gaining share fastest in hybrid-electric locomotive designs. Air-Cooled retains volume leadership in diesel-electric retrofits.
Industry Standard:
Certification burden varies by export destination, fragmenting supplier qualification timelines.
- ISO:International Railway Industry Standard audits demand 18-to-24-month documentation cycles. German OEMs require IRIS-certified thermal design capabilities for Tier 1 supplier qualification, creating barrier concentration for new market entrants.
- DIN:German national standards govern precision hydraulic fan drive specifications. Japanese specialty suppliers concentrate production of these components, creating geographic supply risk for North American rebuilders.
- ASME:Pressure vessel codes apply to liquid-cooled heat exchanger assemblies.
- ANSI:United States national standards coordinate with EPA emissions testing protocols.
ISO commands specification authority for cross-border procurement. DIN retains niche dominance in precision hydraulic subsystems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Class I freight carriers in the United States drive procurement volume for EPA Tier 4-compliant cooling systems. German engineering clusters supply precision hydraulic fan drives. Chinese State Railway Group modernization pulls high-capacity axial assemblies into domestic manufacturing lines.
United States
Union Pacific and BNSF Railway specify variable-pitch fan systems for 2026-2028 delivery slots under fleet renewal programs. EPA Tier 4 emissions mandates force cooling-system redesigns for exhaust gas recirculation coolers and intercoolers. Manufacturing concentration in the Midwest rail corridor supports rebuild operations for legacy diesel-electric locomotives.
Germany
Deutsche Bahn and private freight operators source precision hydraulic fan drives for mainline locomotive programs. DIN standards govern component specifications, creating qualification barriers for non-European suppliers. Engineering clusters in Baden-Württemberg and Bavaria concentrate thermal design expertise for rail-certified assemblies.
China
State Railway Group fleet renewal targets under GB standards pull high-capacity axial fan assemblies into domestic production lines. MIIT efficiency requirements and dual carbon goals shape procurement criteria for new-build locomotives. Manufacturing concentration in the Yangtze River Delta serves both domestic demand and export programs.
India
Indian Railways' net-zero freight corridor targets under CEA guidelines require hybrid cooling architectures for dual-mode locomotives. Diesel-electric fleet expansion in non-electrified corridors sustains demand for conventional forced-convection systems. Industrial clusters around Chennai and Pune supply blade castings and motor assemblies for domestic refurbishment lines.
Japan
East Japan Railway and freight operators specify compact cooling systems for high-density urban operations. METI efficiency standards and JIS certification requirements filter supplier qualification. Manufacturing concentration in the Nagoya industrial corridor supports precision motor and hydraulic component production for domestic and export markets.
Locomotive Radiator Fan Market Competitive Landscape
Global majors compete with regional champions across integrated motor-fan-controller packaging. Market structure tilts toward consolidation as Class I carriers consolidate vendor lists around vertically integrated suppliers. Three archetypes dominate: aerospace-derived motor specialists, European axial fan designers, and variable-pitch mechanism innovators. Competitive moves center on backward integration into captive blade manufacturing and strategic partnerships for predictive maintenance platform deployment.
Among North American system integrators, Ametek Inc. and Flexxaire Inc. occupy positions on the premium tier. ZIEHL-ABEGG Inc. anchors European supply for specialized axial configurations. These named entities exemplify the shift toward integrated packages rather than discrete component procurement, with each representing distinct geographic and technological positioning within the vendor base.
| Leading Market Players |
|---|
| Ametek Inc. |
| Multi Wing America Inc. |
| ZIEHL-ABEGG Inc. |
| Bergstrom Inc. |
| Sunonwealth Electric Machine Industry Co. Ltd |
| Flexxaire Inc. |
| Valeo SA |
| Horton Holding Inc. |
| Aerovent |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialists in motor and blade manufacturing anchor supply-side discipline across United States and German production clusters, translating captive production of copper-wound motors and composite impellers into pricing power over Class I freight carrier procurement teams.
Pricing Analysis
Copper and neodymium magnet cost pass-through dominates contract negotiations, with three-tier pricing structure across premium, standard, and economy levels stratifying by ISO certification grade and after-sales service bundling. Price differentiation hinges on EPA Tier 4 compliance documentation and captive motor manufacturing. Cost compression in commodity aluminum retrofits is intensifying because Chinese State Railway Group procurement leverages established repair shop relationships. Aftermarket replacement buyers exhibit highest price sensitivity; new-build hybrid locomotive programs show lowest.
Supply Chain Analysis
Workforce availability constraints in Baden-Württemberg engineering clusters and Yangtze River Delta manufacturing hubs concentrate precision hydraulic drive and axial fan assembly production. Supply draws from copper mining in Chile, rare-earth magnet processing in China, and glass-reinforced polymer compounding in Germany. Single-source vulnerability in Japanese specialty hydraulic component suppliers creates geographic concentration risk for North American rebuilders. Distribution runs through Tier 1 OEM direct contracts and authorized aftermarket service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite blade substitution and predictive maintenance platform deployment represent parallel margin-expansion vectors, with material cost-down trajectories and recurring service revenue streams reshaping profit pool distribution.
For Market Incumbents: Lock in long-term offtake agreements for copper and rare-earth magnet feedstock before commodity volatility compresses fixed-price rail contract margins. Deepen backward integration into captive blade casting capabilities to defend specification influence as Class I carriers consolidate vendor lists around integrated motor-fan-controller packages. Prioritize IRIS certification investment to maintain Tier 1 OEM qualification against 18-to-24-month audit cycles. For New Entrants and Emerging Players: Capture specification windows in Indian Railways' dual-mode locomotive electrification corridor and European F-Gas-driven air-cooled system adoption. Target hybrid cooling architecture penetration in non-electrified Indian freight routes as the most penetrable white-space. Lead with variable-pitch mechanism innovation paired with edge-computing diagnostics to bypass entrenched hydraulic drive incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap composite blade specialists with captive polymer compounding and rail-certified thermal design capabilities. Five-to-ten-year viability rests on EPA Tier 4 retrofit cycle completion and China GB standard fleet renewal saturation. Monitor Union Pacific and BNSF variable-pitch specification rates as inflection indicator for technology substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Composite Blade Manufacturing | Captive glass-reinforced polymer production secures margin against aluminum commodity volatility for United States new-build programs. |
| Predictive Maintenance Platform Deployment | Vibration-sensor-equipped fan assemblies with edge-computing diagnostics shift revenue from hardware to recurring service contracts. |
| IRIS Certification Investment | Eighteen-to-24-month documentation cycles create barrier concentration for German OEM Tier 1 supplier qualification. |
| Long-term Copper and Rare-Earth Magnet Supply Agreement | Fixed-price rail contract profitability hinges on feedstock cost predictability amid commodity price swings. |
| Joint Venture for Indian Dual-Mode Locomotive Cooling | CEA-guided net-zero freight corridor targets open specification windows for hybrid architecture market entry. |
Research Methodology
Direct dialogue with locomotive OEM procurement directors, aftermarket service managers, thermal design engineers, and Class I freight carrier maintenance executives grounded qualitative findings. Secondary validation drew from EPA emissions compliance filings, FRA safety databases, Chinese State Railway Group procurement disclosures, and EU F-Gas Regulation implementation reports. Bottom-up and top-down triangulation cross-checked component-level production estimates against fleet renewal program announcements.
Bottom-up volume modeling segmented by fan type, material grade, cooling architecture, and certification standard across the analysis window. Top-down demand validation referenced locomotive production and refurbishment schedules from United States, German, Chinese, and Indian rail operators. CAGRs were derived from production volume trajectories and specification-grade procurement intensity. Industry-specific forecast inputs included EPA Tier 4 compliance deadlines and China dual carbon policy implementation pacing.
Copper price volatility, rare-earth export restriction escalations, and IRIS audit timeline delays are the dominant revision risks to projection assumptions. Forecasts reflect documented locomotive fleet renewal commitments and thermal management specification trends. Material deviation in named triggers warrants pause and re-evaluation of capacity expansion and certification investment timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Sanitary Systems for Rail Transit Market
Railway
Railway Automated Inspection Equipment Market
Railway
Latin America Connected Rail Market
Railway
Hydrogen Fuel Cell Train Market
Railway
South Korea Connected Rail Market
Railway
Rail Bellows Market
Railway
Railway Pantograph Market
Railway
Rail Brake Frame Market
Railway
Freight Cars Market
Railway
Gearbox for Rail Vehicles Market
Railway
Train Suspension System Market
Railway
Railroads Market
Railway
Rail Seat Market
Railway
Freight Wagon Market
Railway
Railway Bearing Market
Railway
Global Train Brake Market